
 Zinc Polycarboxylate Cement Market | 2026-2036
Zinc Polycarboxylate Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Polycarboxylate Cement Market Analytics
Prosthodontic applications are rebalancing toward temporary crown procedures as elective dental visits normalize post-pandemic. Ivoclar Vivadent leverages its Swiss manufacturing base to sustain premium positioning in conventional cement lines. GC Corporation anchors Asian supply through integrated zirconia sourcing. Dentsply Sirona competes by bundling cement with digital impression workflows.
Zinc polycarboxylate cement comprises zinc oxide and polyacrylic acid that react to form a solid matrix with inherent adhesion to tooth structure without additional primers. The material serves primarily as a luting agent for crowns, bridges, and orthodontic bands where pulpal biocompatibility matters. Self-adhesive formulations command widening share as chairside time compression rewards simplified protocols. Luting agents retain the deepest margin pool due to recurrent cementation volume across aging bridge work. Resin-modified variants accelerate fastest where moisture tolerance gaps limit glass ionomer deployment.
The FDA regulates these materials as Class II medical devices under 21 CFR 872, requiring biocompatibility testing per ISO 10993. The EU MDR and CE marking framework now demand updated clinical evidence for permanent luting indications. India's CDSCO aligns with BIS standards for dental cement imports while state dental councils enforce usage protocols. Stakeholders must monitor regulatory divergence between harmonized ISO standards and emerging national requirements that fragment approval pathways.
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines for permanent luting agents while dental clinics in emerging economies accelerate self-adhesive cement adoption to reduce chairside complexity.
Growth Catalysts
- India's tier-two dental expansion:Private dental chains in cities like Jaipur, Lucknow, and Indore are standardizing zinc polycarboxylate protocols for crown cementation, creating volume pull from mid-market clinics.
- ISO 10993 biocompatibility harmonization:Convergence of FDA and EU testing standards is reducing redundant certification costs for manufacturers seeking dual-market access.
- Resin-modified formulation advances:Moisture-tolerant hybrid chemistries are penetrating tropical climates where conventional glass ionomers fail, opening Southeast Asian markets.
Market Restraints
- Zinc oxide supply concentration:Chinese smelters control roughly two-thirds of pharmaceutical-grade zinc oxide feedstock, exposing formulators to export quota volatility.
- Resin cement substitution pressure:Dual-cure adhesive systems are capturing permanent luting share in premium US and German clinics where bond strength trumps biocompatibility.
- EU MDR clinical evidence requirements:Updated technical documentation mandates for permanent indications are extending approval cycles by 12-18 months for legacy products.
Strategic Opportunities
- Brazil's underserved public dental network:ANVISA's streamlined Class II registration pathway for luting agents matches SUS procurement tenders for basic restorative materials.
- Digital workflow integration:Chairside CAD/CAM milling is electrifying same-day crown demand, positioning self-adhesive zinc polycarboxylate as the preferred provisional-to-definitive bridge material.
- Japan's aging bridge maintenance cycle:METI reimbursement incentives for minimally invasive retreatment favor recementation over replacement, sustaining recurrent luting agent consumption.
Industry Challenges
- Biocompatibility testing capacity bottlenecks:ISO 10993-5 cytotoxicity assay backlogs at certified European laboratories are delaying product launches.
- Legacy inventory reconciliation:Clinics must manage simultaneous stocks of conventional powder-liquid systems and newer paste-paste dispensers, complicating procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Polycarboxylate Cement Market |
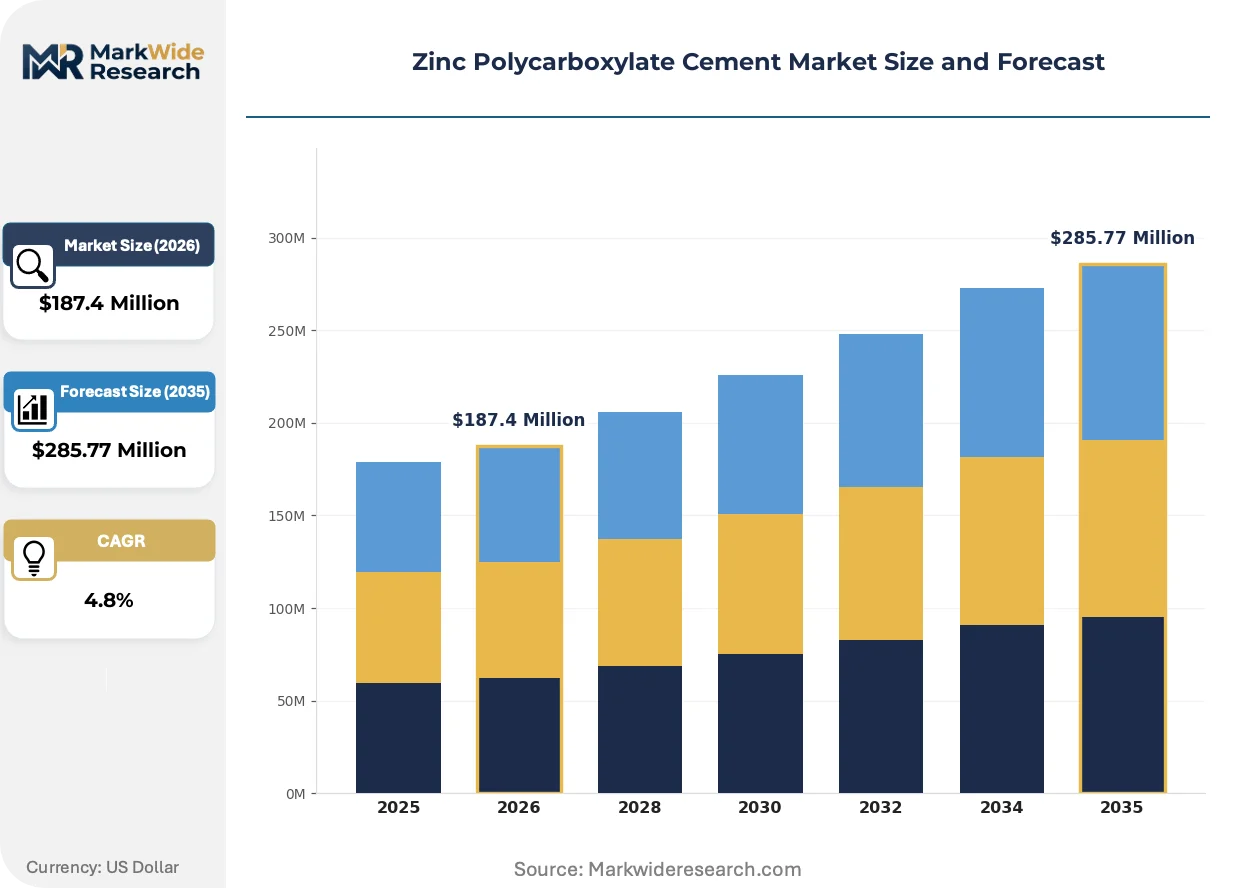
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Conventional, Resin-Modified, Glass Ionomer Application: Dental Restorations, Orthodontics, Temporary Crowns, Luting Agents End User: Dentists, Dental Clinics, Hospitals, Laboratories Distribution Channel: Online, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Ivoclar Vivadent, BISCO, Inc., 3M, DMG Chemisch-Pharmazeutische Fabrik GmbH, Kerr Corporation, Dentsply Sirona, Shofu Inc., SDI Limited, GC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Polycarboxylate Cement Market Evolving Landscape
Formulation chemistry and regulatory documentation standards are converging to reshape competitive positioning, with moisture tolerance and simplified protocols emerging as the primary axes of differentiation.
Self-adhesive zinc polycarboxylate cements incorporating modified polyacrylic acid copolymers are electrifying chairside efficiency by eliminating separate etching and priming steps. Dental chains in India's private sector are deploying these systems at scale to compress appointment duration. The technology is electrifying margin capture for high-volume operators while threatening conventional powder-liquid formats in price-sensitive segments.
The EU Medical Device Regulation's 2021 recast is forcing permanent luting agents into higher scrutiny classes, requiring clinical performance data that legacy zinc polycarboxylate products never previously submitted. Manufacturers serving European markets are reallocating R&D budgets toward technical file remediation rather than new chemistry development. Provisional indication cements face lighter documentation burdens, creating a two-tier compliance landscape.
Group purchasing organizations in US dental service organizations are consolidating procurement decisions across multi-clinic networks, unbundling cement selection from individual practitioner preference. Distributors serving these aggregators are shifting toward private-label formulations and direct-to-chain contracts. This concentration is most visible in Florida and Texas, where DSO penetration exceeds national averages.
Zinc Polycarboxylate Cement Market Segmentation
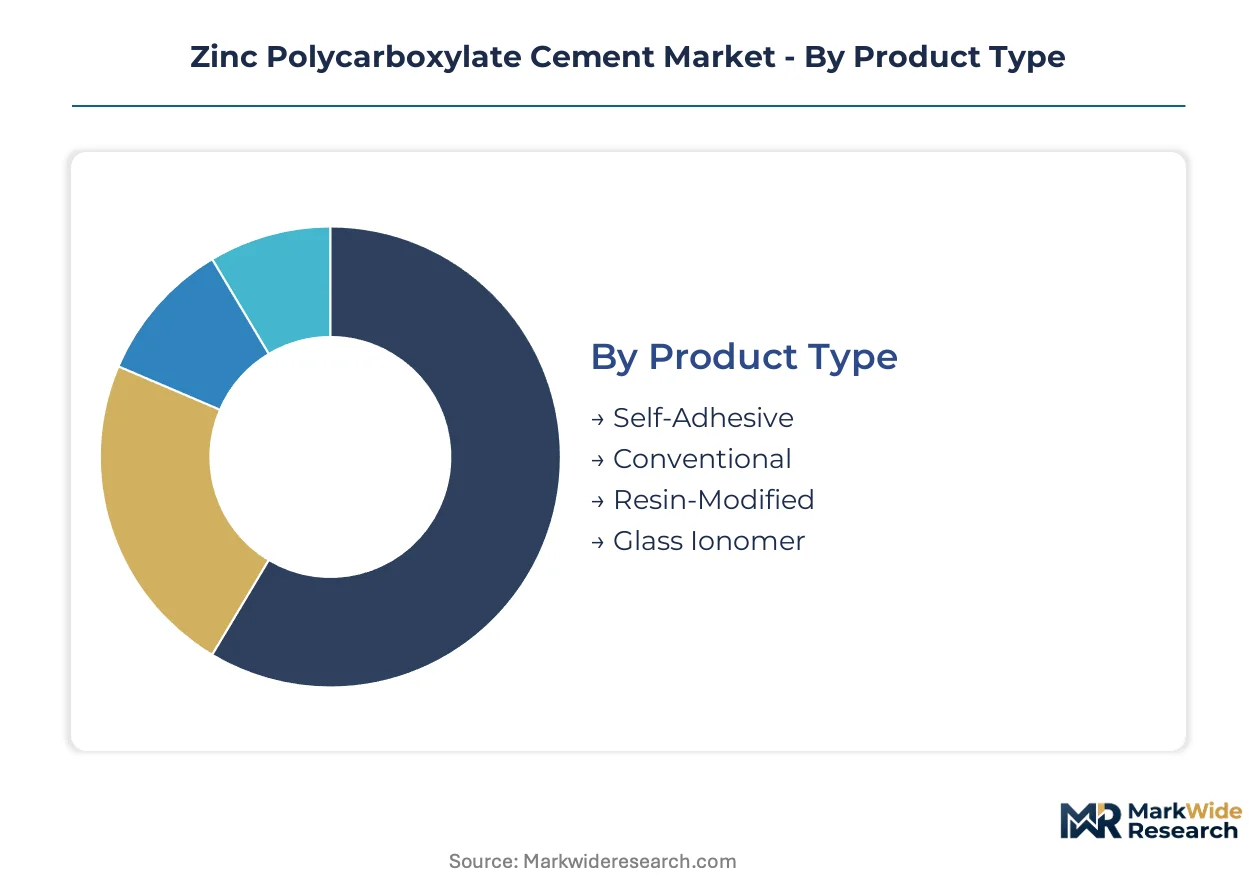
Segmentation in zinc polycarboxylate cement reveals how formulation chemistry, clinical workflow, and procurement channel intersect to determine margin capture. Manufacturers must align product architecture with the specific constraints of chairside efficiency, regulatory burden, and supply chain reliability.
Product Type:
Clinicians select formulations based on the trade-off between procedural speed and bond durability requirements.
- Self-Adhesive:Modified polyacrylic acid copolymers eliminate separate etching and priming steps. Dental chains in India's tier-two cities deploy these systems to compress appointment duration and maximize chair throughput.
- Resin-Modified:Hybrid chemistries incorporate hydrophilic monomers that tolerate moisture better than conventional glass ionomers. Southeast Asian clinics in tropical climates favor this variant where humidity compromises traditional formulations.
- Conventional:Powder-liquid systems requiring manual mixing retain cost advantage in price-sensitive public procurement.
- Glass Ionomer:Fluoride-releasing alternatives compete for pediatric and preventive applications where pulpal protection outweighs adhesive strength.
Self-adhesive formulations lead on scale; resin-modified variants lead on momentum.
Application:
Procedure volume and reimbursement economics determine which indications absorb the majority of cement consumption.
- Luting Agents:Crown, bridge, and orthodontic band cementation generates recurrent demand through aging restoration maintenance cycles. Japan's METI reimbursement incentives for minimally invasive retreatment sustain this segment's volume.
- Temporary Crowns:Post-pandemic normalization of elective dental visits has rebalanced prosthodontic workflows toward provisional procedures. Same-day CAD/CAM milling electrifies demand for cement serving as the bridge between provisional and definitive restoration.
- Dental Restorations:Permanent filling applications face substitution pressure from composite resins in premium clinics.
- Orthodontics:Band cementation for fixed appliances maintains steady consumption through adolescent treatment cohorts.
Luting agents dominate absolute volume; temporary crowns demonstrate the steepest expansion trajectory.
End User:
Procurement authority and workflow standardization separate high-volume institutional buyers from fragmented individual practitioners.
- Dental Clinics:Private chains in Brazil, India, and the southern United States consolidate purchasing through group purchasing organizations. DSO penetration in Florida and Texas exceeds national averages, unbundling cement selection from individual dentist preference.
- Dentists:Solo and small-group practices retain brand loyalty and protocol continuity, resisting formulary standardization.
- Hospitals:Academic medical centers and public health systems prioritize ISO 10993 documentation and bulk pricing.
- Laboratories:Outsourced crown fabrication creates indirect demand for luting agent recommendations to prescribing clinicians.
Dental clinics command the largest addressable base; laboratories represent the most concentrated margin pool.
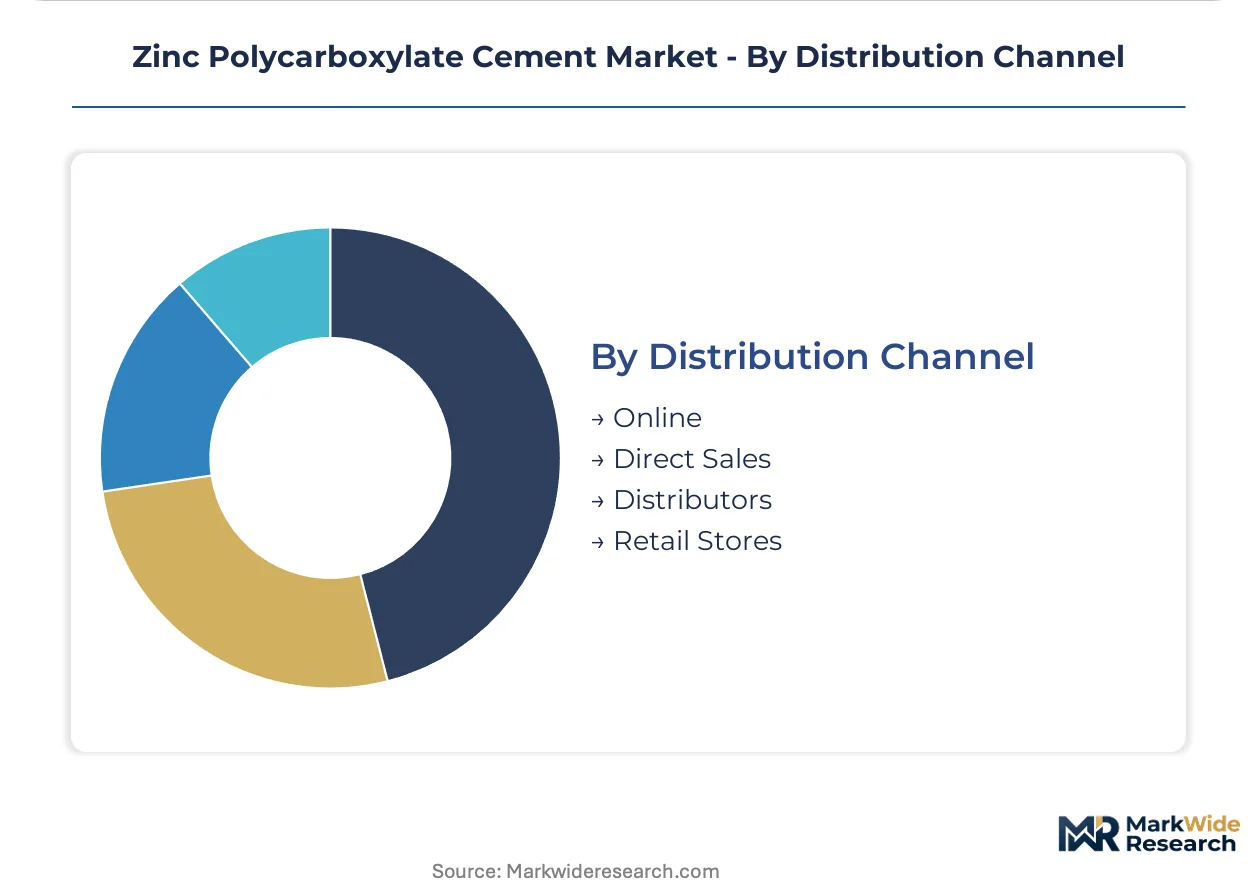
Distribution Channel:
Channel selection reflects customer scale, geographic density, and the need for technical support.
- Distributors:Dental supply wholesalers maintain inventory breadth and same-day delivery capability for high-frequency consumables. Regional distributors in India's state-level markets navigate CDSCO import requirements and BIS standard compliance.
- Direct Sales:Manufacturers bypass intermediaries for large DSO contracts and government tenders. ANVISA-registered suppliers leverage this channel for Brazil's SUS procurement.
- Online:E-commerce platforms capture small-practice and emergency replenishment orders.
- Retail Stores:Limited presence for over-the-counter dental cement in select markets.
Distributors retain channel leadership; direct sales gains share fastest among consolidated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing zinc polycarboxylate cement manufacturing toward jurisdictions where FDA and EU MDR compliance costs widen competitive gaps against emerging-market producers.
United States
Group purchasing organizations in Florida and Texas dental service organizations consolidate procurement across multi-clinic networks. FDA Class II device oversight under 21 CFR 872 mandates ISO 10993 biocompatibility documentation. Premium clinics in California and New York Metro substitute dual-cure resin cements where bond strength outweighs biocompatibility considerations.
Germany
EU MDR recast requirements compress approval timelines for permanent luting agents while extending technical file remediation cycles. DMG Chemisch-Pharmazeutische Fabrik GmbH anchors Central European supply through integrated manufacturing. Bavarian dental laboratories drive indirect demand via crown fabrication recommendations to prescribing clinicians.
India
Private dental chains in Jaipur, Lucknow, and Indore standardize self-adhesive protocols to compress chairside duration. CDSCO aligns with BIS standards for dental cement imports while state dental councils enforce usage protocols. Maharashtra and Karnataka host distributor networks navigating fragmented state-level regulatory interpretation.
Japan
METI reimbursement incentives for minimally invasive retreatment sustain recementation volume across aging bridge work. GC Corporation leverages integrated zirconia sourcing to anchor Asian supply positioning. Kanto and Kansai regions concentrate prosthodontic demand through aging demographic profiles and established dental infrastructure.
Brazil
ANVISA's streamlined Class II registration pathway matches SUS procurement tenders for basic restorative materials. São Paulo and Rio de Janeiro dental clinics deploy self-adhesive formulations to maximize throughput in high-volume operations. Southeast Asian humidity tolerance requirements favor resin-modified hybrid chemistries in tropical climate deployment.
Zinc Polycarboxylate Cement Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier Swiss and Japanese producers defending margin through integrated material sourcing while mid-market formulators compete on regulatory compliance efficiency. The vendor base organizes around three strategic archetypes: integrated dental conglomerates with digital workflow bundling, regional specialists with captive chemical production, and private-label contractors serving consolidated dental service organization procurement. Dominant competitive moves include backward integration into zinc oxide feedstock and direct-to-chain contracting that bypasses traditional distributor networks.
Among integrated dental materials producers, Ivoclar Vivadent exemplifies premium-tier positioning through Swiss manufacturing heritage, while GC Corporation occupies a position representing Asian-integrated supply chain control. Dentsply Sirona sits within the digital workflow bundling archetype, leveraging comprehensive dental equipment portfolios to anchor cement placement within broader clinical system sales.
| Leading Market Players |
|---|
| Ivoclar Vivadent |
| BISCO, Inc. |
| 3M |
| DMG Chemisch-Pharmazeutische Fabrik GmbH |
| Kerr Corporation |
| Dentsply Sirona |
| Shofu Inc. |
| SDI Limited |
| GC Corporation |
| Others |
Value Network & Pricing Analysis
ISO 10993 biocompatibility harmonization gates qualified supply access for premium-tier zinc polycarboxylate cement manufacturers, compressing margin capture for formulators lacking certified laboratory partnerships while rewarding compliant producers with pricing power in FDA and EU MDR markets.
Pricing Analysis
Distributor margin compression shapes zinc polycarboxylate cement economics, with dental supply wholesalers extracting 15-25% markup before clinic delivery. Three-tier pricing structure across premium, standard, and economy levels reflects ISO certification grade and brand heritage, with Swiss and Japanese producers commanding 40-60% premiums over private-label alternatives. Cost compression in economy tiers intensifies because Chinese zinc oxide feedstock volatility forces formulators to absorb input swings. Solo practitioners exhibit highest price sensitivity, while DSO procurement committees prioritize standardization over unit cost.
Supply Chain Analysis
India's PLI scheme for pharmaceutical-grade chemicals is reshaping sourcing patterns for dental cement manufacturers seeking qualified zinc oxide outside Chinese smelter concentration. Active pharmaceutical ingredient producers in Gujarat and Maharashtra now supply refined feedstock to formulators serving CDSCO-registered markets. The supply chain draws from Chinese zinc oxide concentration, German polymer acid production, and Indian compounding facilities. Single-source vulnerability in pharmaceutical-grade zinc oxide exposes formulators to export quota disruptions. Distribution runs through regional dental supply wholesalers maintaining same-day delivery capability for chairside replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zinc polycarboxylate cement offers margin expansion through self-adhesive formulation premiums and DSO procurement consolidation, with cost-down potential in resin-modified hybrid chemistry scale-up.
For Market Incumbents: Lock in backward integration into pharmaceutical-grade zinc oxide sourcing to neutralize Chinese smelter quota volatility threatening input cost stability. Secure direct-to-DSO contracts in Florida and Texas where group purchasing organization penetration exceeds national benchmarks, bypassing distributor margin extraction. Invest in ISO 10993-5 cytotoxicity assay capacity to accelerate EU MDR technical file remediation ahead of legacy product deadline compression. For New Entrants and Emerging Players: Tier-two Indian dental chains in Jaipur, Lucknow, and Indore represent the most penetrable buyer archetype, with private operators standardizing protocols but lacking locked supplier relationships. ANVISA's streamlined Class II registration pathway for Brazil's SUS procurement tenders offers regulatory arbitrage against EU MDR documentation burdens. Pursue private-label manufacturing contracts with regional distributors serving India's state-level CDSCO compliance requirements. For Investors and Strategic Acquirers: Roll-up economics work for mid-market dental cement formulators with captive zinc oxide sourcing because Chinese feedstock concentration is forcing independent producers into distressed exit scenarios. Target acquisition archetypes include BIS-certified Indian compounders and ANVISA-registered Brazilian manufacturers with established SUS procurement relationships. Watch METI reimbursement incentive adjustments for minimally invasive retreatment as the signal indicating sustained recementation volume versus bridge replacement substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Oxide | Captive pharmaceutical-grade feedstock supply neutralizes Chinese smelter export quota exposure for formulators. |
| EU MDR Technical File Remediation | Clinical evidence investment for permanent luting indications defends market access against 12-18 month approval delays. |
| DSO Direct Contracting | Bypassing distributor networks captures margin compression benefits in Florida and Texas consolidated procurement markets. |
| Resin-Modified Formulation Scale-Up | Moisture-tolerant hybrid chemistry expansion penetrates Southeast Asian tropical climate applications. |
| Private-Label Manufacturing Partnerships | Regional distributor alliances in India navigate CDSCO import requirements without brand-building overhead. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and Brazil, with primary inputs from each market's dental supply chain participants. The analysis combines structured interviews with prosthodontic clinicians, dental service organization procurement directors, zinc oxide feedstock suppliers, and regulatory affairs specialists at CE marking notified bodies. Secondary validation draws from FDA 510(k) filings, EUDAMED device registration data, CDSCO import records, ANVISA Class II registration pathways, and METI reimbursement schedule publications. Bottom-up cement consumption estimates triangulate against top-down dental procedure volume projections.
Granularity-level modeling disaggregates volume and value across the analysis window by product type (self-adhesive, resin-modified, conventional, glass ionomer), application (luting agents, temporary crowns, restorations, orthodontics), and end user (dental clinics, dentists, hospitals, laboratories). CAGRs derive from procedure volume elasticity to aging demographic profiles, reimbursement incentive adjustments, and DSO penetration trajectories. Forecast inputs include zinc oxide price volatility indices and ISO 10993 testing laboratory capacity utilization rates.
Underlying measurement precision varies by segment; luting agent volume estimates carry tighter precision than temporary crown projections due to more reliable bridge maintenance cycle data. Forecasts incorporate assumptions regarding EU MDR approval timeline normalization and Indian tier-two city dental chain expansion velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Italy Architectural Coatings Market
Building Materials
China Cement Market
Building Materials
Cladding Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Building Asphalt Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Construction Stone Market
Building Materials
Glass Facade Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Concrete and Cement Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
US Contract Glazing Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Natural Stone Market
Building Materials
East Africa White Cement Market
Building Materials
India Concrete Admixtures Market