
 Russia Ceramic Tiles Market | 2026-2036
Russia Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Ceramic Tiles Market Analytics
After-sales maintenance contracts and digital surface-design subscriptions is broadening what Russian tile producers monetize beyond physical slabs. Kerama Marazzi leverages its captive design studios to lock in repeat specification from Moscow developers. Unitile anchors volume through direct relationships with federal infrastructure contractors. Lasselsberger Ceramics differentiates via specialized large-format porcelain output for premium retail fit-outs.
Ceramic tiles are sintered clay-based surfacing materials fired at 1,000–1,250°C, with porcelain variants requiring kaolin-rich bodies and higher densification for low water absorption below 0.5%. They serve primarily as protective, hygienic, and aesthetic finishes for interior and exterior building envelopes. Porcelain tiles command the deepest margin pools in Russia due to frost resistance requirements and specification in high-traffic commercial flooring. Glazed tiles still occupy the largest volume share across mass residential wall cladding in mid-rise developments. Online platforms represent the fastest-growing distribution channel as builder-procurers shift toward centralized digital tendering.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST R certification for tile frost resistance and slip resistance, directly filtering which products qualify for public infrastructure tenders. The Eurasian Economic Commission's technical regulations harmonize cross-border standards, shaping import competition from Belarus and Kazakhstan manufacturers. Sanitary-epidemiological oversight by Rospotrebnadzor adds surface-hygiene testing for healthcare and food-service installations. Stakeholders must monitor how Rosstandart's anticipated updates to GOST 6787 for ceramic tile dimensions will force retooling decisions across domestic production lines.
Market Dynamics
Rosstandart's pending GOST 6787 dimensional updates are forcing domestic manufacturers to retool production lines ahead of enforcement, compressing capital deployment windows and reshaping competitive readiness across Russia's Central Federal District production clusters.
Growth Catalysts
- Federal infrastructure procurement mandates:Rosstandart frost-resistance certification requirements filter qualified suppliers for public tender participation, directing specification toward certified domestic producers.
- Saint Petersburg residential density:High-rise development concentration in Russia's second-largest city sustains wall cladding volume demand for glazed ceramic formats.
- Kaolin beneficiation advances:Domestic porcelain body refinement is reducing import dependency for high-grade raw material inputs.
Market Restraints
- Natural gas price volatility:Kiln firing operations consume substantial methane feedstock, exposing producers to input cost swings from Gazprom pricing adjustments.
- Import concentration from Belarus:Cross-border supply from Eurasian Economic Commission member states limits pricing power for mid-grade glazed tile segments.
- Frost resistance testing bottlenecks:Rosstandart laboratory capacity constraints extend certification timelines for new product launches.
Strategic Opportunities
- Siberian Federal District underpenetration:Novosibirsk and Krasnoyarsk construction markets remain underserved by large-format porcelain distribution networks.
- Digital tendering platform expansion:Builder-procurer migration to centralized e-procurement systems is opening direct manufacturer-to-developer channels bypassing traditional distributor markups.
- Rospotrebnadzor healthcare specifications:Surface-hygiene testing mandates for hospital and food-service installations create premium positioning for antimicrobial glaze formulations.
Industry Challenges
- Digital surface-design talent scarcity:Captive design studio operation requires specialized CAD-to-CAM workflow expertise that domestic labor markets undersupply.
- Legacy kiln reconfiguration costs:GOST 6787 compliance demands dimensional tolerance upgrades that strain mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Ceramic Tiles Market |
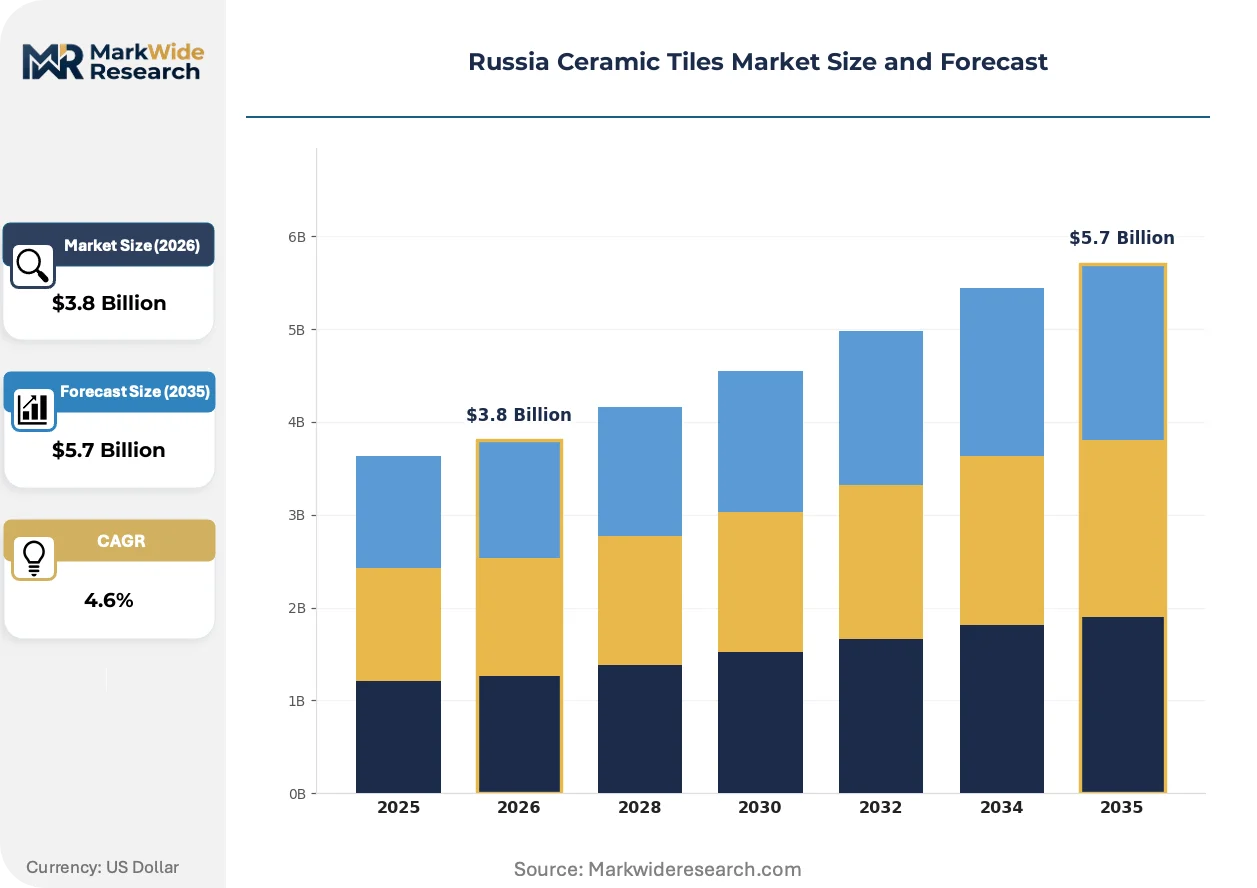
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Porcelain Tiles, Stoneware Tiles, Terracotta Tiles Usage Type: Flooring, Wall Cladding, Backsplashes, Decorative Elements Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Distributors End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Unitile, Mohawk Industries, Kerama Marazzi, Tarkett, Saloni, Lasselsberger Ceramics, Cersanit, Porcelanosa, Italon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Ceramic Tiles Market Evolving Landscape
Digital inkjet decoration systems are compressing design-to-production cycles while Rosstandart regulatory tightening and builder-procurer channel migration collectively reshape how value is captured across Russia's tile supply chain.
Single-pass inkjet printing systems are automating surface pattern application with micron-scale precision, replacing multi-screen rotary processes. Moscow-based premium developers are specifying these digitally decorated formats for luxury residential lobbies and retail fit-outs. The technology is automating batch-size flexibility, enabling economic production of sub-500-square-meter custom design runs previously reserved for hand-painted artisan formats.
Rosstandart's draft GOST 6787-2024 dimensional tolerance revisions will tighten length and width deviation allowances from plus-minus 0.5% to plus-minus 0.3% for rectified porcelain tiles. Domestic producers serving federal infrastructure contractors face forced capital allocation toward precision cutting and calibration equipment. Large-format slab manufacturers in the Central Federal District are pre-positioning compliance capacity to capture early-mover specification advantage.
Centralized digital tendering platforms are consolidating builder-procurer purchasing decisions onto single interfaces, collapsing traditional distributor tier structures. Federal infrastructure contractors in Moscow and Saint Petersburg are migrating specification authority from site-level procurement officers to centralized engineering departments. This concentration is most visible in multi-phase residential developments where master developers negotiate frame agreements covering entire construction cycles.
Russia Ceramic Tiles Market Segmentation
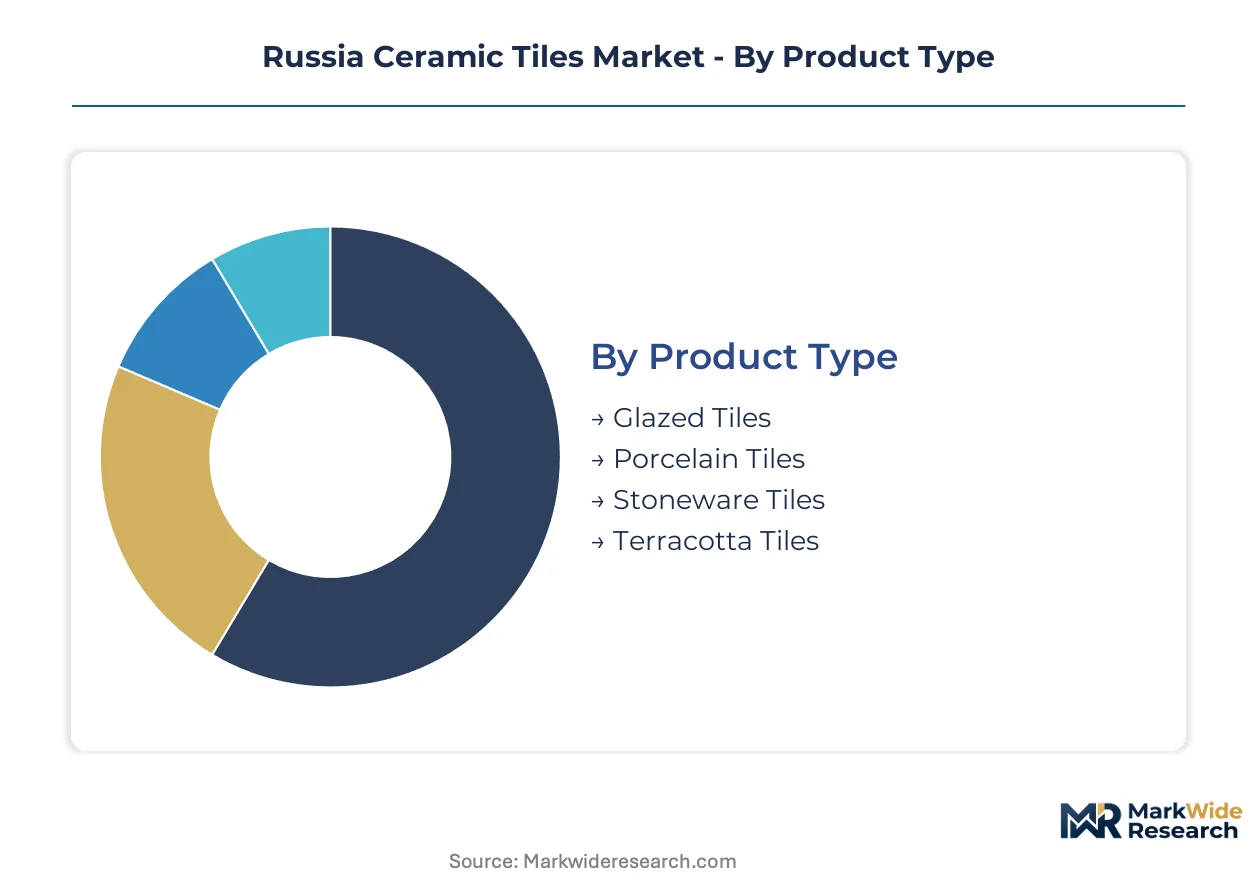
Segmentation in Russia's ceramic tiles market reveals how specification authority, procurement channels, and end-use requirements fragment demand across technical grades and application contexts. Understanding these splits exposes where margin pools concentrate and where volume scale accumulates.
Product Type:
Volume dominance sits with glazed formats, while premium margin capture concentrates in porcelain formulations engineered for frost resistance and structural loading.
- Glazed Tiles:Clay-based bodies receive vitreous surface coatings that enable color variety and stain resistance at moderate cost. Demand concentrates in mid-rise residential wall cladding across Moscow's peripheral districts, where developers prioritize budget-compliant aesthetic coverage over structural performance.
- Porcelain Tiles:Kaolin-rich bodies fired at higher temperatures achieve sub-0.5% water absorption and frost-cycle durability. Specification from Saint Petersburg infrastructure contractors drives adoption, as Rosstandart certification requirements filter qualified suppliers for public tender participation.
- Stoneware Tiles:Intermediate density bodies serve commercial flooring where abrasion resistance exceeds glazed tile capability but porcelain cost premiums are rejected.
- Terracotta Tiles:Unglazed earthenware formats retain traditional architectural specification in heritage restoration projects and premium residential accents.
Mature deployment sits with glazed tiles across mass residential construction. Newer deployment is concentrated in porcelain large-format slabs for premium retail and hospitality fit-outs.
Usage Type:
Application geometry determines tile specification logic — horizontal loading demands structural performance, while vertical surfaces prioritize aesthetic coverage and installation efficiency.
- Flooring:Structural applications demand slip-resistance certification and load-bearing capacity, concentrating specification in rectified porcelain formats for high-traffic commercial environments.
- Wall Cladding:Vertical surfaces dominate residential volume, with glazed ceramic formats specified for bathroom and kitchen coverage in multi-unit developments across the Central Federal District.
- Backsplashes:Compact surface areas in food-service and residential kitchens drive demand for decorative small-format tiles with moisture-resistant grout lines.
- Decorative Elements:Accent applications in luxury residential lobbies and hotel interiors specify digitally printed custom designs with sub-500 square meter economic batch viability.
Volume concentration anchors in wall cladding for residential developments. Specification complexity and margin expansion are climbing the fastest in decorative element customization enabled by single-pass inkjet systems.
Distribution Channel:
Channel structure is bifurcating between centralized procurement authority and fragmented retail access, with digital platforms collapsing traditional intermediary tiers.
- Direct Sales:Manufacturer-to-developer relationships bypass distributor markups, concentrating volume through frame agreements with federal infrastructure contractors managing multi-phase construction cycles.
- Retail Outlets:Brick-and-mortar showrooms serve individual homeowners and small contractors in secondary cities, though foot traffic is migrating toward digital discovery.
- Online Platforms:Centralized e-procurement systems consolidate builder-procurer purchasing decisions, collapsing traditional distributor structures and opening direct manufacturer access.
- Distributors:Traditional intermediaries retain relevance in regional markets where logistics infrastructure and credit terms remain critical to contractor purchasing decisions.
Established volume flows through distributor networks in underserved regions. Channel expansion is accelerating most quickly through online platforms as Moscow and Saint Petersburg developers centralize procurement authority.
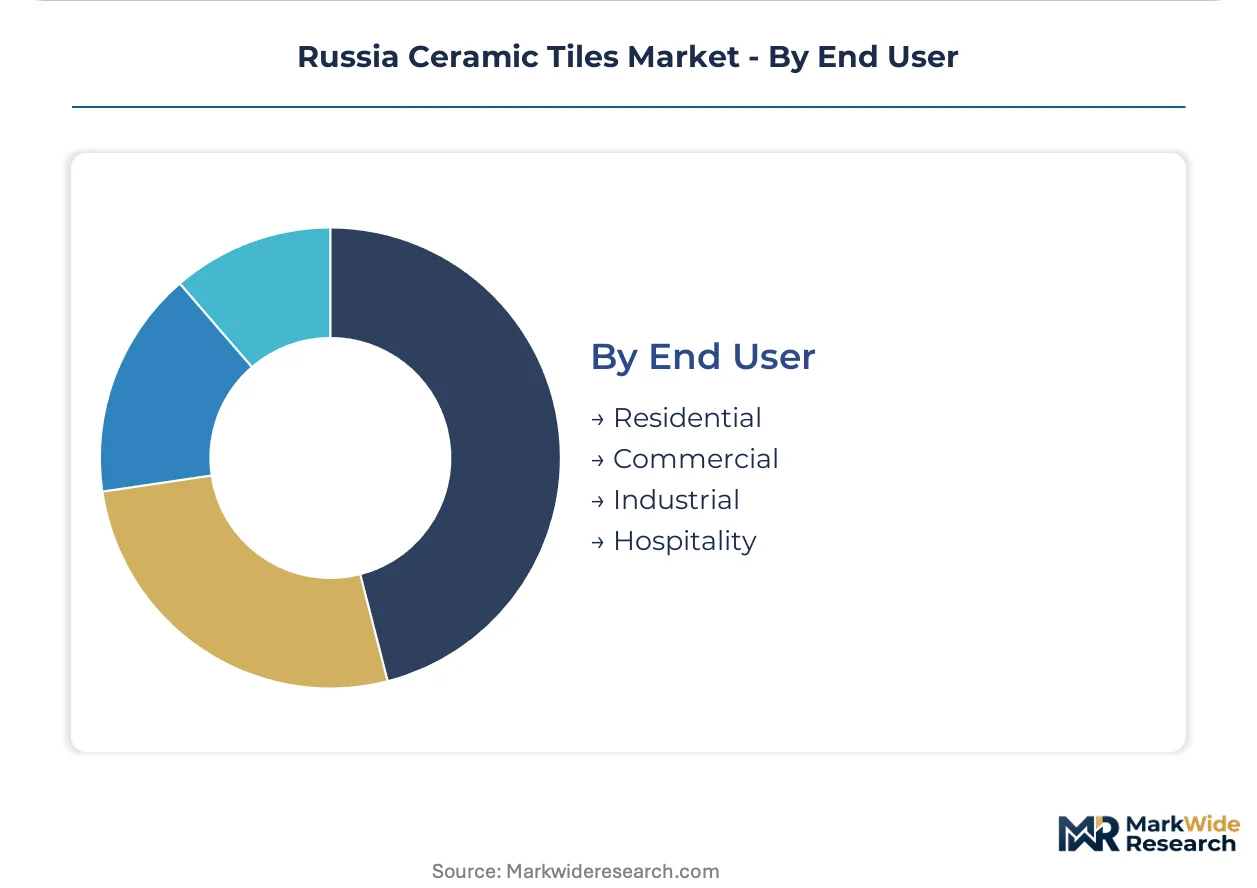
End User:
End-use segmentation separates specification authority between individual consumption decisions and institutional procurement processes with distinct compliance requirements.
- Residential:Individual homeowners and small developers drive glazed tile volume for interior wall coverage, with purchasing decisions influenced by showroom exposure and contractor recommendations.
- Commercial:Office and retail fit-out specifications demand frost-resistant porcelain for exterior cladding and high-traffic flooring, with Rosstandart certification filtering qualified suppliers.
- Industrial:Manufacturing facilities and warehousing specify heavy-duty formats with chemical resistance and load-bearing capacity, often through direct procurement relationships.
- Hospitality:Hotels and restaurants balance aesthetic differentiation with durability requirements, driving demand for digitally decorated premium formats in lobby and dining environments.
Scale concentration remains with residential construction across the Central Federal District. Premium specification and compliance complexity are deepening most rapidly in hospitality and commercial segments requiring antimicrobial glaze formulations for Rospotrebnadzor healthcare mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production clusters concentrate in Russia's Central Federal District, while consumption spreads across federal sub-regions with varying infrastructure maturity. This geographic split shapes logistics networks and specification authority.
Central Federal District
Moscow anchors specification authority for premium porcelain formats, with master developers negotiating frame agreements covering multi-phase construction cycles. Rosstandart's GOST certification requirements filter qualified suppliers for public infrastructure tenders. Production facilities in the Moscow Oblast and Kaluga Oblast serve both capital-region demand and export positioning toward Belarus and Kazakhstan.
Northwestern Federal District
Saint Petersburg sustains glazed tile volume through high-rise residential density and heritage restoration projects requiring terracotta formats. The city's port infrastructure enables import flows from European manufacturers. Local distributors maintain showrooms serving contractor networks across the Leningrad Oblast and Novgorod Oblast.
Siberian Federal District
Novosibirsk and Krasnoyarsk construction markets remain underserved by large-format porcelain distribution networks, creating whitespace for direct manufacturer expansion. Cold-climate building codes intensify frost-resistance requirements. Regional logistics costs elevate delivered pricing, protecting domestic producers with proximate kiln capacity.
Southern Federal District
Rostov-on-Don and Krasnodar Krai residential development drives mid-grade glazed tile consumption for interior wall cladding. Proximity to Black Sea ports exposes the region to import competition from Turkish and Italian manufacturers. Local distributors compete on credit terms and delivery speed rather than product differentiation.
Volga Federal District
Nizhny Novgorod and Kazan industrial construction sustains demand for heavy-duty stoneware formats in manufacturing facilities. The region's chemical processing sector specifies acid-resistant tile for containment applications. Samara Oblast infrastructure contractors source through centralized procurement platforms consolidating multi-site purchasing authority.
Russia Ceramic Tiles Market Competitive Landscape
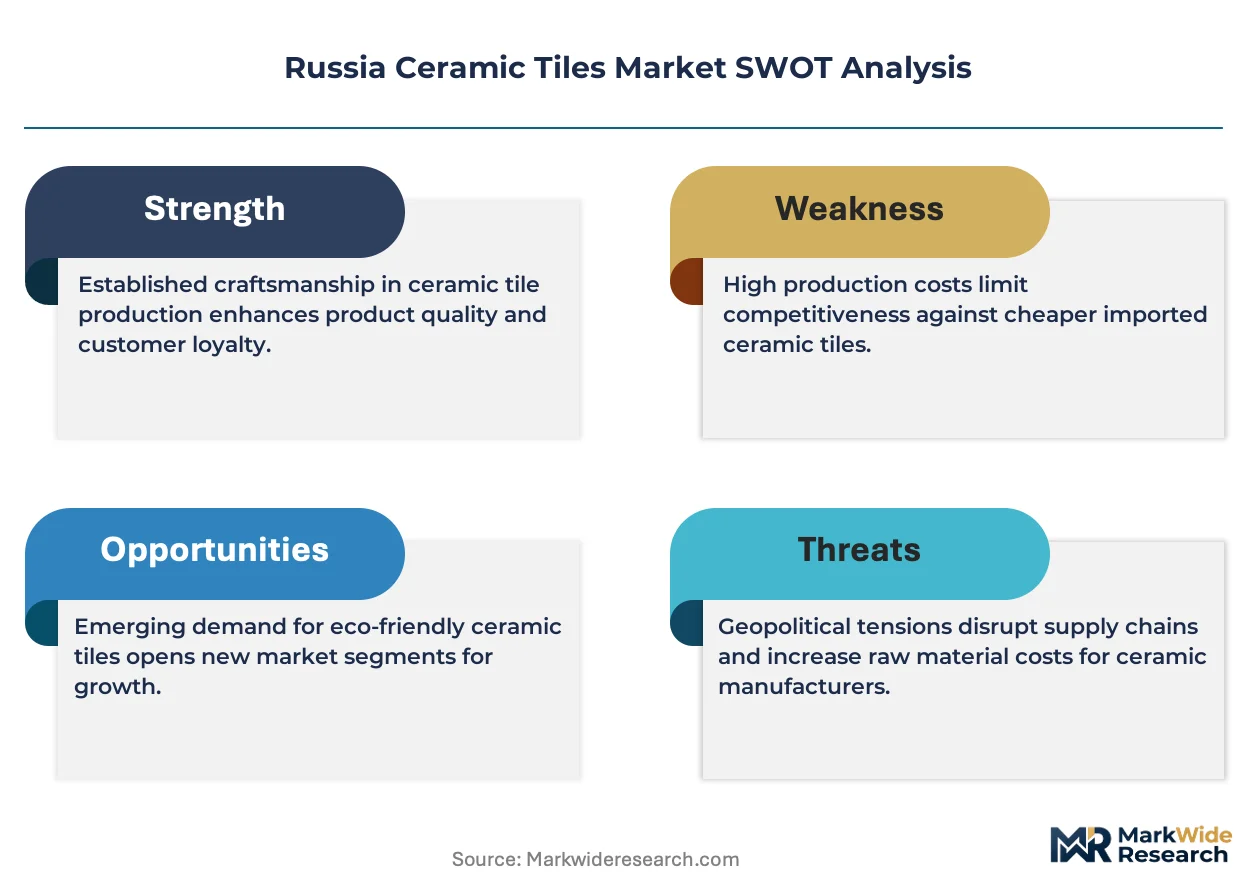
Top-tier vendors anchor federal infrastructure procurement, while mid-tier specialists compete on regional distribution reach and format specialization. The vendor base separates into three functional tiers: scale-driven producers with captive raw material access, design-forward specialists leveraging digital decoration capabilities, and regional fabricators competing on logistics proximity. Consolidation pressure intensifies as GOST 6787 compliance costs strain balance sheets. Dominant competitive moves include backward integration into kaolin beneficiation and frame agreement negotiation with master developers.
Among Russia-based producers, Unitile exemplifies the scale-driven archetype through direct relationships with federal contractors. Kerama Marazzi occupies a position in the design-forward tier, leveraging captive studio resources for repeat specification from Moscow developers. Lasselsberger Ceramics anchors the specialized large-format segment for premium retail fit-outs. These three patterns—volume scale, design lock-in, and format specialization—capture how value concentrates across competitive positions.
| Leading Market Players |
|---|
| Unitile |
| Mohawk Industries |
| Kerama Marazzi |
| Tarkett |
| Saloni |
| Lasselsberger Ceramics |
| Cersanit |
| Porcelanosa |
| Italon |
| Others |
Value Network & Pricing Analysis
Single-pass inkjet decoration adoption is compressing design-to-production cycles while simultaneously concentrating margin capture among producers with captive CAD-to-CAM workflow expertise, reshaping both cost structures and competitive positioning across Russia's Central Federal District production clusters.
Pricing Analysis
Margin tightening in mid-grade glazed tile segments traces to cross-border supply concentration from Belarus and Kazakhstan under Eurasian Economic Commission harmonized standards. Three-tier pricing structure across premium, standard, and economy levels separates GOST-certified porcelain for federal infrastructure from uncertified imports and mass residential glazed formats. Pricing pressure accelerates in standard tiers as Gazprom natural gas price volatility feeds through kiln firing economics. Small contractors and individual homeowners in secondary cities exhibit highest price sensitivity, while Moscow master developers negotiating frame agreements prioritize certification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Ukrainian and Chinese kaolin suppliers for high-grade porcelain body formulations. Domestic production draws from Central Federal District kiln clusters in Moscow Oblast and Kaluga Oblast, with raw material inputs resting on imported beneficiated kaolin and local clay deposits. Supply chain risk centers on Rosstandart laboratory capacity constraints extending frost-resistance certification timelines. Distribution runs through collapsing traditional distributor tiers as centralized digital tendering platforms open direct manufacturer-to-developer channels in Moscow and Saint Petersburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's ceramic tiles market sits in a technology-transition phase where single-pass inkjet decoration systems displace multi-screen rotary processes, rewarding producers with integrated design-to-production capabilities.
For Market Incumbents: Cement specification lock-in through backward integration into kaolin beneficiation and preemptive GOST 6787-2024 compliance capacity installation. Frame agreement negotiation with Moscow master developers covering multi-phase construction cycles defends volume position against Belarusian import erosion. Captive design studio operation captures repeat specification from premium retail fit-out developers.
For New Entrants and Emerging Players: Federal infrastructure contractors represent the most penetrable channel archetype for certified porcelain suppliers without established distributor relationships. Novosibirsk and Krasnoyarsk construction markets in the Siberian Federal District offer whitespace for large-format porcelain distribution network establishment. Direct sales teams targeting regional hospital procurement under Rospotrebnadzor antimicrobial glaze mandates provide a compliant entry vector.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building materials conglomerates seeking Central Federal District production footprint. Long-term viability favors producers with integrated raw material access and digital decoration capability rather than commodity glazed tile fabricators. Watch Rosstandart GOST 6787 enforcement timing as inflection indicator for forced retooling investment cycles and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Beneficiation | Reduces import dependency for high-grade porcelain body inputs while securing margin capture. |
| GOST 6787-2024 Compliance Capacity Installation | Captures early-mover specification advantage from Moscow federal infrastructure contractors. |
| Digital Tendering Platform Direct Access | Bypasses traditional distributor markups through centralized e-procurement system integration. |
| Antimicrobial Glaze Formulation Development | Qualifies producers for Rospotrebnadzor healthcare and food-service installation mandates. |
| Siberian Federal District Distribution Expansion | Addresses underpenetrated Novosibirsk and Krasnoyarsk construction markets with large-format porcelain. |
Research Methodology
Document review covered Rosstandart regulatory filings, Eurasian Economic Commission technical regulations, and customs trade data, complemented by interviews with plant managers at Central Federal District production facilities, procurement leads at Moscow master developers, and distribution channel partners in Saint Petersburg. Secondary validation drew from GOST certification databases, Gazprom pricing disclosures, and federal infrastructure tender records. Bottom-up volume modeling triangulated against top-down construction sector expenditure analysis.
Segment-level projections across product type, usage application, distribution channel, and end-user category were generated through driver-based modeling incorporating kiln capacity utilization, natural gas input cost trajectories, and certification timeline assumptions. CAGRs were derived from elasticity-adjusted demand curves reflecting substitution dynamics between glazed and porcelain formats. Forecast inputs included Rosstandart regulatory enforcement schedules and digital tendering platform adoption rates among builder-procurers.
Caveats apply where Gazprom pricing volatility, Rosstandart laboratory capacity expansion delays, or Eurasian Economic Commission cross-border tariff adjustments could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement timing and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
GCC Ceramic Tiles Market