
 Inorganic Filler Market | 2026-2036
Inorganic Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Filler Market Foresight
Technical service contracts for particle size optimization and dispersion engineering is hardening as a separate revenue layer in inorganic filler supply. Imerys S.A. leverages its European processing network to sustain long-term supply agreements with automotive Tier 1 suppliers. OMYA AG anchors its position through vertical integration into high-purity calcium carbonate mining and downstream surface treatment capabilities. Evonik Industries AG competes by specializing in silane-treated and functionalized filler grades for engineered plastics.
Inorganic fillers are non-combustible mineral or synthetic particulate additives, typically 0.1–100 microns in median particle diameter, introduced into polymer matrices, coatings, or elastomer compounds to modify mechanical properties, reduce resin content, or improve dimensional stability; calcium carbonate dominates by volume due to its low cost and broad compatibility, while talc grades command margin pools in automotive underhood applications where thermal resistance and stiffness retention matter. Micronized form segments are gaining fastest in electronics encapsulation where sub-micron distribution controls dielectric performance, and powder form still occupies the bulk of construction and packaging volume. Plastics application segments lead in absolute consumption, though rubber application segments in tire manufacturing are shifting toward precipitated silica hybrids that displace conventional mineral loads.
REACH registration requirements in Europe and EPA Toxic Substances Control Act reporting in the United States are elevating traceability burdens for barytes and certain clay grades, pushing producers toward certified supply chains and third-party testing documentation. China's GB standards for construction materials and SAMR quality supervision are tightening heavy metal limits in fillers destined for food-contact packaging. India's BIS certification mandates for plastic building products are expanding addressable demand for standardized calcium carbonate and talc grades. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that fragments product portfolios across export markets.
Market Dynamics
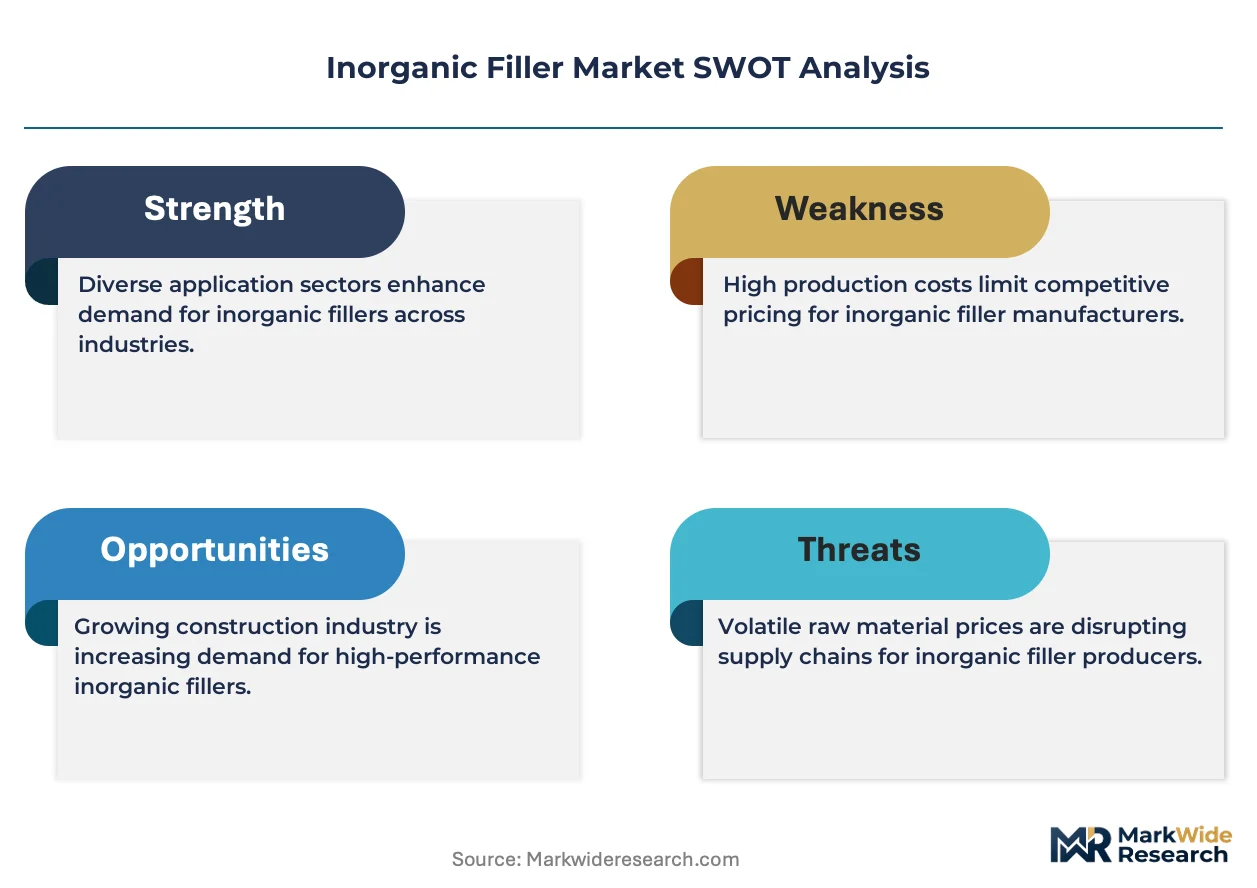
The inorganic filler market is being fundamentally restructured by REACH and EU Green Deal mandates that compel automotive OEMs to source lightweight, low-carbon mineral additives through certified supply chains rather than commodity spot markets.
Growth Catalysts
- EU Green Deal material standards:Automotive manufacturers in Germany and France must achieve recyclability targets that favor talc and calcium carbonate composites over heavier alternatives.
- China's dual carbon goals:Beijing's infrastructure stimulus channels procurement toward locally processed calcium carbonate for electric vehicle battery housings and charging station construction.
- Surface treatment chemistry:Silane coupling agents now enable mineral fillers to bond with engineered thermoplastics at loadings previously unattainable, expanding addressable resin substitution rates.
Market Restraints
- Energy cost volatility:Natural gas prices in Italy and Spain directly govern micronization and calcination economics, compressing margins for unintegrated processors.
- High-purity barytes concentration:Medical-grade and radiation-shielding applications depend on Chinese and Moroccan mine output subject to export licensing unpredictability.
- Precipitated silica substitution:Tire manufacturers are displacing conventional mineral loads with silica-silane systems that improve rolling resistance beyond what ground minerals achieve.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic production incentives for functionalized fillers serving packaging and automotive export sectors are attracting greenfield investment.
- Sub-micron dielectric grades:Electronics encapsulation demand for particle size distributions below 0.5 microns remains underserved outside Japanese and German supplier bases.
- Technical service unbundling:Dispersion engineering and particle size optimization contracts are separating from material supply, creating recurring revenue streams for formulation laboratories.
Industry Challenges
- Cross-jurisdictional formulation lock-in:Divergent heavy metal limits between China's SAMR, India's BIS, and EU REACH force parallel product lines that fragment batch economics.
- Surface chemistry talent scarcity:Silane treatment process engineering expertise concentrates within a narrow cohort of European and Japanese technical specialists, constraining capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Filler Market |
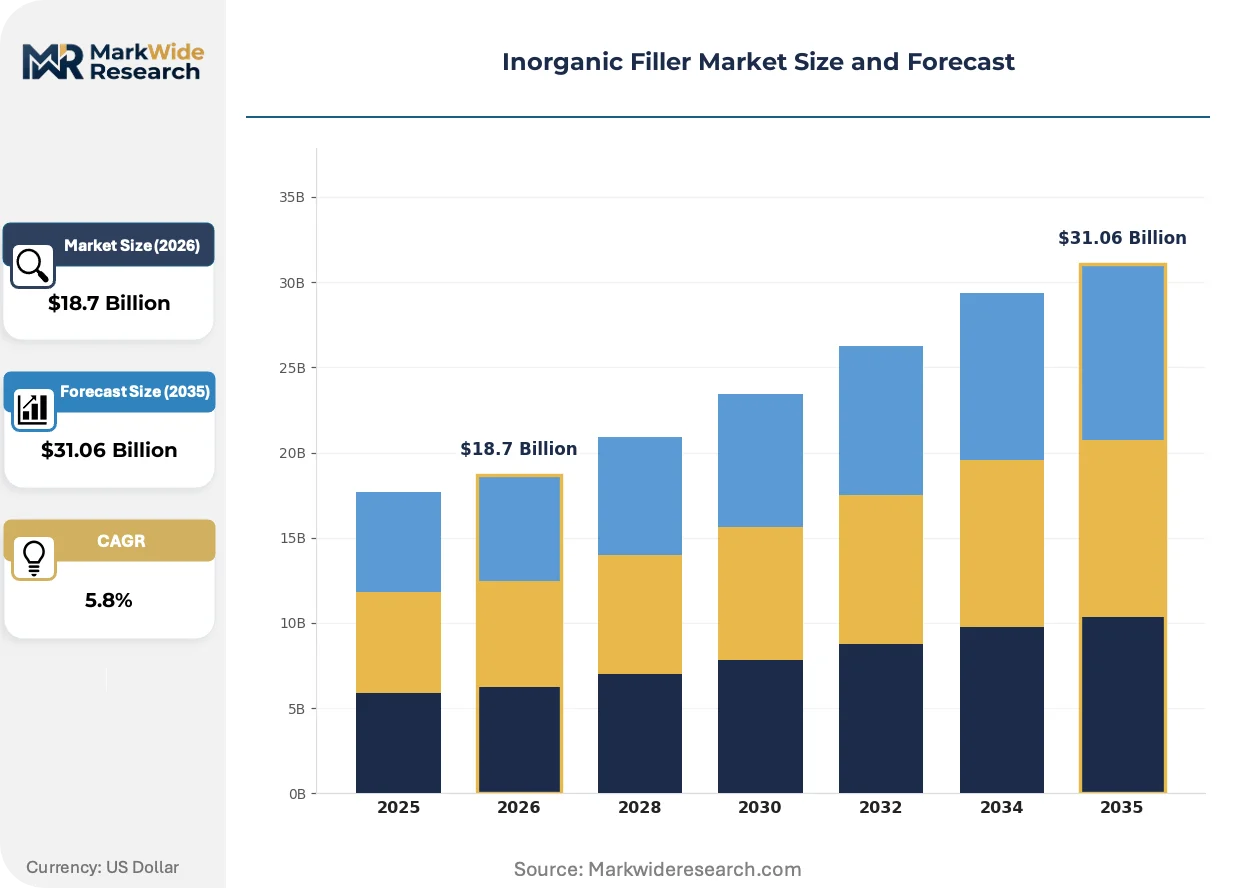
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Talc, Barytes, Clay Application: Plastics, Paints, Adhesives, Rubber End User: Construction, Automotive, Packaging, Electronics Form: Powder, Granules, Micronized, Pellets |
| Companies Covered | Imerys S.A., OMYA AG, Minerals Technologies Inc., Huber Engineered Materials, Quarzwerke Group, Sibelco, Evonik Industries AG, Hoffmann Mineral GmbH, LKAB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Filler Market Shifts & Advancements
Active modification of mineral surfaces and particle architecture is compressing the performance gap between commodity fillers and engineered additives, while regulatory traceability requirements are digitizing supply chain documentation.
Sub-micron calcium carbonate produced through controlled precipitation is decentralizing compounding operations by enabling masterbatch producers to achieve dispersion quality previously requiring captive mineral processing. Tier 1 automotive suppliers in Germany and South Korea are qualifying these grades for Class A interior surfaces. The technology is decentralizing supply chain power from integrated miners toward specialized dispersion houses with formulation IP.
REACH registration requirements for barytes and certain kaolin grades are tightening documentary burdens across European polymer compounders. ECHA's expanded substance evaluation program now demands third-party testing for crystalline silica content in talc destined for food-contact applications. French and Italian packaging converters are responding by consolidating supplier panels to pre-certified mineral processors with in-house analytical laboratories.
Automotive OEMs are compressing filler qualification cycles from 18 months to 9 months as platform electrification accelerates material refresh rates. Tier 1 suppliers are displacing traditional spot purchasing with multi-year technical service agreements that bundle particle optimization with volume commitments. This pattern is most visible in battery tray and electric motor housing applications where thermal management specifications are evolving quarterly.
Inorganic Filler Market Segmentation
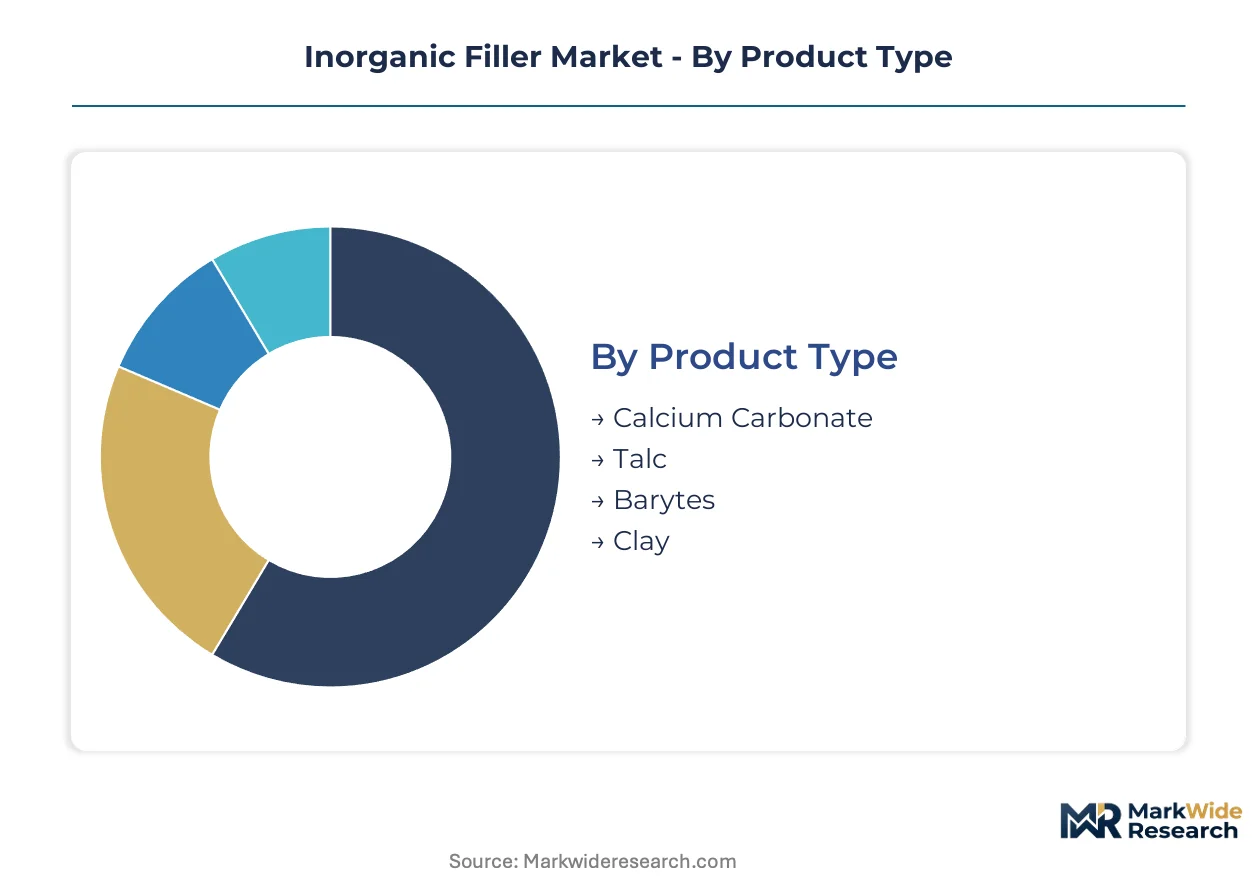
Particle architecture and surface chemistry specifications determine substitution economics across resin systems. Segmentation reveals where technical service contracts concentrate versus where commodity spot purchasing still dominates procurement behavior.
Product Type:
Mineralogy and processing intensity create distinct margin tiers, with surface-treated grades commanding formulation partnerships while raw milled products compete on delivered cost.
- Calcium Carbonate:Ground and precipitated grades span 0.1–10 micron median diameters, with surface-treated variants enabling loadings above 60% in polypropylene. Demand concentrates in China's construction sector for PVC pipe and electric vehicle battery housing compounds under Beijing's dual carbon infrastructure stimulus.
- Talc:Lamellar magnesium silicate with aspect ratios governing stiffness-to-impact balance, requiring cryogenic milling for automotive underhood specifications. German and French OEMs are expanding long-term supply agreements for platy grades meeting EU Green Deal recyclability targets in Class A interior surfaces.
- Barytes:Barium sulfate with density above 4.2 g/cm³ serving radiation shielding and sound-dampening applications.
- Clay:Kaolin and calcined grades for paper coating and engineered thermoplastic reinforcement.
Mature deployment sits with Calcium Carbonate. Newer deployment is concentrated in surface-treated Talc grades for electrified automotive platforms.
Application:
Resin compatibility requirements and loading thresholds segment the market between formulation-intensive specialties and high-volume commodity blending.
- Plastics:Polyolefin and polyamide compounding absorbs the largest volume, with masterbatch producers driving dispersion quality specifications. China's packaging sector and Germany's automotive Tier 1 suppliers are the dominant demand anchors, with qualification cycles compressing from 18 months to 9 months for electric vehicle interior applications.
- Rubber:Tire manufacturing is displacing conventional mineral loads with precipitated silica-silane systems that improve rolling resistance beyond ground mineral performance.
- Paints:TiO₂ extension and rheology control in architectural and industrial coatings.
- Adhesives:Viscosity modification and cost reduction in construction and packaging sealants.
Plastics maintains the steepest expansion trajectory as resin substitution rates climb with silane coupling agent advances. Rubber represents the most vulnerable segment to mineral displacement.
End User:
Regulatory traceability requirements and qualification burden intensity separate certified supply chain participants from spot market suppliers.
- Automotive:Electrification is accelerating material refresh rates, with battery tray and electric motor housing specifications evolving quarterly. German and South Korean Tier 1 suppliers are bundling particle optimization with multi-year technical service agreements rather than traditional spot purchasing.
- Construction:China's infrastructure stimulus channels procurement toward locally processed calcium carbonate for charging station construction and building materials.
- Packaging:Food-contact applications face tightening heavy metal limits under China's SAMR and EU REACH, forcing supplier panel consolidation to pre-certified processors.
- Electronics:Sub-micron dielectric grades for encapsulation remain underserved outside Japanese and German supplier bases.
Construction represents the highest volume deployment. Electronics embodies the fastest value-per-kilogram expansion as dielectric specifications tighten.
Form:
Particle size distribution and handling characteristics determine whether supply flows through integrated miners or specialized dispersion houses.
- Micronized:Sub-micron calcium carbonate produced through controlled precipitation is decentralizing compounding operations by enabling masterbatch producers to achieve dispersion quality previously requiring captive mineral processing. German and South Korean automotive suppliers are qualifying these grades for Class A interior surfaces.
- Powder:Bulk construction and packaging volume moves through conventional milling operations with lower processing intensity.
- Granules:Dust-reduced handling forms for high-volume plastics compounding.
- Pellets:Pre-dispersed concentrates for direct injection molding feed.
Powder dominates absolute tonnage. Micronized forms are gaining share fastest in electronics encapsulation and premium automotive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China mines and processes the largest volumes of calcium carbonate and talc, yet Germany and South Korea absorb premium grades for automotive electrification. The United States sustains demand for high-purity barytes in medical and radiation-shielding applications.
China
Beijing's dual carbon infrastructure stimulus channels procurement toward locally processed calcium carbonate for electric vehicle battery housings and charging station construction. SAMR quality supervision tightens heavy metal limits in fillers destined for food-contact packaging. The Yangtze River Delta concentrates masterbatch production where sub-micron precipitation grades are displacing conventional milling.
Germany
Automotive OEMs in Stuttgart and Munich expand lightweight composite adoption under EU Green Deal material standards and REACH registration requirements. The KBA enforces recyclability targets that favor talc and calcium carbonate composites over heavier alternatives. Bavaria's chemical processing corridor anchors technical service contracts bundling particle optimization with multi-year volume commitments.
United States
Radiation-shielding and medical-grade applications sustain demand for high-purity barytes despite import dependency on Chinese and Moroccan mine output. EPA Toxic Substances Control Act reporting elevates traceability burdens for certain clay grades. The Gulf Coast petrochemical corridor concentrates compounding operations serving packaging and construction sectors.
India
The PLI scheme for specialty chemicals attracts greenfield investment in functionalized fillers serving packaging and automotive export sectors. BIS certification mandates for plastic building products expand addressable demand for standardized calcium carbonate and talc grades. Gujarat's chemical manufacturing belt hosts emerging dispersion engineering laboratories.
South Korea
Tier 1 automotive suppliers compress filler qualification cycles from 18 months to 9 months as platform electrification accelerates material refresh rates. The MFDS maintains strict oversight of mineral additives in food-contact applications. The Busan-Ulsan industrial corridor qualifies sub-micron calcium carbonate grades for Class A interior surfaces.
Inorganic Filler Market Competitive Landscape
Top-tier vendors anchor integrated mining and surface treatment operations, while mid-scale processors compete on regional logistics and technical service bundling. The market structures around three strategic archetypes: captive mineral processors with upstream quarry control, specialized dispersion houses with formulation IP, and chemical companies with silane coupling agent expertise. Dominant competitive moves include backward integration into high-purity mining assets and multi-year technical service agreements that lock in automotive Tier 1 relationships.
Within the integrated processor tier, Imerys S.A. and OMYA AG occupy positions exemplifying European quarry-to-compound supply chain control. Evonik Industries AG represents the functionalization specialist archetype, anchoring competitive positioning through chemical treatment capabilities rather than mineral extraction. These three companies illustrate how geographic origin and corporate structure map to strategic differentiation in a market where particle architecture and surface chemistry determine substitution economics.
| Leading Market Players |
|---|
| Imerys S.A. |
| OMYA AG |
| Minerals Technologies Inc. |
| Huber Engineered Materials |
| Quarzwerke Group |
| Sibelco |
| Evonik Industries AG |
| Hoffmann Mineral GmbH |
| LKAB Group |
| Others |
Supply & Pricing Matrix
Captive mineral processing in China and Europe anchors supply positions while simultaneously governing pricing power through surface-treatment value-add tiers. Automotive Tier 1 suppliers in Germany and South Korea now bundle multi-year technical service agreements with volume commitments, compressing spot-market leverage for unintegrated processors.
Pricing Analysis
Margin tightening in raw milled grades reflects natural gas cost volatility across Italy and Spain, where micronization and calcination economics compress returns for processors lacking captive quarry access. Three-tier pricing structure across surface-treated, standard ground, and raw milled grades separates formulation partnerships from commodity spot transactions. Cost-down pressure on construction-sector calcium carbonate accelerates because China's infrastructure stimulus channels procurement toward locally processed volumes. Masterbatch producers in packaging applications exhibit highest price sensitivity, while automotive electrification programs demonstrate lowest sensitivity due to qualification burden intensity.
Supply Chain Analysis
Surface chemistry talent scarcity in European and Japanese technical corridors constrains capacity expansion timelines for silane treatment operations. Supply concentrates in China for calcium carbonate mining and precipitation processing, in Germany for automotive-grade talc milling, and in Morocco and China for high-purity barytes extraction. Raw material dependencies rest on natural gas for calcination energy inputs, silane coupling agents for functionalization chemistry, and specialized milling media for sub-micron particle architecture. Single-source vulnerability in medical-grade barytes exposes radiation-shielding and sound-dampening applications to export licensing unpredictability. Distribution runs through integrated miners with downstream compounding capabilities, specialized dispersion houses with formulation IP, and regional logistics processors serving construction and packaging volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over high-purity mining assets and surface-treatment chemistry capabilities determines who captures formulation partnerships versus commodity spot margins.
For Market Incumbents: Deploy long-term technical service agreements bundling particle optimization with volume commitments to lock in automotive Tier 1 relationships before qualification cycles compress further. Deepen upstream control over high-purity calcium carbonate and talc mining assets to insulate margin pools from energy cost volatility. Precipitated silica substitution in tire manufacturing and surface chemistry talent scarcity in European technical corridors represent twin threats requiring defensive certification investment and captive R&D in silane treatment process engineering. For New Entrants and Emerging Players: India's PLI scheme for specialty chemicals opens a window for greenfield functionalized filler production serving packaging and automotive export sectors with domestic production incentives. Target sub-micron dielectric grades for electronics encapsulation, a segment underserved outside Japanese and German supplier bases where technical qualification barriers are lower than automotive Tier 1 programs. Pursue technical service unbundling as a go-to-market angle, offering dispersion engineering contracts separate from material supply to capture recurring revenue without captive mineral processing infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized dispersion houses with formulation IP and proven automotive qualification records. Long-term viability over the five-to-ten-year window favors processors with integrated quarry-to-compound supply chain control and in-house analytical laboratories for regulatory traceability documentation. Watch for inflection in China's SAMR enforcement patterns on heavy metal limits in food-contact packaging, as divergence from EU REACH standards would force parallel product lines and fragment batch economics for non-integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Mining Assets | Captive supply of calcium carbonate and talc quarries insulates margin pools from commodity spot volatility and energy cost swings. |
| Long-term Technical Service Agreements | Bundling particle optimization with multi-year volume commitments locks in automotive Tier 1 relationships as qualification cycles compress. |
| Surface Treatment Chemistry Investment | In-house silane coupling agent capabilities enable loadings above 60% in polypropylene, expanding addressable resin substitution rates. |
| Sub-micron Precipitation Capacity Expansion | Controlled precipitation grades decentralize compounding operations and qualify for Class A automotive interior surfaces. |
| Regulatory Certification Laboratory Buildout | In-house analytical capabilities for REACH and SAMR traceability documentation consolidate supplier panels at packaging converters. |
Research Methodology
Trade databases, SEC filings from listed chemical processors, and ECHA substance evaluation registers formed the secondary backbone for volume and value estimation. Primary interviews with mineral processing plant managers, procurement leads at automotive Tier 1 suppliers, technical R&D directors at masterbatch producers, and distribution channel partners in construction and packaging sectors validated secondary assumptions. Bottom-up and top-down triangulation reconciled production capacity data with end-use consumption patterns across plastics, rubber, paints, and adhesives applications.
Bottom-up modeling aggregated segment-level consumption by product type, application, end user, and form across the projection horizon. The analytical framework incorporated grade tier differentiation between surface-treated and raw milled products, end-use industry classification separating automotive electrification from construction stimulus programs, and regional production hub clustering around China's Yangtze River Delta and Germany's Bavarian chemical corridor. CAGRs were derived from elasticity-adjusted demand curves calibrated to infrastructure spending trajectories and automotive platform electrification timelines. Industry-specific forecast inputs included silane coupling agent adoption rates in polypropylene compounding and precipitated silica displacement velocity in tire manufacturing.
The model assumes a particular technology adoption path for sub-micron precipitation grades; alternative pathways for controlled precipitation scale-up would alter the outlook for dispersion house market share capture. Forecasts reflect assumptions on regulatory harmonization between China's SAMR and EU REACH heavy metal limits, with divergence scenarios fragmenting batch economics. Material deviation in automotive electrification spending, natural gas price trajectories in Southern Europe, or export licensing unpredictability in Moroccan and Chinese barytes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Driveline Additives Market
Additives
Enzyme Stabilizer Market
Additives
Global Feed Acidifiers Market
Additives
Agrochemicals Additives Market
Additives
Dishwashing Additives Market
Additives
Water-Borne Coating Additives Market
Additives
Inorganic Rheology Modifiers Market
Additives
Apocarotenal Market
Additives
Plasticizer Concrete Admixtures Market
Additives
United States Betaine Market
Additives
Grinding Aids Market
Additives
Asia Pacific Silage Additives Market
Additives
Shortstop Inhibitor Market
Additives
Calcium Acetate Market
Additives
Binder Excipients Market
Additives
Organic Dispersants Market