
 Europe Glass Insulators Market | 2026-2036
Europe Glass Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glass Insulators Market Insights
Modular insulator stack configurations is rebalancing procurement patterns across European utilities. Sediver leverages its manufacturing footprint in France to dominate toughened glass supply for 400 kV networks. Global Insulator Group anchors its position through backward integration into raw glass production, while Verescence La Granja Insulators specializes in custom pin-type designs for Iberian distribution operators.
Glass insulators are electrical insulation devices manufactured from borosilicate or soda-lime glass, formed through tempering or toughening processes to achieve dielectric strength exceeding 140 kV and mechanical load ratings from 70 kN to 530 kN, serving primarily to isolate energized conductors from supporting structures in overhead power systems. Suspension glass insulators sustain premium pricing due to their established performance in contaminated environments across coastal Spain and industrial Poland. Distribution line applications are expanding fastest as rural electrification and renewable interconnection projects multiply connection points. Standard glass technology still occupies volume leadership, though toughened glass variants are displacing legacy units in critical transmission corridors where mechanical failure carries systemic risk.
CE marking under the EU Construction Products Regulation and ECHA REACH compliance for chemical substance restrictions shape material selection and market access across member states. Germany's KBA and France's national energy regulator enforce grid reliability standards that mandate periodic insulator replacement, creating recurring demand windows. Stakeholders must monitor the EU F-Gas Regulation's indirect pressure on composite alternatives, as this could redirect procurement back toward glass-based solutions in substation and railway electrification segments.
Market Dynamics
Grid modernization mandates across Germany, France, and Spain are accelerating replacement cycles for toughened glass suspension units, while the EU Green Deal compresses procurement timelines for high-voltage corridor upgrades.
Growth Catalysts
- EU Green Deal decarbonization targets:National renewable energy mandates in Germany and Spain are forcing utilities to expand transmission capacity, driving bulk orders for 400 kV toughened glass strings.
- France's grid reliability enforcement:The national energy regulator mandates periodic insulator replacement, creating recurring demand windows for distribution and transmission operators.
- Toughened glass manufacturing advances:Automated thermal tempering processes are reducing unit defects and extending mechanical load ratings, improving field performance in contaminated Iberian coastal zones.
Market Restraints
- Raw material cost volatility:Borosilicate glass feedstock and soda ash prices fluctuate with energy costs, squeezing margin stability for fabricators without captive supply.
- Composite insulator substitution threat:Polymer-based alternatives offer lighter weight for difficult terrain installations, pressuring glass share in mountainous Alpine corridors.
- REACH compliance burden:ECHA chemical substance restrictions add testing costs and documentation requirements that disproportionately burden smaller Spanish and Italian manufacturers.
Strategic Opportunities
- Polish distribution electrification:Rural grid extension programs and renewable interconnection projects are multiplying low-voltage connection points for pin-type glass units.
- Railway electrification segments:Cross-border high-speed rail corridors between France, Belgium, and the Netherlands require specialized glass insulators for catenary systems.
- CE marking harmonization:Unified EU Construction Products Regulation certification is reducing market access friction for compliant suppliers seeking multi-country tenders.
Industry Challenges
- Specialized glass tempering technician shortage:The workforce skilled in controlled thermal shock processes for dielectric-grade toughening is concentrated among aging employees at French and German plants.
- Legacy inventory integration friction:Utilities maintaining mixed fleets of porcelain and glass units face spare parts complexity and training overhead for field crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glass Insulators Market |
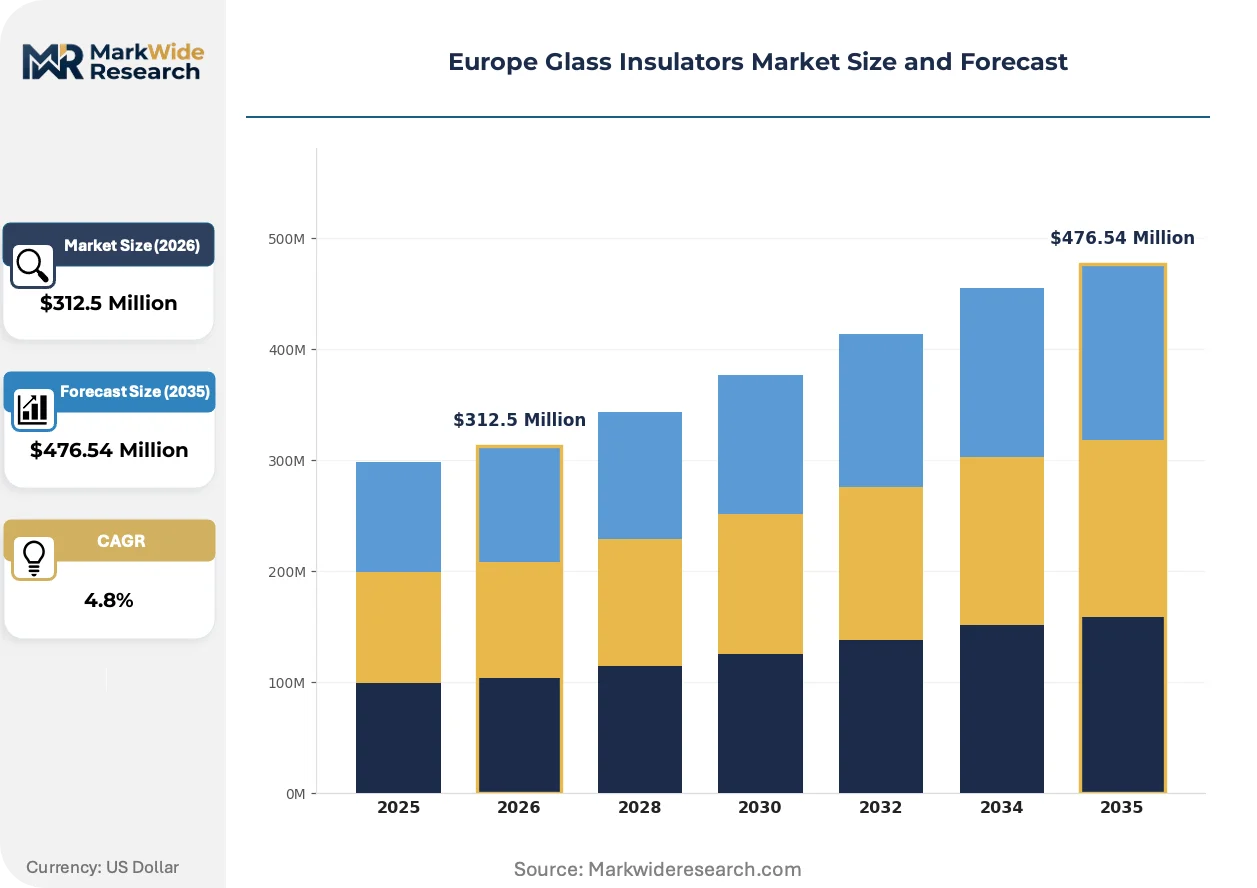
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suspension, Line Post, Pin, Insulator Stack End User: Electric Utilities, Telecommunications, Rail Transport, Renewable Energy Application: Transmission Lines, Distribution Lines, Substations, Railway Electrification Technology: Standard Glass, Toughened Glass, Polymer Composite, Hybrid Solutions |
| Companies Covered | Sediver, Global Insulator Group, Hubbell, MacLean Power Systems, Verescence La Granja Insulators, LA GRANJA INSULATORS, Seves Group, JSC U.M.E.K., NGK INSULATORS, LTD., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glass Insulators Market Trends and Innovations
Material science advances and regulatory pressure are compressing product lifecycles while reshaping how European utilities specify and procure insulation hardware for evolving grid architectures.
Coated toughened glass surfaces with hydrophobic silicone layers are overtaking standard uncoated units in premium procurement specifications. German transmission operators now require this treatment for 400 kV corridor installations exposed to industrial contamination. The technology is overtaking legacy glass in critical applications where flashover risk carries systemic grid reliability consequences.
France's national energy regulator tightened grid reliability standards that mandate accelerated inspection and replacement cycles for suspension strings in high-voltage corridors. This regulatory pressure forces utilities to standardize on toughened glass with documented mechanical load histories rather than mixed-material inventories. Distribution operators in industrial zones are responding by consolidating supplier relationships to ensure batch traceability.
Specification bundling now dominates large transmission tenders, with utilities procuring complete insulator-string assemblies including hardware fittings rather than component-level sourcing. This pattern compresses the supplier base and rewards fabricators with in-house metalworking capability. The shift is most visible in Spanish and Portuguese renewable interconnection projects where engineering-procurement-construction contractors demand single-source accountability.
Europe Glass Insulators Market Segmentation
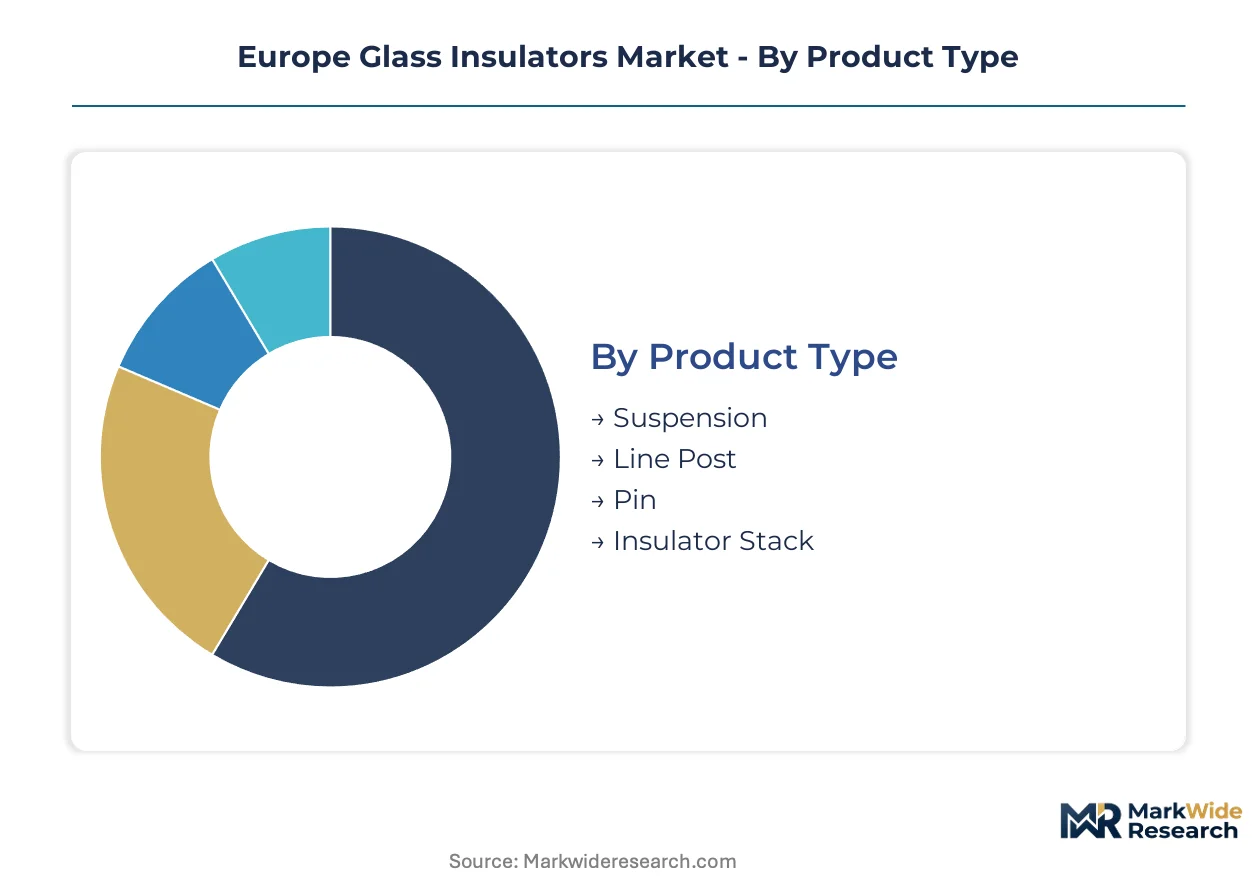
Segmentation reveals how CE marking requirements and ECHA REACH compliance burden vary sharply across product configurations and end-use applications. Procurement specifications in this market diverge based on voltage ratings, mechanical load requirements, and contamination exposure levels.
Product Type:
CE marking under the EU Construction Products Regulation applies universally, yet testing intensity and documentation depth scale with mechanical load ratings and intended voltage class.
- Suspension:Toughened glass suspension units withstand mechanical loads from 70 kN to 530 kN and dielectric strength exceeding 140 kV. German transmission operators now mandate hydrophobic silicone coatings for 400 kV corridor installations exposed to industrial contamination zones.
- Insulator Stack:Modular stack configurations are rebalancing procurement patterns across European utilities. Specification bundling in Spanish and Portuguese renewable interconnection projects favors fabricators with in-house metalworking capability for complete string assemblies.
- Line Post:Designed for horizontal conductor support in distribution networks with moderate mechanical loading requirements.
- Pin:Custom pin-type designs serve Iberian distribution operators with compact footprint requirements for low-voltage connection points.
Leading the category by volume: Suspension. Growing fastest: Insulator Stack.
End User:
Cost tier differentiation separates premium-specification buyers with captive engineering teams from price-sensitive operators outsourcing design decisions.
- Electric Utilities:Grid modernization mandates across Germany, France, and Spain accelerate replacement cycles for toughened glass suspension units. France's national energy regulator enforces periodic insulator replacement, creating recurring demand windows with documented mechanical load history requirements.
- Rail Transport:Cross-border high-speed rail corridors between France, Belgium, and the Netherlands require specialized glass insulators for catenary systems with vibration-resistant hardware specifications.
- Renewable Energy:Wind and solar interconnection projects multiply connection points for bulk procurement of toughened glass strings.
- Telecommunications:Fiber optic cable support structures utilize lower mechanical load ratings with reduced dielectric requirements.
Volume concentration: Electric Utilities. Steepest expansion trajectory: Rail Transport.
Application:
Application selection dictates contamination exposure severity and corresponding surface treatment specifications.
- Transmission Lines:High-voltage corridors across coastal Spain and industrial Poland demand toughened glass with established performance in contaminated environments. German operators now require coated surfaces for premium procurement specifications where flashover risk carries systemic consequences.
- Distribution Lines:Rural electrification and renewable interconnection projects in Poland multiply low-voltage connection points for pin-type glass units.
- Substations:Equipment insulation requirements favor standardized dimensions with batch traceability documentation.
- Railway Electrification:Catenary system specifications demand vibration-resistant hardware with specialized mechanical attachment geometries.
Revenue concentration: Transmission Lines. Gaining share fastest: Distribution Lines.
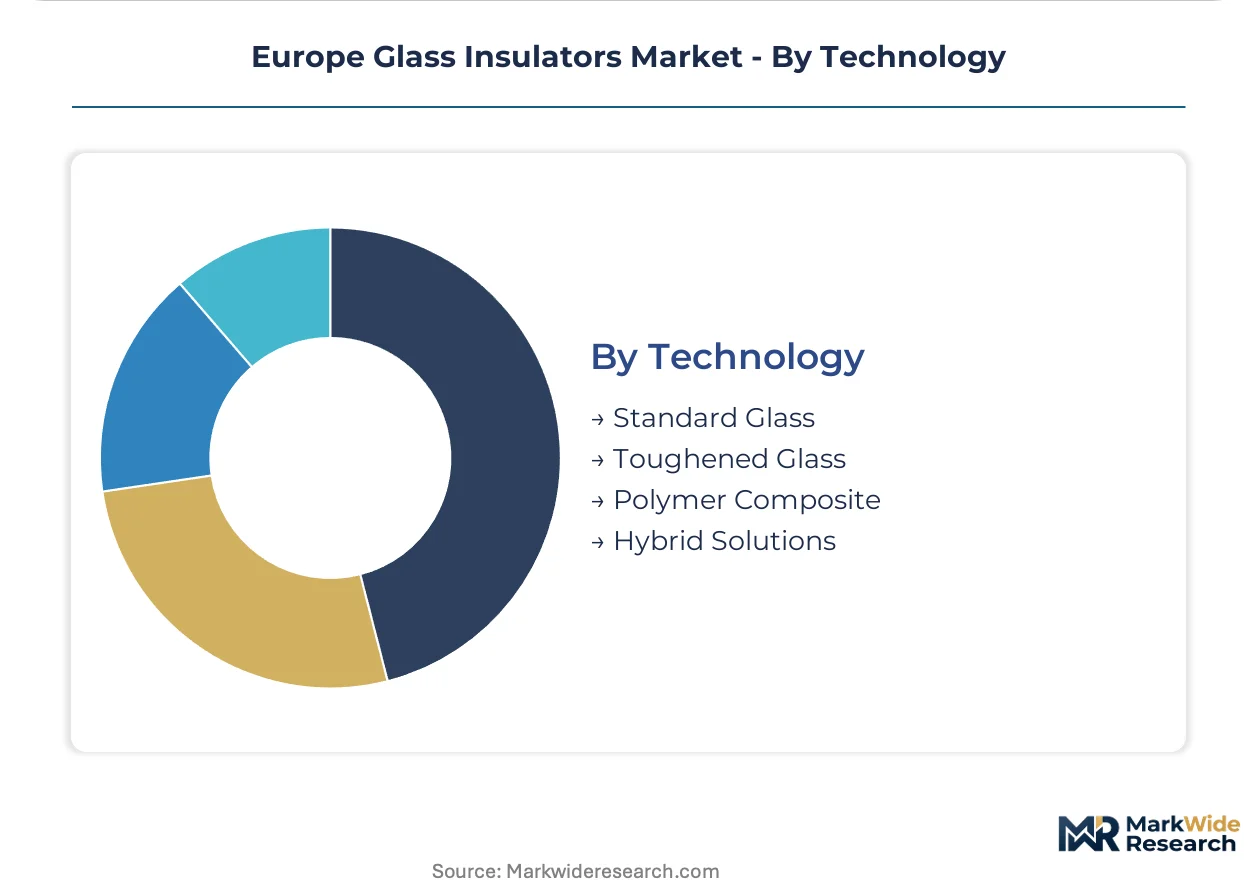
Technology:
Technology selection determines raw material cost exposure and workforce skill requirements for thermal processing operations.
- Toughened Glass:Automated thermal tempering processes reduce unit defects and extend mechanical load ratings. The workforce skilled in controlled thermal shock processes concentrates among aging employees at French and German plants, constraining capacity expansion.
- Standard Glass:Legacy technology occupies volume leadership in price-sensitive applications, though displacement accelerates in critical transmission corridors where mechanical failure carries systemic risk.
- Polymer Composite:Lighter weight alternatives pressure glass share in mountainous Alpine corridors with difficult terrain access requirements.
- Hybrid Solutions:Combined material approaches attempt to merge mechanical performance with reduced installation labor.
Market position by volume: Standard Glass. Technology climbing fastest: Toughened Glass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for renewable energy manufacturing in Spain and Poland's industrial clusters are concentrating glass insulator procurement activity. France's grid reliability mandates and Germany's transmission corridor upgrades anchor demand volume. Distribution electrification programs across Central and Eastern Europe multiply connection points for pin-type and suspension units.
Germany
Transmission operators in North Rhine-Westphalia and Bavaria mandate hydrophobic silicone coatings for 400 kV corridor installations exposed to industrial contamination. KBA enforces vehicle electrification standards that indirectly pressure grid capacity expansion. Manufacturing clusters around Stuttgart and Cologne host tempering facilities serving domestic utilities and export markets.
France
The national energy regulator mandates periodic insulator replacement cycles, creating recurring demand windows for toughened glass suspension strings. CE marking under the EU Construction Products Regulation shapes procurement documentation requirements. Auvergne-Rhône-Alpes hosts specialized glass tempering operations supplying transmission operators across the Iberian Peninsula.
Spain
Renewable interconnection projects in Castilla-La Mancha and Andalusia multiply bulk orders for toughened glass strings from engineering-procurement-construction contractors. EU Green Deal decarbonization targets compress procurement timelines for high-voltage corridor upgrades. Coastal contamination zones around Valencia drive specification for coated surfaces in premium tenders.
Poland
Rural electrification programs and wind farm interconnection projects in Silesia and Greater Poland multiply low-voltage connection points for pin-type glass units. EU cohesion funds accelerate distribution network modernization in former industrial regions. Local fabricators leverage cost positioning to capture share in price-sensitive tenders from regional utilities.
Italy
Grid operators in Lombardy and Emilia-Romagna maintain mixed fleets of porcelain and glass units, creating spare parts complexity that favors standardized toughened glass consolidation. ECHA REACH compliance adds testing costs that burden smaller domestic manufacturers. Alpine corridor terrain in the north pressures glass share against lighter polymer alternatives.
Europe Glass Insulators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers in this market. The supplier base clusters around three strategic archetypes: integrated glass manufacturers with captive raw material supply, specialized insulator fabricators with tempering expertise, and diversified electrical equipment conglomerates with broad utility relationships. Competitive positioning hinges on backward integration into soda-lime and borosilicate feedstock, plus in-house metalworking capability for bundled hardware-assembly tenders. Capacity expansion in thermal tempering and strategic partnerships with EPC contractors represent the dominant competitive moves.
Among France-based specialists, Sediver and Verescence La Granja Insulators exemplify the focused fabricator archetype with deep tempering process expertise. Global Insulator Group occupies a position representing integrated supply chain control, while NGK INSULATORS, LTD. anchors the diversified industrial conglomerate tier with cross-material insulation portfolios. These named entities sit within a competitive structure where procurement consolidation favors suppliers capable of complete string-assembly accountability.
| Leading Market Players |
|---|
| Sediver |
| Global Insulator Group |
| Hubbell |
| MacLean Power Systems |
| Verescence La Granja Insulators |
| LA GRANJA INSULATORS |
| Seves Group |
| JSC U.M.E.K. |
| NGK INSULATORS, LTD. |
| Others |
Pricing and Supply Chain Analysis
Captive supply of borosilicate glass feedstock anchors both supply security and pricing power for integrated fabricators serving German and French transmission operators. This backward integration into raw material production insulates major suppliers from soda ash price volatility while forcing smaller Spanish and Italian competitors into spot-market exposure.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as French utilities facing regulator-mandated replacement windows pay 15-25% above contract rates for expedited toughened glass suspension strings. Contract-based long-term offtake agreements anchor volume pricing for EPC contractors in Spanish renewable interconnection projects, while spot inventory discounts attract price-sensitive Polish distribution operators. Price differentiation hinges on CE marking tier and hydrophobic silicone coating certification, with coated 400 kV units commanding substantial premiums over standard uncoated alternatives. Pricing pressure stems from composite insulator substitution in Alpine terrain, squeezing margin stability for glass-only fabricators without hybrid capability.
Supply Chain Analysis
Domestic-content mandates under EU public procurement directives are reshaping sourcing patterns, favoring tempering facilities in France and Germany over lower-cost Iberian imports for critical infrastructure tenders. Manufacturing concentrates in France, Germany, and Poland, with Auvergne-Rhône-Alpes and Stuttgart-Cologne clusters hosting dielectric-grade glass operations. Raw material sourcing draws from Belgian soda ash suppliers and German borosilicate feedstock producers, creating cross-border dependencies vulnerable to energy cost spikes. Single-source vulnerability concentrates in specialized thermal tempering technician pools concentrated among aging workforces at French and German plants. Distribution runs through direct utility contracts and EPC contractor partnerships, with specification bundling favoring fabricators offering complete string assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH documentation burdens and CE marking testing requirements create substantial barrier-to-entry moats protecting incumbent suppliers with established regulatory affairs infrastructure.
For Market Incumbents: Extend tempering capacity in Poland to capture rural electrification procurement while consolidating supplier relationships with EPC contractors demanding single-source accountability for bundled string assemblies. Defend against composite insulator substitution by accelerating hydrophobic coating certification for Alpine corridor specifications. Prioritize backward integration into borosilicate feedstock to neutralize raw material cost volatility squeezing margin stability. For New Entrants and Emerging Players: Regional Polish utilities represent the most penetrable buyer archetype, with EU cohesion fund-backed distribution modernization creating procurement windows for cost-positioned pin-type specialists. Target railway electrification segments in Benelux cross-border corridors where vibration-resistant hardware specifications favor niche engineering capability over scale. Enter through engineering partnerships with Spanish renewable EPCs seeking secondary glass suppliers to diversify single-source risk. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electrical equipment conglomerates seeking insulation portfolio breadth, with NGK INSULATORS archetypes representing logical strategic buyers. Long-term viability favors integrated manufacturers with captive raw glass supply and in-house metalworking for bundled tender participation. Watch for EU F-Gas Regulation tightening on composite alternatives as the signal indicating potential demand inflection back toward glass-based solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Glass Production | Captive borosilicate supply insulates margin stability against Belgian soda ash price volatility. |
| Hydrophobic Silicone Coating Certification | German TSOs now mandate this treatment for 400 kV industrial contamination zone installations. |
| Polish Tempering Capacity Expansion | EU cohesion fund electrification programs multiply low-voltage connection point demand. |
| EPC Contractor Partnership Consolidation | Spanish renewable interconnection projects demand single-source accountability for string assemblies. |
| Specialized Railway Electrification Hardware Development | Cross-border high-speed corridors require vibration-resistant catenary system specifications. |
Research Methodology
Multi-period observation of utility procurement patterns, EPC contractor award flows, and tempering facility capacity utilization anchored the trend analysis, supplemented by interviews with transmission planning officers, distribution network engineers, glass tempering plant managers, and regulatory compliance leads at French and German manufacturers. Secondary validation drew from EU Tenders Electronic Daily records, national energy regulator filings, ECHA REACH registration databases, and customs trade data for borosilicate glass imports. Bottom-up volume builds across product configurations triangulated against top-down utility capex forecasts.
Input-output matrices mapped tempering capacity, raw material feedstock availability, and procurement award volumes to generate segment-level projections across the analysis window. Modeled dimensions included voltage class tier, mechanical load rating, contamination exposure level, and end-use application. CAGRs derived from utility replacement cycle analysis and renewable interconnection project pipelines, with sensitivity testing around composite insulator substitution rates and EU Green Deal implementation pacing.
Revisions become necessary when EU F-Gas Regulation amendments materially alter composite insulator competitiveness, or when REACH compliance burdens trigger consolidation waves among smaller Spanish and Italian fabricators. Forecasts reflect documented assumptions regarding grid modernization mandate continuity and cohesion fund disbursement schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Lens Market
Glass
Double Glazing Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Glass Insulator Market
Glass
Advanced Glass Market
Glass
Sapphire Glass Market
Glass
3D Glass Market
Glass
North America Glass Insulators Market
Glass
France Silica Sand Market
Glass
Glazing Gel Market
Glass
Foam Glass Granulate Market
Glass
Pharmaceutical Glass Tubing Market
Glass
GCC Flat Glass Market
Glass
Solar Reflective Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Solar Control Glass Market