
 Global Glass Insulation Market | 2026-2036
Global Glass Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Insulation Market Analysis
Aerogel integration into multilayer glazing systems is rewriting thermal performance benchmarks for curtain wall assemblies. Owens Corning leverages its captive borosilicate supply to control input costs across North American batt production. Saint-Gobain anchors European demand through ISOVER-branded mineral wool lines optimized for passive house certification. Knauf Insulation competes aggressively on blown-in loose fill density ranges that meet EN 13162 without premium aerogel overlays.
Glass insulation comprises inorganic fibrous or cellular materials manufactured from silica sand, recycled glass cullet, and fluxing agents, formed through rotary spinning or flame attenuation into low-density thermal barriers with declared lambda values typically between 0.030 and 0.045 W/mK; the primary purpose is reducing conductive heat flow in building envelopes and industrial equipment. Batts and blankets dominate volume shipments due to standardized cavity dimensions in residential wood-frame construction across temperate climates, while aerogel-based boards capture disproportionate margin pools in commercial retrofit where space constraints command premium pricing. Foam glass technology leads growth in below-grade and cryogenic applications where compressive strength and hydrophobicity override raw material cost sensitivity.
The US Department of Energy's appliance and equipment standards program, California Title 24 energy code, and the EU Energy Performance of Buildings Directive collectively mandate step-downs in assembly U-values that directly expand addressable volume for high-R glass insulation. China's GB 50189 standard for public building energy efficiency and India's ECBC compliance pathways for commercial construction create parallel enforcement architectures across Asia. Stakeholders must monitor regulatory harmonization between ASHRAE 90.1 and EN ISO 6946 test protocols, as divergence in declared thermal resistance methods threatens to fragment product certification requirements and complicate cross-border specification.
Market Dynamics
Retrofit mandates across Germany and France are compressing specification cycles for high-performance glass wool, while California and New York energy codes force simultaneous upgrades in wall and roof thermal resistance. This regulatory synchronization is pulling forward demand from replacement construction and accelerating product substitution toward mineral wool and aerogel composites.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Step-downs in assembly U-values mandate mineral wool and fiberglass in commercial retrofits across France and Germany.
- China's GB 50189 standard:Provincial green building quotas in eastern provinces require mineral wool in all new public construction.
- Aerogel multilayer glazing:Integration into curtain wall assemblies is rewriting thermal benchmarks for space-constrained commercial buildings.
Market Restraints
- Borosilicate supply concentration:Captive supply chains in North America create input cost volatility for batt producers dependent on external silica sand sourcing.
- Flame attenuation energy intensity:Rotary spinning and flame attenuation processes face carbon cost exposure under EU ETS pricing mechanisms.
- Substitute rigid foam boards:Polyisocyanurate and phenolic foam capture share in below-grade applications where compressive strength requirements are less stringent.
Strategic Opportunities
- Cryogenic foam glass:Hydrophobic cellular glass technology addresses unmet demand in LNG infrastructure and industrial cold storage across the US Gulf Coast.
- Passive house certification:ISOVER-branded mineral wool lines optimized for PHI standards create specification pull in Austrian and Swiss residential markets.
- Direct-to-contractor digital channels:E-commerce platforms for blown-in loose fill bypass traditional distributor markups in Scandinavian residential markets.
Industry Challenges
- ASHRAE 90.1 and EN ISO 6946 divergence:Fragmented thermal resistance test protocols complicate cross-border product certification and delay market entry timelines.
- Rotary spinning technician scarcity:Specialized furnace operation and fiber formation expertise concentrates in aging workforce pools across Czech and Polish manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Insulation Market |
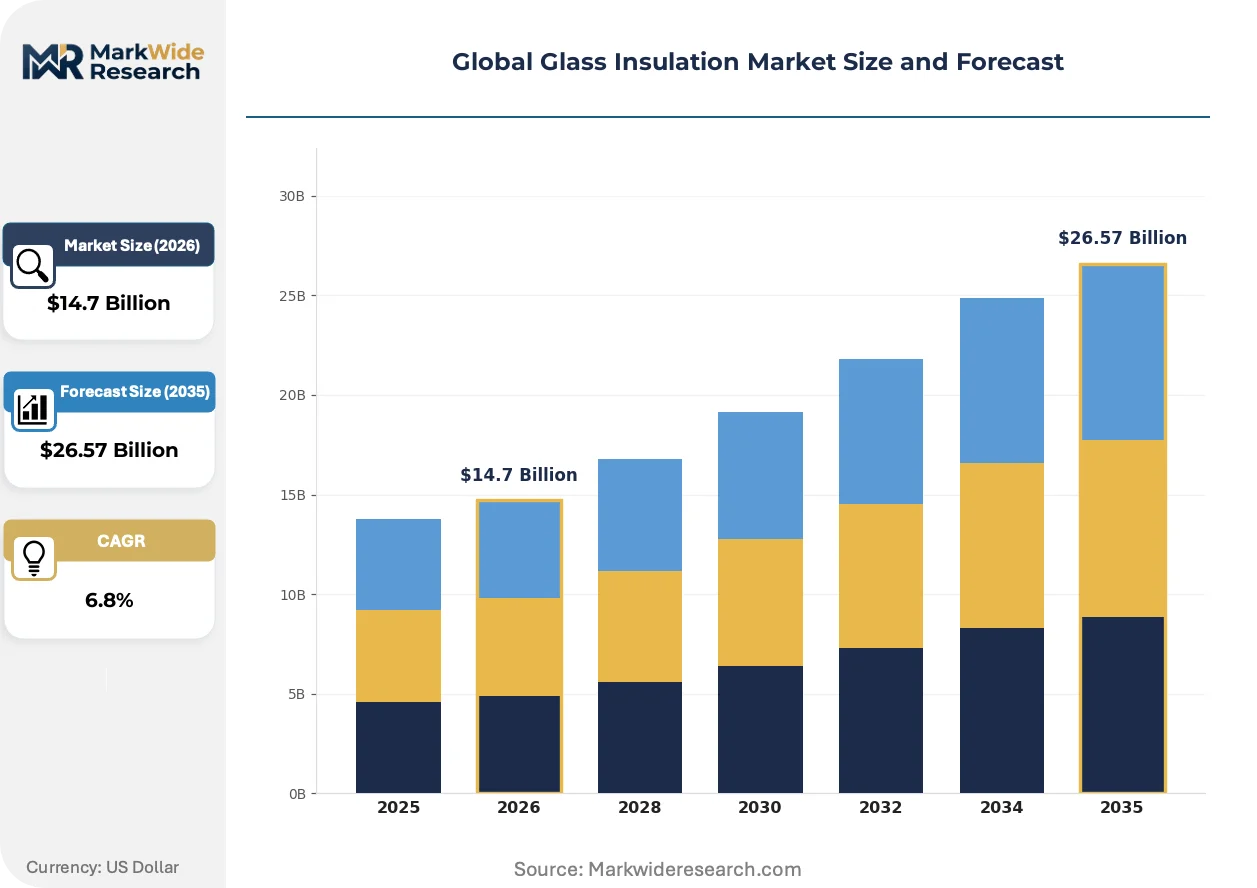
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batts, Blankets, Boards, Loose Fill Application: Residential, Commercial, Industrial, Automotive Technology: Fiberglass, Aerogel, Foam Glass, Mineral Wool End User: Contractors, Builders, Architects, Engineers |
| Companies Covered | Owens Corning, Knauf Insulation, Saint-Gobain, PPG Industries, Viracon, Nippon Sheet Glass, AGC, Johns Manville, CertainTeed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Insulation Market Emerging Trajectories
Aerogel integration is collapsing the performance gap between conventional fibrous insulation and vacuum-insulated panels. Three parallel developments are compressing specification timelines and reshaping competitive positioning across building envelope markets.
Multilayer aerogel glazing systems are collapsing the thickness-performance tradeoff that has constrained curtain wall retrofits for decades. Commercial building owners in Manhattan and London are specifying 15mm aerogel interlayers to achieve R-20 equivalent performance in 50mm assemblies. This compression is eliminating the spatial penalty that previously blocked insulation upgrades in historic facade renovations.
California Title 24 and New York Local Law 97 are synchronizing enforcement timelines that force simultaneous envelope and HVAC upgrades. Building owners face 2025-2030 compliance windows that compress procurement cycles from 18 months to 6 months. High-R glass wool batts are capturing specification share from lower-density alternatives as designers prioritize single-source envelope packages.
Blown-in loose fill density certification is shifting contractor selection criteria from brand loyalty to test-result documentation. EN 13162 compliance verification through third-party assay is displacing traditional specification-by-manufacturer in French and Belgian residential markets. This documentation-driven selection is compressing margin pools for undifferentiated commodity batts while expanding premium positioning for declared-lambda transparency.
Global Glass Insulation Market Segmentation
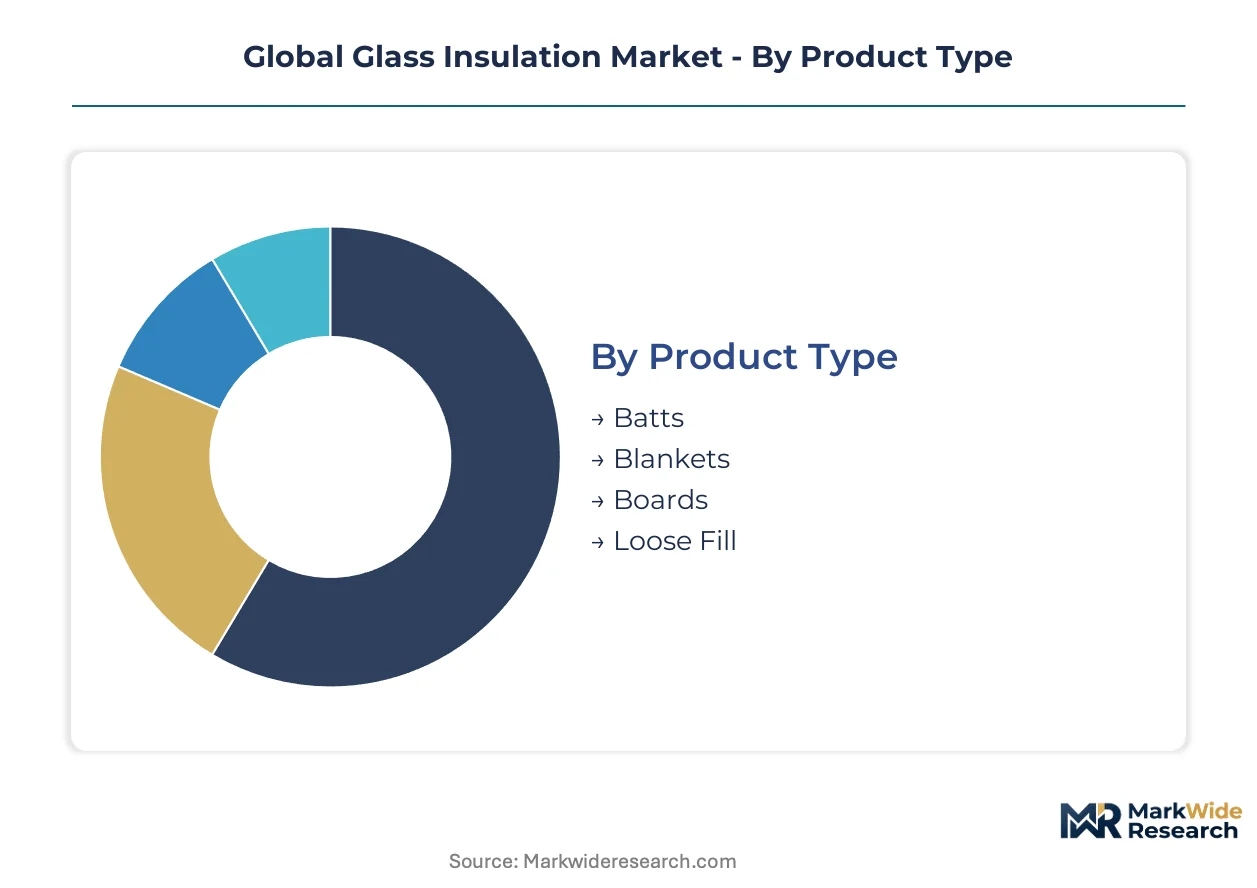
Glass insulation markets fragment across four dimensions that determine procurement patterns and margin capture. Product form dictates installation labor intensity and logistics cost. Application verticals separate code-driven retrofits from discretionary new construction. Technology tiers stratify by thermal performance and raw material input costs.
Product Type:
After-sales service intensity varies sharply across product forms, with loose fill requiring blower equipment support and batts demanding minimal field technical assistance.
- Batts:Pre-cut rectangular sections manufactured through rotary spinning of molten borosilicate glass into bonded fiber matrices with standard widths of 400-600mm. Residential wood-frame construction across Germany and France consumes standardized cavity dimensions that compress specification cycles and favor batt formats over blown alternatives. By volume, batts lead. By growth pace, loose fill is ahead.
- Loose Fill:Unbonded fiber blown into attic cavities and enclosed wall assemblies using pneumatic equipment, achieving higher installed densities than hand-placed alternatives. Scandinavian residential markets and US Midwest retrofits are concentrating specification toward EN 13162-certified density ranges that displace commodity-grade alternatives.
- Blankets:Continuous rolls of fibrous insulation without pre-cut segmentation, suited for metal building roofs and long-span commercial structures.
- Boards:Rigid compressed fiber or cellular glass panels for below-grade and flat roof assemblies where compressive strength requirements exceed batt capabilities.
By volume, batts lead. By growth pace, loose fill is ahead.
Application:
Cost tier stratification separates premium commercial retrofits from price-sensitive residential new construction, with industrial applications commanding performance premiums over thermal efficiency alone.
- Commercial:Curtain wall retrofits and roof assemblies in Manhattan and London specify aerogel interlayers and high-R mineral wool to meet Local Law 97 and comparable carbon compliance deadlines. Space constraints in historic facade renovations command 3-5x material premiums over standard batts.
- Residential:Wood-frame construction across temperate climates drives batt and loose fill volume, with passive house certification in Austria and Switzerland pulling specification toward declared-lambda transparency.
- Industrial:Process equipment, tanks, and piping insulation where service temperature ranges and mechanical durability override first-cost sensitivity.
- Automotive:NVH suppression and thermal management in electric vehicle battery enclosures, where compressive resilience and hydrophobicity specifications diverge from building envelope norms.
Commercial applications capture the highest margin pools. Residential channels move the greatest unit volumes.
Technology:
Customer type splits between specification influencers—architects and engineers selecting performance tiers—and procurement executors selecting suppliers within mandated categories.
- Fiberglass:Dominant technology formed through flame attenuation or rotary spinning of silica sand and recycled cullet into low-density thermal barriers with lambda values of 0.030-0.040 W/mK. California Title 24 and New York energy code step-downs are synchronizing demand for high-R fiberglass batts across simultaneous envelope and HVAC upgrade cycles.
- Aerogel:Silica-based nanoporous solids with thermal conductivity below 0.020 W/mK, integrated as interlayers in multilayer glazing or composite boards. Curtain wall retrofits in space-constrained commercial buildings are compressing the thickness-performance tradeoff that previously blocked insulation upgrades.
- Foam Glass:Cellular glass manufactured from recycled glass and foaming agents, providing hydrophobicity and compressive strength for below-grade and cryogenic applications. LNG infrastructure across the US Gulf Coast and industrial cold storage are driving fastest expansion for this technology tier.
- Mineral Wool:Stone or slag fibers formed through high-temperature spinning, offering fire resistance and acoustic absorption alongside thermal performance. China's GB 50189 mandates mineral wool in all new public construction across eastern provinces.
Fiberglass commands installed volume leadership. Aerogel is climbing the fastest on value terms.
End User:
Supply concentration shapes contractor access patterns, with direct-to-contractor digital channels bypassing traditional distributor markups in fragmented residential markets.
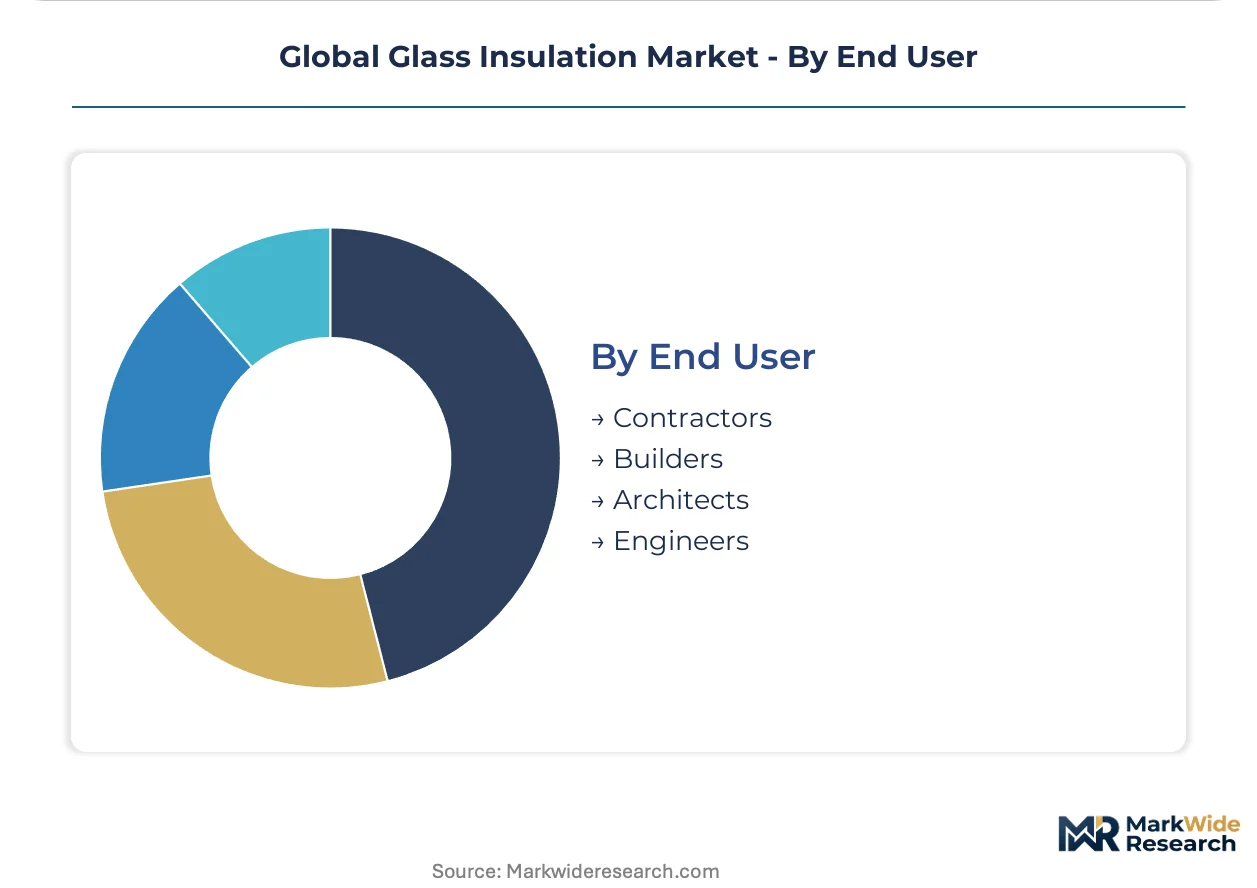
- Contractors:Installation firms selecting products based on labor productivity, equipment compatibility, and code compliance documentation. EN 13162 third-party assay verification is displacing brand-loyal specification in French and Belgian residential markets.
- Builders:Production homebuilders and commercial developers optimizing material cost against construction cycle time, with standardized cavity dimensions favoring batt formats.
- Architects:Design professionals specifying thermal performance targets and aesthetic constraints, increasingly selecting aerogel composites for curtain wall assemblies in premium commercial projects.
- Engineers:Technical specifiers calculating assembly U-values and condensation risk, driving demand for declared-lambda transparency and ASHRAE 90.1 compliance verification.
Contractors execute the majority of procurement decisions. Architects influence the highest-value specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glass wool exports supply retrofit contractors across France and Benelux, while Chinese mineral wool shipments dominate public construction procurement in Southeast Asia. This trade-flow architecture concentrates high-value specification influence in Western European manufacturing clusters and volume production in Chinese eastern provinces.
United States
California Title 24 energy code step-downs and New York Local Law 97 carbon compliance deadlines are synchronizing demand for high-R fiberglass batts. The US Department of Energy's appliance standards program mandates assembly U-value reductions that expand addressable volume for glass insulation. Manufacturing clusters in the Midwest and Southeast supply batt and loose fill products to contractors executing compressed 6-month procurement cycles.
Germany
Commercial building retrofit programs across Bavaria and North Rhine-Westphalia are accelerating specification of high-performance glass wool systems for passive house certification. The EU Energy Performance of Buildings Directive mandates mineral wool and fiberglass in commercial retrofits. Industrial concentration in the Rhine-Ruhr corridor anchors production of ISOVER-branded mineral wool lines optimized for stringent thermal performance targets.
China
Provincial green building quotas in eastern provinces now require mineral wool and fiberglass insulation in all new public construction under GB 50189 standards. The Yangtze River Delta and Pearl River Delta manufacturing bases supply standardized batt formats for wood-frame construction. Shanghai and Hangzhou municipal governments enforce compliance pathways that concentrate demand in high-density urban districts.
France
Retrofit mandates in Île-de-France and Auvergne-Rhône-Alpes are compressing specification cycles for high-performance glass wool in historic facade renovations. The EU Energy Performance of Buildings Directive step-downs in assembly U-values drive commercial building envelope upgrades. Paris metropolitan area contractors prioritize EN 13162-certified density ranges that displace commodity-grade alternatives through third-party assay verification.
India
ECBC compliance pathways for commercial construction in Maharashtra and Gujarat create enforcement architectures parallel to European and North American codes. The Bureau of Energy Efficiency mandates thermal resistance improvements in new public and commercial buildings. Mumbai and Ahmedabad industrial clusters supply fiberglass and mineral wool products to contractors navigating fragmented certification requirements across state jurisdictions.
Global Glass Insulation Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates around multinational building materials conglomerates with captive borosilicate supply chains and regional specialists competing on blown-in loose fill density certification. Three archetypes dominate: integrated glass-to-insulation manufacturers, standalone mineral wool producers, and aerogel technology licensors. Competitive moves center on backward integration into raw material sourcing and direct-to-contractor digital channel expansion.
Within the integrated-manufacturer tier, Owens Corning and Saint-Gobain exemplify archetypes combining captive glass supply with broad product portfolios. Knauf Insulation occupies a position as a standalone mineral wool specialist competing aggressively on density certification transparency. These three entities represent contrasting strategic postures: upstream control over borosilicate inputs versus specification-driven premium positioning versus contractor-facing service intensity.
| Leading Market Players |
|---|
| Owens Corning |
| Knauf Insulation |
| Saint-Gobain |
| PPG Industries |
| Viracon |
| Nippon Sheet Glass |
| AGC |
| Johns Manville |
| CertainTeed Corporation |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr corridor freight networks linking German manufacturing clusters to French retrofit contractors impose differential logistics costs that amplify pricing power for captive borosilicate producers while squeezing margin pools for external silica sand dependent batt manufacturers across Eastern European markets.
Pricing Analysis
Fiberglass-to-aerogel-to-foam glass technology-generation pricing gaps stratify the market into three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects declared lambda certification grades under EN ISO 6946 and ASHRAE 90.1 protocols, with volume scale discounts compressing unit economics for residential contractors. Pricing pressure stems from carbon cost exposure under EU ETS mechanisms affecting flame attenuation energy intensity. Residential wood-frame builders exhibit highest price sensitivity, while Manhattan and London commercial retrofitters absorb 3-5x material premiums for space-constrained aerogel interlayers.
Supply Chain Analysis
Contract manufacturing concentration among Owens Corning's captive North American facilities, Saint-Gobain's ISOVER-branded European lines, and Knauf Insulation's standalone mineral wool plants shapes capacity allocation across regions. Supply concentrates in the United States, Germany, and China, with raw material dependencies on borosilicate glass, recycled cullet, and fluxing agents. Single-source vulnerability around rotary spinning technician scarcity in Czech and Polish manufacturing clusters threatens production continuity. Distribution runs through building materials distributors with direct-to-contractor digital channels bypassing traditional markups in Scandinavian residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Glass Insulation Market sits in early-cycle expansion as EU Energy Performance of Buildings Directive step-downs and China's GB 50189 provincial mandates synchronize enforcement timelines that pull forward retrofit demand from replacement construction cycles.
For Market Incumbents: Entrench specification control through backward integration into borosilicate supply chains that neutralize input cost volatility from external silica sand sourcing. Expand EN 13162-certified density range documentation to displace commodity-grade competitors in French and Belgian residential markets through third-party assay verification. Prioritize rotary spinning technician training programs to mitigate workforce aging risks in Central European manufacturing clusters.
For New Entrants and Emerging Players: Cryogenic foam glass applications across US Gulf Coast LNG infrastructure represent the most penetrable entry point given performance premiums overriding raw material cost sensitivity. Direct-to-contractor digital platforms for blown-in loose fill in Scandinavian markets bypass entrenched distributor relationships. Target passive house certification-optimized mineral wool lines in Austrian and Swiss residential segments where declared-lambda transparency commands specification pull.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates seeking to divest non-core insulation assets amid portfolio rationalization pressures. Five-to-ten year viability hinges on regulatory harmonization between ASHRAE 90.1 and EN ISO 6946 test protocols that would consolidate certification requirements and accelerate cross-border market entry. Monitor EU ETS carbon pricing trajectories as the critical inflection signal for production cost competitiveness across flame attenuation-dependent manufacturers.
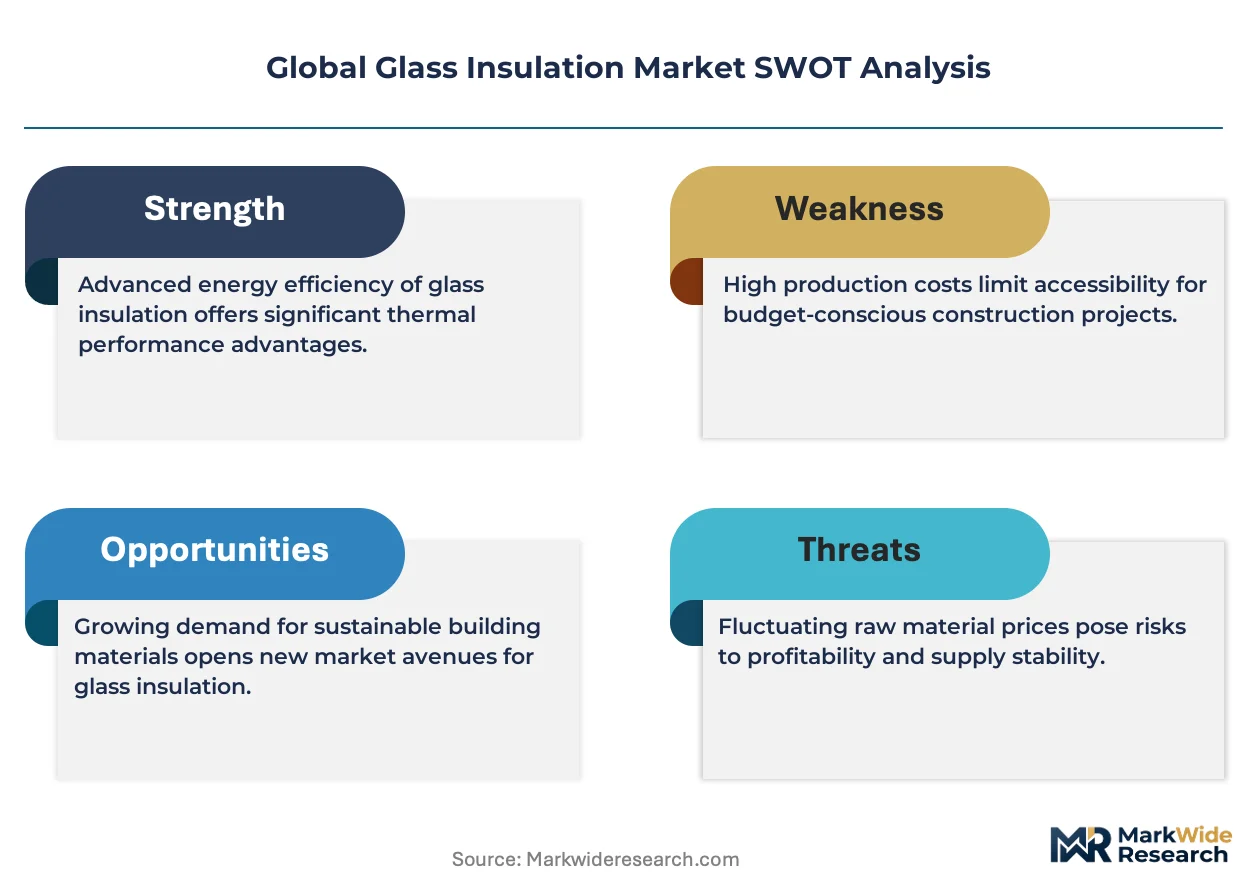
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Supply | Owens Corning's captive supply chain neutralizes silica sand price volatility across North American batt production. |
| Aerogel Multilayer Glazing Partnerships | Saint-Gobain's curtain wall assembly collaborations capture R-20 equivalent performance in 50mm historic facade renovations. |
| EN 13162 Certification Investment | Knauf Insulation's third-party density assay verification displaces brand-loyal specification in French residential markets. |
| Direct-to-Contractor Digital Channel Expansion | Scandinavian e-commerce platforms for blown-in loose fill bypass traditional distributor markups and compress procurement cycles. |
| Cryogenic Foam Glass Capacity Addition | US Gulf Coast manufacturing positions capture LNG infrastructure demand where hydrophobicity specifications override first-cost sensitivity. |
Methodological Framework
The analysis maps fiberglass, aerogel, foam glass, and mineral wool technology tiers, each validated through plant managers at rotary spinning facilities, procurement leads at commercial construction firms, distribution channel partners, and technical R&D directors overseeing lambda value certification. Primary interviews combined with secondary validation from customs and trade data, SEC 10-K filings, EU ETS carbon market reports, and national energy code documentation. Bottom-up installation volume estimates triangulated against top-down building stock modeling across Germany, France, China, and the United States.
Assumptions held fixed include current EU Energy Performance of Buildings Directive U-value step-down schedules and China's GB 50189 provincial enforcement pathways, while carbon pricing trajectories and ASHRAE 90.1 revision timing were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product form, application vertical, technology tier, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs derived from regression analysis against historical retrofit penetration rates and new construction floor area forecasts, with inputs from building energy code stringency indices and industrial cold storage capacity expansion plans.
Practitioners should monitor EU ETS price levels, ASHRAE 90.1-EN ISO 6946 harmonization negotiations, and rotary spinning technician workforce demographics for early signals of forecast revision triggers. Quarterly review of carbon market futures, certification protocol divergence indicators, and passive house certification uptake rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Thin Insulation Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Insulation Market