
 Phenolic Panel Market | 2026-2036
Phenolic Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Phenolic Panel Market Outlook
Healthcare and laboratory infrastructure is consolidating its share of phenolic panel consumption as infection-control specifications harden. Wilsonart International Holdings LLC leverages its North American manufacturing footprint to serve this vertical with specialized surfacing solutions. Fundermax GmbH anchors European demand through its facade systems division, while Trespa International BV competes on exterior cladding performance in institutional builds across the Benelux region.
Phenolic panels are rigid composite sheets formed from phenolic resin-impregnated kraft paper layers cured under heat and pressure, typically achieving densities of 1.4–1.5 g/cm³ and Class A fire ratings. These panels serve primarily as durable, chemically resistant surfacing for interior architecture, laboratory furniture, and exterior rainscreen systems where hygiene and flame retardancy are mandatory. Honeycomb phenolic configurations lead volume in aerospace and rail applications where weight reduction governs specification, while fire-resistant grades command premium positioning in high-rise facade markets. High-pressure laminates sustain the broadest end-user penetration across furniture components and interior walls, though laminated variants are gaining share in modular construction for faster on-site assembly.
EMA's Construction Products Regulation and REACH chemical compliance frameworks govern material composition and emissions disclosure across European supply chains, while ASTM E84 and NFPA 285 in the United States dictate surface-burning and fire-propagation standards for exterior installations. China's GB 8624 classification and Japan's JIS A 1321 test methods add further certification layers for exporters targeting Asia-Pacific project tenders. Stakeholders must monitor evolving facade-fire regulations in multiple jurisdictions, as code harmonization between EU CPR and emerging economy standards will determine which resin formulations and core constructions retain market access.
Market Dynamics
Facade fire-safety code convergence between EU Construction Products Regulation and evolving ASTM E84 test protocols is compressing specification cycles and forcing resin formulation upgrades across manufacturing footprints.
Growth Catalysts
- EU energy-efficiency retrofits:Germany's accelerated building renovation mandates under the EU Green Deal are pulling high-pressure phenolic systems into facade replacement cycles at scale.
- Healthcare infection-control hardening:Laboratory and hospital infrastructure specifications now require chemically resistant surfacing that phenolic panels deliver through kraft-paper resin saturation.
- Honeycomb core innovation:Aerospace and rail OEMs specify lightweight phenolic honeycomb configurations for interior panels where weight reduction governs fuel efficiency.
Market Restraints
- Formaldehyde feedstock volatility:Phenolic resin production depends on petrochemical-derived precursors subject to energy-price swings and refinery output fluctuations.
- Specialized press capacity concentration:High-pressure laminate manufacturing requires capital-intensive multi-daylight presses concentrated in Germany, Japan, and the US.
- Mineral wool substitution:Stone wool and glass wool facade insulation systems compete on installed cost in mid-rise commercial construction.
Strategic Opportunities
- Modular construction penetration:Prefabricated building modules specify laminated phenolic panels for faster on-site assembly and reduced wet-trade labor.
- India building code alignment:BIS fire-rating harmonization with ISO 1182 and EN 13501 creates certification pathways for phenolic facade systems in high-rise construction.
- Digital specification platforms:Building information modeling libraries now embed phenolic panel performance data directly into architect workflow tools.
Industry Challenges
- Multi-jurisdiction certification timelines:ASTM E84, NFPA 285, and EN 13501-1 testing sequences extend product launch cycles by 18-24 months.
- Resin chemistry talent scarcity:Formulation chemists with phenolic curing expertise concentrate at legacy manufacturers, constraining new entrant R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenolic Panel Market |
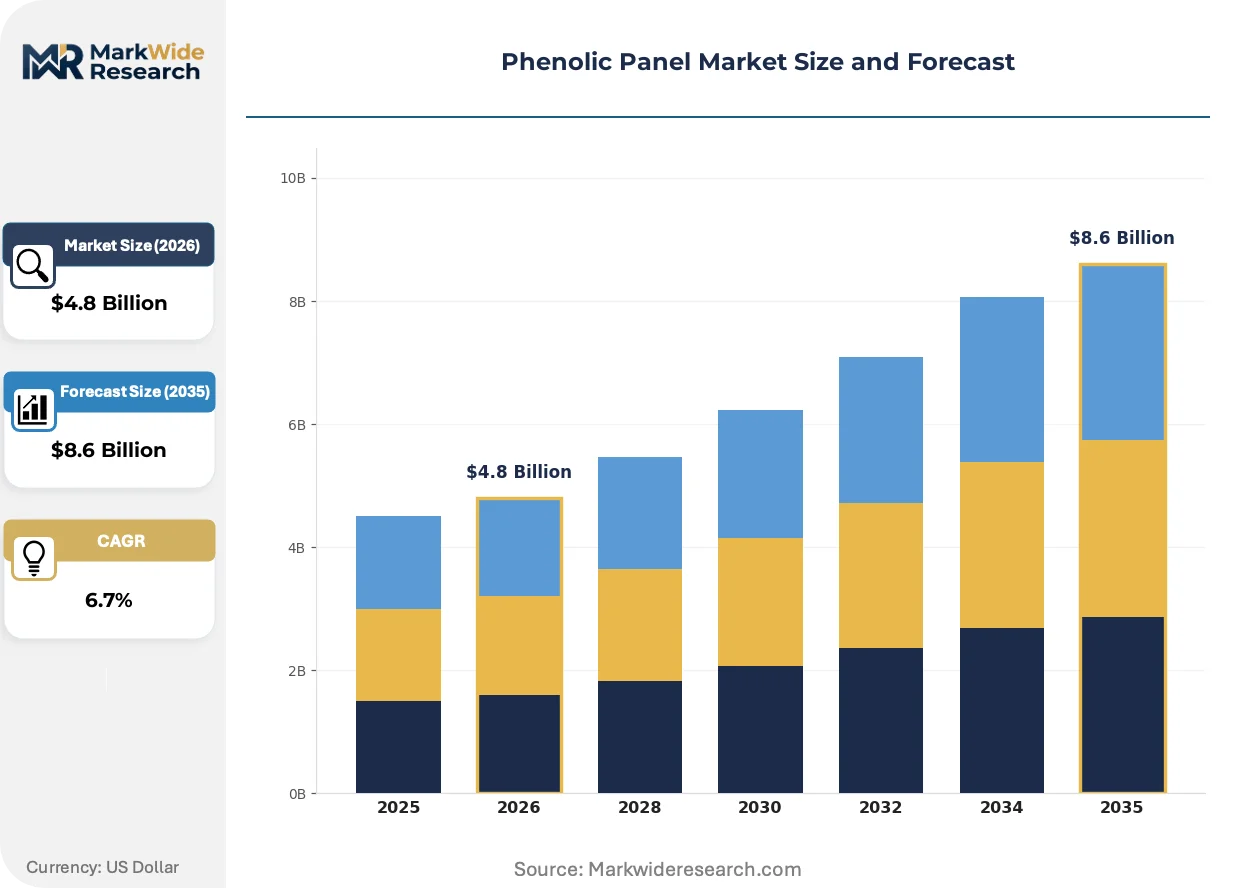
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honeycomb, Laminated, Fire-Resistant, High-Pressure Application: Interior Walls, Exterior Facades, Ceiling Tiles, Furniture Components End User: Construction, Automotive, Aerospace, Marine Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Wilsonart International Holdings LLC, Abet Laminati S.p.A., Trespa International BV, Merino Group, Greenlam Industries Ltd., Fundermax GmbH, Arpa Industriale S.p.A., Stylam Industries Ltd., Formica Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenolic Panel Market Strategic Shifts
Digital fabrication and bio-based resin chemistry are converging to redefine how phenolic panels are specified, produced, and installed across commercial and transportation applications.
Low-emission phenolic formulations are rewriting material selection criteria for interior air quality. Architects specifying LEED and WELL-certified buildings now prioritize panels meeting CDPH Section 01350 VOC thresholds. This shift compresses demand for conventional high-formaldehyde products while expanding addressable market in healthcare and education verticals.
REACH chemical disclosure requirements and evolving ECHA SVHC candidate list entries are forcing resin suppliers to document supply chain composition. Manufacturers must now map kraft paper and phenol sourcing through tier-three suppliers. German facade system integrators respond by consolidating qualified supplier pools and demanding third-party EPD verification.
Specification behavior now favors performance-guaranteed supply agreements over spot purchasing. Large commercial contractors in the US bundle phenolic panel procurement with installation warranties through single-source distributor relationships. This consolidation concentrates volume with national distributors holding NFPA 285 fire-engineering expertise and certified installer networks.
Phenolic Panel Market Segmentation
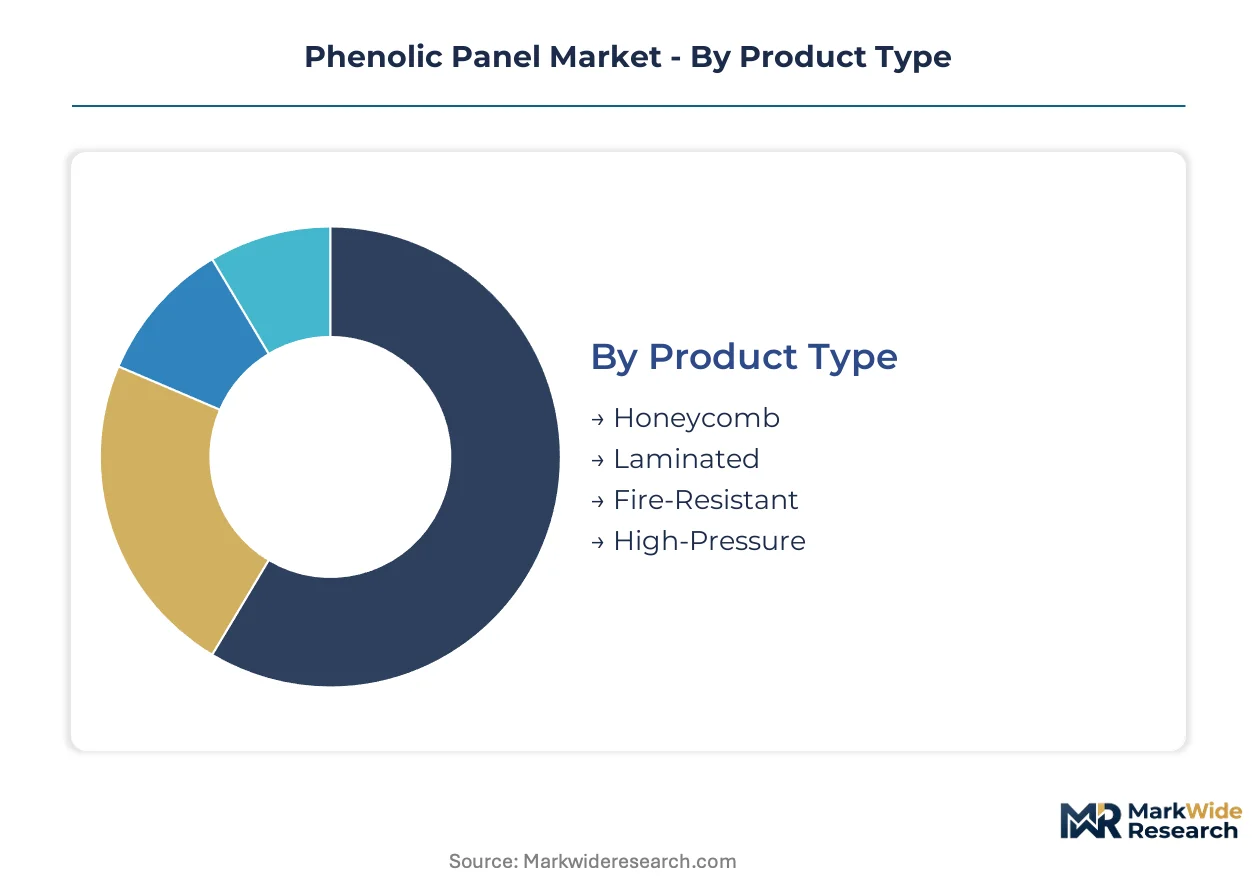
Phenolic panel specification behavior varies sharply across product construction, installation context, and procurement pathway. Manufacturers configure resin saturation, core density, and surface finish to match fire-rating requirements and weight constraints in each vertical.
Product Type:
Technical construction—honeycomb core geometry, laminate layer count, and resin cure profiles—determines performance tier and pricing band.
- Honeycomb:Hexagonal cell structures bonded with phenolic resin achieve density below 0.5 g/cm³ while maintaining structural integrity. Aerospace OEMs in Toulouse and Hamburg specify these configurations for galley and partition panels where every kilogram affects fuel burn.
- Fire-Resistant:Enhanced resin formulations and denser kraft-paper saturation push flame-spread indices below 25 on ASTM E84. High-rise facade projects in Dubai and Singapore mandate these grades for NFPA 285 compliance on buildings exceeding 75 meters.
- High-Pressure:Multi-daylight press curing at 1,400 psi delivers surface hardness resistant to laboratory chemical exposure. Wilsonart and Fundermax dominate this tier through captive press capacity in Texas and Austria.
- Laminated:Pre-finished surface layers enable rapid field installation without wet trades. Modular construction contractors in California and Ontario specify these for accelerated project schedules.
High-Pressure leads on scale; Honeycomb leads on momentum.
Application:
Installation environment dictates moisture resistance, UV stability, and impact durability requirements.
- Exterior Facades:Rainscreen systems require open-joint detailing and freeze-thaw cycling resistance. German facade renovators under EU Green Deal mandates specify high-pressure phenolic systems for energy retrofit projects in Berlin and Munich.
- Interior Walls:Healthcare and education verticals prioritize low-VOC emissions and cleanability. LEED-certified hospital projects in Massachusetts and Washington specify CDPH Section 01350-compliant panels for patient room surfacing.
- Furniture Components:Laboratory casework and chemical-resistant worktops demand impervious surfaces. University research facilities in Oxford and Stanford specify these for fume hood surrounds and benchtops.
- Ceiling Tiles:Acoustic-rated phenolic panels with perforated faces serve rail and aviation interior applications. Hitachi Rail and Alstom specify these for passenger compartment noise reduction.
Interior Walls commands installed volume; Exterior Facades climbs fastest on regulatory tailwinds.
End User:
Customer technical sophistication and procurement scale shape specification authority and contract structure.
- Construction:General contractors and facade system integrators bundle panel procurement with installation warranties. Turner Construction and Skanska consolidate volume through national distributor relationships holding NFPA 285 engineering expertise.
- Aerospace:Tier-1 OEMs and their seating suppliers dictate honeycomb core geometries and fire-testing protocols. Safran and Collins Aerospace qualify panel sources through multi-year supply agreements with burn-test documentation.
- Automotive:Electric vehicle battery enclosure manufacturers evaluate phenolic composites for thermal runaway containment. BMW and Porsche engineering teams test resin formulations for 1,000°C flame resistance.
- Marine:Cruise ship refurbishments and naval vessel interiors specify IMO-compliant low-flame spread materials. Meyer Werft in Papenburg and Fincantieri in Monfalcone drive specification for passenger cabin partitions.
Construction anchors demand volume; Aerospace commands premium pricing through qualification barriers.
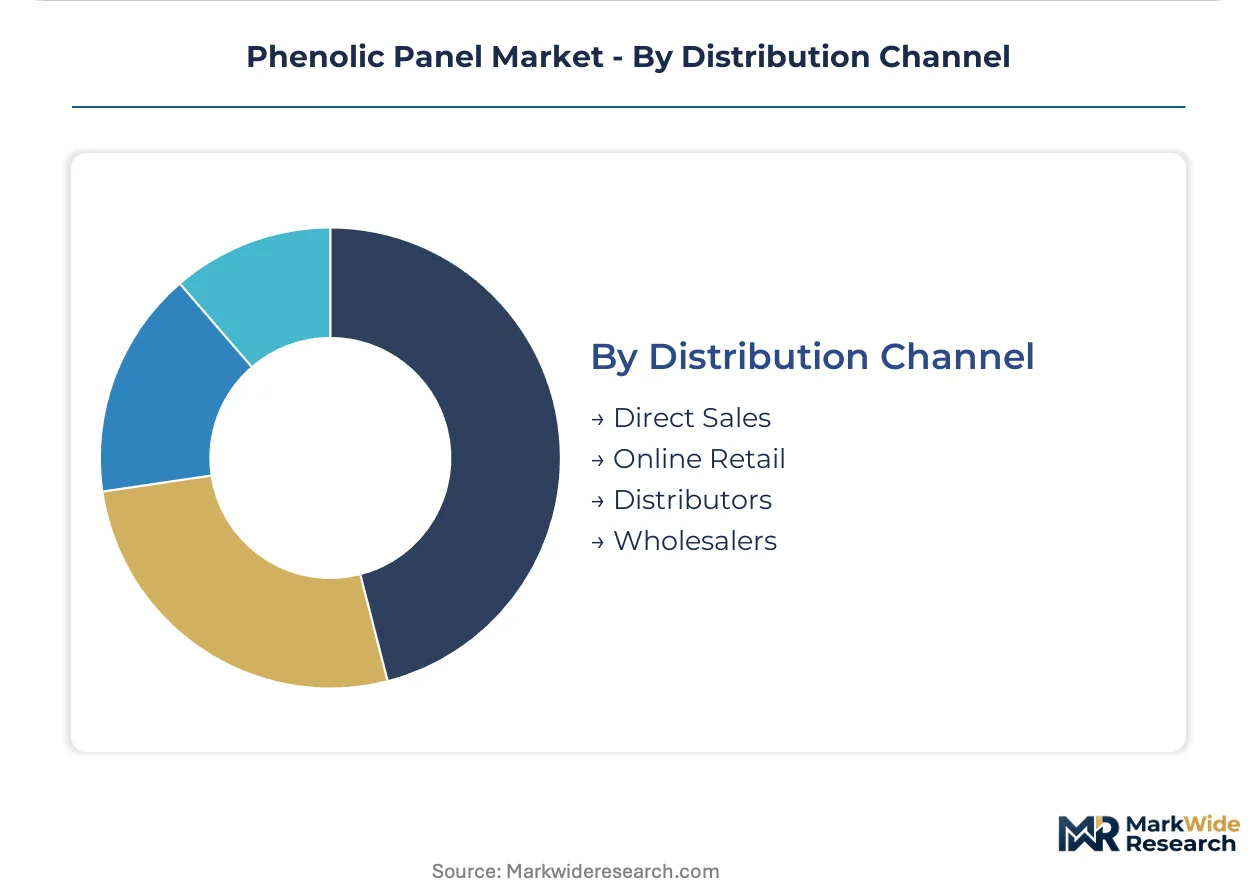
Distribution Channel:
Channel structure reflects project scale, technical support requirements, and geographic coverage needs.
- Distributors:National and regional stocking distributors hold inventory and provide cut-to-size fabrication. US-based Laminart and Panel Specialists maintain CNC routing capacity for architect-specified dimensions.
- Direct Sales:Large facade contractors and rail OEMs negotiate frame contracts directly with Fundermax, Trespa, and Wilsonart for guaranteed allocation and project-specific color matching.
- Wholesalers:Building material wholesalers serve mid-size commercial contractors with standard dimensions and stocked colors. Beacon Roofing Supply and Allied Building Products carry phenolic panel SKUs in major US metro markets.
- Online Retail:Digital platforms capture small-project and replacement demand from facility maintenance teams. Specialized architectural surfacing e-commerce sites offer sample ordering and specification downloads.
Distributors dominate transaction volume; Direct Sales captures margin through relationship lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping phenolic panel manufacturing footprints as producers migrate toward jurisdictions with streamlined fire-certification pathways and lower compliance costs. Manufacturers now site multi-daylight press capacity in countries offering faster EN 13501-1 or ASTM E84 approval timelines.
Germany
Facade renovation mandates under the EU Green Deal are accelerating specification rates for high-pressure phenolic systems in commercial retrofit projects. EMA's Construction Products Regulation governs material composition and emissions disclosure across supply chains. Berlin and Munich industrial clusters concentrate qualified system integrators serving energy-efficiency retrofits at scale.
United States
Healthcare infrastructure expansion and laboratory construction are hardening demand for chemically resistant surfacing solutions. ASTM E84 and NFPA 285 standards dictate surface-burning and fire-propagation requirements for exterior installations. Texas-based manufacturing footprints serve North American distribution networks with specialized press capacity.
China
High-rise commercial construction and rail infrastructure projects are expanding addressable market for fire-rated facade materials. GB 8624 classification standards add certification layers for domestic and export project tenders. Yangtze River Delta manufacturing zones concentrate laminate production for modular construction applications.
India
Building code alignment with international fire-rating standards is creating certification pathways for phenolic facade systems in urban high-rise development. BIS harmonization with ISO 1182 and EN 13501 enables specification in premium commercial projects. Maharashtra and Gujarat industrial corridors attract panel fabricators serving domestic infrastructure growth.
Japan
Transportation interior applications and healthcare facility specifications sustain demand for low-emission phenolic configurations. METI oversees JIS A 1321 test methods governing flame-spread performance in rail and aviation sectors. Osaka-Nagoya industrial clusters concentrate honeycomb core manufacturing for aerospace OEM supply chains.
Phenolic Panel Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated European firms commanding premium positioning in facade systems while Asian fabricators capture volume in standard-grade interior applications. The market structure tilts toward consolidation at the high-pressure laminate tier where capital-intensive multi-daylight press capacity creates entry barriers. Three archetypes dominate: legacy European facade system integrators, North American surfacing specialists with healthcare vertical focus, and Asian volume producers serving modular construction. Competitive moves center on backward integration into resin formulation and strategic partnerships with certified installer networks.
Among European facade system integrators, Fundermax GmbH and Trespa International BV exemplify the premium-tier archetype through Austrian and Dutch manufacturing heritage respectively. Wilsonart International Holdings LLC represents North American positioning with Texas-based production infrastructure. These three firms anchor distinct geographic demand centers while occupying positions across high-pressure laminate and specialized surfacing tiers.
| Leading Market Players |
|---|
| Wilsonart International Holdings LLC |
| Abet Laminati S.p.A. |
| Trespa International BV |
| Merino Group |
| Greenlam Industries Ltd. |
| Fundermax GmbH |
| Arpa Industriale S.p.A. |
| Stylam Industries Ltd. |
| Formica Group |
| Others |
Value Chain & Pricing Dynamics
Facade system integrators in Germany and the United States consolidate procurement volume through multi-year frame contracts, locking in project-based pricing with installation warranty bundling that compresses spot-market participation. This buyer concentration rewards national distributors holding NFPA 285 fire-engineering expertise with margin capture on technical specification support.
Pricing Analysis
Distributor markups of 15-25 percentage points separate national stocking distributors from direct-to-OEM channels serving aerospace and rail OEMs. Pricing stratifies across fire-resistant, high-pressure, and honeycomb tiers based on EN 13501-1 certification grade and resin formulation complexity. Cost compression in standard-grade interior laminates is intensifying because Asian volume producers are expanding modular construction supply agreements. Small commercial contractors and facility maintenance teams exhibit highest price sensitivity, while tier-1 aerospace OEMs prioritize burn-test documentation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Safran, Collins Aerospace, and Alstom through qualified supplier programs with multi-year allocation guarantees. Manufacturing draws from phenol feedstock anchored in Germany, Japan, and Texas, with kraft paper sourcing concentrated in Scandinavian pulp mills and Southeast Asian recycled fiber processors. Single-source vulnerability in specialized multi-daylight press capacity creates bottleneck risk, as legacy equipment concentration in Austria and Japan constrains rapid volume scaling. Distribution runs through three-tier structures: direct sales for facade contractors, national distributors for commercial construction, and digital platforms for small-project replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phenolic panel market functions as a regulatory compounder where EU Green Deal renovation mandates and evolving ASTM E84 test protocols continuously harden material specifications and extend certification timelines. This regulatory density creates durable competitive moats for incumbents with established fire-testing documentation.
For Market Incumbents: Anchor market position through backward integration into low-emission resin formulation and captive multi-daylight press capacity expansion in Texas or Austria. Mineral wool substitution in mid-rise commercial facades and formaldehyde feedstock volatility represent dual threats requiring supplier pool consolidation and third-party EPD verification to defend specification authority. For New Entrants and Emerging Players: The price-point gap between premium European facade systems and economy-grade Asian interior laminates creates white-space opportunity in India and Southeast Asia modular construction. Target BIS fire-rating harmonization pathways and digital specification platform integration as entry vectors, with laminated panel configurations for accelerated on-site assembly offering fastest penetration. For Investors and Strategic Acquirers: Building material distributors with NFPA 285 engineering expertise are the most active acquirer in this space, consolidating certified installer networks to capture installation warranty bundling margins. The 5-10 year viability window favors targets with REACH-compliant resin chemistry and established EN 13501-1 test documentation. Monitor ECHA SVHC candidate list expansion as inflection signal for formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive phenolic chemistry control secures supply against formaldehyde feedstock volatility. |
| Multi-Daylight Press Capacity Expansion | Texas or Austria manufacturing footprints serve healthcare and facade retrofit demand clusters. |
| Digital Specification Platform Partnership | BIM library embedding enables architect workflow integration and specification lock-in. |
| Certified Installer Network Acquisition | Installation warranty bundling concentrates volume with distributors holding NFPA 285 expertise. |
| Low-Emission Product Line Launch | CDPH Section 01350 compliance opens LEED and WELL-certified building verticals. |
Study Parameters
Bottom-up construction and aerospace modeling reconciled against top-down resin production and press capacity tracking forms the analytical core of this study. Primary interviews with facade system integrators, laboratory furniture procurement managers, aerospace Tier-1 supplier quality directors, and phenolic resin formulation chemists combined with secondary validation from EU Construction Products Regulation filings, ASTM E84 test laboratory records, SEC 10-K disclosures from surfacing specialists, and customs trade data on phenol and kraft paper imports. Triangulation between specification behavior surveys and manufacturing capacity utilization estimates ensures demand-supply reconciliation.
Historical trendline analysis of high-pressure laminate production volumes, facade renovation permit flows in Germany, and aerospace interior panel delivery schedules established baseline growth patterns across the projection horizon. Segmentation modeling incorporates product construction tier, installation environment, end-user technical sophistication, and procurement channel structure. CAGRs derive from regression analysis against EU Green Deal spending trajectories and healthcare infrastructure capital budgets, with cross-validation against resin consumption forecasts and press capacity expansion announcements.
Caveats apply where formaldehyde feedstock price spikes, unanticipated ECHA SVHC list expansions, or delays in India BIS harmonization could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Performance Composites Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Laminar Composites Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Biocomposites Market
Composite Materials
Plastic Composites Market
Composite Materials
Composite Rollers Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Composite Cans Market
Composite Materials
Graphene Composites Market