
 Birefringent Crystals Market | 2026-2036
Birefringent Crystals Market Size, Share, and Industry Trends Forecast 2026-2036
Birefringent Crystals Market Insights
Modular polarization subsystem bundling is consolidating buyer choice across the birefringent crystals supply base. CASTECH INC. leverages captive crystal growth capacity to anchor its position in telecom-grade calcite supply. Thorlabs, Inc. differentiates through vertically integrated polishing and coating operations that reduce customer integration burden. Newport Corporation competes via broad photonics portfolio breadth that locks in multi-product procurement relationships.
Birefringent crystals exhibit anisotropic refractive indices that split incident light into orthogonally polarized ordinary and extraordinary rays, with typical birefringence values ranging from 0.01 for quartz to 0.17 for calcite depending on crystal structure and wavelength. These materials serve as the functional core of waveplates, polarizing beam splitters, and optical isolators used in laser systems, fiber optic networks, and scientific instrumentation. Synthetic crystal segments are capturing margin pools as melt-grown yttrium orthovanadate and alpha-barium borate displace natural calcite in high-power laser applications where optical damage thresholds matter most. Thin film form factors are expanding fastest in telecommunications transceivers where miniaturization drives substrate thinning below 100 micrometers.
ISO 10110 surface quality standards and RoHS substance restrictions shape material selection and fabrication protocols across European and Asian supply chains. The US FDA regulates medical laser systems incorporating these crystals through 21 CFR 1040.10 performance standards, while China's GB/T precision optics standards enforce domestic substitution in government-funded research procurement. Stakeholders must monitor divergence between national metrology standards as dual-use export controls tighten on high-purity synthetic crystal growth technology.
Market Dynamics
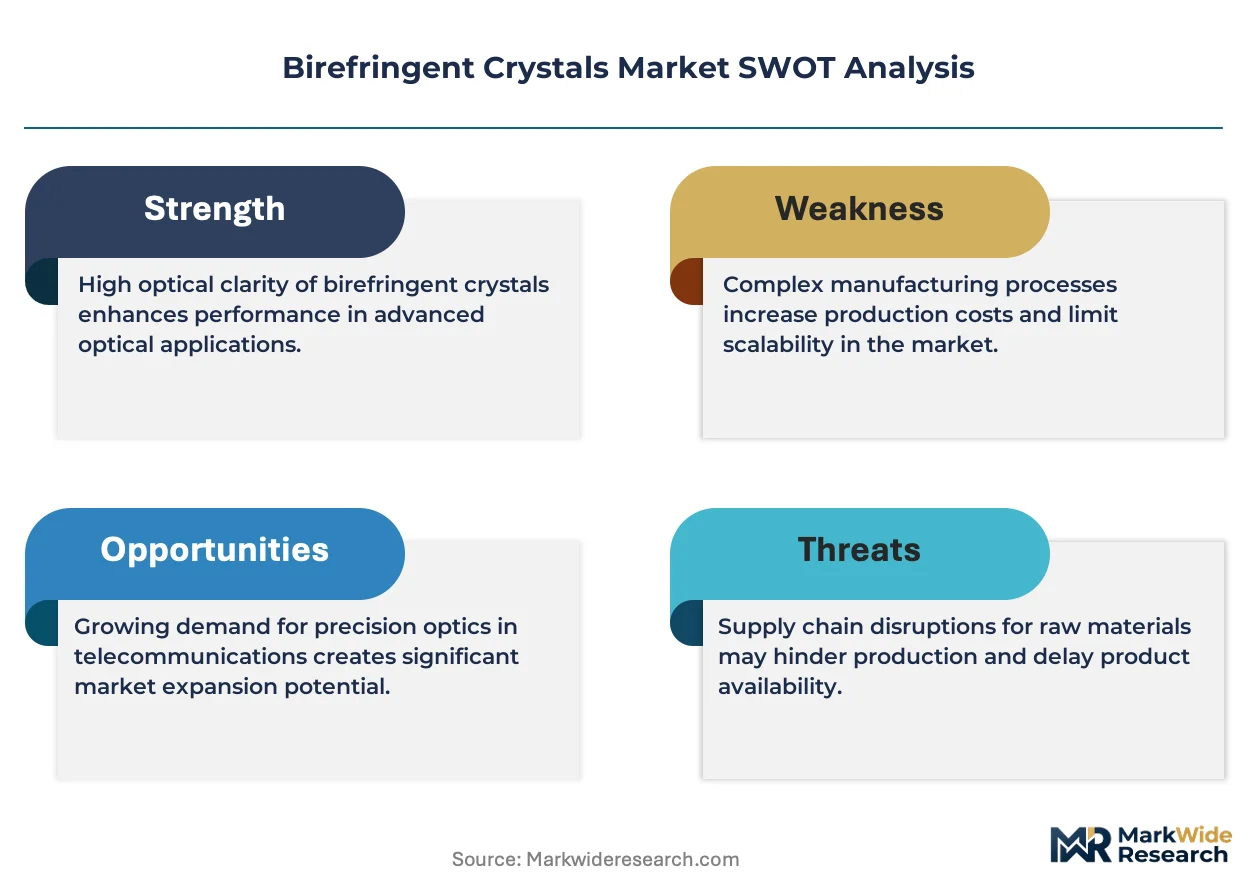
Telecommunications infrastructure buildouts are compressing procurement cycles for polarization-control components, forcing crystal suppliers to align melt-growth capacity with coherent optical transmission deployment timelines. China's MIIT 5G backhaul specifications and Germany's precision optics clusters are pulling specifications in divergent directions.
Growth Catalysts
- Coherent optical transmission:400G and 800G fiber deployments require tighter extinction ratios in polarization multiplexing systems, pulling calcite and yttrium orthovanadate into transceiver assemblies.
- RoHS substance restrictions:European electronics manufacturers are eliminating cadmium-based polarizers, redirecting procurement toward synthetic birefringent crystals that meet ECHA compliance thresholds.
- High-power laser systems:Medical device manufacturers in Japan are adopting alpha-barium borate for harmonic generation, displacing legacy quartz in dermatological and surgical platforms regulated by PMDA.
Market Restraints
- Raw material concentration:High-purity optical-grade calcite deposits concentrate in Mexico and Iceland, exposing processors to geopolitical supply interruptions and freight cost volatility.
- Synthetic growth capex:Czochralski and hydrothermal growth systems for yttrium orthovanadate require multi-million-dollar furnace investments with 18-24 month qualification timelines.
- Dual-use export controls:US Commerce Department restrictions on high-purity crystal growth technology are fragmenting equipment supply chains for non-domestic synthetic producers.
Strategic Opportunities
- Thin-film miniaturization:Substrate thinning below 100 micrometers for silicon photonics integration opens volume contracts with transceiver manufacturers serving hyperscale data centers.
- Quantum key distribution:Polarization-entangled photon sources for quantum cryptography are creating specification pull from national security agencies in South Korea and the Netherlands.
- India PLI scheme:Production-linked incentives for telecom equipment manufacturing are attracting crystal polishers and coaters to establish Gujarat and Tamil Nadu operations.
Industry Challenges
- Metrology skill scarcity:Interferometric birefringence measurement and wavefront distortion analysis require technicians trained on Zygo or Wyko systems, with limited vocational pipelines in emerging manufacturing regions.
- ISO 10110 certification timelines:Surface quality validation for scratch-dig specifications creates 8-12 week delays between polishing completion and customer acceptance.
- Legacy quartz integration:Scientific instrument OEMs maintain decades-old optical designs optimized for crystalline quartz, creating friction for synthetic crystal substitution despite superior damage thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Birefringent Crystals Market |
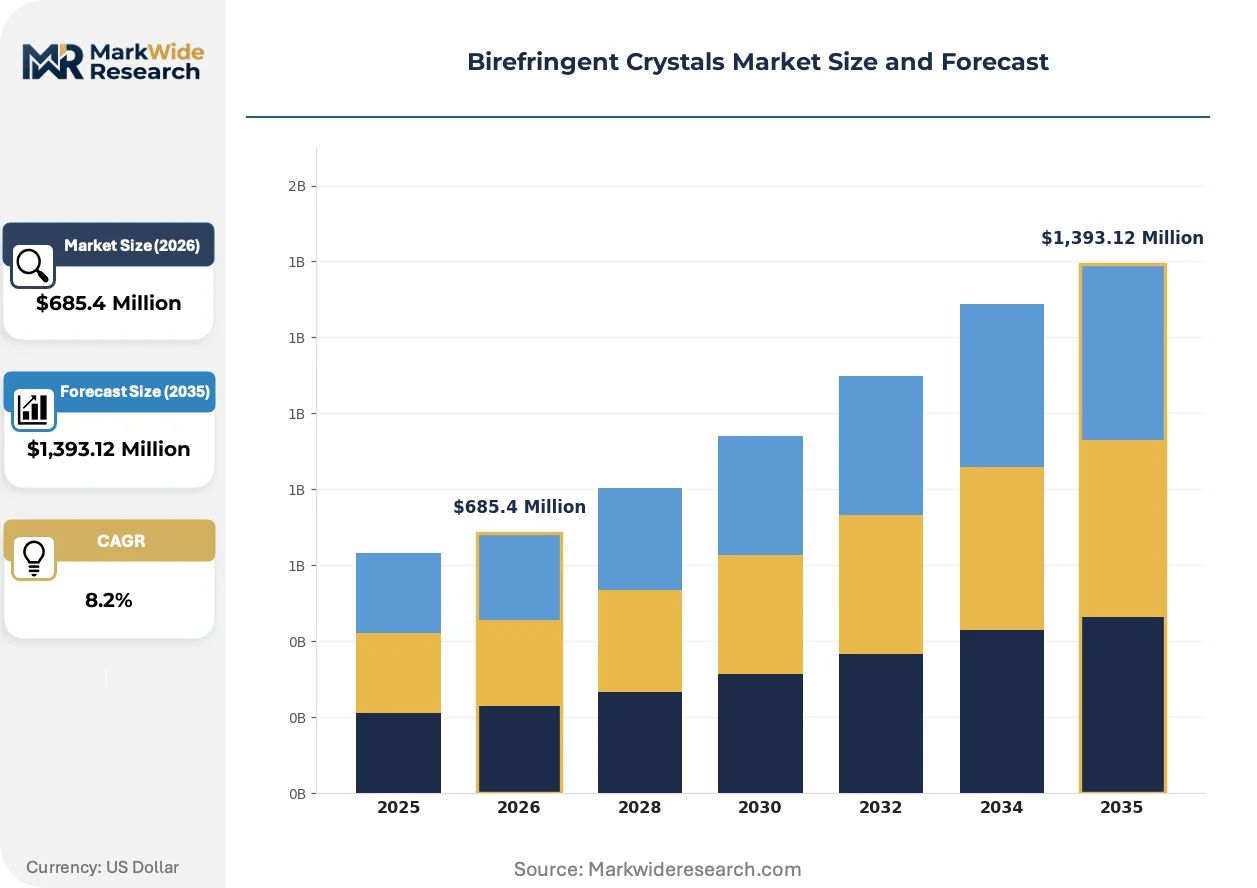
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Synthetic, Polarizers, Optical Elements Application: Telecommunications, Imaging Systems, Material Processing, Optical Filtering End User: Electronics, Aerospace, Medical, Research Institutes Form: Single Crystals, Composite Crystals, Thin Films, Bulk Crystals |
| Companies Covered | CASTECH INC., FOCtek Photonics Inc., A-Star Photonics Inc., Inrad Optics Inc., Crystal Technology, Inc., Thorlabs, Inc., Newport Corporation, Del Mar Photonics Inc., Leysop Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Birefringent Crystals Market Trends and Innovations
Synthetic crystal growth and precision polishing automation are compressing cost structures while telecommunications miniaturization is fragmenting form factor requirements across the supply base.
Thin-film lithium niobate on insulator is consolidating transceiver manufacturing around wafer-scale processing. Optical component vendors serving coherent DSP platforms are adopting this material for integrated modulators, collapsing the discrete crystal assembly steps that previously dominated polarization management. The shift is consolidating supplier tiers as wafer foundries capture functions once performed by specialized crystal houses.
REACH substance restrictions are forcing reformulation of optical coatings and polishing compounds across European supply chains. ECHA candidate list expansions covering per- and polyfluoroalkyl substances are eliminating legacy anti-reflection chemistries, compelling coaters to qualify fluorine-free alternatives with equivalent durability. German precision optics clusters in Jena and Oberkochen are responding fastest, locking in regulatory-compliant coating capacity.
Modular polarization subsystem bundling is altering procurement relationships across the value chain. System integrators serving telecom OEMs are consolidating waveplate, polarizer, and isolator sourcing into single-supplier contracts, displacing the discrete component spot-buying that previously dominated. This concentration is most visible in Shenzhen and Suzhou, where transceiver assemblers are vertically integrating optical subassembly design.
Birefringent Crystals Market Segmentation
Crystal form and manufacturing method dictate capital deployment patterns across the birefringent crystals supply base. Procurement specifications diver sharply between telecom transceiver manufacturers demanding sub-100-micrometer substrates and scientific instrument builders requiring centimeter-scale optical elements with λ/10 wavefront tolerances.
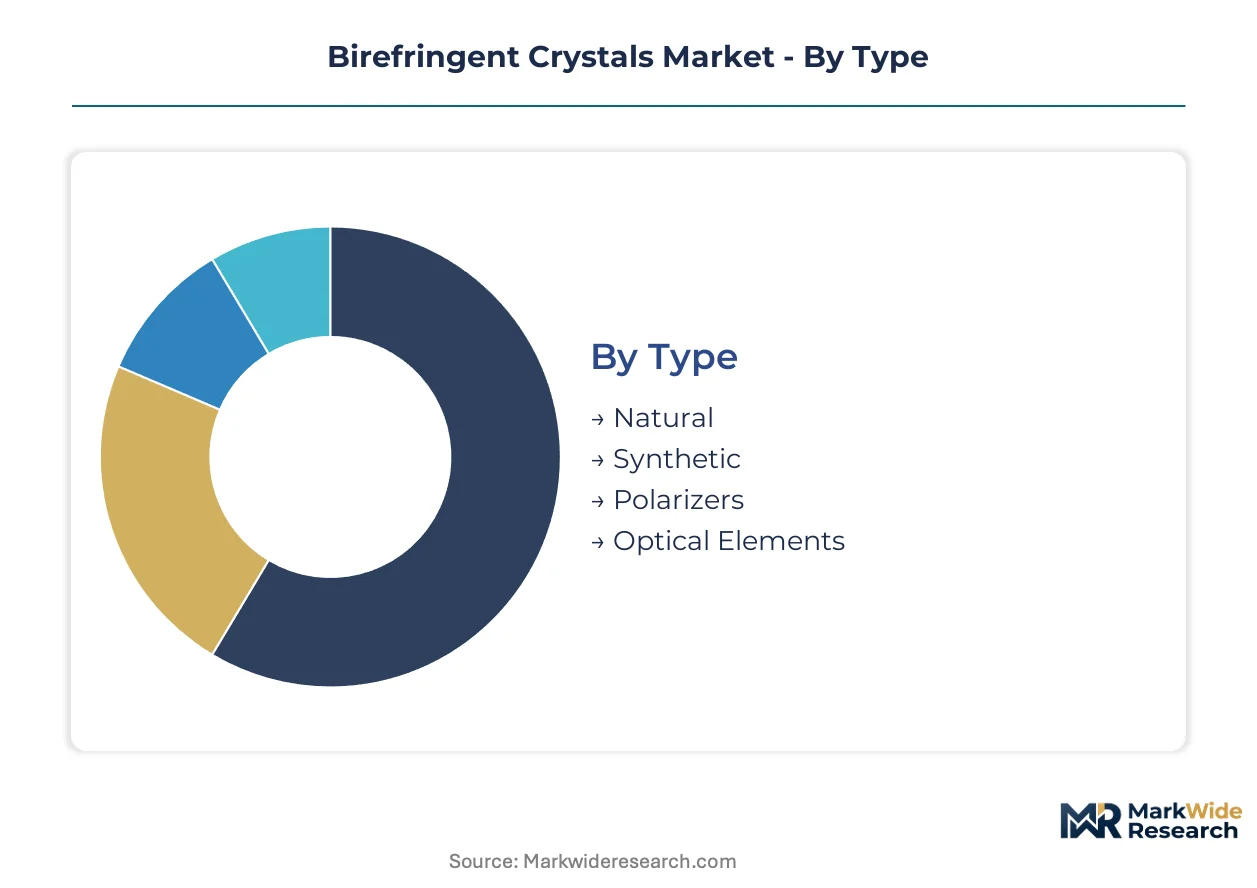
Type:
Capital intensity peaks in synthetic crystal growth, where Czochralski furnaces and hydrothermal autoclaves demand multi-million-dollar installations with 18-24 month qualification timelines.
- Natural:Optical-grade calcite from Mexican and Icelandic deposits requires minimal processing capex beyond sawing and polishing equipment. Medical laser OEMs in Japan specify natural material for harmonic generation where crystal lattice purity exceeds melt-grown alternatives.
- Synthetic:Melt-grown yttrium orthovanadate and alpha-barium borate command premium positioning through engineered defect densities and optical damage thresholds above 10 GW/cm². Telecommunications infrastructure buildouts in China and Germany are pulling synthetic volumes as coherent transmission systems require extinction ratios exceeding 30 dB.
- Polarizers:Thin-film wire-grid and crystal polarizer assemblies integrate into silicon photonics packages for 400G/800G transceivers.
- Optical Elements:Finished waveplates, beam splitters, and isolators ship as calibrated subassemblies to instrument manufacturers.
Synthetic crystals absorb the bulk of installed capacity; thin-film polarizers are expanding most quickly as wafer-scale processing displaces discrete crystal assembly.
Application:
Volume concentration follows telecommunications deployment cycles, with coherent optical transmission infrastructure consuming polarization-control components in million-unit annual quantities.
- Telecommunications:Polarization-multiplexed 400G and 800G fiber systems require tight birefringence tolerance in modulator and receiver subassemblies. China's MIIT 5G backhaul specifications and Germany's precision optics clusters are pulling specifications toward sub-0.5-degree waveplate retardation accuracy.
- Imaging Systems:Machine vision and medical endoscopy platforms specify calcite polarizing beam splitters for contrast enhancement in dermatological and surgical applications regulated by PMDA and FDA 21 CFR 1040.10.
- Material Processing:High-power laser cutting and welding systems employ alpha-barium borate for second-harmonic generation in industrial metalworking platforms.
- Optical Filtering:Spectroscopy and fluorescence instrumentation uses birefringent tunable filters for wavelength selection in research and quality control environments.
Telecommunications commands the dominant share of unit volume; material processing applications are climbing the fastest as fiber laser power scaling drives harmonic generation demand.
End User:
Customer sophistication tiers separate specification-driven aerospace and medical buyers from price-sensitive electronics assemblers serving consumer markets.
- Electronics:Transceiver manufacturers in Shenzhen and Suzhou consolidate waveplate, polarizer, and isolator sourcing into single-supplier contracts, displacing discrete component spot-buying.
- Aerospace:Satellite optical communication terminals require radiation-hardened birefringent elements with demonstrated performance across temperature extremes.
- Medical:Surgical laser systems and dermatological platforms specify alpha-barium borate and yttrium orthovanadate for harmonic generation, with PMDA and FDA 21 CFR 1040.10 governing device approval timelines.
- Research Institutes:National laboratories and university physics departments procure custom-cut crystals for quantum optics and spectroscopy experiments, with China's GB/T standards enforcing domestic substitution in government-funded procurement.
Electronics sector procurement dominates current volumes; medical device applications are gaining share fastest as surgical laser platforms displace legacy quartz in harmonic generation stages.
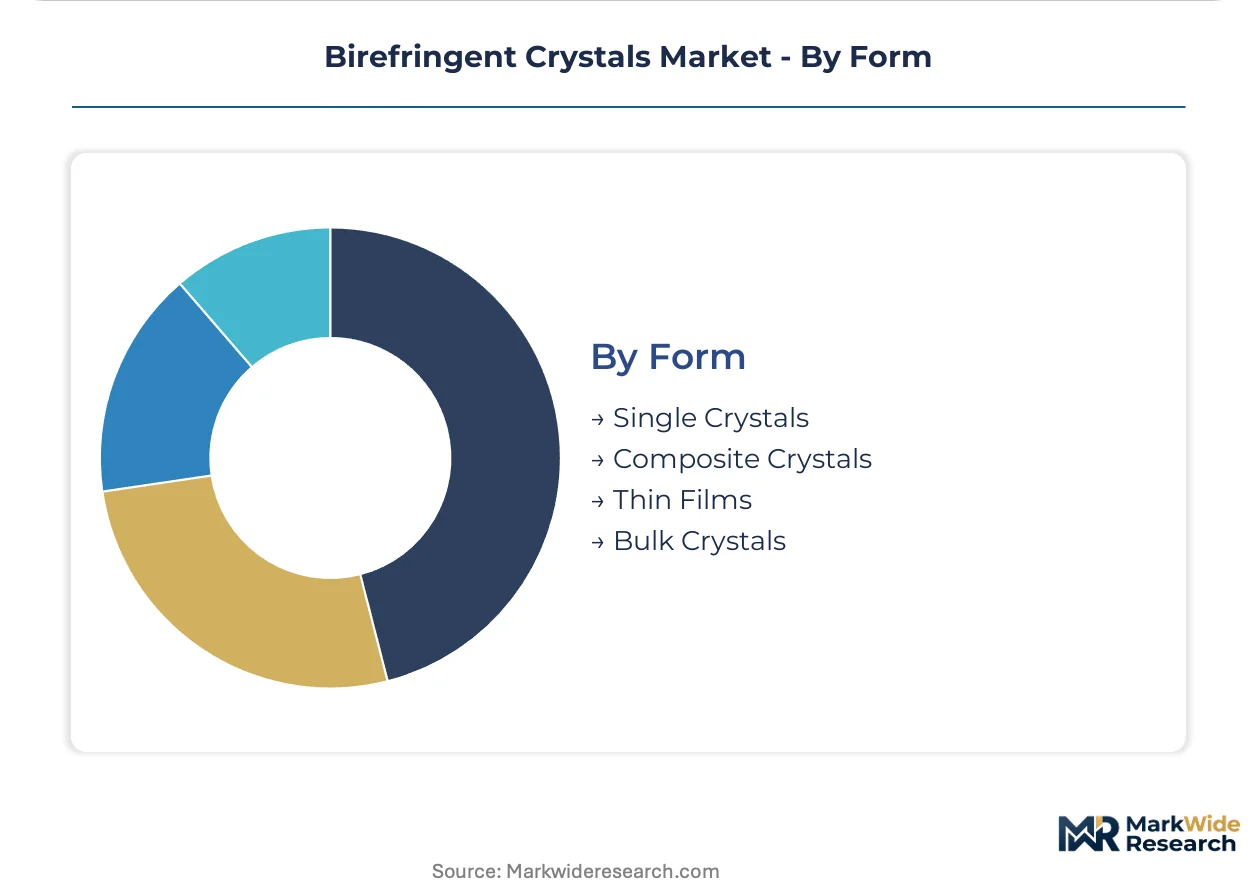
Form:
Manufacturing process selection determines achievable dimensional precision and optical surface quality, with thin-film processing enabling wafer-scale economies unavailable to bulk crystal polishers.
- Single Crystals:Monolithic calcite and yttrium orthovanadate boules yield discrete optical elements through oriented sawing and polishing to λ/10 or λ/20 surface figures.
- Composite Crystals:Bonded assemblies combine multiple crystal orientations for achromatic or temperature-compensated polarization control in precision instrumentation.
- Thin Films:Substrate thinning below 100 micrometers and lithium niobate-on-insulator processing enable silicon photonics integration for coherent transceiver modulators.
- Bulk Crystals:Centimeter-scale unprocessed boules serve scientific instrument builders and custom optical shops with in-house fabrication capability.
Single crystals retain the largest installed fabrication capacity; thin films are on the steepest expansion trajectory as wafer foundries capture polarization functions from specialized crystal houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-designated optical communication industrial parks in Suzhou and Shenzhen concentrate birefringent crystal polishing and coating capacity through tax incentives and subsidized utility rates.
China
Coherent 400G/800G transceiver deployment drives synthetic yttrium orthovanadate consumption in Yangtze River Delta packaging houses. MIIT 5G optical backhaul specifications mandate sub-0.5-degree waveplate retardation accuracy. Shenzhen transceiver assemblers are vertically integrating polarization subassembly design under government-funded industrial upgrading programs.
Germany
Precision optics OEMs in Jena and Oberkochen specify calcite polarizing beam splitters for medical laser systems and machine vision platforms. REACH substance restrictions on per- and polyfluoroalkyl substances force coaters to qualify fluorine-free anti-reflection chemistries. The country's precision optics clusters are locking in regulatory-compliant coating capacity ahead of ECHA candidate list expansions.
Japan
Surgical laser manufacturers specify alpha-barium borate for harmonic generation in dermatological platforms regulated by PMDA. Medical device approval timelines under 21 CFR 1040.10-equivalent standards stretch 18-24 months. Osaka-based optical component vendors are consolidating waveplate and isolator sourcing into single-supplier contracts.
United States
FDA 21 CFR 1040.10 performance standards govern medical laser systems incorporating birefringent crystals for harmonic generation and polarization control. Dual-use export controls from the Commerce Department fragment equipment supply chains for high-purity synthetic crystal growth technology. Greater Boston research institutes procure custom-cut crystals for quantum optics experiments.
India
Production-linked incentives for telecom equipment manufacturing under the PLI scheme attract crystal polishers and coaters to Gujarat and Tamil Nadu operations. The country's national electronics regulator mandates domestic value-add thresholds for government-funded research procurement. Hyderabad and Bengaluru optical component vendors are consolidating discrete component spot-buying into bundled subsystem contracts.
Birefringent Crystals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the birefringent crystals supply base. The market structure fragments across three tiers: captive crystal growers with in-house polishing, independent optical component fabricators, and modular subsystem integrators. Strategic archetypes include telecom-grade volume suppliers, scientific-instrument precision specialists, and thin-film wafer-scale processors. Competitive moves center on backward integration into crystal growth capacity and geographic expansion into PLI-subsidized Indian manufacturing zones.
Among China-based fabricators, CASTECH INC. and FOCtek Photonics Inc. occupy positions within the captive-growth archetype, representing suppliers with controlled upstream material supply. Thorlabs, Inc. and Newport Corporation exemplify the diversified photonics portfolio approach, anchoring multi-product procurement relationships through broad component breadth. These named entities sit within competitive tiers defined by manufacturing depth rather than scale alone.
| Leading Market Players |
|---|
| CASTECH INC. |
| FOCtek Photonics Inc. |
| A-Star Photonics Inc. |
| Inrad Optics Inc. |
| Crystal Technology, Inc. |
| Thorlabs, Inc. |
| Newport Corporation |
| Del Mar Photonics Inc. |
| Leysop Ltd. |
| Others |
Pricing and Supply Chain Analysis
A three-tier pricing structure across premium, standard, and economy levels separates synthetic melt-grown boules from polished natural calcite and thin-film substrates, with each tier anchoring distinct supply chain configurations. Premium synthetic crystals command pricing power through captive Czochralski furnace capacity in China and Germany, while commodity calcite processors in Mexico and Iceland compete on freight-adjusted spot pricing to Asian polishers.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ISO 10110-certified waveplates held in regional distribution centers serving telecom OEMs in Suzhou and Shenzhen. Price differentiation hinges on extinction ratio certification tiers and volume scale, with 400G/800G transceiver manufacturers negotiating annual contracts while research institutes tolerate 12-week lead times for λ/20 surface figure specifications. Cost compression in natural calcite processing is intensifying because Mexican freight volatility and Icelandic labor shortages are squeezing spot-market margins. Electronics assemblers serving hyperscale data centers exhibit highest price sensitivity, whereas PMDA-regulated medical laser OEMs in Japan absorb premiums for damage-threshold documentation.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Jena, and Osaka operate hub-and-spoke patterns consolidating polished crystal shipments to transceiver assemblers and medical device manufacturers. Supply concentrates in China for synthetic yttrium orthovanadate growth, Mexico and Iceland for optical-grade calcite extraction, and Germany for precision coating and metrology equipment. Raw material dependencies encompass high-purity rare-earth oxides, optical-grade calcite rough, and fluorine-free anti-reflection coating precursors subject to ECHA candidate list restrictions. Single-source vulnerability in Czochralski furnace supply from US Commerce Department-controlled vendors fragments equipment access for non-domestic synthetic producers. Distribution runs through modular polarization subsystem integrators consolidating discrete component procurement into single-supplier contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The birefringent crystals market is consolidating around backward integration into captive crystal growth capacity, with synthetic boule production emerging as the decisive margin-control lever separating tier-one suppliers from polished-component job shops.
For Market Incumbents: To counter thin-film lithium niobate-on-insulator displacement from wafer foundries, CASTECH INC. and Thorlabs, Inc. should deepen in-house production of melt-grown yttrium orthovanadate while locking multi-year offtake agreements with rare-earth oxide refiners. Certification investment in REACH-compliant fluorine-free coating chemistries ahead of ECHA candidate list expansions will defend positioning in German precision optics clusters. For New Entrants and Emerging Players: Direct-to-transceiver-assembler digital channels bypassing Shenzhen optical subassembly distributors offer the most penetrable route for thin-film substrate specialists targeting 800G coherent DSP platforms. India's PLI-subsidized Gujarat and Tamil Nadu operations present white-space manufacturing capacity for polishers serving domestic telecom equipment procurement mandates. For Investors and Strategic Acquirers: Re-rating potential sits with synthetic crystal growth specialists possessing qualified Czochralski furnace capacity given China's MIIT 5G backhaul deployment timelines and coherent transmission infrastructure pull. Long-term viability over a 5-10 year window favors targets with backward integration into rare-earth oxide supply and established ISO 10110 surface quality certification pipelines. The signal to watch is qualification timeline compression for sub-100-micrometer substrates in silicon photonics integration programs.| Strategic Initiative | Industry Significance |
|---|---|
| Czochralski Furnace Capacity Expansion | Captive synthetic boule production locks margin pools as natural calcite supply tightens. |
| Fluorine-Free Coating Chemistry Qualification | REACH-compliant anti-reflection capacity secures positioning in German precision optics clusters. |
| Thin-Film Substrate Thinning Below 100 Micrometers | Wafer-scale processing captures silicon photonics integration contracts from discrete crystal houses. |
| India PLI Manufacturing Zone Establishment | Subsidized Gujarat and Tamil Nadu operations access domestic telecom procurement mandates. |
| Modular Polarization Subsystem Bundling | Single-supplier contracts displace discrete component spot-buying in Shenzhen transceiver assembly. |
Research Methodology
Trade databases, SEC filings from listed photonics conglomerates, and ECHA regulatory disclosure records formed the secondary backbone, cross-referenced with primary interviews involving crystal growth engineers, telecom transceiver procurement managers, and precision optics coating specialists. Bottom-up unit economics from synthetic furnace capacity installations and top-down market sizing from coherent optical transmission deployment forecasts were triangulated to validate volume estimates.
Historical trendline analysis of telecommunications infrastructure capex cycles and medical laser platform approval timelines under PMDA and FDA 21 CFR 1040.10 informed projection assumptions across the analysis window. Segmentation dimensions encompassed crystal type (natural, synthetic, thin-film), application (telecommunications, medical, research), and form factor (bulk, composite, substrate-thinned). CAGRs were derived from elasticity modeling against 400G/800G transceiver shipment trajectories and high-power laser power scaling curves in material processing.
Inputs from customs trade data and MIIT procurement disclosure records were available through the study window; gaps in private furnace capacity utilization rates introduce uncertainty bands around synthetic crystal supply forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Silica Sand Market
Glass
Global Laminated Glass Market
Glass
Low Iron Glass Market
Glass
Foam Glass Market
Glass
Antibacterial Glass Market
Glass
Antiglare Glass Market
Glass
Impact Resistant Glass Market
Glass
Cellular Glass Market
Glass
Glass Grade Dolomite Market
Glass
East Africa Flat Glass Market
Glass
Glass Forming Machine Market
Glass
Double Glazing Glass Market
Glass
UAE Silica Sand Market
Glass
Decorative Glass Market
Glass
Global Glassware Market
Glass
Global Self-Cleaning Glass Market