
 Foam Glass Granulate Market | 2026-2036
Foam Glass Granulate Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Glass Granulate Market Analysis
The gap between premium high-temperature foam glass and commodity lightweight grades is expanding as industrial buyers demand certified thermal performance for energy retrofits. Owens Corning leverages its mineral wool distribution network to cross-sell foam glass granulate into commercial roofing systems. Glapor Werk Mitterteich GmbH anchors its position through captive recycling of post-consumer glass in Bavaria. Misapor AG competes on volume in European civil engineering fill applications where cost-per-cubic-meter governs procurement.
Foam glass granulate consists of crushed, sintered glass particles with closed-cell porosity achieving bulk densities of 100–200 kg/m³ and thermal conductivity below 0.08 W/mK, engineered primarily for thermal insulation and lightweight structural fill. High-temperature foam glass commands margin pools in industrial kiln lining and petrochemical vessel applications where service temperatures exceed 400°C. Standard foam glass dominates construction volume in European wall cavity insulation, while custom foam glass variants sustain pricing power in acoustic engineering for rail and automotive OEMs.
Germany's Federal Institute for Materials Research (BAM) certifies foam glass for building applications under harmonized European standards, while the EU Green Deal renovation wave mandates step-change improvements in building envelope performance. China's GB standards for green building materials and the Ministry of Ecology and Environment's dual carbon goals are redirecting specification authority toward low-embodied-carbon insulation. Stakeholders must monitor how national building codes recalibrate thermal resistance requirements and whether recycled-content thresholds become mandatory procurement criteria.
Market Dynamics
EU Green Deal renovation mandates and China's dual carbon goals are compressing specification cycles for thermal insulation materials, forcing producers to recalibrate formulations for lower embodied carbon while maintaining certified thermal performance thresholds.
Growth Catalysts
- EU Green Deal building efficiency mandates:The renovation wave directive tightens building envelope standards across Germany, France, and Italy, mandating step-change improvements in thermal resistance that favor certified foam glass granulate over conventional fill materials.
- Industrial kiln lining retrofits:Petrochemical and ceramics manufacturers in the United States and China are specifying high-temperature foam glass for vessel insulation as service temperature requirements exceed 400°C in process equipment.
- Post-consumer glass recycling infrastructure:Bavaria's captive glass recycling networks and similar regional clusters in the Czech Republic and Poland are securing feedstock supply for sintered foam glass production at scale.
Market Restraints
- Soda ash and flux mineral price volatility:Energy-intensive raw material processing in Ukraine and Turkey creates input cost instability that compresses margin pools for standard-grade foam glass granulate producers.
- German REACH chemical safety compliance:Registration requirements for modified silicate binders and foaming agents add regulatory friction and extend product certification timelines by 12-18 months for new formulations.
- Expanded polystyrene substitution in civil engineering:Cost-per-cubic-meter procurement criteria in European road base and landfill capping applications favor cheaper synthetic lightweight fills despite inferior thermal performance.
Strategic Opportunities
- India's green building material certification expansion:The Bureau of Indian Standards and state-level urban development authorities are drafting thermal insulation standards for commercial construction that create first-mover positioning for certified foam glass imports.
- Rail and automotive acoustic engineering:Custom density foam glass variants are penetrating OEM specifications for underbody insulation and trackbed vibration damping where fire resistance ratings exceed polymer foam capabilities.
- Direct-to-contractor digital procurement platforms:Specialized construction material marketplaces in Germany and the Netherlands are disintermediating traditional distributor networks for renovation-grade insulation products.
Industry Challenges
- BAM harmonized European standard certification timelines:Third-party thermal conductivity and compressive strength testing for new foam glass formulations requires 8-14 months, delaying market entry for reformulated products.
- Sintering furnace capex intensity:Continuous rotary kiln installation for commercial-scale foam glass production demands 15-25 million euro capital commitments that constrain mid-cap expansion plans.
- Cross-border waste glass feedstock traceability:Post-consumer glass sourcing documentation for recycled-content claims requires blockchain-enabled chain-of-custody systems that few producers have operationalized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Glass Granulate Market |
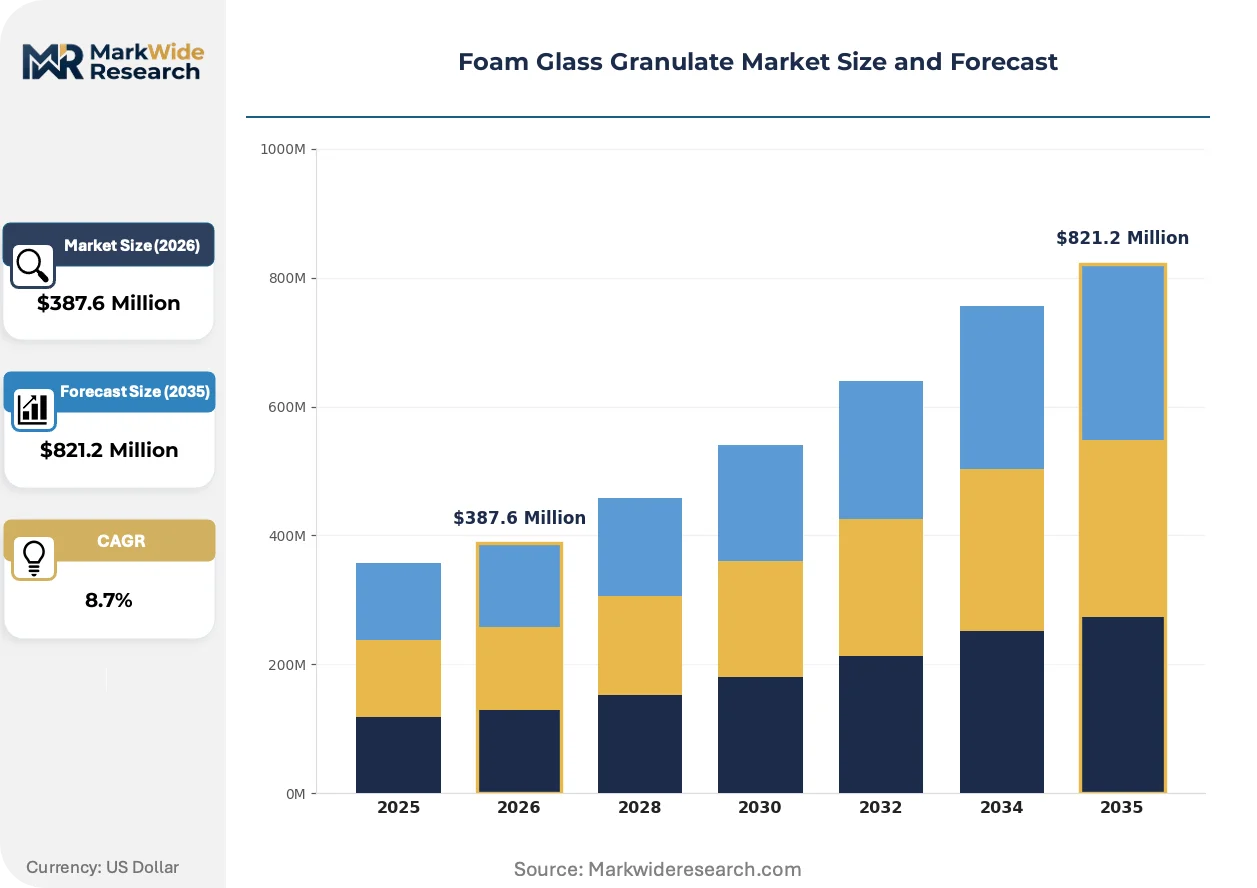
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Foam Glass, Lightweight Foam Glass, High-Temperature Foam Glass, Custom Foam Glass End Use Industry: Construction, Automotive, Packaging, Furniture Application: Insulation, Fill Material, Lightweight Aggregate, Soundproofing Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Owens Corning, Glapor Werk Mitterteich GmbH, Misapor AG, AeroAggregates of North America, LLC, Dennert Poraver GmbH, Zhejiang Zhenshen Insulation Technology Corp., Uusioaines Oy, REFAGLASS, Veriso GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Glass Granulate Market Emerging Trajectories
Active reformulation of binder chemistries and foaming processes is compressing the performance gap between virgin and recycled-content foam glass, while digital specification tools are accelerating material selection cycles in commercial construction procurement.
Closed-cell porosity control technology is integrating machine-vision feedback loops into sintering line operations. Industrial insulation contractors in Germany and the United States are adopting these quality-assured grades for petrochemical vessel applications where thermal drift voids warranty coverage. The technology is integrating real-time density monitoring that reduces batch rejection rates and compresses premium-grade pricing premiums.
China's Ministry of Ecology and Environment dual carbon implementation rules are tightening embodied carbon disclosure requirements for green building material procurement. Project developers in Shanghai and Shenzhen must now submit cradle-to-gate carbon footprints for insulation materials, favoring foam glass granulate with verified post-consumer recycled content. Municipal construction authorities are responding by fast-tracking approval pathways for materials exceeding 70% recycled glass thresholds.
Specification authority is migrating from general contractors to envelope engineering consultants who control thermal modeling software inputs. These consultants in France, Belgium, and Austria are unbundling insulation selection from broader subcontractor packages and demanding manufacturer-direct technical support. The shift is most visible in deep energy retrofit tenders where whole-building simulation accuracy determines material eligibility.
Foam Glass Granulate Market Segmentation
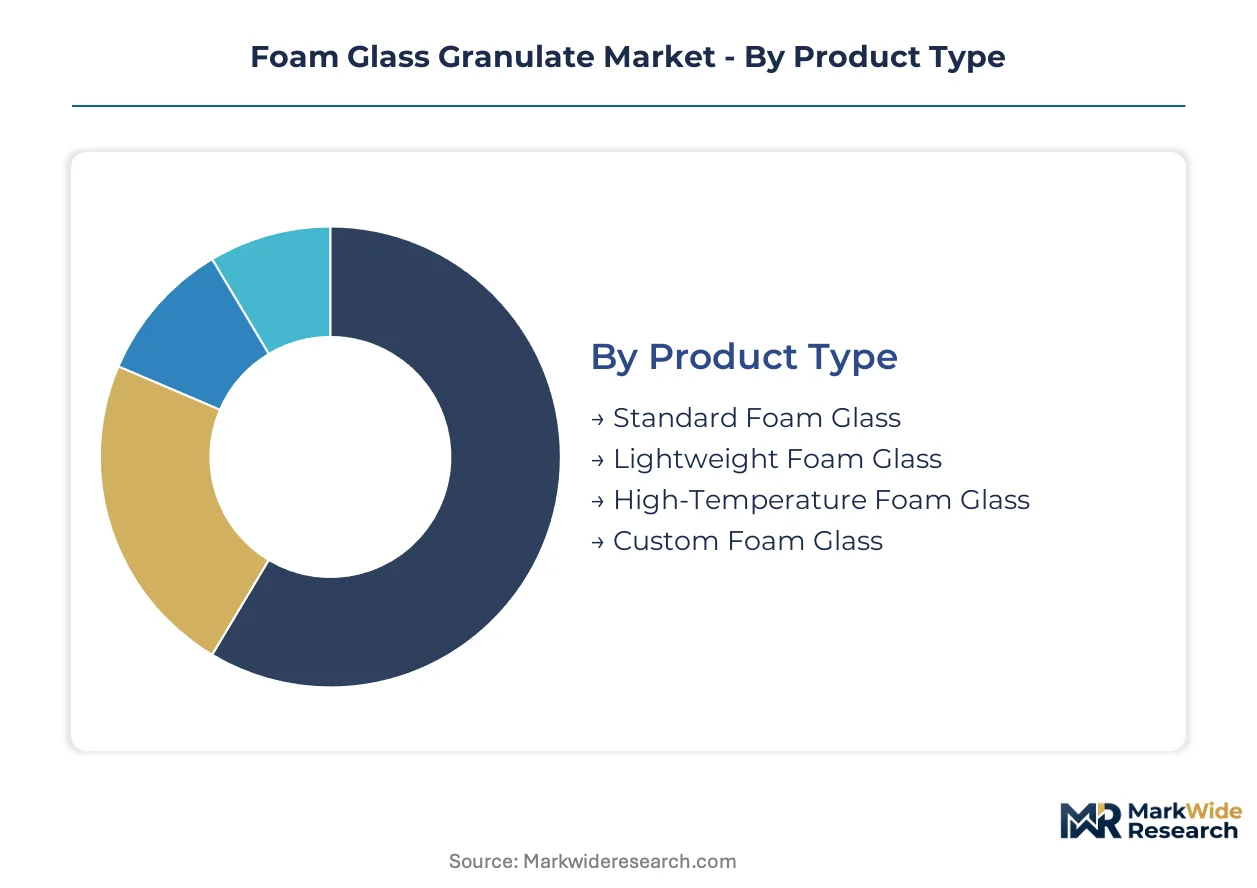
Foam glass granulate producers configure product portfolios around thermal performance certification tiers and feedstock processing intensity. Segmentation discipline separates premium-grade kiln investments from commodity fill operations with divergent margin structures.
Product Type:
High-temperature and custom formulations demand continuous rotary kiln installations exceeding 15 million euro, while standard grades operate on batch sintering equipment with lower capital barriers.
- High-Temperature Foam Glass:Sintered glass matrix engineered for service temperatures exceeding 400°C with closed-cell porosity maintaining structural integrity under thermal cycling. Petrochemical vessel insulation in the United States and ceramics manufacturing in Germany specify these grades where thermal drift voids warranty coverage, compressing procurement cycles to certified suppliers only.
- Standard Foam Glass:Crushed, sintered particles achieving bulk densities of 100-200 kg/m³ and thermal conductivity below 0.08 W/mK for general construction fill. European wall cavity insulation and German renovation projects concentrate volume here, though REACH compliance for modified silicate binders extends certification timelines.
- Lightweight Foam Glass:Ultra-low density variants below 100 kg/m³ for non-structural fill applications.
- Custom Foam Glass:Density-engineered grades for acoustic and fire-resistance specifications in rail and automotive OEM supply chains.
Most installed capacity flows through Standard Foam Glass. Expansion is steepest in High-Temperature Foam Glass.
End Use Industry:
Construction absorbs the majority of volume tonnage, while automotive and packaging applications command pricing premiums through specification complexity.
- Construction:Deep energy retrofits and green building certification drives demand across Germany, France, and Italy where EU Green Deal mandates tighten envelope performance. Civil engineering fill for road base and landfill capping competes on cost-per-cubic-meter with expanded polystyrene.
- Automotive:OEM underbody insulation and battery enclosure fire barriers specify custom density foam glass where polymer foams fail fire resistance ratings. Trackbed vibration damping for rail infrastructure extends this segment into acoustic engineering procurement.
- Packaging:Cold chain thermal protection for pharmaceutical distribution.
- Furniture:Lightweight core material for high-performance seating and fixture applications.
Construction dominates current throughput. Automotive is gaining share fastest on electrification-driven fire safety specifications.
Application:
Insulation applications anchor revenue stability through recurring renovation demand, while soundproofing penetrates premium industrial segments.
- Insulation:Thermal resistance certification under BAM harmonized European standards and China's GB green building material frameworks. Shanghai and Shenzhen municipal authorities fast-track approvals for formulations exceeding 70% recycled glass content under dual carbon disclosure rules.
- Soundproofing:Custom-engineered density gradients for rail trackbed and automotive NVH applications where machine-vision quality assurance reduces batch rejection rates.
- Fill Material:Lightweight structural backfill for geotechnical stabilization.
- Lightweight Aggregate:Concrete additive applications reducing structural dead load.
Insulation commands the largest dedicated production lines. Soundproofing exhibits the steepest margin expansion trajectory.
Distribution Channel:
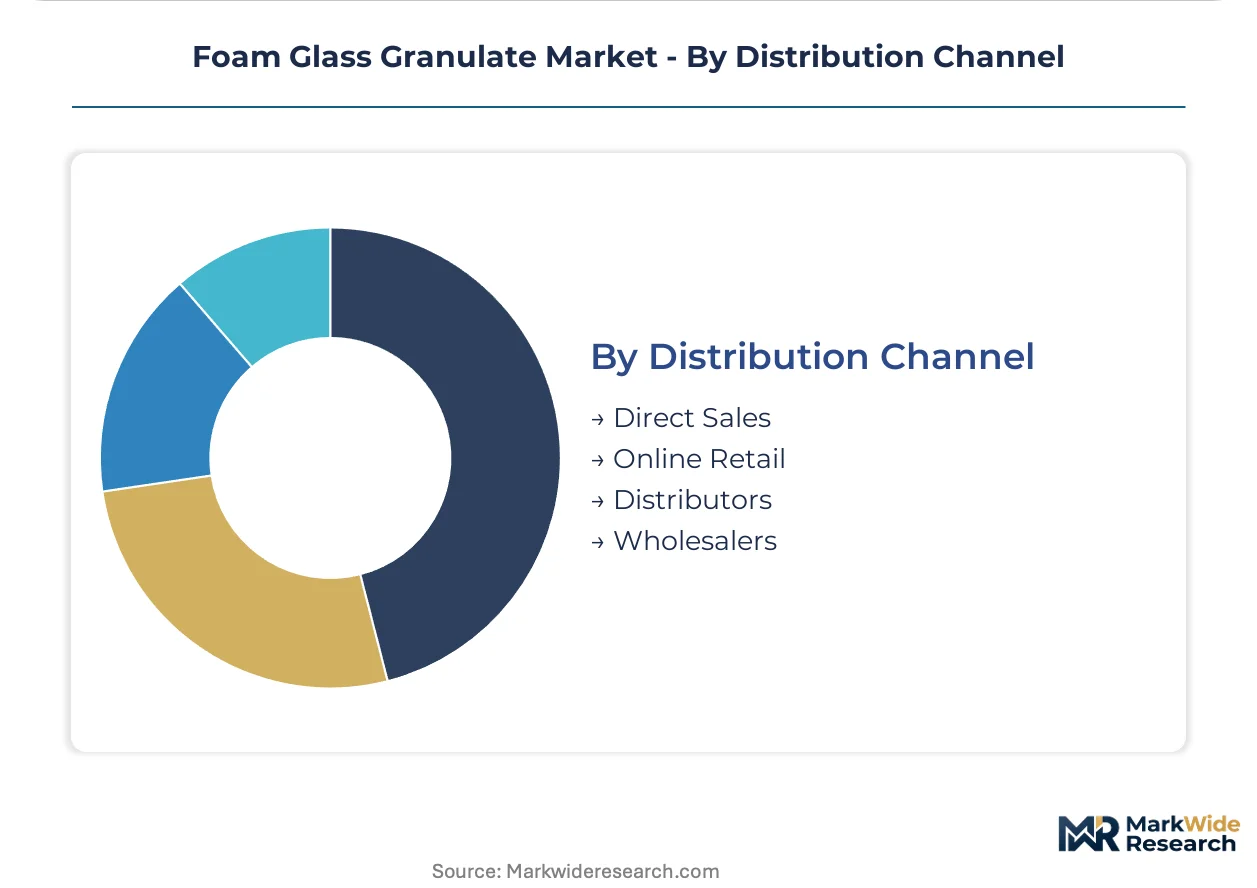
Direct sales relationships dominate premium-grade procurement, while digital platforms disintermediate standard-grade renovation materials.
- Direct Sales:Manufacturer-direct technical support for envelope engineering consultants controlling thermal modeling software inputs in France, Belgium, and Austria. Deep energy retrofit tenders require whole-building simulation accuracy that favors direct specification relationships.
- Distributors:Traditional mineral wool distribution networks cross-sell foam glass granulate into commercial roofing systems, leveraging existing contractor relationships for renovation-grade volume.
- Online Retail:Specialized construction material marketplaces in Germany and the Netherlands.
- Wholesalers:Bulk volume channels for civil engineering fill procurement.
Distributors handle the majority of standard-grade tonnage. Direct sales is climbing the fastest on consultant-led specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glass processing workforces in Bavaria and post-consumer recycling networks in the Czech Republic anchor European supply chains for sintered foam glass production.
Germany
Deep energy retrofit tenders and industrial kiln lining specifications concentrate demand in Bavaria and North Rhine-Westphalia. The Federal Institute for Materials Research certifies foam glass formulations under harmonized European standards, extending product approval timelines. Glapor Werk Mitterteich GmbH operates captive post-consumer glass recycling in Bavaria, securing feedstock for continuous rotary kiln output.
United States
Petrochemical vessel insulation and commercial roofing retrofits drive specification volume across the Gulf Coast and Northeast corridor. EPA industrial emissions frameworks and state-level building efficiency codes tighten thermal performance requirements. AeroAggregates of North America anchors production capacity in the Mid-Atlantic region, serving civil engineering fill contracts for road base stabilization.
China
Municipal green building procurement in Shanghai and Shenzhen accelerates demand for low-embodied-carbon insulation materials. The Ministry of Ecology and Environment's dual carbon disclosure rules mandate cradle-to-gate carbon footprints for construction materials. Zhejiang Zhenshen Insulation Technology Corp. exemplifies regional production scaling in the Yangtze River Delta manufacturing cluster.
India
Commercial construction expansion in Maharashtra and Gujarat creates specification opportunities for imported certified foam glass. The Bureau of Indian Standards drafts thermal insulation standards for green building certification that favor verified low-carbon materials. Mumbai and Pune development authorities pilot fast-track approval pathways for insulation exceeding recycled-content thresholds.
Czech Republic
Post-consumer glass collection networks and cross-border feedstock trade sustain sintering operations serving Central European civil engineering contracts. EU Green Deal renovation wave directives filter through national building codes, tightening envelope performance specifications. Regional clusters near the German border specialize in lightweight aggregate production for geotechnical stabilization projects.
Foam Glass Granulate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the foam glass granulate market. Continuous rotary kiln installations exceeding fifteen million euro separate premium-grade high-temperature specialists from batch-sintering commodity operators. Three archetypes dominate: vertically integrated glass recyclers with captive feedstock, mineral wool conglomerates cross-selling through distribution networks, and regional civil engineering fill specialists competing on cost-per-cubic-meter. Capacity expansion and certification-driven product reformulation represent the dominant competitive vectors as BAM and GB standard timelines extend market entry barriers.
Among European integrated producers, Glapor Werk Mitterteich GmbH and Misapor AG occupy positions at opposite ends of the value chain. Owens Corning exemplifies the conglomerate archetype, leveraging mineral wool distribution infrastructure for cross-category insulation sales. Zhejiang Zhenshen Insulation Technology Corp. represents scale-driven Asian production positioned for municipal green building procurement. These three anchors illustrate how feedstock security, distribution reach, and certification compliance separate tier-one positioning from commodity fill competition.
| Leading Market Players |
|---|
| Owens Corning |
| Glapor Werk Mitterteich GmbH |
| Misapor AG |
| AeroAggregates of North America, LLC |
| Dennert Poraver GmbH |
| Zhejiang Zhenshen Insulation Technology Corp. |
| Uusioaines Oy |
| REFAGLASS |
| Veriso GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Continuous rotary kiln technology adoption is compressing production economics for high-temperature foam glass while concentrating supply among capital-rich producers in Germany and the United States. This equipment transition simultaneously raises barriers for batch-sintering operators and shifts margin pools toward certified thermal performance tiers.
Pricing Analysis
Bundled technical support and certification documentation commands 15-25% premiums over unbundled commodity tonnage in European procurement. Three-tier pricing structure across premium, standard, and economy levels separates BAM-certified high-temperature grades from civil engineering fill. Cost compression in standard-grade foam glass is intensifying because expanded polystyrene substitution pressure in road base applications forces volume discounts. Civil engineering contractors exhibit highest price sensitivity, while petrochemical vessel specifiers prioritize thermal drift warranties over unit cost.
Supply Chain Analysis
Direct-to-contractor digital platforms in Germany and the Netherlands are disintermediating traditional distributor networks for renovation-grade insulation. Supply concentrates in Germany, China, and the United States, with Bavarian captive recycling networks and Yangtze River Delta manufacturing clusters anchoring feedstock security. Sintering operations draw from post-consumer glass, soda ash, and flux mineral inputs. Single-source vulnerability in Ukrainian and Turkish energy-intensive raw material processing creates input cost instability. Distribution runs through mineral wool conglomerate networks for cross-category insulation sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in high-temperature certification tiers as industrial buyers prioritize thermal performance warranties over unit economics. Continuous rotary kiln scale economics and recycled-content verification systems represent the primary cost-down and premium-justification levers.
For Market Incumbents: Acquire captive post-consumer glass recycling infrastructure to secure feedstock against cross-border traceability requirements. Owens Corning demonstrates cross-selling leverage through mineral wool distribution networks that incumbent foam glass specialists must replicate or partner against. Invest in machine-vision quality assurance systems to compress batch rejection rates and defend premium-grade pricing power against emerging batch-sintering competitors. For New Entrants and Emerging Players: EU Green Deal renovation mandates in Germany and France open a window for certified standard-grade foam glass imports where BAM certification timelines constrain domestic capacity expansion. Target India's Bureau of Indian Standards drafting phase for green building material certification, where first-mover positioning in thermal insulation standards creates specification lock-in. Pursue direct digital procurement platform relationships to bypass established distributor networks in renovation-grade segments. For Investors and Strategic Acquirers: Valuations sit cheapest among batch-sintering civil engineering fill specialists facing expanded polystyrene substitution pressure. Long-term viability centers on backward integration into post-consumer glass collection networks and continuous rotary kiln conversion for high-temperature grade participation. Watch for municipal recycled-content threshold mandates in Shanghai, Shenzhen, and Mumbai as inflection indicators for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Glass Collection | Bavarian captive recycling networks secure feedstock for sintering operations against traceability requirements. |
| Continuous Rotary Kiln Capacity Expansion | 15-25 million euro installations separate premium-grade high-temperature specialists from commodity competitors. |
| BAM Harmonized European Standard Certification Investment | Eighteen-month approval timelines create defensive moats for certified suppliers in German renovation tenders. |
| Direct-to-Contractor Digital Platform Partnership | German and Dutch construction marketplaces disintermediate traditional distributor networks for renovation volume. |
| Machine-Vision Quality Assurance System Deployment | Real-time density monitoring reduces batch rejection rates and compresses premium-grade pricing premiums. |
Methodological Framework
Bottom-up construction and industrial insulation modeling reconciled against top-down sintering capacity tracking forms the analytical core of this study. Primary interviews with plant managers at foam glass producers, procurement leads at petrochemical OEMs, envelope engineering consultants in France and Belgium, and distribution channel partners in Germany were validated against secondary sources including BAM certification databases, EU Green Deal directive texts, Chinese GB standards documentation, and customs trade data for post-consumer glass feedstock flows.
Input-output matrices across product type, end-use industry, application, and distribution channel dimensions generate volume and value outputs over the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling for thermal insulation materials under building efficiency mandates. Forecast inputs include EU renovation wave implementation timelines, Chinese dual carbon disclosure rule enforcement patterns, and industrial kiln lining retrofit cycles in United States petrochemical facilities.
Revisions become necessary when REACH chemical safety compliance timelines extend, recycled-content procurement thresholds become mandatory, or soda ash and flux mineral price volatility exceeds historical bands. Forecasts reflect documented assumptions regarding sintering furnace utilization rates and certification approval pathway durations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Dynamic Glazing Market
Glass
Glass Substrate Market
Glass
Ultra Violet Glass Bottles Market
Glass
Solar Control Glass Market
Glass
Impact Resistant Glass Market
Glass
Global Self-Cleaning Glass Market
Glass
Borosilicate Glass Market
Glass
Tempered Glass Market
Glass
North America Glass Insulators Market
Glass
Patterned Glass Market
Glass
Sapphire Glass Market
Glass
Glass Prepreg Market
Glass
Paper Glass Maker Market
Glass
Europe Glass Insulators Market
Glass
3D Glass Market
Glass
Recycled Glass Market