
 Global Glass Additives Market | 2026-2036
Global Glass Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Additives Market Foresight
The gap between premium functional additives and commodity colorants is broadening as automotive and electronics buyers demand precision-engineered solutions. Evonik Industries AG leverages its silane chemistry portfolio to dominate high-performance coating additives. Ferro Corporation anchors its position through specialized colorant systems for architectural glass. BASF SE differentiates via integrated dispersant technologies that reduce manufacturing variability for fabricators.
Glass additives encompass chemical modifiers introduced during melting, forming, or post-processing to alter optical, mechanical, or surface properties of silicate-based materials; typical formulations operate at processing temperatures exceeding 1400°C and include rare-earth oxides for color stability or organosilanes for adhesion promotion. Colorants and anti-fog agents command premium positioning as automotive HUD windshields and display cover glass proliferate. Dispersants and viscosity modifiers serve mature volume pools in container and flat glass, where margin compression pushes suppliers toward technical service bundling.
The EPA enforces emissions thresholds for heavy metal precursors in U.S. glass manufacturing, while REACH restricts cadmium and lead compounds across European supply chains. China's MEE implements dual carbon goals that elevate energy-efficient melting additives. Stakeholders must monitor evolving substance restrictions and carbon border adjustments to preserve formulation compliance and sourcing flexibility.
Market Dynamics
Automotive electrification is compressing development cycles for lightweight, optically precise glazing systems, forcing additive suppliers to synchronize R&D timelines with OEM platform launches rather than traditional glass production schedules.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases in manufacturing processes are accelerating demand for low-emission melting additives that maintain thermal efficiency without process gas penalties.
- Head-up display windshields:Automotive HUD penetration in premium vehicle segments is pulling specialized anti-reflective and wavelength-selective coating additives into high-volume procurement contracts.
- Rare-earth oxide clusters:Processing technology advances in China's Inner Mongolia and Jiangxi provinces are expanding feedstock availability for high-stability colorants used in architectural and automotive applications.
Market Restraints
- Lanthanum and cerium price volatility:Concentrated mining operations in China and Australia expose colorant formulators to input cost swings that compress margin predictability on long-term supply contracts.
- REACH substance restrictions:ECHA authorization requirements for cadmium and lead compounds are forcing reformulation of legacy colorant systems, extending qualification timelines by 18-24 months for European fabricators.
- Thin-film solar cell substitution:Emerging transparent conductive oxide alternatives in building-integrated photovoltaics are displacing traditional conductive glass additives in select architectural segments.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Production-linked incentives for advanced material manufacturing are creating localized formulation capacity to serve subcontinent glass fabricators previously dependent on European imports.
- Recycled cullet compatibility:Additive systems enabling higher post-consumer glass content in container and flat glass production align with brand sustainability commitments from beverage and cosmetics packagers.
- Silane-organic hybrid convergence:Crosslinking chemistry combining organofunctional silanes with UV-curable acrylics is opening post-processing surface modification applications previously inaccessible to in-melt additives.
Industry Challenges
- High-temperature process modeling:Computational fluid dynamics expertise for predicting additive behavior above 1400°C remains scarce, slowing virtual qualification of new formulations and extending physical trial requirements.
- Dual carbon compliance documentation:China's MEE enforcement of carbon intensity verification demands granular supply chain traceability that many mid-tier additive distributors cannot yet provide to downstream customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Additives Market |
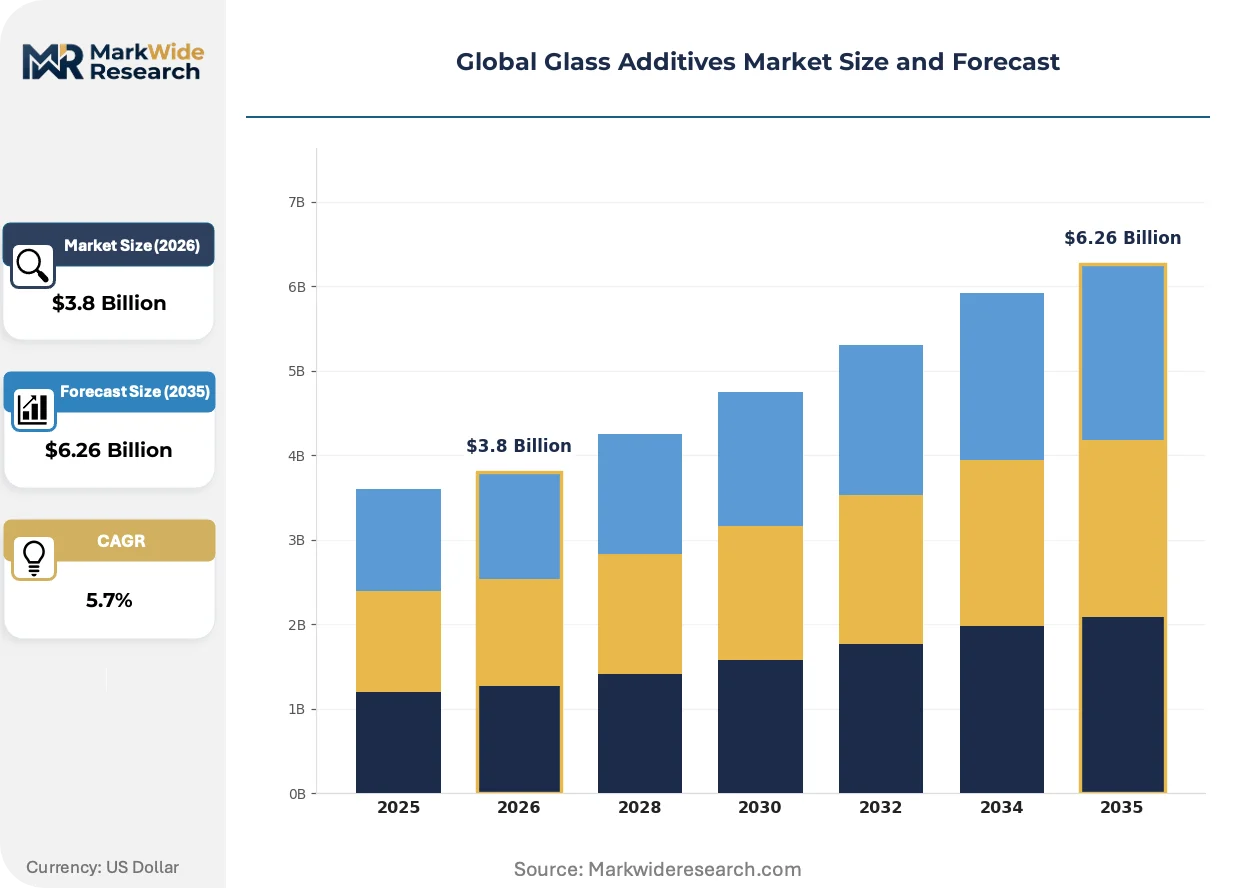
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colorants, Defoamers, Viscosity Modifiers, Dispersants, Anti-Fog Agents Application: Construction, Automotive Manufacturing, Electronics, Packaging, Optical Systems End User Industry: Chemical Producers, Coating Manufacturers, Glass Fabricators, Consumer Goods Manufacturers Form: Liquid, Powder, Granules, Emulsions, Pellets |
| Companies Covered | Evonik Industries AG, Arkema S.A., DuPont de Nemours, Inc., W.R. Grace & Co., Torrecid Group, Schott AG, BASF SE, 3M Company, Ferro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Additives Market Shifts & Advancements
Digital process control and closed-loop quality systems are displacing manual batch adjustment practices across glass manufacturing, embedding additive dosing precision into real-time production optimization rather than offline laboratory verification.
Laser-induced breakdown spectroscopy for inline chemical analysis is automating melt homogeneity monitoring, enabling container glass producers in Germany and the United States to reduce additive over-dosage by 15-20 percent while tightening color consistency specifications for brand-owner customers. This compression of process variability is reducing technical service calls and shifting supplier value propositions toward predictive analytics rather than reactive troubleshooting.
REACH authorization timelines for chromium VI compounds are forcing reformulation of green and black colorant portfolios across European architectural glass supply chains, with fabricators in Italy and Poland accelerating qualification of rare-earth alternatives ahead of 2025 sunset dates. The regulatory pressure is consolidating procurement toward suppliers with established substance registration dossiers and toxicology testing infrastructure.
Automotive tier-one suppliers are compressing additive qualification cycles by 40 percent, replacing sequential OEM approval processes with parallel validation tracks that demand pre-certified additive platforms from glass coaters. This behavioral shift concentrates purchasing authority at windshield integrators in Michigan, Stuttgart, and Shanghai, marginalizing smaller regional formulators lacking global technical support networks.
Global Glass Additives Market Segmentation
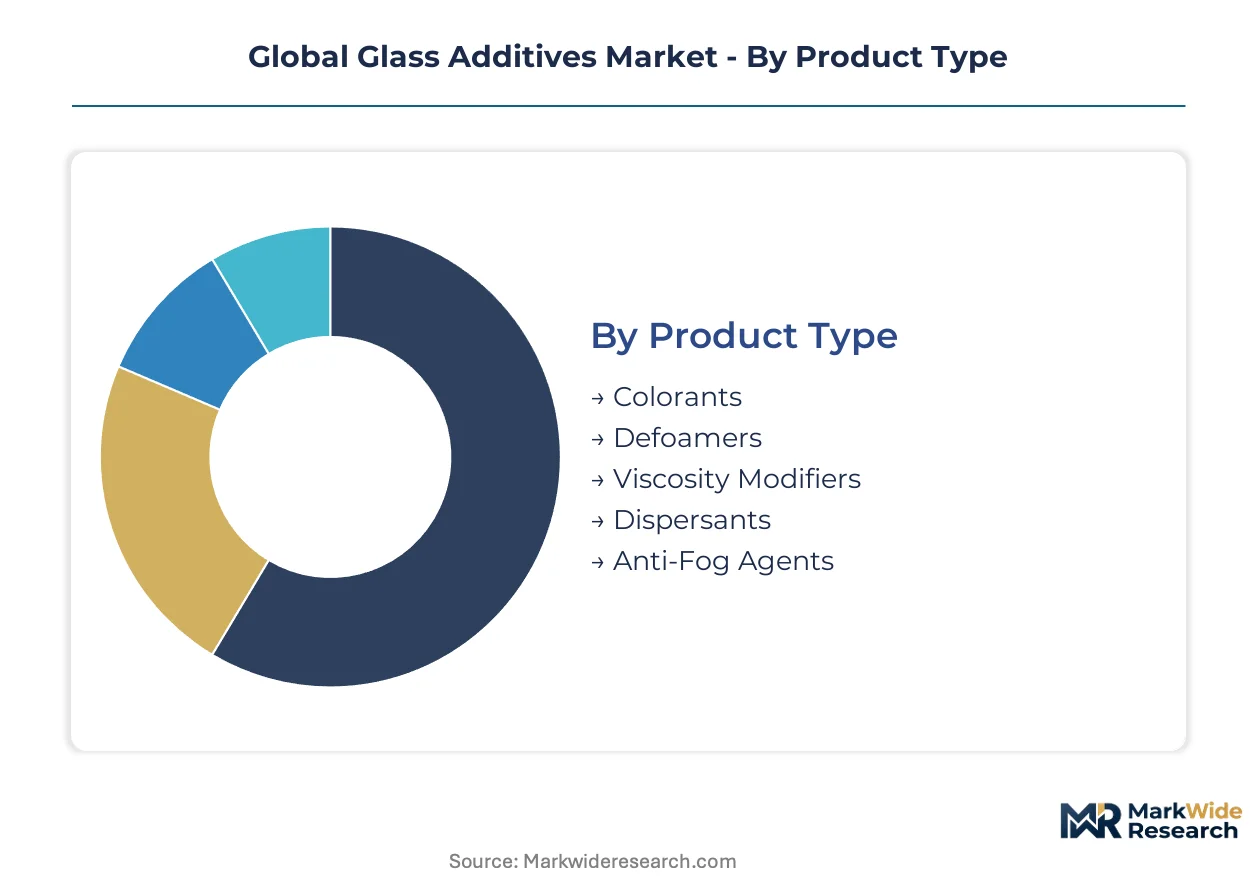
Glass additive suppliers face divergent technical requirements across product categories, forcing portfolio decisions between high-margin specialty formulations and volume-driven commodity supply. Segmentation clarity enables fabricators to match additive selection to specific melting processes, optical specifications, and regulatory constraints governing end-use applications.
Product Type:
Customization intensity varies sharply across this spectrum, with functional additives demanding precise formulation tuning while colorants compete increasingly on standard color matching protocols.
- Colorants:Rare-earth oxide and transition metal formulations deliver spectral stability across architectural and automotive glazing. Demand concentrates in Germany and China's automotive glass clusters, where OEM color consistency specifications now exceed legacy tolerances by 40 percent.
- Anti-Fog Agents:Hydrophilic surfactant systems modify surface energy to prevent condensation on display cover glass and HUD windshields. Automotive tier-one suppliers in Michigan and Stuttgart are pulling these additives into multi-year procurement contracts as HUD penetration accelerates in premium vehicle segments.
- Defoamers:Silicone and mineral oil-based systems control bubble formation during high-temperature melting operations.
- Viscosity Modifiers:Alumina and zirconia compounds adjust melt rheology for container and flat glass forming efficiency.
- Dispersants:Polymeric surfactants ensure homogeneous distribution of pigments and functional particles within glass matrices.
Leading the category by volume: Dispersants. Growing fastest: Anti-Fog Agents.
Application:
Cost tier stratification dominates, with optical systems and electronics commanding formulation premiums while construction applications drive commodity volume.
- Automotive Manufacturing:Lightweight glazing requirements and HUD integration demand precision-engineered coating additives with wavelength-selective properties. Electrification timelines in Germany, China, and the United States are compressing supplier R&D cycles to synchronize with OEM platform launches.
- Optical Systems:High-purity additives for lenses, fiber optics, and photonic devices require sub-ppm impurity thresholds. Japanese and German precision optics manufacturers anchor demand, with qualification protocols extending 24-36 months for new additive sources.
- Construction:Architectural glass colorants and solar control additives serve mature volume pools across flat glass fabrication.
- Electronics:Display cover glass and semiconductor packaging drive ultra-high purity dispersant requirements.
- Packaging:Container glass colorants and clarifying agents support beverage and cosmetics brand sustainability commitments.
Steepest expansion trajectory: Automotive Manufacturing. Largest volume anchor: Construction.
End User Industry:
Customer type fragmentation creates distinct service models, from technical partnership with glass fabricators to transactional supply for chemical producers.
- Glass Fabricators:Direct additive procurement by flat, container, and specialty glass manufacturers concentrates purchasing authority at integrated producers in China, Germany, and the United States. These stakeholders demand bundled technical service including melt modeling support and real-time dosing optimization.
- Coating Manufacturers:Post-processing additive consumers for architectural and automotive surface treatments require silane-organic hybrid systems compatible with UV-curable acrylic platforms.
- Chemical Producers:Intermediate compound suppliers feed formulated additive systems downstream.
- Consumer Goods Manufacturers:Brand owners specify container glass colorants and recycled content compatibility for packaging sustainability claims.
Highest technical service intensity: Glass Fabricators. Fastest procurement consolidation: Coating Manufacturers.
Form:
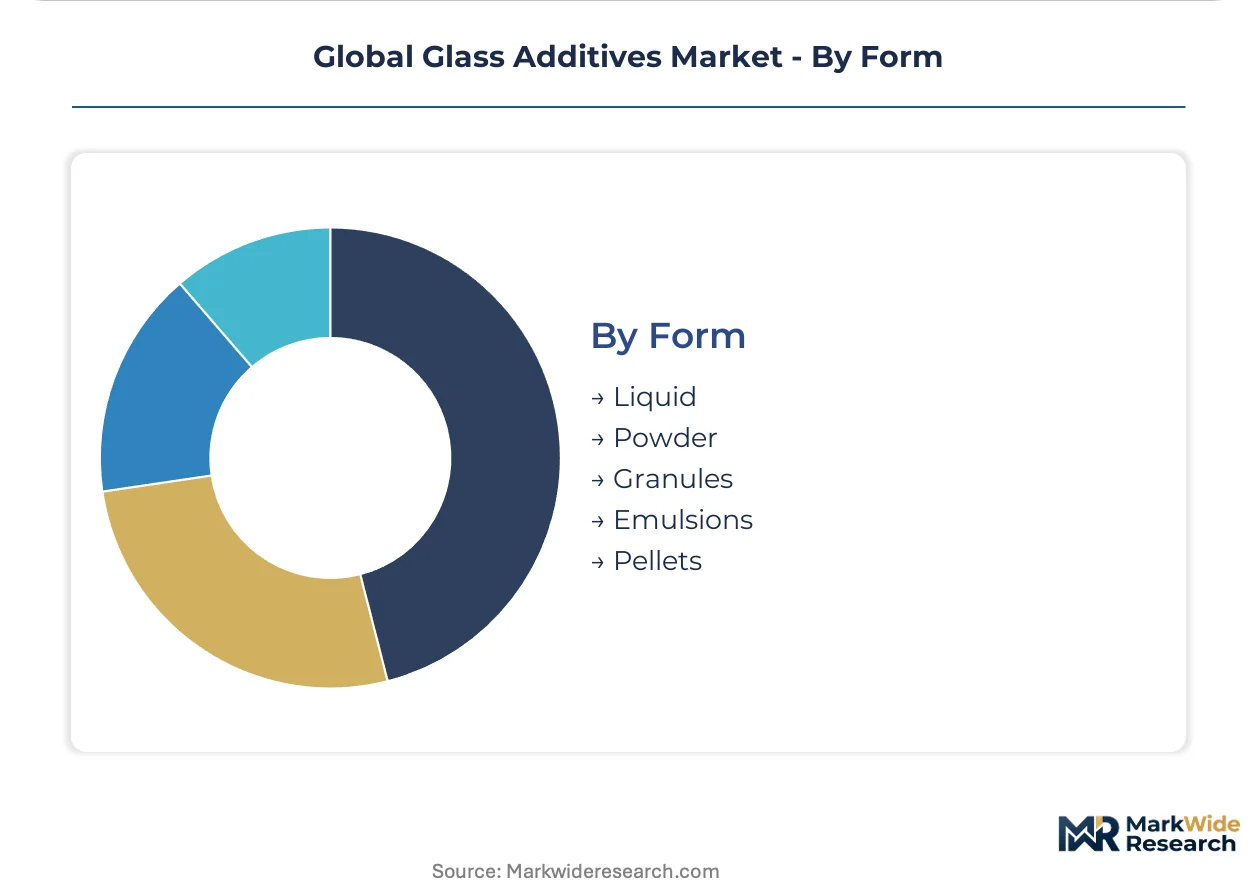
Supply concentration and margin structure vary by physical state, with liquid systems enabling precision dosing automation while powder forms retain cost advantages in bulk applications.
- Liquid:Pumpable additive systems integrate with closed-loop digital dosing controls now displacing manual batch practices across German and U.S. container glass operations. Inline homogeneity monitoring via laser-induced breakdown spectroscopy favors liquid form compatibility.
- Powder:Dry-blended colorants and mineral modifiers serve high-volume flat glass and container applications where pneumatic conveying systems predominate in Chinese and Indian fabrication clusters.
- Granules:Intermediate physical form balancing flowability with reduced dust generation during handling.
- Emulsions:Water-based or solvent carrier systems for specialized coating and surface modification applications.
- Pellets:Dust-free dosing units for automated feeding systems in continuous melting operations.
Dominant volume share: Powder. Fastest automation alignment: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors global glass additive procurement through its concentration of automotive glazing integrators and flat glass fabrication corridors serving the Yangtze River Delta manufacturing belt.
China
Inner Mongolia and Jiangxi rare-earth mining clusters feed oxide colorant production for architectural and automotive applications. The MEE enforces dual carbon goals that elevate energy-efficient melting additives across state-owned glass fabricators. Tianjin's specialty chemical port zone handles bulk silane imports for coating manufacturers serving HUD windshield producers.
Germany
Stuttgart's automotive tier-one supplier ecosystem demands precision-engineered anti-reflective coating additives synchronized with OEM electrification platforms. The EU F-Gas Regulation accelerates low-emission melting additive adoption across Bavarian container glass operations. Mainz hosts optical systems manufacturers requiring sub-ppm purity dispersants for photonic device fabrication.
United States
Michigan's windshield integration corridor pulls specialized wavelength-selective additives into multi-year procurement contracts as HUD penetration accelerates. The EPA enforces heavy metal precursor thresholds that constrain cadmium-based colorant formulations in Ohio and Pennsylvania flat glass plants. Pacific Northwest electronics manufacturers drive ultra-high purity dispersant demand for semiconductor packaging applications.
India
Gujarat's specialty chemical manufacturing zone leverages PLI scheme incentives to build localized formulation capacity for container glass colorants. BIS standards for recycled cullet compatibility push additive suppliers toward technical service bundling with fabricators in Maharashtra. Firozabad's traditional glassware cluster modernizes with automated dosing systems for cosmetic packaging exporters.
Japan
Kansai precision optics manufacturers anchor demand for high-stability rare-earth colorants with 24-36 month qualification protocols. METI industrial standards for display cover glass drive anti-fog agent specifications in Osaka-Tokyo electronics supply chains. Nagoya's automotive glazing specialists coordinate additive R&D with hybrid vehicle platform launches.
Global Glass Additives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the glass additive supply base. Integrated chemical conglomerates with captive silane and rare-earth processing capabilities dominate high-margin functional additive segments, while regional distributors compete on technical service proximity to container and flat glass fabricators. Three archetypes define competitive positioning: multinational material science platforms with melt modeling expertise, specialized colorant houses with toxicology registration infrastructure, and regional formulators bundling logistics with batch optimization support. M&A activity concentrates among coating additive portfolios, while capacity expansion focuses on India's PLI-linked manufacturing zones.
Among Germany-based material science platforms, Evonik Industries AG and BASF SE exemplify the integrated archetype combining silane chemistry with dispersant technologies. Ferro Corporation anchors the specialized colorant tier through its focus on architectural glass registration compliance. Arkema S.A. occupies a position bridging European formulation heritage with Asian manufacturing scale. These three represent distinct competitive vectors: integrated R&D platforms, regulatory-specialized colorant houses, and transregional scale operators.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Arkema S.A. |
| DuPont de Nemours, Inc. |
| W.R. Grace & Co. |
| Torrecid Group |
| Schott AG |
| BASF SE |
| 3M Company |
| Ferro Corporation |
| Others |
Supply & Pricing Matrix
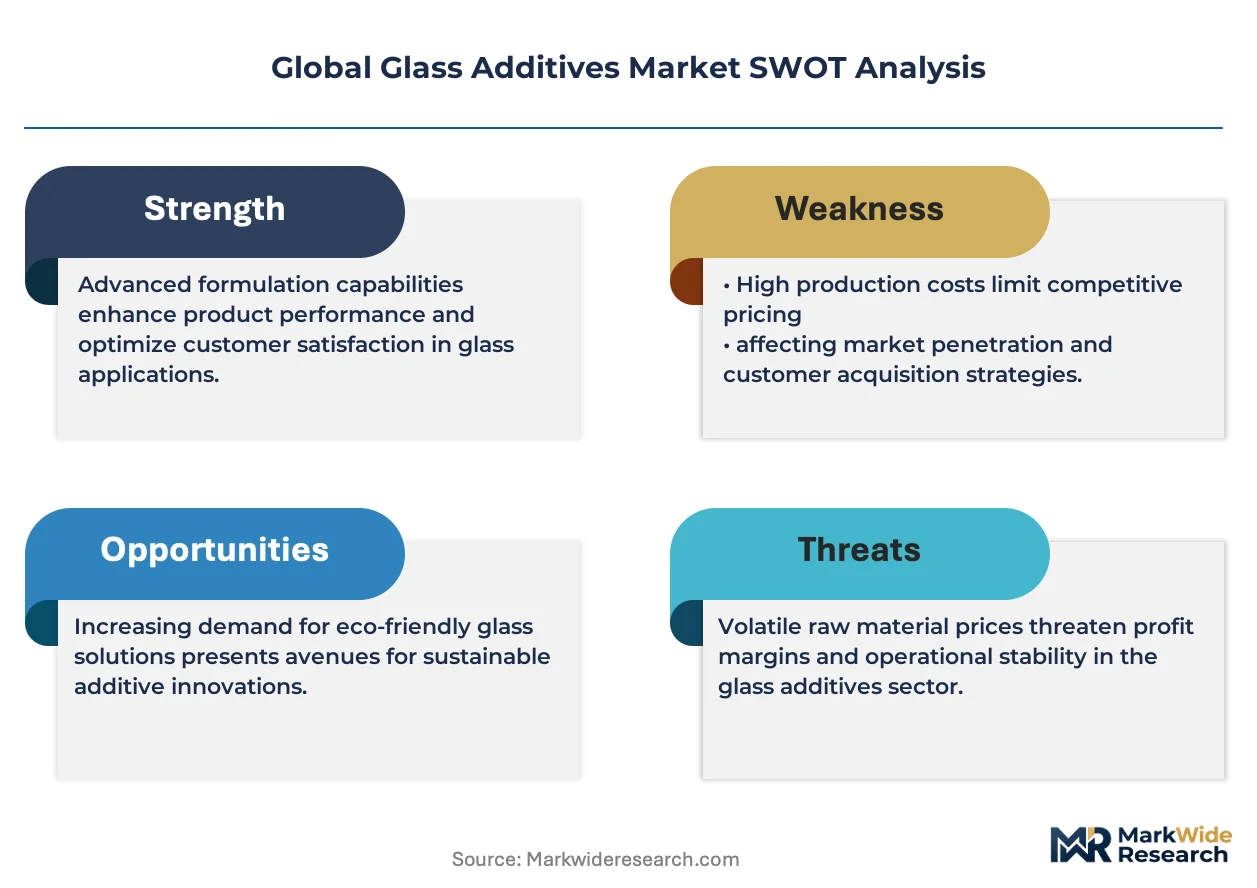
The EU F-Gas Regulation gates both qualified supply and premium-tier pricing access for glass additive manufacturers, as compliance certification becomes a non-negotiable entry ticket to European automotive and container glass procurement channels while simultaneously stratifying supplier tiers by environmental credential depth.
Pricing Analysis
Yield-based pricing anchors the functional additive segment, with coating manufacturers in Stuttgart and Michigan contracting for wavelength-selective formulations tied to HUD windshield optical throughput guarantees rather than per-kilogram rates. Price differentiation separates REACH-registered rare-earth colorants from unregistered commodity alternatives, with certification tier and volume scale as secondary drivers. Cost compression in container glass dispersants is intensifying because Chinese state-owned fabricators consolidate purchasing toward integrated suppliers. Packaging brand owners exhibit highest price sensitivity, while automotive tier-one suppliers prioritize optical precision over unit cost.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Germany's Bavarian manufacturing belt and China's Jiangxi rare-earth processing zones constrains capacity expansion for high-purity additive production. Supply concentrates in China, Germany, and the United States, with raw material dependencies on Inner Mongolia rare-earth oxides, silane precursors from Tianjin port zones, and alumina from Australian bauxite refineries. Single-source vulnerability runs through China's concentrated rare-earth mining operations. Distribution feeds from integrated chemical conglomerates through regional formulators to glass fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with upstream control over rare-earth oxide processing and downstream captive coating formulation capabilities as the decisive levers separating margin leaders from price-takers.
For Market Incumbents: To counter REACH authorization timelines forcing 18-24 month qualification delays, accelerate toxicology dossier pre-submission for rare-earth alternatives ahead of chromium VI sunset dates. Prioritize backward integration into silane chemistry to defend coating additive margins against hybrid organic-silane convergence threats. For New Entrants and Emerging Players: Capture India's PLI-linked specialty chemical zones as the most penetrable geography, where localized formulation capacity for container glass colorants remains undersupplied. Target recycled cullet compatibility systems as the fastest-qualifying application entry point, leveraging technical service bundling as the go-to-market angle against established European importers. For Investors and Strategic Acquirers: MEE dual carbon enforcement documentation demands are the leading indicator that supply chain traceability infrastructure will separate acquirable from stranded mid-tier assets. Position for 5-10 year holding periods around coating additive portfolios with established automotive HUD qualification tracks. Monitor ECHA authorization grant rates for rare-earth alternatives as the inflection signal for colorant segment consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive oxide supply secures margin stability against Chinese mining concentration volatility. |
| REACH Pre-Registration Dossier Investment | Early toxicology filing accelerates qualification ahead of chromium VI sunset deadlines. |
| Silane-Organic Hybrid R&D Partnership | Crosslinking chemistry access opens post-processing surface modification applications. |
| India PLI-Linked Manufacturing Scale-Up | Localized production serves subcontinent fabricators previously dependent on European imports. |
| Recycled Cullet Compatibility System Launch | Sustainability-aligned formulations capture beverage and cosmetics packager procurement shifts. |
Research Methodology
Document review covered trade customs data, SEC chemical sector filings, and ECHA substance registration databases, complemented by interviews with plant managers at German container glass operations, procurement leads at Michigan automotive glazing integrators, technical R&D directors at coating manufacturers, and distribution channel partners serving Chinese state-owned fabricators. Bottom-up additive consumption modeling triangulated against top-down glass production volume estimates.
Segment-level value outputs were generated across product type, application, end-user industry, and physical form dimensions over the projection horizon, with CAGRs derived from melt efficiency improvement trajectories and automotive electrification platform launch densities. Forecast inputs incorporated EU F-Gas Regulation phase-down compliance costs and MEE dual carbon verification documentation requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth oxide price volatility and REACH authorization grant delays. Forecasts reflect assumptions regarding automotive HUD penetration rates and recycled cullet processing technology maturation. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tackifier Market
Additives
Packaging Coating Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Anti-Pollution Ingredients Market
Additives
Battery Additives Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Cetane Improver Additives Market
Additives
Crystal Growth Modifier Market
Additives
Global Asphalt Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Global Butyric Acid Derivatives Market
Additives
Citric Acid Anhydrous Market
Additives
South America Concrete Admixtures Market
Additives
Foundry Additives Market
Additives
Anti-Creasing Agent Market
Additives
Printing Ink Additives Market