
 Global Flat Glass Market | 2026-2036
Global Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flat Glass Market Analysis
Automotive glazing is repositioning toward larger, lighter, and more complex curved configurations as electric vehicle architectures reshape windshield and roofline designs. AGC Inc. leverages its chemical strengthening expertise to dominate automotive OEM supply chains across Japan and Europe. Guardian Industries Holdings anchors North American float capacity while competing on coated solar glass for utility-scale photovoltaic projects. Nippon Sheet Glass Co., Ltd. specializes in thin-film conductive coatings for display and automotive sensor applications.
Flat glass consists of silica-based soda-lime sheets produced primarily through the float process, where molten glass flows across a tin bath to achieve uniform thicknesses between 0.4 mm and 25 mm with exceptional optical clarity. Its primary purpose spans transparent architectural envelopes, vehicle safety glazing, and substrate layers for solar energy conversion. Float glass sustains the largest volume share as the foundational feedstock for downstream fabrication, though coated glass commands superior margin pools through low-emissivity and solar control functionalities. Tempered glass leads automotive and structural safety applications where thermal shock resistance and fragmentation behavior determine specification.
The EPA ENERGY STAR program and California Title 24 building codes mandate minimum thermal performance thresholds that directly elevate low-emissivity coated glass penetration in new construction. ECHA REACH compliance and the EU F-Gas Regulation constrain fluorinated gas use in insulating glass unit manufacturing, reshaping equipment investment and process chemistry decisions. Stakeholders must monitor evolving carbon border adjustment mechanisms and building decarbonization mandates that will increasingly differentiate competitive position based on embodied emissions transparency and Scope 3 data availability.
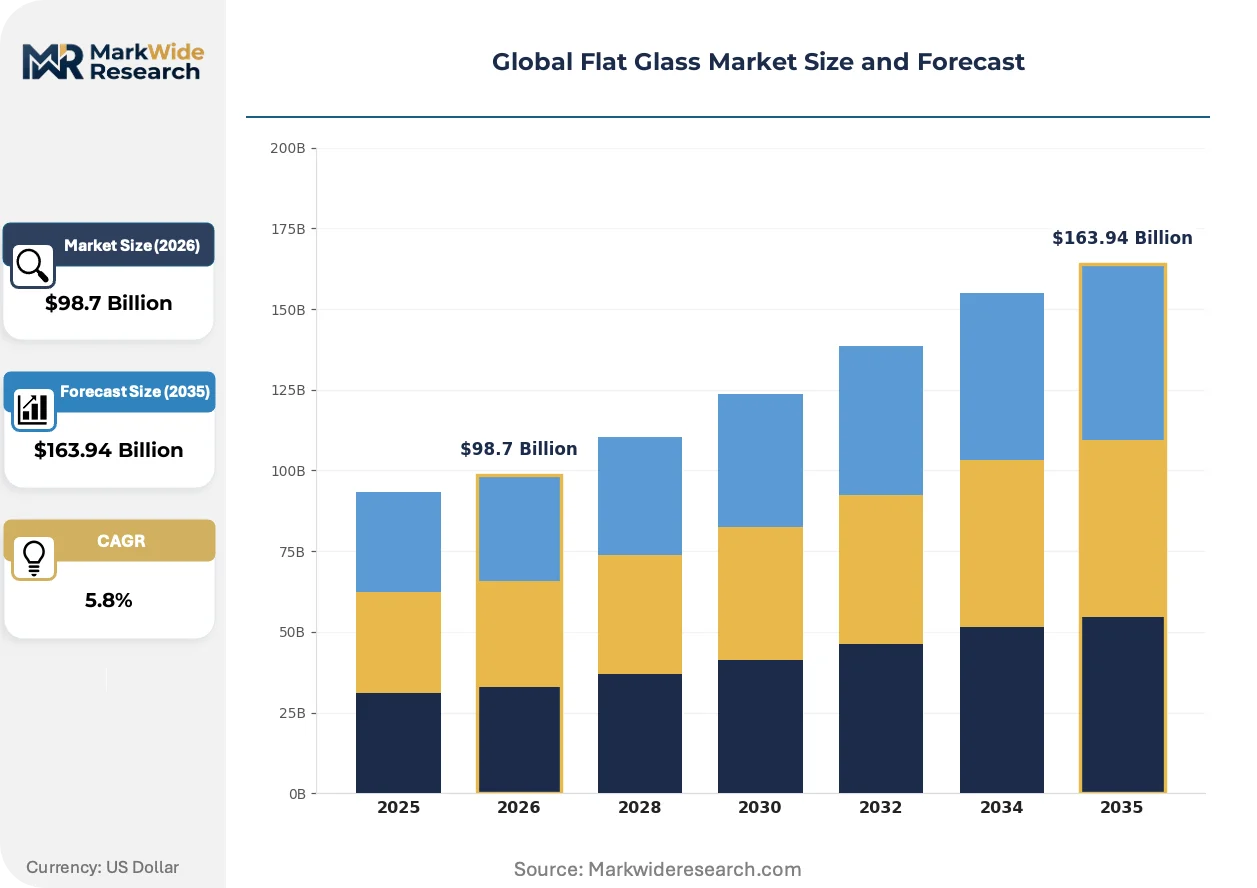
Market Dynamics
Float glass production capacity concentrates heavily in China, where state-backed capital deployment and integrated raw material access have compressed regional cost curves and redirected trade flows toward Southeast Asian and Middle Eastern construction markets.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandates near-zero energy building standards by 2030, forcing specification of triple-glazed low-emissivity units across residential and commercial new builds.
- Automotive electrification:Battery electric vehicle platforms demand larger panoramic windshields and lighter weight configurations, expanding coated glass surface area per vehicle by 40-60% versus internal combustion equivalents.
- Solar photovoltaic manufacturing:Crystalline silicon and thin-film module assembly lines in China, Vietnam, and India are consuming tempered solar glass at volumes that now rival architectural applications.
Market Restraints
- Raw material energy intensity:Soda ash and natural gas input costs constitute 35-45% of float glass production economics, exposing margins to volatility in European and North American energy markets.
- Supply concentration risk:Chinese producers control approximately 60% of global float capacity, creating geographic single-point vulnerability for automotive and solar OEMs seeking supply diversification.
- Technical thickness limitations:Ultra-thin float below 0.7 mm exhibits unacceptable optical distortion for display substrates, constraining penetration into foldable electronics applications.
Strategic Opportunities
- India construction buildout:Smart Cities Mission and PMAY-Urban housing targets create addressable demand for 8-10 million tons of architectural glass through 2030, with domestic float capacity lagging requirements.
- Building-integrated photovoltaics:Semi-transparent solar glazing merges energy generation with envelope function, opening premium specification channels in commercial facades and atrium roofing.
- Electrochromic and thermochromic coatings:Dynamic tinting technologies eliminate external shading hardware, commanding 3-4x pricing multiples against static low-emissivity products in luxury residential and aviation segments.
Industry Challenges
- Skilled furnace operations talent:Float glass manufacturing requires 15-20 year experience curves for melting and tin bath management, with generational retirement waves in European and North American facilities.
- Coating equipment capex cycles:Magnetron sputtering lines for low-emissivity and solar control films demand $50-80 million per installed unit, with 7-10 year depreciation horizons mismatching demand volatility.
- Scope 3 emissions verification:EU Carbon Border Adjustment Mechanism and CSRD reporting requirements force glass fabricators to audit upstream silica sand, soda ash, and tin suppliers for embodied carbon transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flat Glass Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Laminated Glass, Tempered Glass, Coated Glass Application: Building & Construction, Automotive, Furniture, Electronics End User: Manufacturers, Distributors, Retailers, Contractors Technology: Casting, Drawing, Blowing, Coating |
| Companies Covered | Guardian Industries Holdings, Fuyao Glass Industry Group Co., Ltd., Compagnie de Saint-Gobain S.A., CSG Holding Co., Ltd., Türkiye Şişe ve Cam Fabrikalari A.Ş., AGC Inc., Xinyi Glass Holdings Limited, Central Glass Co., Ltd., Nippon Sheet Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flat Glass Market Emerging Trajectories
Active chemistry and process control advances are compressing the performance gap between commodity float and functional coated products, while digital specification tools are rewiring how architects and contractors source complex glazing assemblies.
Thin-film photovoltaic deposition is converging with architectural glass substrates, enabling transparent power-generating facades. Commercial real estate developers in California and Germany are specifying these units for net-zero certification compliance. The technology is converging with structural glazing systems to eliminate visible framing and maximize active surface area.
The EU F-Gas Regulation phases down hydrofluorocarbon use in insulating glass unit spacer manufacturing, compelling fabricators to adopt thermoplastic warm-edge technologies or vacuum-insulated alternatives. Equipment suppliers in Germany and Italy are retrofitting existing IGU lines to accommodate silicone and polyisobutylene primary seal chemistries. Automotive OEM supply chains face parallel constraints under REACH substance restrictions for hexavalent chromium in mirror coatings.
Direct-to-fabricator digital platforms are compressing traditional distributor margins by connecting project-specified glazing contractors with certified coating and tempering facilities. Large commercial contractors in Texas, Florida, and Ontario are bypassing regional glass merchants to secure volume pricing and production slot guarantees. The shift concentrates procurement leverage among national installation networks while fragmenting local distributor economics.
Global Flat Glass Market Segmentation
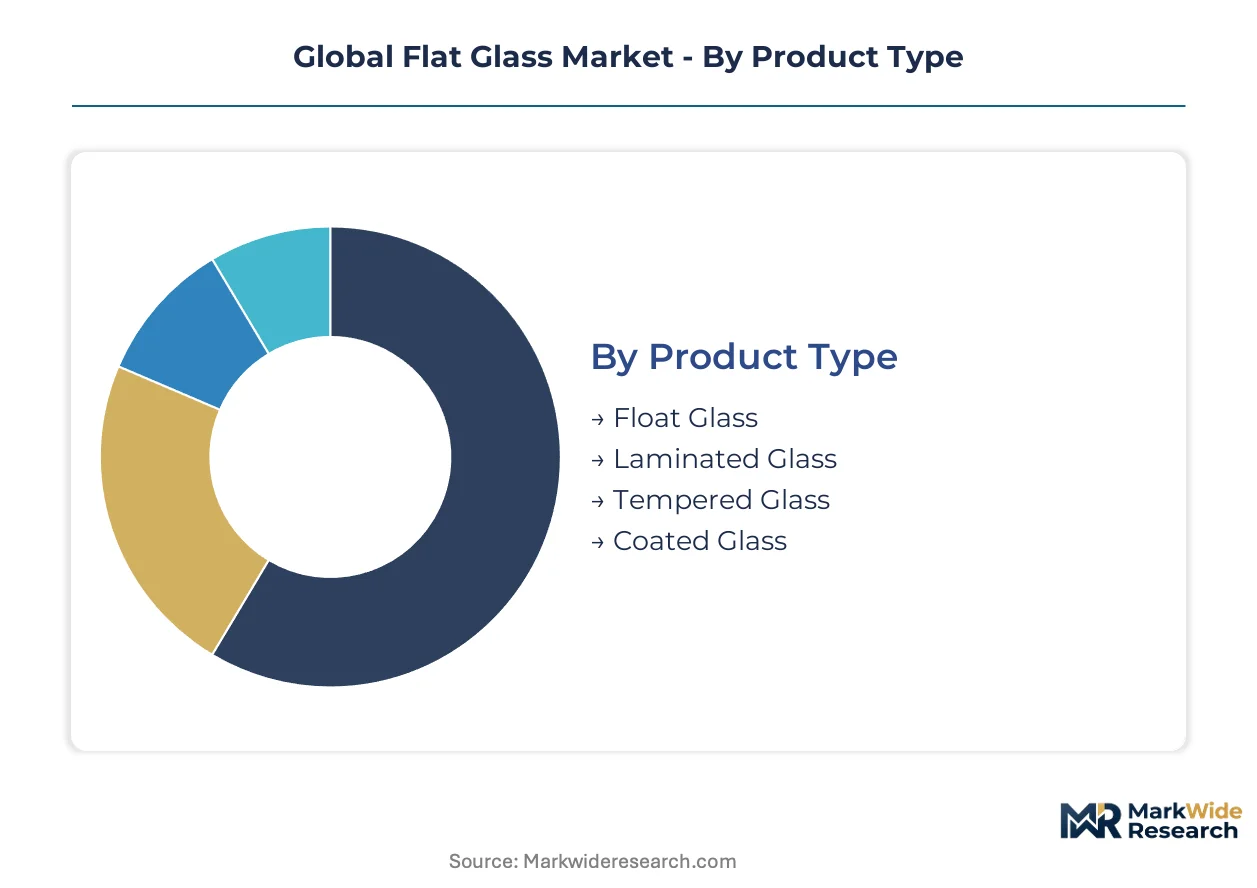
Flat glass segmentation separates commodity volume plays from value-added premium tiers. Product type and application dimensions reveal where margin pools concentrate versus where tonnage dominates procurement economics.
Product Type:
Float glass anchors volume shipments while coated variants command pricing multiples through functional performance layers.
- Float Glass:Soda-lime silica sheets produced via the tin bath process achieve thickness precision from 0.4 mm to 25 mm with exceptional optical clarity. Demand concentrates in Chinese construction markets where state-backed infrastructure deployment absorbs half of global float output for curtain wall and fenestration stock.
- Coated Glass:Magnetron-sputtered metallic and metal-oxide films deliver low-emissivity and solar control functionalities that reduce HVAC loads. European specification under the Energy Performance of Buildings Directive is forcing triple-glazed low-emissivity penetration across residential and commercial new builds.
- Tempered Glass:Thermal or chemical strengthening creates safety glazing with controlled fragmentation patterns for automotive and structural applications.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for impact resistance and acoustic dampening in hurricane zones and luxury vehicles.
Mature deployment sits with float glass as the foundational feedstock. Newer deployment is concentrated in coated glass where energy codes rewrite specification criteria.
Application:
Construction tonnage dwarfs automotive in volume, yet vehicle electrification is expanding coated surface area per unit faster than any architectural segment.
- Building & Construction:Architectural envelopes consume the majority of flat glass tonnage through curtain walls, windows, and skylights. Indian Smart Cities Mission and PMAY-Urban housing targets are generating demand for 8-10 million tons of architectural glass through 2030.
- Automotive:Battery electric vehicle platforms require panoramic windshields and lighter weight configurations that expand coated glass surface area per vehicle by 40-60% versus internal combustion equivalents. AGC Inc. leverages chemical strengthening expertise to dominate OEM supply chains across Japan and Europe.
- Furniture:Tempered and laminated variants serve tabletops, shelving, and decorative partitions where edge finish quality determines specification.
- Electronics:Ultra-thin float below 0.7 mm supplies display substrates and touch panel cover glass, though optical distortion constraints limit foldable electronics penetration.
Volume concentration rests with building and construction. Steepest expansion trajectory belongs to automotive as electrification reshapes glazing architectures.
End User:
Channel structure determines pricing transparency and technical support intensity, with contractors capturing the most complex specification decisions.
- Manufacturers:Float producers and downstream fabricators source raw glass and coating chemicals for vertical integration into value-added products.
- Distributors:Regional glass merchants hold inventory risk and provide cutting services, though digital platforms are compressing their margins by connecting contractors directly to certified coating facilities.
- Retailers:Big-box and specialty building material outlets serve residential replacement and small commercial renovation projects.
- Contractors:Large commercial glazing contractors in Texas, Florida, and Ontario are bypassing regional distributors to secure volume pricing and production slot guarantees from national installation networks.
Established relationships dominate manufacturer and distributor tiers. Emerging leverage is concentrating among contractors as procurement digitization fragments traditional channel economics.
Technology:
Process selection locks in capital intensity and product capability boundaries for decades given furnace depreciation horizons.
- Float Process:Molten glass flows across a tin bath to achieve uniform thickness with exceptional optical clarity; this method sustains the largest volume share across all applications.
- Coating:Magnetron sputtering deposits thin-film metallic and dielectric layers for low-emissivity, solar control, and conductive functionalities; equipment demands $50-80 million per installed line with 7-10 year depreciation cycles.
- Casting:Molten glass pours into molds for patterned or textured architectural products where optical perfection is secondary to aesthetic surface character.
- Drawing:Vertical or horizontal pulling produces thin sheet for specialty electronics and laboratory applications with tight thickness tolerances.
Process maturity centers on float technology. Capability expansion is migrating toward coating as functional performance layers capture margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta free-trade zones concentrate over half of global float glass capacity, while India's Special Economic Zones under the Smart Cities Mission redirect procurement flows toward domestic fabrication clusters.
China
State-backed infrastructure deployment absorbs the majority of global float output for curtain wall stock and solar panel substrates. The Ministry of Ecology and Environment enforces dual carbon goals that constrain new furnace approvals and elevate low-emissivity coating penetration. The Yangtze River Delta industrial corridor hosts integrated mega-plants supplying Southeast Asian construction markets.
United States
EPA ENERGY STAR thresholds and California Title 24 codes mandate thermal performance standards that elevate low-emissivity specification in commercial new builds. The Inflation Reduction Act channels investment tax credits toward building-integrated photovoltaic installations. The Texas Gulf Coast petrochemical corridor anchors domestic soda ash supply chains feeding float operations.
Germany
The EU Energy Performance of Buildings Directive forces triple-glazed low-emissivity penetration across residential construction by 2030. ECHA REACH compliance and the F-Gas Regulation reshape insulating glass unit chemistry and equipment investment. The Ruhr industrial basin retains specialized tempering and coating fabricators serving automotive OEM supply chains.
India
The Pradhan Mantri Awas Yojana-Urban housing targets generate demand for 8-10 million tons of architectural glass through 2030. Bureau of Indian Standards certification requirements and anti-dumping duties on Chinese imports protect domestic float capacity expansion. Gujarat's Mundra and Hazira port zones concentrate new furnace investments targeting Middle East export markets.
Japan
Automotive electrification expands coated glass surface area per vehicle as battery platforms demand panoramic windshields. METI energy efficiency standards accelerate specification of high-performance glazing in commercial retrofits. The Chubu region around Nagoya hosts chemical strengthening specialists supplying precision automotive glazing.
Global Flat Glass Market Vendor Landscape
Top-tier vendors anchor integrated float-to-coating operations, while mid-tier specialists compete on regional fabrication and tempering services. The market structures around three strategic archetypes: state-backed Chinese mega-producers with captive raw material access, Japanese and European technology leaders commanding automotive and display coating premiums, and regional fabricators leveraging proximity to construction demand. Dominant competitive moves include backward integration into soda ash and silica mining, and magnetron sputtering line expansion to capture low-emissivity specification growth.
Within the technology-leader tier, AGC Inc. and Nippon Sheet Glass Co., Ltd. exemplify precision coating and chemical strengthening capabilities, while Compagnie de Saint-Gobain S.A. occupies a position spanning integrated float production and architectural systems integration. Guardian Industries Holdings represents North American capacity concentration competing on utility-scale solar glass specification. These named entities anchor archetype patterns rather than exhaust competitive positioning.
| Leading Market Players |
|---|
| Guardian Industries Holdings |
| Fuyao Glass Industry Group Co., Ltd. |
| Compagnie de Saint-Gobain S.A. |
| CSG Holding Co., Ltd. |
| Türkiye Şişe ve Cam Fabrikalari A.Ş. |
| AGC Inc. |
| Xinyi Glass Holdings Limited |
| Central Glass Co., Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Experienced furnace operators in the Ruhr industrial basin and Chubu region command wage premiums that compress margin spreads between commodity float and value-added coated products. Labor-cost differentials between these specialized European and Japanese talent pools versus emerging-market facilities create three-tier pricing stratification across premium, standard, and economy glass grades.
Pricing Analysis
Lead-time premiums for expedited tempered solar glass deliveries to Vietnamese and Indian module assembly lines run 15-25% above contract baselines, while spot inventory of standard architectural float trades at discounts in oversupplied Chinese wholesale channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EPA ENERGY STAR and EU CE marking tiers, with low-emissivity coated products capturing sustained premiums. Pricing pressure stems from compressed float margins as Chinese state-backed capacity expansion floods Southeast Asian export markets. Residential replacement contractors in North American big-box retail channels exhibit highest price sensitivity, while automotive OEMs under long-term supply agreements demonstrate lowest elasticity.
Supply Chain Analysis
Freight cost volatility on Asia-Europe container routes and Red Sea transit disruptions have elevated landed costs for soda ash and silica sand imports to European float operations. Supply concentrates in China, Germany, and the United States, with raw material dependencies centering on Wyoming trona deposits for soda ash, Australian silica sand, and Qatari natural gas feedstocks. Single-source vulnerability from Chinese control of 60% of global float capacity exposes automotive and solar OEMs to forced allocation risk during peak demand windows. Distribution runs through regional glass merchants in mature markets, though digital platforms are fragmenting traditional channel economics by connecting large contractors directly to certified coating facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU Carbon Border Adjustment Mechanism compliance costs and CSRD reporting requirements will force smaller fabricators without Scope 3 audit capabilities toward distressed exits or acquisition.
For Market Incumbents: Lock in long-term offtake agreements with automotive OEMs electrifying their platforms to secure volume commitments before coating capacity shortages materialize. Backward integration into Wyoming trona mining or captive soda ash production hedges against energy-input volatility that threatens margin stability. Prioritize magnetron sputtering line investments in India and Southeast Asia to capture specification growth from Smart Cities Mission infrastructure deployment. For New Entrants and Emerging Players: Enter via building-integrated photovoltaics specification channels where semi-transparent solar glazing commands 3-4x pricing multiples and incumbent coating capacity remains constrained. Target Indian domestic fabrication clusters in Gujarat's Mundra and Hazira port zones where Bureau of Indian Standards certification requirements and anti-dumping duties protect nascent local capacity. Pursue joint venture structures with established float producers to access furnace operations expertise without 15-20 year talent development timelines. For Investors and Strategic Acquirers: Re-rating potential sits with specialized coating fabricators possessing EU F-Gas Regulation-compliant thermoplastic warm-edge IGU capabilities given accelerating building decarbonization mandates. Long-term viability over the projection horizon favors assets with demonstrated Scope 3 emissions transparency and verified upstream supplier audit trails. Monitor EU Carbon Border Adjustment Mechanism implementation pace as the critical inflection signal for competitive position shifts based on embodied carbon disclosure maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Sputtering Line Expansion | Captures low-emissivity specification growth under EPA ENERGY STAR and California Title 24 codes. |
| Backward Integration into Soda Ash | Secures Wyoming trona supply chains against natural gas price volatility in float production economics. |
| Joint Venture in Indian SEZs | Accesses Smart Cities Mission demand while leveraging anti-dumping duty protection against Chinese imports. |
| Thermoplastic Warm-Edge IGU Retrofit | Ensures EU F-Gas Regulation compliance for insulating glass unit manufacturing equipment. |
| Scope 3 Emissions Audit Program | Builds CSRD reporting capability and Carbon Border Adjustment Mechanism readiness for European market access. |
Methodological Framework
Multi-period observation of float furnace operating rates, low-emissivity coating penetration by building code jurisdiction, and automotive OEM glazing content per vehicle anchored the trend analysis, supplemented by interviews with plant managers at integrated float-coating facilities, procurement leads at solar module assemblers, and regulatory affairs directors navigating ECHA REACH and EPA ENERGY STAR compliance. Secondary validation drew from U.S. Energy Information Administration natural gas price data, European Commission building stock statistics, SEC 10-K filings of listed glass manufacturers, and Bureau of Indian Standards certification records. Bottom-up capacity-by-facility modeling triangulated against top-down construction and automotive production forecasts.
Input-output matrices mapped silica sand, soda ash, and natural gas input costs to float glass production economics across Chinese, European, and North American cost curves, then layered magnetron sputtering capex cycles and coating yield rates to derive value-added product margins. Segmentation dimensions included product type, application vertical, end-user channel, and technology process. CAGRs were derived from regression analysis of historical shipment data against regulatory mandate implementation schedules and OEM platform electrification roadmaps. Forecast inputs incorporated furnace retirement timelines and greenfield capacity approval rates under China's Ministry of Ecology and Environment dual carbon constraints.
Revisions become necessary when EU Carbon Border Adjustment Mechanism scope expansion, sudden furnace outage clusters, or automotive platform delays materialize beyond modeled scenarios. Forecasts reflect documented assumptions regarding energy price trajectories and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Europe Flat Glass Market
Glass
Glass Substrate Market
Glass
3D Glass Substrate Market
Glass
Glass Lined Equipment Market
Glass
Float Glass Market
Glass
Glass Grade Dolomite Market
Glass
Global Glassware Market
Glass
Antiglare Glass Market
Glass
Recycled Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
Paper Glass Maker Market
Glass
Europe Glassware Market
Glass
North America Flat Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Solar Control Glass Market