
 Global Scratch Resistant Glass Market | 2026-2036
Global Scratch Resistant Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scratch Resistant Glass Market Intelligence
Buyer concentration in the electronics sector is broadening as mid-tier smartphone and wearable brands enter the supply base alongside established flagship OEMs. Corning Incorporated leverages its proprietary fusion-draw process to sustain technology leadership in thin, damage-resistant substrates. AGC Inc. anchors Japanese automotive glazing demand through chemically tempered products engineered for head-up displays and curved instrument clusters.
Scratch resistant glass denotes silicate-based substrates engineered to withstand surface abrasion through ion-exchange strengthening, thermal tempering, or ceramic coating deposition, typically achieving Mohs hardness ratings of 6.5 to 9 depending on composition and treatment depth. These materials serve primarily to protect displays, lenses, and architectural surfaces from mechanical wear while maintaining optical clarity. Gorilla Glass and chemically treated variants occupy the dominant volume position in consumer electronics, whereas sapphire glass commands premium positioning in camera covers and luxury watch faces where extreme hardness justifies higher processing costs. Physical vapor deposition coatings are gaining traction in automotive interior applications where anti-reflective and anti-fingerprint properties add functional value beyond scratch resistance alone.
The US FDA oversees material safety in medical device displays where scratch resistant glass interfaces with sterilization protocols, while the EU REACH regulation restricts hazardous substances in chemical strengthening baths and coating formulations. China's SAMR enforces GB standards for architectural safety glass that incorporate abrasion resistance testing as a mandatory certification element. Stakeholders must monitor evolving chemical disclosure requirements across these jurisdictions, as compliance documentation is becoming a gatekeeper for OEM qualification programs and cross-border component shipments.
Market Dynamics
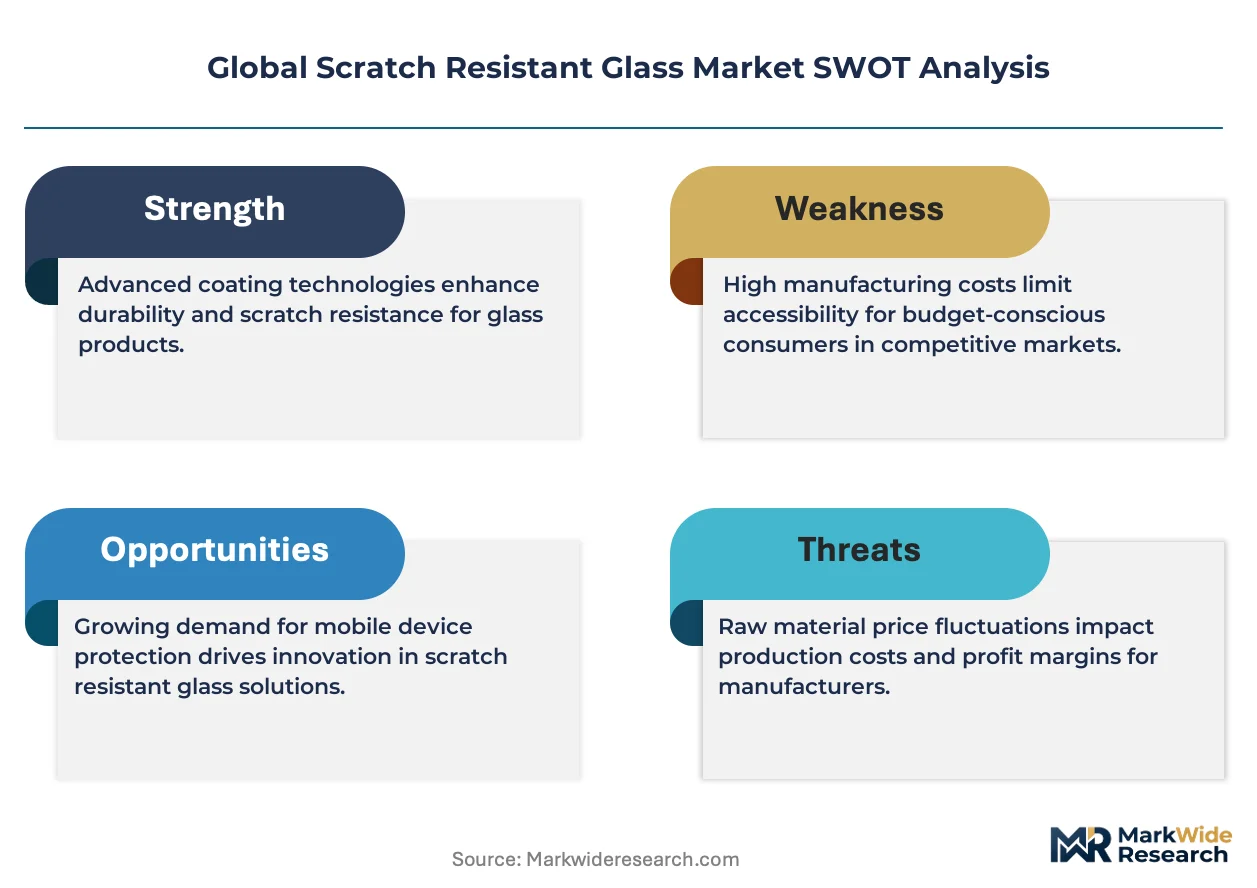
Ion-exchange chemical strengthening processes are displacing thermal tempering as the dominant hardening methodology as electronics OEMs demand thinner substrates with superior damage resistance. This technology transition is compressing equipment replacement cycles across glass processors while elevating compliance burdens for chemical bath management.
Growth Catalysts
- EU REACH chemical disclosure mandates:Manufacturers investing in compliant ion-exchange baths are securing preferred supplier status with European automotive OEMs qualifying for head-up display programs.
- Wearable device form factor evolution:Smartwatch producers are specifying chemically strengthened cover glass below 0.5mm thickness, expanding addressable substrate volume beyond smartphone applications.
- China domestic sourcing acceleration:Electronics brands headquartered in Shenzhen and Beijing are qualifying local ion-exchange processors to reduce import dependency for hardened glass components.
Market Restraints
- Potassium nitrate price volatility:The primary salt used in chemical strengthening baths fluctuates with fertilizer market cycles, compressing processor margins during agricultural demand spikes.
- Equipment supplier concentration:Fusion-draw furnace technology for ultra-thin glass remains controlled by a narrow set of Western and Japanese equipment vendors, creating capex bottlenecks for new entrants.
- Sapphire substitution in camera covers:Premium smartphone producers are specifying synthetic sapphire for lens protection where Mohs hardness above 9 justifies unit cost premiums.
Strategic Opportunities
- India electronics manufacturing incentives:The country's PLI scheme for mobile phone production is attracting cover glass processors to establish ion-exchange facilities near assembly hubs in Tamil Nadu and Uttar Pradesh.
- Automotive interior display expansion:Curved instrument clusters and passenger entertainment screens are creating specification pull for chemically tempered substrates with anti-reflective PVD coatings.
- Anti-fingerprint coating convergence:Oleophobic layer deposition is merging with scratch-resistant base glass in single-process offerings, enabling premium pricing for functionalized substrates.
Industry Challenges
- Ion-exchange process engineering talent scarcity:Deep expertise in salt bath chemistry and compression layer depth control resides with a limited cohort of specialists concentrated in legacy display glass regions.
- Multi-jurisdiction certification sequencing:Substrates for medical device displays require sequential FDA material safety validation and EU MDR conformity assessment, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scratch Resistant Glass Market |
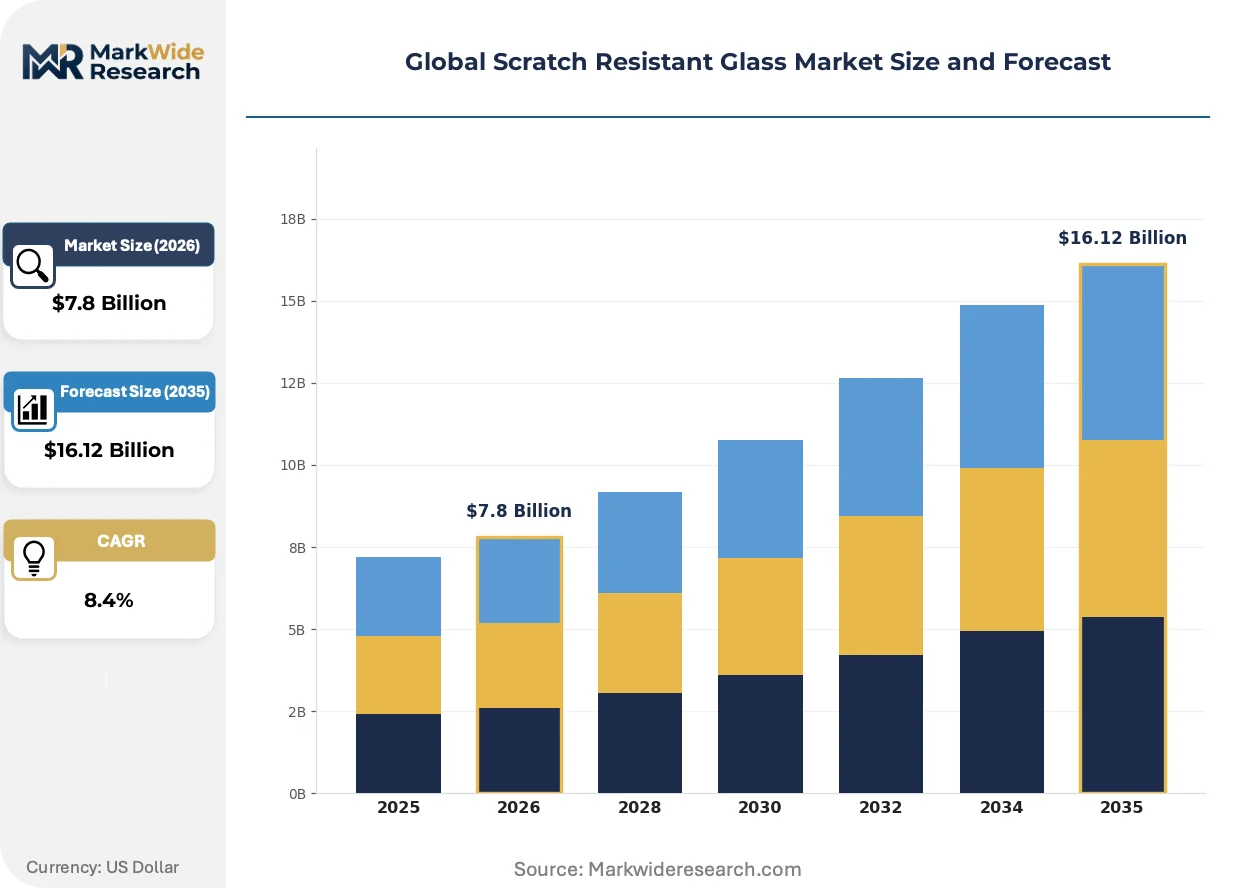
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Gorilla Glass, Sapphire Glass Application: Automotive, Electronics, Architecture, Consumer Goods End User: Manufacturers, Retailers, Consumers, Builders Technology: Chemical Treatment, Coating, Physical Vapor Deposition, Ion Exchange |
| Companies Covered | Corning Incorporated, AGC Inc., SCHOTT AG, Nippon Electric Glass Co., Ltd., Guardian Industries, Kyocera, Asahi Glass, Saint-Gobain, Monocrystal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scratch Resistant Glass Market Strategic Shifts & Innovations
Glass processors are integrating functional coatings directly into strengthening workflows, collapsing what were separate manufacturing stages. This convergence is reshaping equipment specifications and supplier qualification criteria across electronics and automotive supply chains.
Laminated glass-ceramic composites are unifying impact resistance with surface hardness in single-substrate solutions. Automotive HUD manufacturers are adopting these materials for windscreen-integrated projection surfaces where stone-chip resistance must coexist with optical precision. The technology is unifying previously separate supply chains for tempered safety glass and coated cover substrates, compressing vendor consolidation timelines.
China's SAMR is tightening GB standard enforcement for architectural safety glass abrasion resistance, mandating third-party testing documentation for imported substrates. The regulation is forcing international processors to establish domestic certification partnerships or risk exclusion from commercial building projects. Façade contractors in Shanghai and Beijing are now requiring batch-level test reports as standard procurement terms.
Electronics OEMs are consolidating cover glass suppliers from multi-source to dual-source arrangements, extending qualification periods but reducing switching frequency. This concentration pattern is most visible among mid-tier smartphone brands in Southeast Asia, where technical audit costs previously supported broader vendor rosters. Procurement teams are prioritizing processors with captive ion-exchange capacity over those outsourcing chemical strengthening.
Global Scratch Resistant Glass Market Segmentation
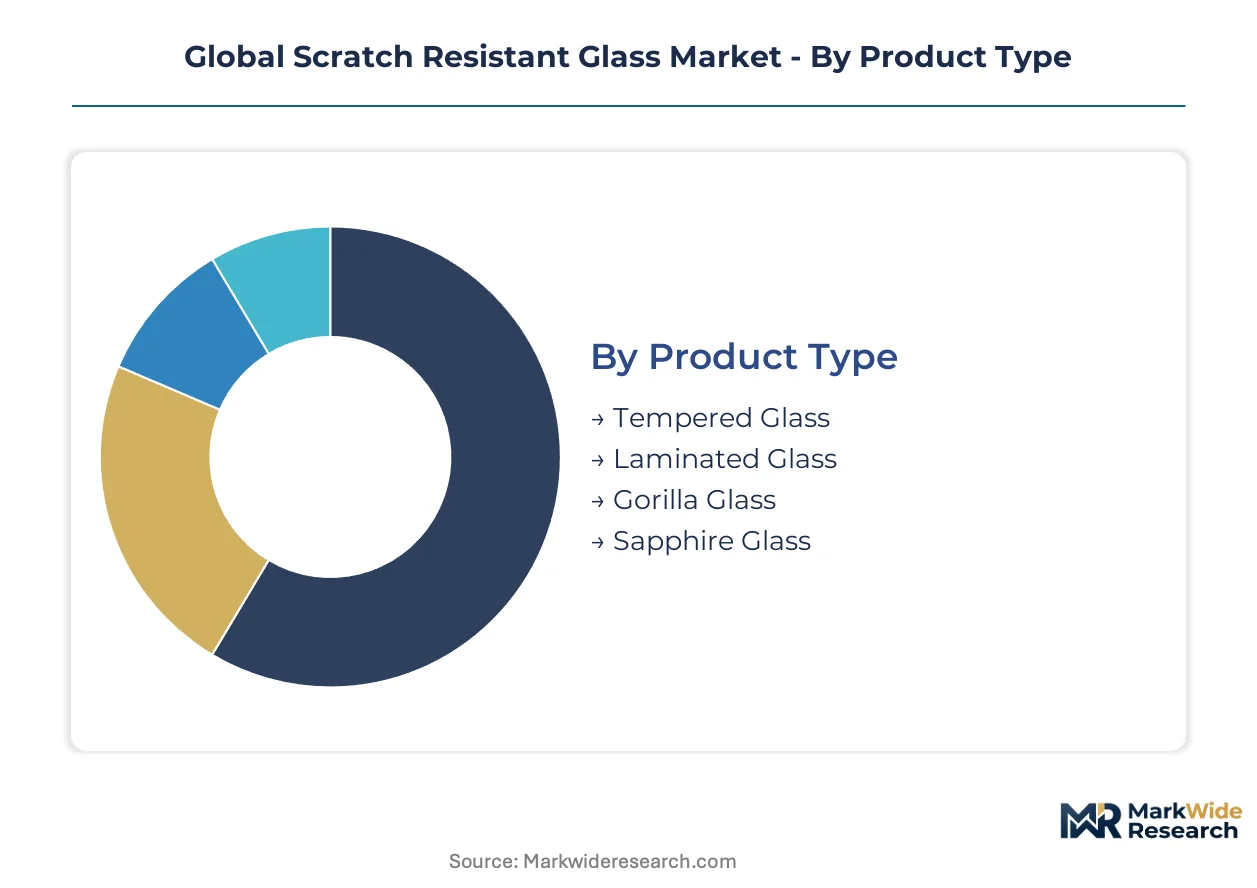
Segmentation reveals how ion-exchange capacity, coating integration workflows, and end-use certification requirements fragment supply capabilities across the scratch resistant glass value chain. Processors with captive chemical strengthening infrastructure command premium positioning in electronics and automotive qualification programs.
Product Type:
Supply concentration clusters around chemically strengthened variants, with fusion-draw capacity limiting volume leadership to processors with proprietary furnace technology.
- Gorilla Glass:Aluminosilicate compositions achieve compression layers exceeding 50 microns through ion-exchange, dominating smartphone cover glass procurement from flagship OEMs in Shenzhen and Seoul. Corning's fusion-draw process sustains technology leadership in substrates below 0.7mm thickness.
- Sapphire Glass:Single-crystal aluminum oxide delivers Mohs hardness above 9 for camera lens covers and luxury watch faces, though kyropoulos growth constraints limit wafer diameter scalability. Synthetic sapphire commands unit cost premiums where optical clarity and extreme abrasion resistance justify processing expense.
- Tempered Glass:Thermal tempering generates surface compression through rapid air quenching, serving architectural glazing and automotive side windows where thickness tolerance is less critical.
- Laminated Glass:Interlayer bonding unifies multiple glass plies for impact resistance in automotive windscreens and hurricane-rated architectural applications.
Gorilla Glass absorbs the bulk of installed capacity; sapphire glass is expanding most quickly in premium camera protection segments.
Application:
End-use qualification timelines and coating functionalization requirements differentiate margin structures across application verticals.
- Electronics:Smartphones, tablets, and wearables specify chemically strengthened cover glass with oleophobic PVD coatings, with procurement consolidating toward dual-source arrangements among Shenzhen and Beijing headquartered brands.
- Automotive:Curved instrument clusters and head-up display windscreens demand chemically tempered substrates with anti-reflective coatings, with EU REACH compliance securing preferred supplier status for European OEM programs.
- Architecture:Façade contractors in Shanghai and Beijing now require batch-level GB standard abrasion resistance documentation as standard procurement terms.
- Consumer Goods:Kitchen appliances and furniture surfaces utilize coated float glass where scratch resistance must coexist with decorative aesthetic requirements.
Electronics commands the deepest ion-exchange capacity allocation; automotive interior displays are climbing the fastest as HUD adoption accelerates.
End User:
Customer type determines specification authority and technical audit intensity across the procurement workflow.
- Manufacturers:Electronics OEMs and automotive tier-1s drive substrate specifications with captive ion-exchange requirements, extending qualification periods but reducing vendor switching frequency.
- Builders:Commercial façade contractors enforce GB standard compliance through third-party testing documentation, particularly in Shanghai and Beijing commercial building projects.
- Retailers:Aftermarket screen protection brands source laminated and tempered variants for device accessory programs with less stringent performance specifications.
- Consumers:Direct procurement concentrates in luxury watch and jewelry segments where sapphire crystal commands aesthetic and functional premiums.
Manufacturers absorb the bulk of installed capacity; builders are expanding most quickly as China's SAMR tightens architectural safety enforcement.
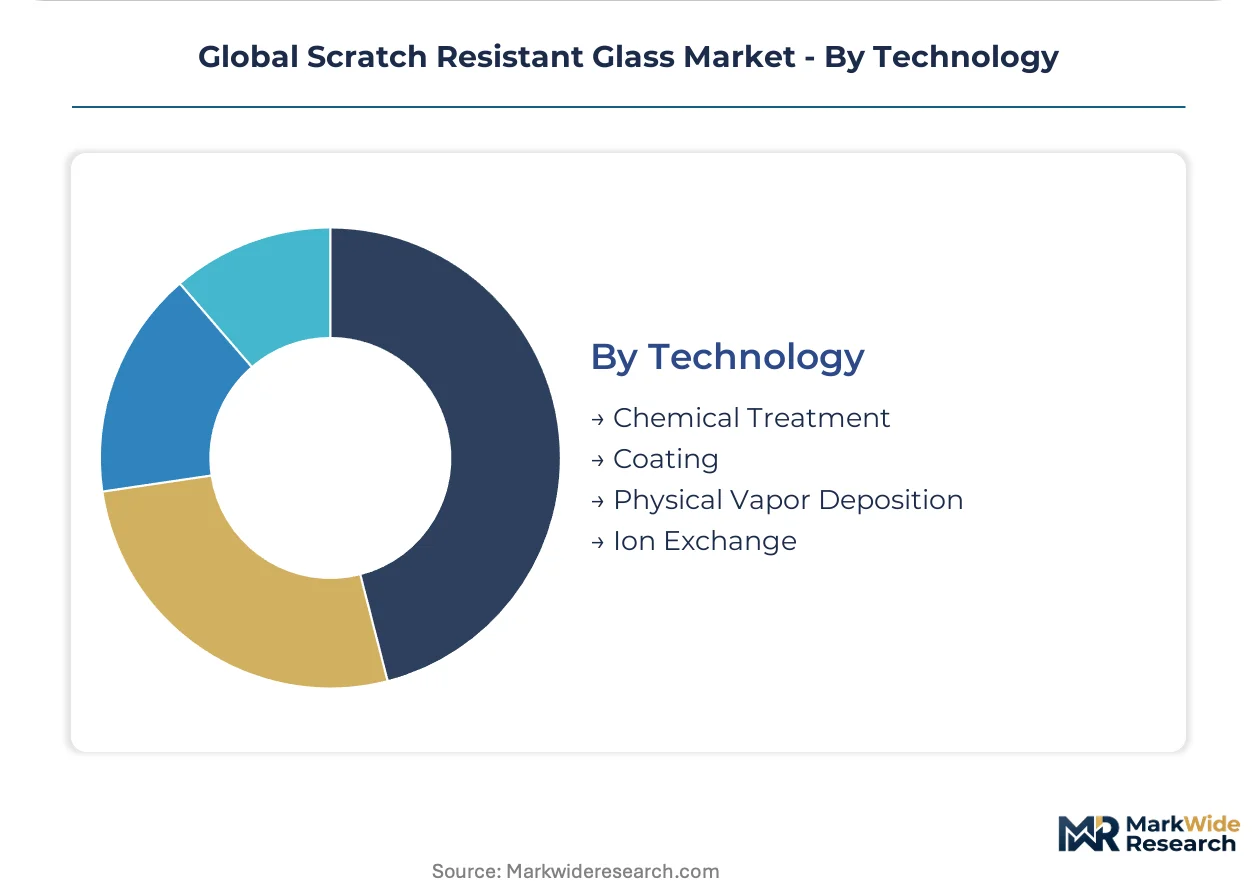
Technology:
Process selection determines capital intensity, chemical compliance burden, and substrate thickness capability.
- Ion Exchange:Potassium-for-sodium substitution generates deep compression layers in aluminosilicate glass, enabling sub-0.5mm substrates for smartwatch and foldable device applications.
- Chemical Treatment:Surface etching and sol-gel coatings provide economical scratch resistance for consumer goods and architectural applications with moderate durability requirements.
- Physical Vapor Deposition:Sputtered anti-reflective and anti-fingerprint layers add functional value to automotive and electronics substrates, with coating convergence collapsing previously separate manufacturing stages.
- Coating:Ceramic and polymer topcoats protect base glass in applications where thermal or chemical strengthening is impractical.
Ion exchange absorbs the bulk of installed capacity; physical vapor deposition is expanding most quickly as functional coating integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics OEM procurement concentrates in China, where Shenzhen and Beijing headquarters brands are qualifying local ion-exchange processors to reduce import dependency for hardened glass components.
China
Domestic electronics brands and automotive producers are scaling local sourcing of ion-exchange hardened glass substrates. SAMR enforces GB standards for architectural safety glass with mandatory abrasion resistance testing as a certification element. Façade contractors in Shanghai and Beijing now require batch-level test reports as standard procurement terms.
United States
Smartphone manufacturers are expanding procurement of chemically strengthened cover glass from domestic fusion-draw facilities. The EPA framework on manufacturing emissions is tightening material compliance requirements for chemical strengthening baths. Corning Incorporated leverages proprietary furnace technology in New York State to sustain leadership in thin, damage-resistant substrates.
Germany
European automotive OEMs are qualifying suppliers for head-up display programs with EU REACH chemical disclosure mandates. ECHA restrictions on hazardous substances in coating formulations are compressing processor qualification timelines. Stuttgart and Munich industrial clusters anchor demand for chemically tempered substrates with anti-reflective PVD coatings.
Japan
AGC Inc. anchors domestic automotive glazing demand through chemically tempered products engineered for curved instrument clusters. METI industrial policy supports advanced glass-ceramic composite development for windscreen-integrated projection surfaces. Nagoya and Osaka manufacturing corridors concentrate ion-exchange process engineering expertise.
South Korea
Seoul-headquartered electronics conglomerates are consolidating cover glass suppliers from multi-source to dual-source arrangements. MFDS medical device regulations intersect with display material safety protocols for sterilization-compatible interfaces. Gyeonggi Province assembly hubs are attracting anti-fingerprint coating convergence investments.
Global Scratch Resistant Glass Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue coating integration and automotive interior specialization. The vendor base clusters around three strategic archetypes: fusion-draw technology holders with captive ion-exchange capacity, regional processors serving domestic electronics brands, and coating specialists merging functional layers with base substrates. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate supplier relationships.
Within the technology leadership tier, Corning Incorporated exemplifies the fusion-draw archetype with proprietary furnace infrastructure. AGC Inc. and SCHOTT AG occupy positions among diversified glass conglomerates with automotive and electronics qualification depth. Nippon Electric Glass Co., Ltd. represents the regional processor model serving East Asian supply chains.
| Leading Market Players |
|---|
| Corning Incorporated |
| AGC Inc. |
| SCHOTT AG |
| Nippon Electric Glass Co., Ltd. |
| Guardian Industries |
| Kyocera |
| Asahi Glass |
| Saint-Gobain |
| Monocrystal |
| Others |
Cost & Logistics Intelligence
Ion-exchange process engineering talent concentrated in Japan's Nagoya and Osaka manufacturing corridors creates labor-cost differentials that widen pricing spreads between premium fusion-draw substrates and economy-grade chemically treated alternatives.
Pricing Analysis
High-volume Gorilla Glass procurement absorbs processor capacity at compressed margins, while sapphire wafer production for camera covers sustains premium pricing tiers. Price differentiation separates Corning's proprietary fusion-draw substrates from regional ion-exchange processors serving Shenzhen and Beijing electronics brands. Pricing pressure stems from potassium nitrate salt cost volatility tied to fertilizer market cycles. Aftermarket screen protection retailers exhibit highest price sensitivity; automotive HUD program suppliers accept premium pricing for REACH-compliant coating integration.
Supply Chain Analysis
Workforce availability for salt bath chemistry expertise concentrates in Japan, South Korea, and upstate New York, constraining new facility ramp rates. Raw material sourcing draws from potassium nitrate suppliers, aluminosilicate batch manufacturers, and PVD coating precursor specialists. Single-source vulnerability pervades fusion-draw furnace technology controlled by narrow Western and Japanese equipment vendors. Distribution runs through electronics OEM direct procurement teams, automotive tier-1 qualification programs, and architectural façade contractors enforcing batch-level GB documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive ion-exchange capacity determines qualification access to consolidated dual-source procurement programs at major electronics OEMs.
For Market Incumbents: Deepen backward integration into potassium nitrate supply arrangements to buffer fertilizer-driven cost volatility. Add captive PVD coating capacity in Gyeonggi Province to capture anti-fingerprint convergence premiums. Defend against sapphire substitution in camera covers by advancing compression layer depth beyond 50 microns in next-generation aluminosilicate formulations. For New Entrants and Emerging Players: Begin with automotive interior display specialization where EU REACH compliance creates qualification barriers incumbents navigate slowly. Target India's Tamil Nadu and Uttar Pradesh electronics manufacturing corridors where PLI incentives reduce effective facility cost bases. Pursue coating-first positioning that merges functional layers with outsourced base glass rather than replicating full fusion-draw infrastructure. For Investors and Strategic Acquirers: The window for entry favors regional processors with captive ion-exchange capacity and established automotive qualification depth. Five-to-ten year viability hinges on coating integration capabilities collapsing manufacturing stages. Watch potassium nitrate price spikes as inflection signals favoring processors with long-term salt supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ion-Exchange Capacity Expansion | Secures dual-source qualification slots with Shenzhen and Seoul electronics OEMs. |
| Anti-Fingerprint Coating Integration | Captures premium pricing from Gyeonggi Province smartwatch assembly hubs. |
| EU REACH Compliance Certification | Unlocks preferred supplier status for Stuttgart and Munich automotive HUD programs. |
| India PLI-Aligned Facility Establishment | Positions near Tamil Nadu mobile phone assembly clusters reducing logistics exposure. |
| Glass-Ceramic Composite R&D Partnership | Addresses windscreen-integrated projection specifications from Nagoya automotive design centers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with ion-exchange process engineers, automotive tier-1 procurement managers, electronics OEM supply chain directors, and architectural façade contractors validated capacity and qualification timelines. Secondary sources included SAMR GB standard documentation, ECHA REACH substance restrictions, EPA emissions framework disclosures, and SEC filings from listed glass processors. Bottom-up substrate volume estimates triangulated against top-down electronics and automotive production forecasts.
Data-stream reconciliation across production capacity databases, chemical import records, and OEM supplier qualification registries shaped the analytical framework. Segmentation modeling spanned product type, application vertical, end-user category, and process technology across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating foldable device adoption curves and HUD penetration assumptions. Forecast inputs included potassium nitrate price indices and ion-exchange equipment lead time surveys.
Underlying measurement precision varies by segment; electronics procurement data carries tighter precision than architectural safety glass estimates. Forecasts reflect assumptions regarding OEM dual-source consolidation timelines and REACH enforcement intensity. Material deviation in foldable device volume ramps or potassium nitrate supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
China Flat Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
North America and Australia Silica Market
Glass
Glass Balustrade Lamination Market
Glass
Glass Manufacturing Market
Glass
India Flat Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Glazing Gel Market
Glass
Borosilicate Glass Market
Glass
Birefringent Crystals Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Asia-Pacific Glassware Market
Glass
Asia-Pacific Silica Sand Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Global Glass Flake Coatings Market
Glass
Global Glass Tempering System Market