
 Mirrored Glass Market | 2026-2036
Mirrored Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Mirrored Glass Market Outlook
Copper-free silvering chemistry is shifting product economics across the mirrored glass supply chain, reducing corrosion risk while extending mirror longevity in humid climates. Saint-Gobain leverages captive float glass capacity across European plants to sustain margin control from raw material through finished mirror. Guardian Industries anchors North American distribution through dedicated architectural glass channels. AGC competes in Asia-Pacific with vacuum coating specialization for solar control mirror variants.
Mirrored glass denotes float glass substrates bearing thin metallic reflective layers, typically silver or aluminum deposited via vacuum coating or chemical silvering processes, achieving reflectance values exceeding 90 percent for visible light while enabling thermal insulation when paired with low-emissivity interlayers. The product serves architectural glazing, automotive rear-view systems, and decorative interior applications where optical precision and durability are specified. Flat mirrors dominate volume shipments across residential and commercial construction, while vacuum coating technology commands premium positioning in solar-integrated building facades where energy performance ratings determine specification. Aluminum coating segments expand in appliance and furniture applications where cost thresholds outweigh maximum reflectance requirements.
China's MEE enforces building energy codes that mandate high-performance glazing in new commercial construction above specified floor areas. The EU Green Deal and F-Gas Regulation constrain manufacturing inputs for certain coating chemistries, redirecting R&D toward compliant deposition processes. The US EPA and state-level California Energy Commission extend efficiency labeling requirements that influence mirrored glass specification in LEED-targeted projects. Stakeholders must monitor regulatory divergence between Asian manufacturing standards and European import compliance thresholds to align capacity investments with accessible demand pools.
Market Dynamics
Copper-free silvering chemistry is compressing traditional coating margins while extending product lifecycles, forcing producers to reconfigure deposition lines and raw material sourcing strategies across major manufacturing hubs.
Growth Catalysts
- China's MEE building energy codes:Mandates for high-performance glazing in new commercial construction above specified floor areas are pulling vacuum-coated mirror specifications into tier-one city developments.
- Solar-integrated facade demand:Architects in Germany's Rhine-Ruhr metropolitan cluster are specifying low-emissivity mirrored glass for energy-positive building envelopes under EU Green Deal efficiency targets.
- Automotive rear-view system upgrades:Electrified vehicle platforms in Japan and South Korea are integrating electrochromic mirror modules requiring precision-coated substrates.
Market Restraints
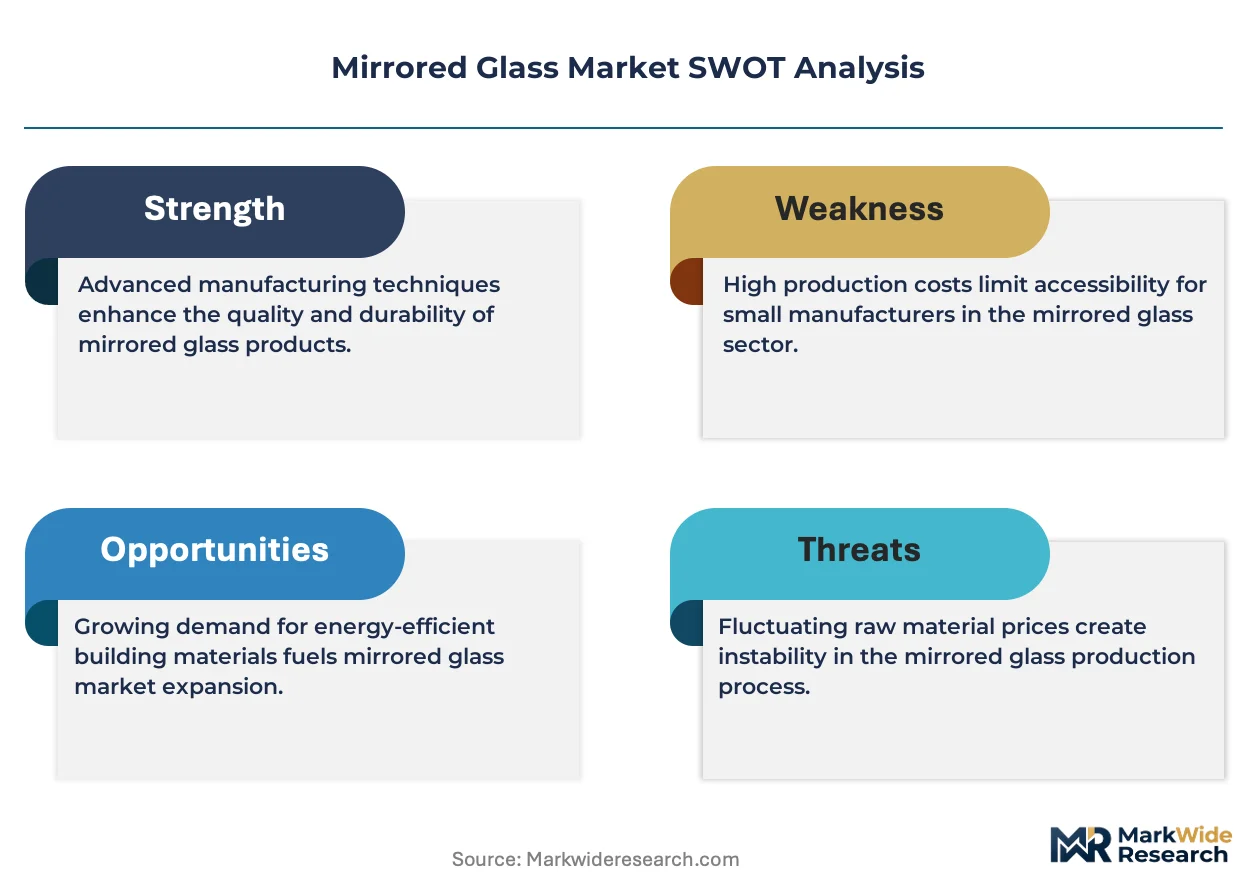
- Silver price volatility:Chemical silvering processes remain exposed to London Bullion Market Association spot price swings, compressing margin predictability for mid-tier producers.
- Float glass supply concentration:Captive flat glass capacity concentrates among three European and two Chinese producer groups, limiting substrate access for independent coaters.
- EU F-Gas Regulation constraints:Certain fluorinated deposition precursors face phase-down schedules, forcing R&D redirection toward compliant vacuum coating chemistries.
Strategic Opportunities
- India's Mumbai-Delhi corridor:Underpenetrated commercial construction markets present white space for solar control mirror variants as BIS energy-efficiency labeling expands.
- Smart mirror convergence:Integration of transparent conductive oxide layers with capacitive touch sensors is opening appliance and retail display applications beyond traditional architectural use.
- California Energy Commission Title 24:Extended efficiency labeling requirements for LEED-targeted projects are creating specification pull for high-reflectance low-e products in Western US developments.
Industry Challenges
- Vacuum coating technician scarcity:Specialized magnetron sputtering expertise concentrates among aging workforces in Japan and Germany, constraining capacity expansion timelines.
- Dual certification complexity:Manufacturers serving both EU and Chinese markets must reconcile divergent testing protocols for thermal performance and corrosion resistance, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mirrored Glass Market |
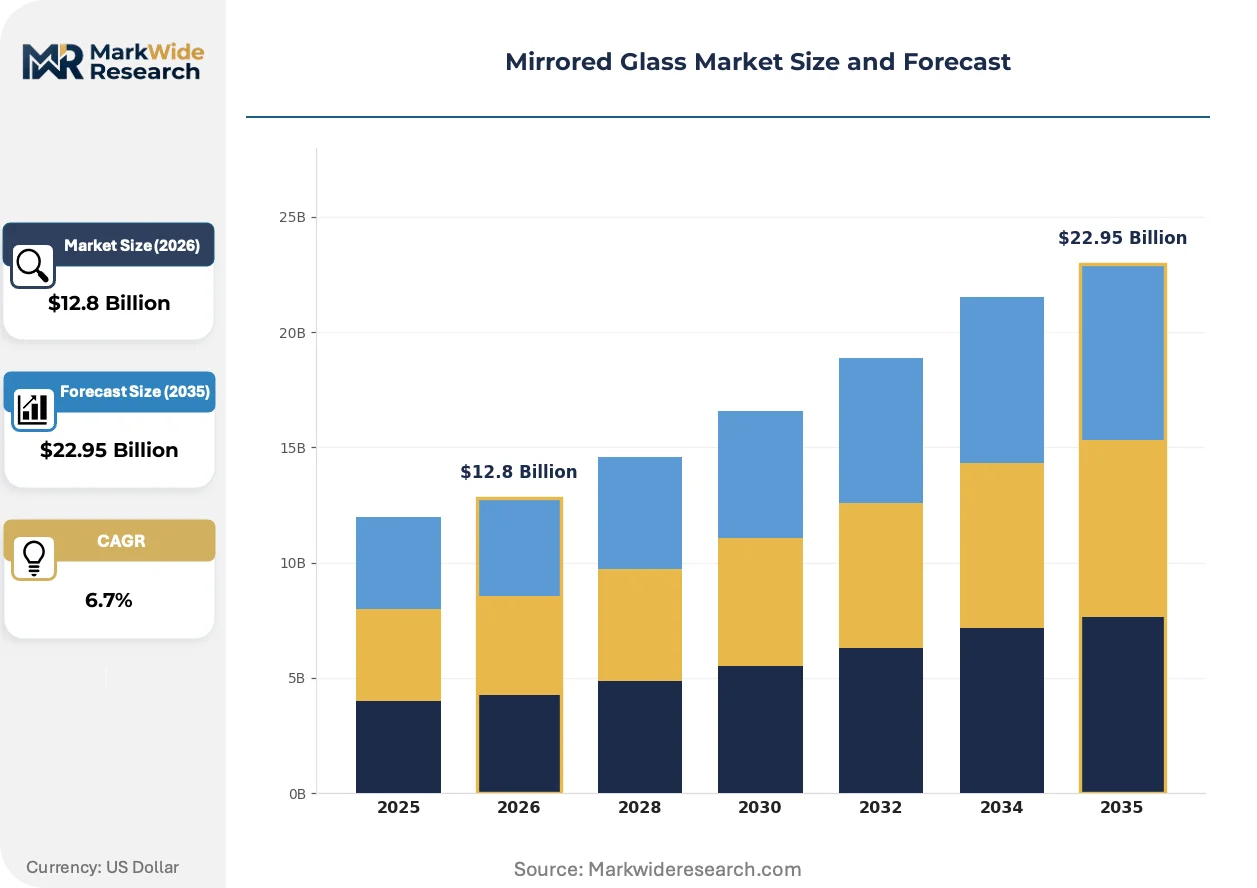
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Mirrors, Convex Mirrors, Concave Mirrors, Decorative Mirrors Application: Automotive, Architecture, Furniture, Appliances End User: Residential, Commercial, Industrial, Retail Technology: Vacuum Coating, Silvering, Aluminum Coating, Chemical Vapor Deposition |
| Companies Covered | Saint-Gobain, Guardian Industries, AGC, Pilkington, Asahi, Taiwan Glass, Sisecam, Xinyi Glass, Jin Jing Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mirrored Glass Market Strategic Shifts
Active coating deposition methods are displacing legacy wet chemistry across premium architectural segments, while regulatory chemistry constraints and buyer procurement centralization reshape competitive requirements.
Copper-free silvering technology is integrating aluminum oxide protective interlayers that eliminate edge corrosion in humid climates. High-rise developers in Singapore and Miami are specifying these variants for coastal facade applications. The shift is compressing demand for traditional copper-backed mirrors in premium specifications.
REACH and RoHS substance restrictions are tightening allowable heavy metal content in mirror backing paints. European coaters are reformulating protective layers to eliminate lead and cadmium stabilizers. Decorative furniture and appliance segments face the steepest compliance cost adjustments.
Buyer consolidation among multinational construction groups is compressing supplier rosters and extending contract durations. General contractors in China's tier-one cities are mandating multi-year volume commitments with fixed pricing clauses. Tier-two coaters without captive float glass supply face exclusion from major project bids.
Mirrored Glass Market Segmentation
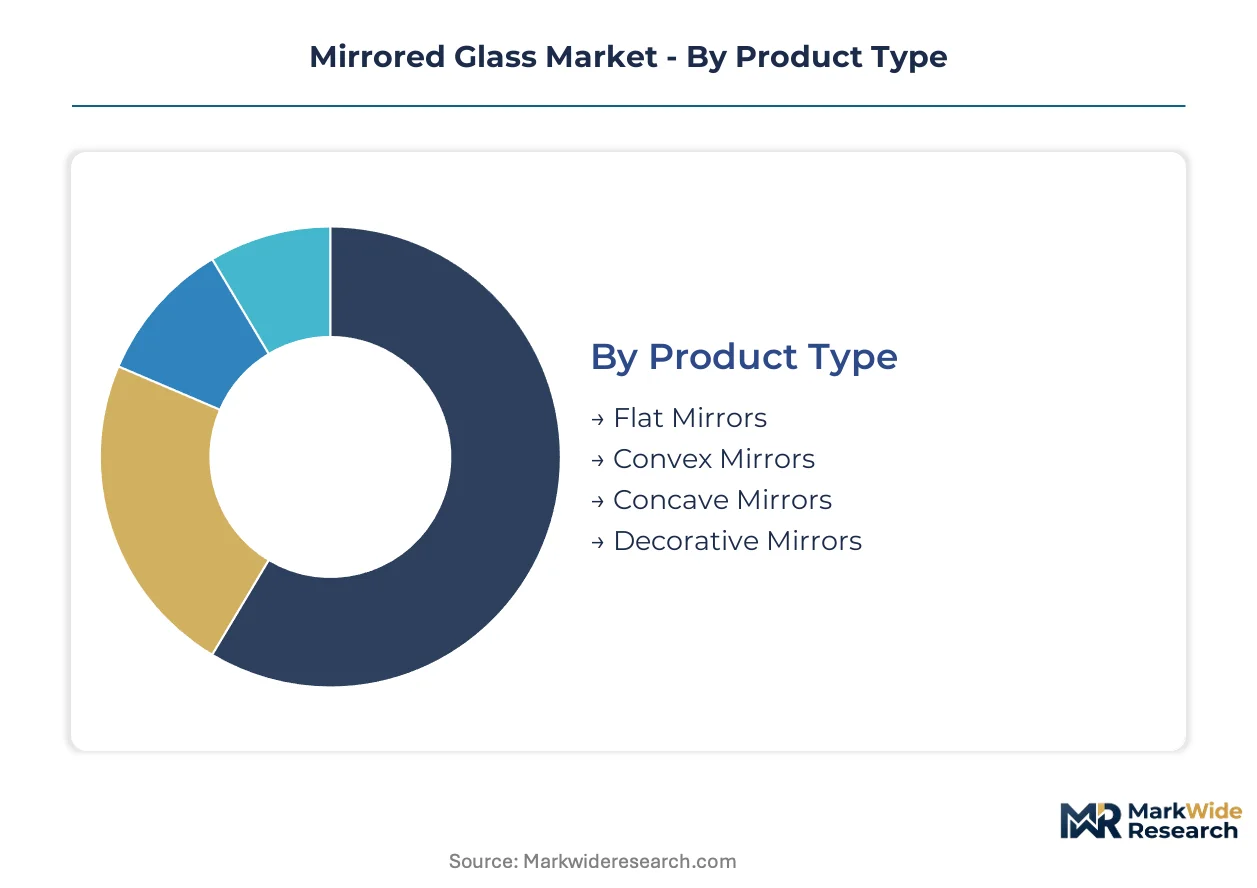
Mirrored glass segmentation tracks divergent technical specifications across architectural, automotive, and decorative channels. Coating chemistry and substrate geometry determine margin profiles and regulatory compliance burdens for manufacturers serving these distinct demand pools.
Product Type:
Geometry specifications dictate deposition process selection and optical performance thresholds across installation environments.
- Flat Mirrors:Standard float glass substrates with uniform reflective layers achieve reflectance values exceeding 90 percent for visible light. Demand concentrates in China's tier-one city commercial towers where MEE energy codes mandate high-performance glazing in new construction above specified floor areas.
- Convex Mirrors:Curved substrates with outward-bulging reflective surfaces expand field of view for traffic safety and retail surveillance applications. Automotive rear-view system upgrades in Japan and South Korea are pulling precision-coated convex variants for electrified vehicle platforms requiring electrochromic integration.
- Concave Mirrors:Inward-curving reflective geometry concentrates light for specialized optical and solar thermal applications.
- Decorative Mirrors:Patterned, tinted, or antiqued finishes serve interior design specifications where aesthetic differentiation outweighs maximum reflectance.
Mature deployment sits with flat mirrors. Newer deployment is concentrated in convex mirror variants for advanced driver-assistance systems.
Application:
End-use sectors impose distinct durability, optical precision, and thermal performance requirements that filter supplier qualification.
- Automotive:Rear-view systems and side mirrors require vibration-resistant substrates with humidity-stable reflective layers. Electrified vehicle platforms in Japan and South Korea are integrating electrochromic mirror modules requiring vacuum-coated precision substrates with transparent conductive oxide interlayers.
- Architecture:Facade glazing and interior partition systems demand solar control properties combined with structural wind-load resistance. Germany's Rhine-Ruhr metropolitan cluster architects are specifying low-emissivity mirrored glass for energy-positive building envelopes under EU Green Deal efficiency targets.
- Furniture:Decorative and functional mirror panels for cabinetry and fixtures prioritize cost thresholds over maximum optical performance.
- Appliances:Refrigerator interiors and cooking equipment surfaces specify corrosion-resistant aluminum coating variants where humidity exposure is moderate.
Volume concentration rests with architectural applications. Steepest expansion trajectory is occurring in automotive electrochromic integration.
End User:
Procurement scale and specification authority vary sharply across buyer categories, compressing supplier rosters for large-volume accounts.
- Residential:Individual homeowners and small contractors purchase through retail and distribution channels with limited technical specification leverage.
- Commercial:Multinational construction groups and general contractors in China's tier-one cities are mandating multi-year volume commitments with fixed pricing clauses that exclude tier-two coaters without captive float glass supply.
- Industrial:Manufacturing facilities and logistics centers specify durability-rated mirrors for safety and process monitoring applications.
- Retail:Department stores and supermarkets deploy convex surveillance mirrors and decorative fixtures with standardized procurement protocols.
Contract leverage concentrates with commercial buyers. Specification fragmentation persists across residential procurement.
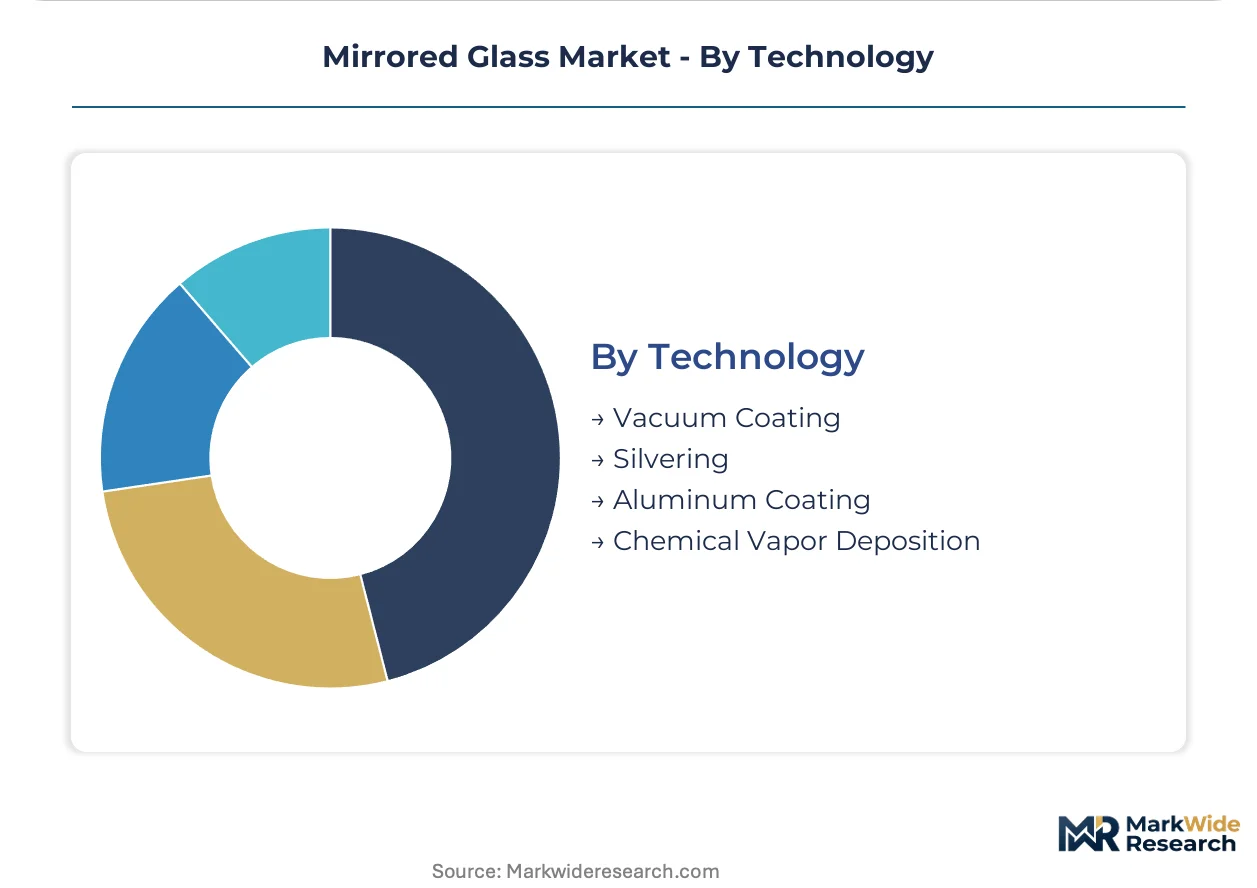
Technology:
Deposition method determines capital intensity, coating uniformity, and regulatory compliance exposure for producers.
- Vacuum Coating:Magnetron sputtering deposits metallic layers in controlled atmospheric conditions achieving superior adhesion and thickness precision. Solar-integrated building facades command premium positioning where energy performance ratings determine specification, with EU F-Gas Regulation constraining certain fluorinated precursors and forcing R&D redirection toward compliant chemistries.
- Silvering:Chemical reduction processes deposit silver layers with copper-free variants integrating aluminum oxide protective interlayers that eliminate edge corrosion in humid climates, compressing demand for traditional copper-backed mirrors in premium Singapore and Miami coastal specifications.
- Aluminum Coating:Thermal evaporation of aluminum delivers cost-efficient reflectance for appliance and furniture segments where maximum reflectance requirements are secondary to price thresholds.
- Chemical Vapor Deposition:Gas-phase precursor reactions enable conformal coating of complex geometries for specialized optical and semiconductor-adjacent applications.
Process maturity resides with silvering chemistry. Fastest capability expansion is occurring in vacuum coating for solar control variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial construction clusters in China's tier-one cities, Germany's Rhine-Ruhr corridor, and India's Mumbai-Delhi belt concentrate mirrored glass specification pull. Regulatory tightening across these jurisdictions is redirecting capacity investments toward compliant deposition technologies.
China
MEE building energy codes mandate high-performance glazing in new commercial construction above specified floor areas, pulling vacuum-coated mirror specifications into Beijing and Shanghai developments. The country's dual carbon goals are tightening energy-efficiency mandates for building envelope materials. Tier-one city general contractors are mandating multi-year volume commitments with fixed pricing clauses that exclude independent coaters without captive float glass supply.
Germany
Architects in the Rhine-Ruhr metropolitan cluster are specifying low-emissivity mirrored glass for energy-positive building envelopes under EU Green Deal efficiency targets. The EU F-Gas Regulation constrains certain fluorinated deposition precursors, forcing R&D redirection toward compliant vacuum coating chemistries. Production gravity concentrates among captive float glass producers with backward integration into raw material supply.
India
Underpenetrated commercial construction markets in the Mumbai-Delhi corridor present white space for solar control mirror variants. BIS energy-efficiency labeling is expanding compliance requirements for building envelope materials. Procurement centralization among multinational construction groups is compressing supplier rosters and extending contract durations in tier-one developments.
United States
California Energy Commission Title 24 extends efficiency labeling requirements that influence mirrored glass specification in LEED-targeted projects across Western states. EPA guidelines intersect with state-level mandates to create multi-jurisdictional compliance burdens. The Southeast construction corridor is absorbing capacity from distributors serving high-rise residential and commercial tower developments.
Japan
Electrified vehicle platforms are integrating electrochromic mirror modules requiring precision-coated substrates with transparent conductive oxide interlayers. METI efficiency standards are accelerating specification of high-performance glazing in commercial retrofits. Specialized magnetron sputtering expertise concentrates among aging workforces in the Kanto industrial belt, constraining capacity expansion timelines.
Mirrored Glass Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with architectural specification favoring integrated producers while appliance and furniture channels absorb independent coaters. Three producer groups control captive float glass capacity in Europe and China, limiting substrate access for non-integrated competitors. Strategic archetypes include backward-integrated glass majors, regional coating specialists, and technology-licensed fabricators. Dominant competitive moves center on captive raw material control and multi-year procurement contracting with general contractors.
Among European integrated producers, Saint-Gobain represents the backward-integrated archetype with in-house float glass capacity, while Guardian Industries anchors North American distribution architecture. AGC exemplifies Asia-Pacific specialization in vacuum coating for solar control variants. These three entities occupy positions that independent coaters cannot readily replicate without substrate supply guarantees or deposition technology licensing.
| Leading Market Players |
|---|
| Saint-Gobain |
| Guardian Industries |
| AGC |
| Pilkington |
| Asahi |
| Taiwan Glass |
| Sisecam |
| Xinyi Glass |
| Jin Jing Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap coating specialists in China's Jiangsu and Zhejiang provinces anchor regional supply clusters while exercising disciplined pricing through long-term float glass offtake agreements with captive producers. Their ownership structure enables patient capital deployment against volatile silver input costs, insulating project bids from spot-market fluctuations that erode margin at independent coaters lacking upstream guarantees.
Pricing Analysis
Volume shipments of flat architectural mirrors compress margin per square meter, while vacuum-coated solar control variants sustain premium positioning through energy-performance certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates LEED-targeted specifications from commodity interior applications. Cost compression in standard-grade silvering is intensifying because copper-free chemistry adoption forces line reconfiguration without immediate price recovery. Commercial construction groups in China's tier-one cities exhibit lowest price sensitivity due to multi-year contracting power, while residential retail channels absorb steepest discount pressure.
Supply Chain Analysis
Specialized magnetron sputtering technician scarcity in Japan's Kanto industrial belt and Germany's Ruhr region constrains capacity expansion timelines for vacuum coating operations. Supply concentrates in China, Germany, and Japan for precision-deposited substrates, with float glass feedstock drawing from captive European and Chinese producer groups. Silver bullion, aluminum ingot, and fluorinated deposition precursors constitute critical input dependencies. Single-source vulnerability sits with fluorinated precursor supply under EU F-Gas Regulation phase-down schedules. Distribution runs through dedicated architectural glass channels anchored by national distributors with specification influence over general contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mirrored glass market reads as a cost-of-compliance story where EU F-Gas Regulation constraints on fluorinated deposition precursors erect barrier-to-entry moats favoring producers with compliant vacuum coating R&D already deployed.
For Market Incumbents: Anticipate silver price volatility through indexed procurement contracts with London Bullion Market Association suppliers, while accelerating backward integration into copper-free silvering capacity in humid-climate export markets. Electrified vehicle platform mirror module specifications from Japanese and South Korean OEMs represent the priority threat vector requiring transparent conductive oxide layer capability investment. For New Entrants and Emerging Players: Capture white space in India's Mumbai-Delhi corridor commercial construction market where BIS energy-efficiency labeling expansion outpaces local vacuum coating capacity. Solar control mirror variants for energy-positive building envelopes offer the most penetrable specification tier. A go-to-market angle anchored by technology licensing from established Japanese or German deposition equipment suppliers bypasses captive float glass exclusion. For Investors and Strategic Acquirers: General contractor consolidation in China's tier-one cities mandating multi-year volume commitments is the leading indicator that procurement centralization will compress supplier rosters to backward-integrated producers with captive substrate supply. Long-term viability over the next decade rests on deposition chemistry compliance across multiple regulatory jurisdictions. Acquisition targets should prioritize regional coating specialists with proven EU and China dual certification capabilities. The signal to monitor is MEE enforcement intensity on building energy code compliance in new commercial construction floor area thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Silvering Line Conversion | Eliminates edge corrosion failure modes in Singapore and Miami coastal specifications while extending product lifecycle. |
| Captive Float Glass Capacity Addition | Secures substrate supply guarantee against Saint-Gobain and Guardian Industries exclusionary contracting with tier-one general contractors. |
| Dual Certification Investment | Enables simultaneous EU REACH compliance and China GB standard qualification, collapsing product launch cycle timelines. |
| Electrochromic Mirror Module Partnership | Positions for Japanese and South Korean electrified vehicle platform integration requiring precision-coated substrates. |
| Fluorinated Precursor Substitution R&D | Anticipates EU F-Gas Regulation phase-down constraints on magnetron sputtering chemistries before compliance deadlines. |
Study Parameters
Multi-period observation of MEE building energy code enforcement patterns, EU F-Gas Regulation implementation timelines, and silver bullion price volatility anchored the trend analysis, supplemented by interviews with architectural specification consultants, float glass procurement directors at integrated producers, vacuum coating line engineers, and general contractor glazing procurement managers. Secondary validation drew from customs trade data, SEC 10-K filings of publicly traded glass producers, BIS and REACH regulatory filings, and project development databases tracking commercial tower construction permits. Bottom-up shipment estimates by coating technology and application triangulated against top-down construction spend allocations.
Input-output matrices modeled capacity utilization, raw material cost pass-through elasticity, and specification pull from energy efficiency regulations across the analysis window. Segmentation dimensions included coating chemistry, substrate geometry, end-use application, and regional regulatory cluster. CAGRs were derived from regression-based projection of construction permit flows and technology substitution curves. Industry-specific forecast inputs comprised silver price scenario modeling and magnetron sputtering technician workforce demographics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE code enforcement intensity, EU F-Gas Regulation amendment scope, and electrified vehicle platform mirror module specification migration. Forecasts reflect documented assumptions on regulatory implementation pacing and construction cycle duration. Material deviation in silver price volatility regimes or dual certification protocol divergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Product Market
Glass
Optical Materials Market
Glass
Decorative Glass Market
Glass
Foam Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Borosilicate Glass Market
Glass
Silica Sand Market
Glass
Antiglare Glass Market
Glass
Optical Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Glass Polishing Powder Market
Glass
United States Flat Glass Market
Glass
3D Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Europe Glass Insulators Market
Glass
Global Vitrification Market