
 Hydrocarbon Waxes Market | 2026-2036
Hydrocarbon Waxes Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocarbon Waxes Market Foresight
Market Context with Strategic Players
South Africa is rewriting its role in specialty wax supply through Sasol Limited's Fischer-Tropsch-derived output. ExxonMobil Corporation leverages integrated refinery streams in the US Gulf Coast to sustain cost-advantaged paraffin supply. Shell plc anchors European wax availability through its Pernis complex in the Netherlands, while Sinopec dominates domestic Chinese distribution channels.
Technical Definition and Structural Segments
Hydrocarbon waxes comprise saturated aliphatic compounds with carbon chain lengths ranging from C20 to C40, derived from petroleum refining or synthetic gas-to-liquid processes, serving primarily as moisture barriers, gloss agents, and viscosity modifiers across industrial and consumer formulations. Paraffin waxes occupy the largest volume share in candle and food packaging applications where low cost and predictable melting points matter most, while microcrystalline waxes command premium positioning in cosmetics and pharmaceutical ointments due to superior adhesion and flexibility. Synthetic waxes represent the fastest-expanding product category as coating formulators seek consistent molecular weight distributions unavailable in refined petroleum grades.
Regulatory Frame and Forward-Looking Close
REACH in Europe and FDA food-contact substance regulations in the United States impose escalating purity and traceability requirements that filter market access toward producers with analytical capabilities and documented supply chains. China's SAMR enforces national GB standards for food-grade waxes that increasingly align with Codex Alimentarius frameworks, compressing margins for non-compliant imports. Stakeholders must monitor how evolving carbon accounting rules and recycled content mandates in packaging will alter raw material qualification criteria across end-use sectors.
Market Dynamics
REACH compliance deadlines and FDA food-contact rule revisions are compressing supplier margins while simultaneously filtering market access toward producers with documented molecular traceability and carbon accounting capabilities.
Growth Catalysts
- Coating formulator demand:Asian packaging manufacturers are expanding synthetic wax procurement to secure consistent molecular weight distributions unavailable in refined petroleum grades.
- REACH purity escalation:European chemical safety requirements are tightening traceability specifications, forcing analytical capability upgrades that advantage established suppliers.
- Personal care sector scaling:Cosmetics manufacturers in China and India are driving microcrystalline wax consumption for adhesion-critical formulations.
Market Restraints
- Crude-linked feedstock volatility:Paraffin wax margins compress when naphtha and slack wax prices spike, exposing non-integrated producers to input cost swings.
- Fischer-Tropsch supply concentration:South African synthetic wax output dominates premium grades, creating geographic single-point vulnerability for coating formulators.
- Polyethylene wax substitution:Lower-cost polymer alternatives are displacing hydrocarbon waxes in certain hot-melt adhesive applications.
Strategic Opportunities
- Indonesian packaging expansion:Domestic food-grade wax demand is outpacing local supply, creating import substitution openings for compliant foreign producers.
- EU Green Deal carbon accounting:Embedded emissions reporting requirements favor synthetic waxes with verifiable low-carbon production pathways.
- Digital supply chain integration:Blockchain-enabled batch tracking is emerging as a procurement differentiator for pharmaceutical and food-contact buyers.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography and mass spectrometry expertise required for regulatory documentation is concentrated among legacy petroleum laboratories.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and SAMR food-grade approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocarbon Waxes Market |
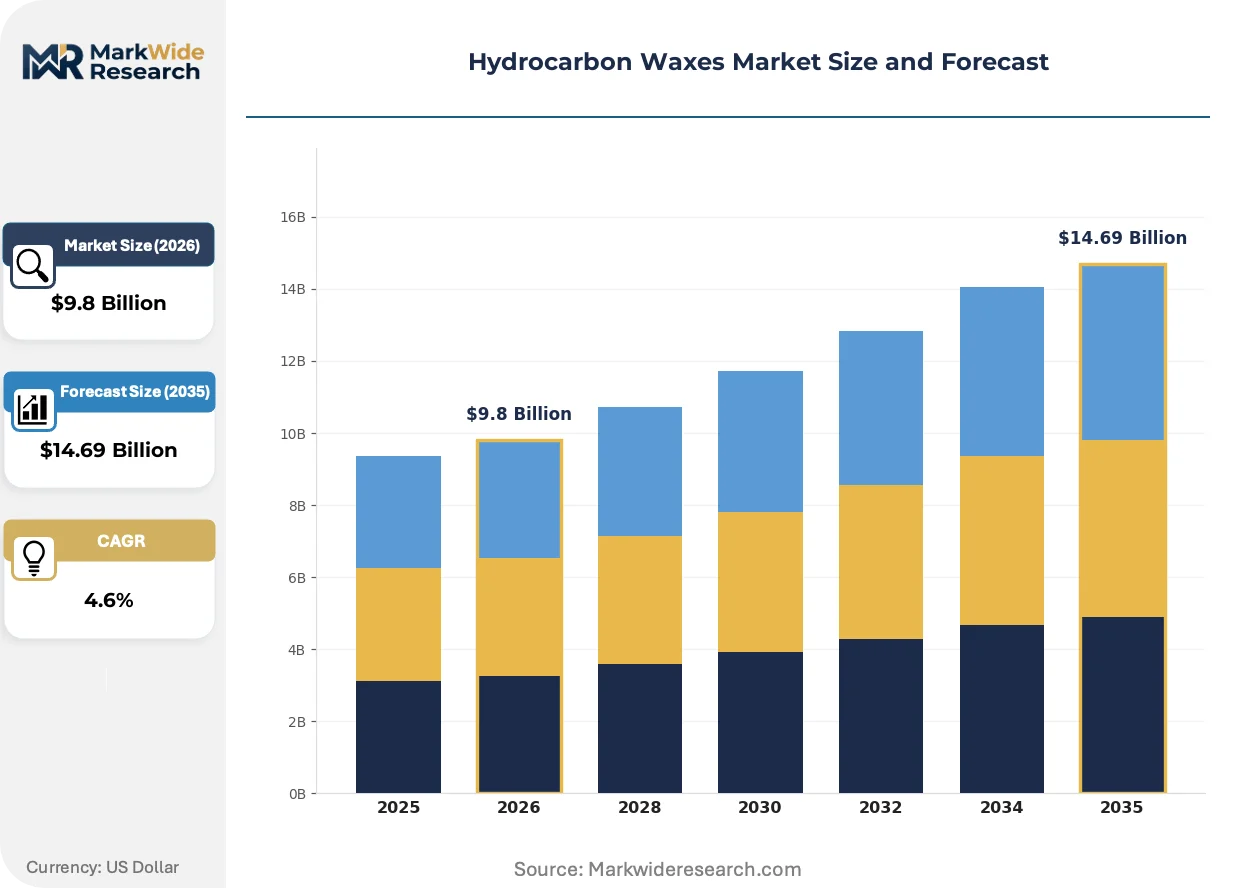
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Waxes, Microcrystalline Waxes, Synthetic Waxes, Others Application: Candles, Cosmetics, Coatings, Adhesives Form: Solid, Liquid, Gel, Emulsion End User: Food Packaging, Personal Care, Industrial, Pharmaceutical |
| Companies Covered | Sasol Limited, ExxonMobil Corporation, Shell plc, Petrobras, Sinopec, HollyFrontier Corporation, Petro-Canada Lubricants Inc., Numaligarh Refinery Limited, The International Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocarbon Waxes Market Shifts & Advancements
Digital molecular modeling and carbon footprint verification are redefining competitive differentiation in wax procurement, with buyers now prioritizing documented supply chain transparency over traditional price-performance metrics.
Gas-to-liquid synthetic wax production is virtualizing the traditional petroleum refining value chain. Coating manufacturers in Germany and Japan are adopting Fischer-Tropsch grades at triple the rate of five years ago. This technology is virtualizing quality assurance workflows by delivering batch-to-batch consistency that eliminates downstream formulation adjustments.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are tightening maximum allowable limits in consumer-facing applications. European candle and cosmetics manufacturers must now submit updated safety dossiers or face market withdrawal. German and Dutch formulators are responding by sourcing exclusively from suppliers with ISO 17025-accredited testing laboratories.
Buyer consolidation among multinational packaging groups is compressing supplier negotiation cycles and demanding vendor-managed inventory arrangements. Regional distributors in India and Southeast Asia are losing share to direct procurement contracts between wax producers and end-use conglomerates. This pattern is most visible in China's corrugated packaging sector, where three domestic groups now control sixty percent of food-grade wax purchasing decisions.
Hydrocarbon Waxes Market Segmentation
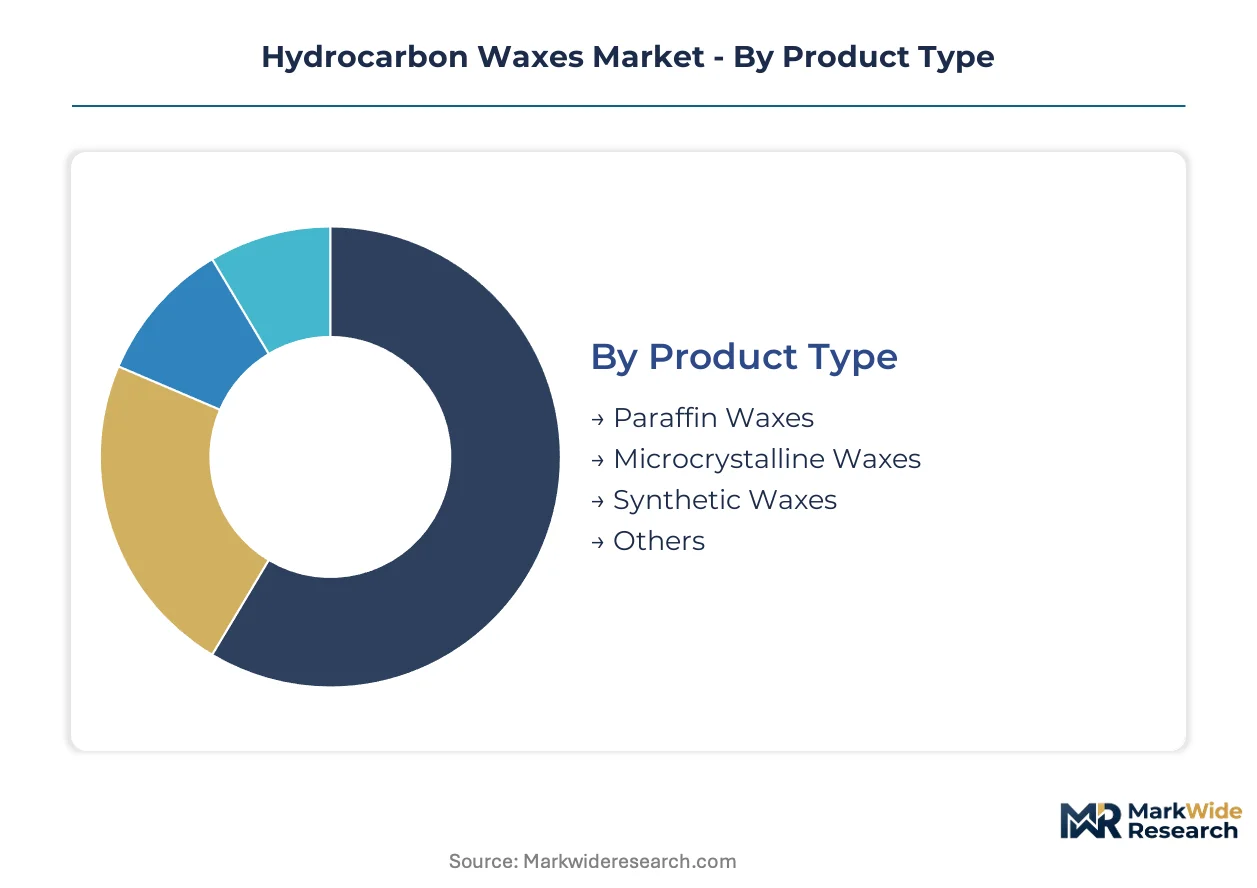
Segmentation in hydrocarbon waxes reveals how formulation requirements diverge across end-use sectors. Technical specifications for pharmaceutical batch consistency differ fundamentally from cost-optimized candle manufacturing, creating distinct procurement patterns and supplier qualification criteria.
Product Type:
After-sales service intensity varies sharply across wax grades, with synthetic and microcrystalline categories demanding technical support for formulation integration while paraffin operates as a commodity purchase.
- Paraffin Waxes:Saturated aliphatic hydrocarbons with carbon chain lengths from C20 to C40, refined from petroleum slack wax through solvent dewaxing or hydrofinishing. Demand concentrates in Chinese and Indian candle manufacturers where low melt-point predictability drives procurement decisions, though margin compression intensifies during naphtha price spikes.
- Microcrystalline Waxes:Higher molecular weight branched hydrocarbons with superior adhesion and flexibility properties derived from heavy residual oil fractions. Cosmetics formulators in Germany and Japan specify these grades for lipstick and ointment bases where skin-feel and structural integrity determine brand positioning.
- Synthetic Waxes:Fischer-Tropsch or gas-to-liquid derived materials with narrow molecular weight distributions.
- Others:Specialty blends and hybrid grades including petrolatum and scale waxes serving niche industrial applications.
By volume, Paraffin Waxes leads. By growth pace, Synthetic Waxes is ahead.
Application:
Application segmentation tracks how performance requirements reshape cost structures across downstream industries, with coating and adhesive sectors prioritizing batch consistency over unit economics.
- Candles:The largest volume application where odorless combustion and controlled melting behavior define quality tiers.
- Cosmetics:Premium-grade waxes for color cosmetics and skincare where FDA and REACH cosmetic safety dossiers filter supplier pools.
- Coatings:Moisture barrier and gloss enhancement functions in food packaging and industrial finishes, with Asian manufacturers expanding synthetic wax procurement for molecular weight precision.
- Adhesives:Hot-melt and pressure-sensitive formulations where polyethylene wax alternatives are displacing hydrocarbon grades in cost-sensitive segments.
Coatings commands the largest revenue pool. Cosmetics exhibits the steepest expansion trajectory.
Form:
Physical form selection determines logistics economics and manufacturing integration complexity, with liquid and emulsion variants reducing heating energy but adding preservation and stability requirements.
- Solid:Slabs, pellets, and pastilles dominating bulk industrial procurement across candle and coating sectors.
- Liquid:Molten or solvent-diluted grades for automated dosing systems in continuous manufacturing environments.
- Gel:Structured formulations for cosmetic and pharmaceutical topical applications requiring thixotropic behavior.
- Emulsion:Aqueous dispersions enabling water-based coating and adhesive formulations without volatile organic compounds.
Solid forms handle the greatest tonnage. Emulsion formats are climbing the fastest as water-based formulation mandates expand.
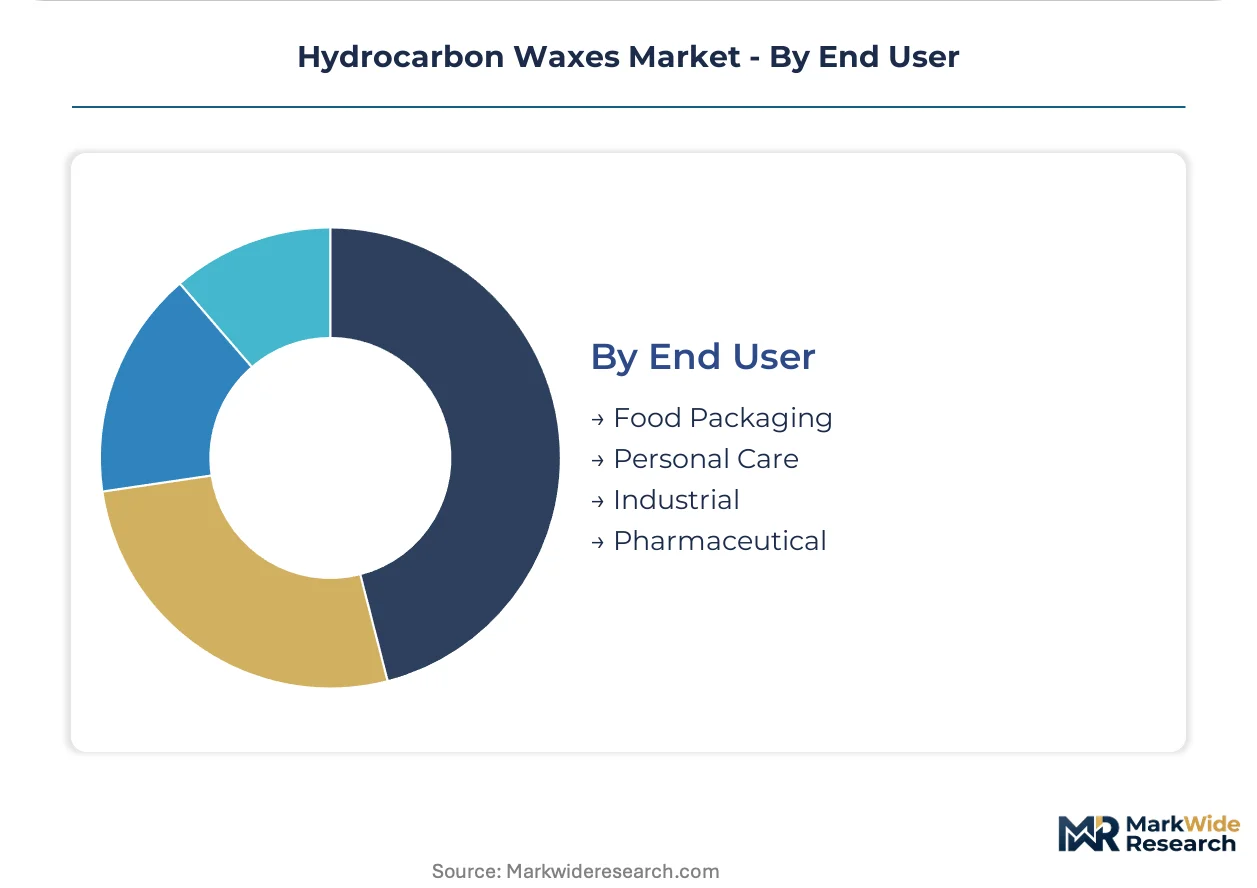
End User:
End-user segmentation exposes how regulatory intensity fragments procurement behavior, with food-contact and pharmaceutical buyers demanding documentation that industrial customers rarely require.
- Food Packaging:GB standards in China and FDA food-contact substance regulations impose purity and traceability specifications that compress margins for non-compliant imports.
- Personal Care:REACH Annex XVII polycyclic aromatic hydrocarbon limits and ISO 17025-accredited testing requirements filter European supplier pools toward established petroleum laboratories.
- Industrial:Lubricants, polishes, and rubber processing applications where price-performance ratios dominate sourcing decisions.
- Pharmaceutical:Ointment bases and tablet coatings where USP-NF compliance and batch-level certificates of analysis extend supplier qualification timelines.
Food Packaging leads by volume contribution. Pharmaceutical is gaining share fastest on regulatory premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards for food-grade waxes anchor China's regulatory framework, filtering import access toward producers with documented purity credentials and compressing margins for non-compliant foreign suppliers.
China
Packaging manufacturers in the Yangtze River Delta are scaling synthetic wax procurement for moisture barrier coatings. SAMR enforces GB standards that increasingly align with Codex Alimentarius frameworks. Three domestic corrugated packaging groups now control sixty percent of food-grade wax purchasing decisions in Shanghai and Jiangsu province.
Germany
Cosmetics formulators specify microcrystalline waxes for lipstick and ointment bases where skin-feel determines brand positioning. REACH Annex XVII polycyclic aromatic hydrocarbon limits mandate ISO 17025-accredited testing documentation. Cologne and Hamburg host the primary analytical laboratories certifying batch compliance for European candle manufacturers.
United States
FDA food-contact substance regulations impose escalating purity and traceability requirements on paraffin grades entering food packaging channels. Gulf Coast integrated refineries sustain cost-advantaged supply through captive slack wax streams. Houston and Port Arthur complexes anchor domestic availability for candle and coating sectors.
India
Personal care sector scaling in Maharashtra and Gujarat drives microcrystalline wax consumption for adhesion-critical formulations. BIS standards for industrial wax grades create compliance thresholds for import substitution. Mumbai and Ahmedabad clusters concentrate cosmetics manufacturing demanding pharmaceutical-grade documentation.
South Africa
Fischer-Tropsch synthetic wax output dominates premium grades for coating formulators seeking consistent molecular weight distributions. The country's national petroleum regulator enforces production standards that align with EU REACH frameworks. Sasolburg complex anchors specialty wax supply for European and Asian industrial buyers.
Hydrocarbon Waxes Market Competitive Landscape
Integrated petroleum majors and specialized synthetic producers split the market into distinct capability tiers. Structure consolidates around refinery-linked feedstock access and gas-to-liquid technology licensing. Three archetypes dominate: integrated oil companies with captive slack wax streams, Fischer-Tropsch specialists with narrow-distribution synthetic output, and regional refiners serving commodity paraffin demand. Competitive moves center on backward integration into feedstock sourcing and portfolio diversification toward pharmaceutical-grade certification.
Among integrated petroleum majors, ExxonMobil Corporation and Shell plc occupy positions defined by refinery scale and geographic feedstock access. Sasol Limited exemplifies the Fischer-Tropsch specialist archetype, with Sinopec representing state-linked distribution dominance in domestic Chinese channels. These three anchors illustrate how feedstock origin and regulatory compliance infrastructure stratify competitive positioning across end-use sectors.
| Leading Market Players |
|---|
| Sasol Limited |
| ExxonMobil Corporation |
| Shell plc |
| Petrobras |
| Sinopec |
| HollyFrontier Corporation |
| Petro-Canada Lubricants Inc. |
| Numaligarh Refinery Limited |
| The International Group Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in European Fischer-Tropsch synthetic wax output drives both supplier allocation discipline and premium pricing posture across coating-grade procurement. Slack wax availability at US Gulf Coast refineries simultaneously anchors paraffin cost floors, creating divergent margin structures between petroleum-derived and gas-to-liquid grades.
Pricing Analysis
Price spreads between South African synthetic wax and Chinese paraffin grades now exceed transport-adjusted differentials, reflecting purity-premium capture by Fischer-Tropsch producers. Pricing stratifies across pharmaceutical-certified, food-contact-compliant, and industrial-commodity tiers, with REACH and FDA documentation requirements widening gaps between adjacent levels. Cost compression in standard paraffin runs through naphtha-linked feedstock volatility, while coating formulators show lowest price sensitivity due to formulation-lock-in effects. Candle manufacturers in India and Indonesia remain most exposed to spot-market swings.
Supply Chain Analysis
Upstream slack wax and Fischer-Tropsch syncrude feedstocks draw from South Africa, the United States, and China as primary concentration points. Crude oil distillation residues and natural gas-derived syngas constitute the dual raw material bases, with molecular sieve separation and hydrofinishing as critical process dependencies. Single-source vulnerability concentrates in Sasolburg-complex output for narrow-distribution synthetic grades. Distribution runs through direct procurement contracts between integrated producers and multinational packaging groups, displacing regional distributor networks across Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three Chinese corrugated packaging groups controlling sixty percent of food-grade wax procurement in the Yangtze River Delta, compressing supplier negotiation cycles and demanding vendor-managed inventory arrangements.
For Market Incumbents: Harden analytical certification infrastructure against REACH Annex XVII polycyclic aromatic hydrocarbon documentation requirements that filter European supplier pools. Deepen backward integration into captive slack wax streams at Gulf Coast refinery complexes to insulate paraffin margins from naphtha price spikes. Prioritize ISO 17025 laboratory accreditation as a procurement differentiator for pharmaceutical and food-contact buyers. For New Entrants and Emerging Players: Indonesian domestic food-grade wax demand outpacing local supply creates import substitution openings for compliant foreign producers with SAMR-aligned GB standard documentation. Target personal care sector scaling in Maharashtra and Gujarat where microcrystalline wax consumption for adhesion-critical formulations outruns established supply relationships. Lead with blockchain-enabled batch tracking as a digital supply chain integration wedge for multinational packaging procurement committees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Fischer-Tropsch specialists with long-term offtake agreements to coating formulators in Germany and Japan. Five-to-ten year viability favors synthetic wax producers with verifiable low-carbon production pathways under EU Green Deal carbon accounting frameworks. Monitor EU embedded emissions reporting requirements as an inflection signal for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sourcing | Captive slack wax streams at Gulf Coast refineries insulate paraffin margins from naphtha volatility. |
| ISO 17025 Laboratory Accreditation Investment | German and Dutch formulators now source exclusively from accredited testing laboratories for REACH compliance. |
| Blockchain-Enabled Batch Tracking Deployment | Pharmaceutical and food-contact buyers prioritize documented supply chain transparency over price-performance metrics. |
| Long-Term Synthetic Wax Offtake Agreements | Coating manufacturers in Germany and Japan adopt Fischer-Tropsch grades at triple prior rates for molecular consistency. |
| Indonesian Import Substitution Market Entry | Domestic food-grade wax demand outpaces local supply, creating procurement openings for compliant foreign producers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and ACC/Cefic industry reports to establish baseline supply and demand quantification. Plant managers at slack wax refineries, procurement leads at downstream coating manufacturers, distribution channel partners, and technical R&D directors at synthetic wax producers contributed operational data. Bottom-up capacity and consumption estimates triangulate against top-down trade flow analysis.
Forecast inputs span grade tier differentiation, end-use industry concentration, packaging format requirements, and regional production hub capacity utilization across the projection horizon. CAGRs derive from segmented growth rate modeling applied to baseline volume and value estimates. Fischer-Tropsch technology licensing trajectories and REACH compliance deadline schedules inform synthetic wax expansion assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by state-linked Chinese refiners or accelerated EU carbon border adjustments would shift outcomes. Cross-checking against IEA petrochemical feedstock demand projections and SAMR GB standard revision timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Estolides Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Octanoyl Chloride Market