
 Global Vacuum Insulated Glass Market | 2026-2036
Global Vacuum Insulated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vacuum Insulated Glass Market Foresight
The architectural glass distribution channel is narrowing as specification decisions consolidate around engineering-led procurement teams at major construction firms. Guardian Glass leverages its North American fabrication network to sustain project-level partnerships with curtain wall contractors. Saint-Gobain S.A. anchors European supply through integrated float-to-fabrication operations spanning multiple countries. Nippon Sheet Glass Co., Ltd. dominates technical specification in Japan's seismic-rated building segment through proprietary spacer technology.
Vacuum insulated glass consists of two or more glass panes hermetically sealed around a perimeter with internal vacuum pressure maintained below 0.1 Pa, eliminating gas conduction and convection to achieve center-of-glass U-values approaching 0.4 W/m²K. This thermal performance enables facade systems to meet stringent envelope standards without excessive glazing thickness or weight. Double Vacuum IGU leads current project specifications due to its balance of performance and structural feasibility, while Triple Vacuum IGU captures premium positioning in sub-arctic and cryogenic applications where marginal insulation gains justify substantial cost premiums. The Low-E coating technology segment concentrates margin pools through proprietary sputtered silver stacks that differentiate supplier offerings.
The EU Green Deal's building renovation targets and F-Gas Regulation phase-down are accelerating substitution of gas-filled units across European member states, while Japan's METI enforces progressive energy conservation standards for commercial structures exceeding specific floor areas. The US EPA Energy Star certification and evolving ASHRAE 90.1 baselines are reshaping domestic specification criteria for institutional and high-performance buildings. Stakeholders must monitor divergence between regional vacuum retention testing protocols and evolving fire-safety classification requirements for edge seal materials.
Market Dynamics
Building code ratcheting across Germany, Japan, and the United States is compressing allowable thermal transmittance values faster than conventional insulating glass units can adapt, forcing specification teams toward vacuum-sealed alternatives.
Growth Catalysts
- EU F-Gas Regulation phase-down:The progressive restriction on hydrofluorocarbon blowing agents for conventional IGUs eliminates cost-competitive alternatives in European commercial retrofits.
- Japan METI energy conservation standards:Mandatory performance thresholds for commercial structures above specific floor areas mandate envelope upgrades that vacuum insulated glass satisfies.
- Seismic-rated high-rise construction:Tokyo and Osaka developers specify vacuum units to reduce glazing weight while meeting thermal targets in tall building envelopes.
Market Restraints
- Edge seal material cost volatility:Specialty glass frits and low-temperature solders fluctuate with rare earth metal pricing, squeezing fabrication margins.
- Getter material supply concentration:Evacuation pumps and non-evaporable getter production clusters in German and Japanese equipment suppliers create single-source vulnerability.
- Structural glazing thickness limitations:Current vacuum cavity geometries restrict maximum pane sizes for hurricane-rated applications in Florida and Gulf Coast specifications.
Strategic Opportunities
- India commercial building stock:Green building council certification adoption in Mumbai and Bangalore creates first-mover positioning before local fabrication scales.
- Cryogenic transport containers:LNG shipping and biomedical cold chain applications demand triple-pane vacuum configurations at premium pricing.
- US Inflation Reduction Act efficiency tax credits:Section 179D deductions for building envelope improvements accelerate payback calculations for institutional owners.
Industry Challenges
- Vacuum retention certification timelines:Accelerated aging protocols for 25-year vacuum integrity guarantees extend product qualification cycles.
- Edge seal fire-safety classification:Evolving EN 1363 and ASTM E119 testing requirements for perimeter materials complicate multi-jurisdiction approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vacuum Insulated Glass Market |
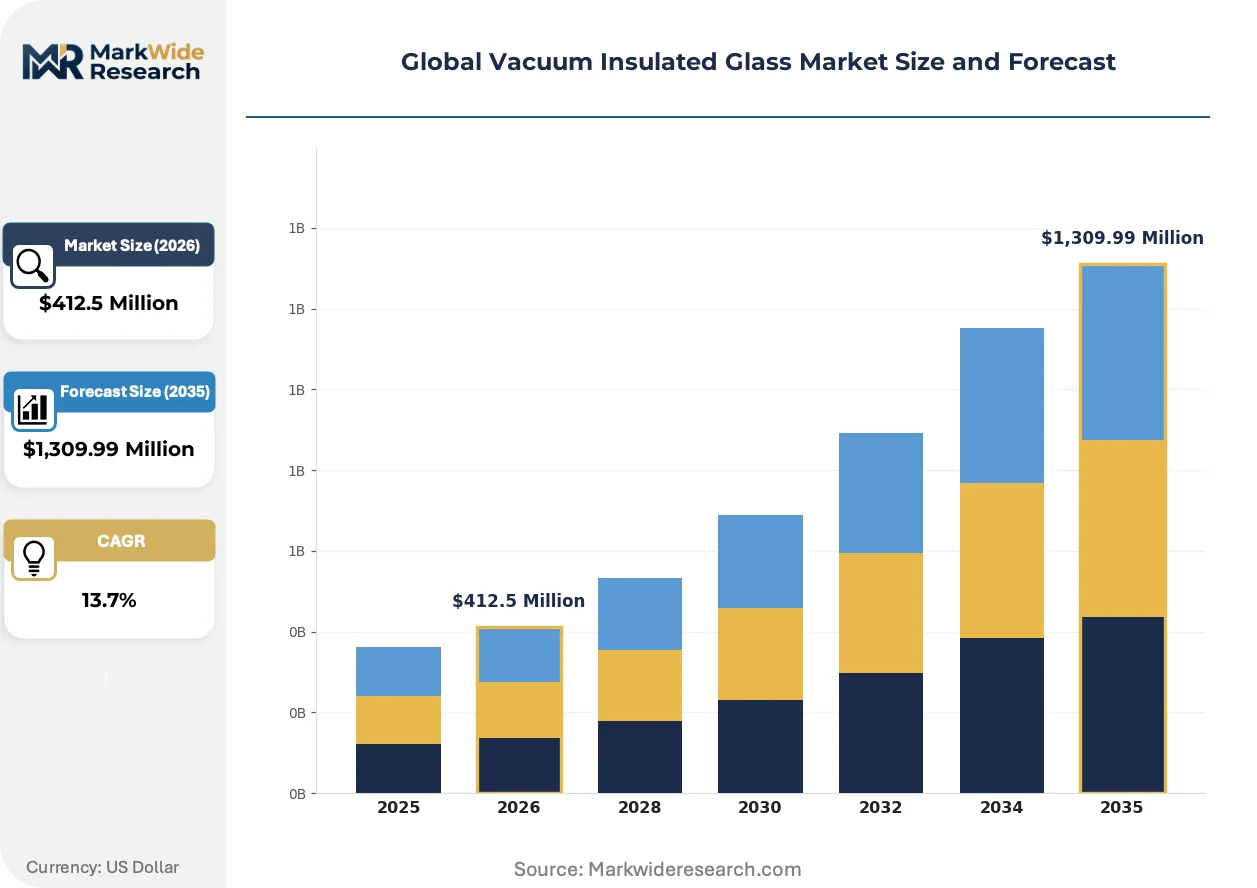
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vacuum IGU, Double Vacuum IGU, Triple Vacuum IGU, Customized Vacuum IGU Technology: Laminated, Tempered, Coated, Low-E, Electrically Heated Application: Commercial Buildings, Residential Properties, Cold Storage, Transport Vehicles, Museums End User: Glass Manufacturers, Construction Companies, OEMs, Aftermarket Suppliers, Facility Management |
| Companies Covered | AGC Inc., Guardian Glass, Nippon Sheet Glass Co., Ltd., Saint-Gobain S.A., Panasonic Corporation, LandGlass Technologies Co., Ltd., Vitro Architectural Glass, Schott AG, Xinyi Glass Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vacuum Insulated Glass Market Shifts & Advancements
Thermal performance benchmarking is collapsing the acceptable performance gap between laboratory specimens and field-installed units, forcing suppliers to validate real-world durability.
Getter-free evacuation technology is collapsing the historical dependency on active pumping systems during manufacture. Japanese fabricators in Yokohama and German specialists in Bavaria now deploy laser-sealed perimeter edges with passive vacuum maintenance. Commercial curtain wall contractors in Frankfurt and Chicago specify these units to eliminate long-term degradation risk.
The EU Green Deal's building renovation targets are mandating deep energy retrofits across member state building stocks. France's RE2020 environmental regulation and Germany's Building Energy Act impose thermal bridge-free envelope requirements. Residential and commercial facade contractors in Paris and Berlin substitute vacuum units for triple-glazed alternatives to meet thickness constraints.
Engineering-led procurement teams at major construction firms now specify performance-guaranteed supply contracts rather than commodity glass purchases. Skanska, Hochtief, and Obayashi procurement departments demand 25-year thermal warranty backing. This concentrates specification authority away from distributor channels toward direct manufacturer relationships in London, New York, and Singapore project offices.
Global Vacuum Insulated Glass Market Segmentation
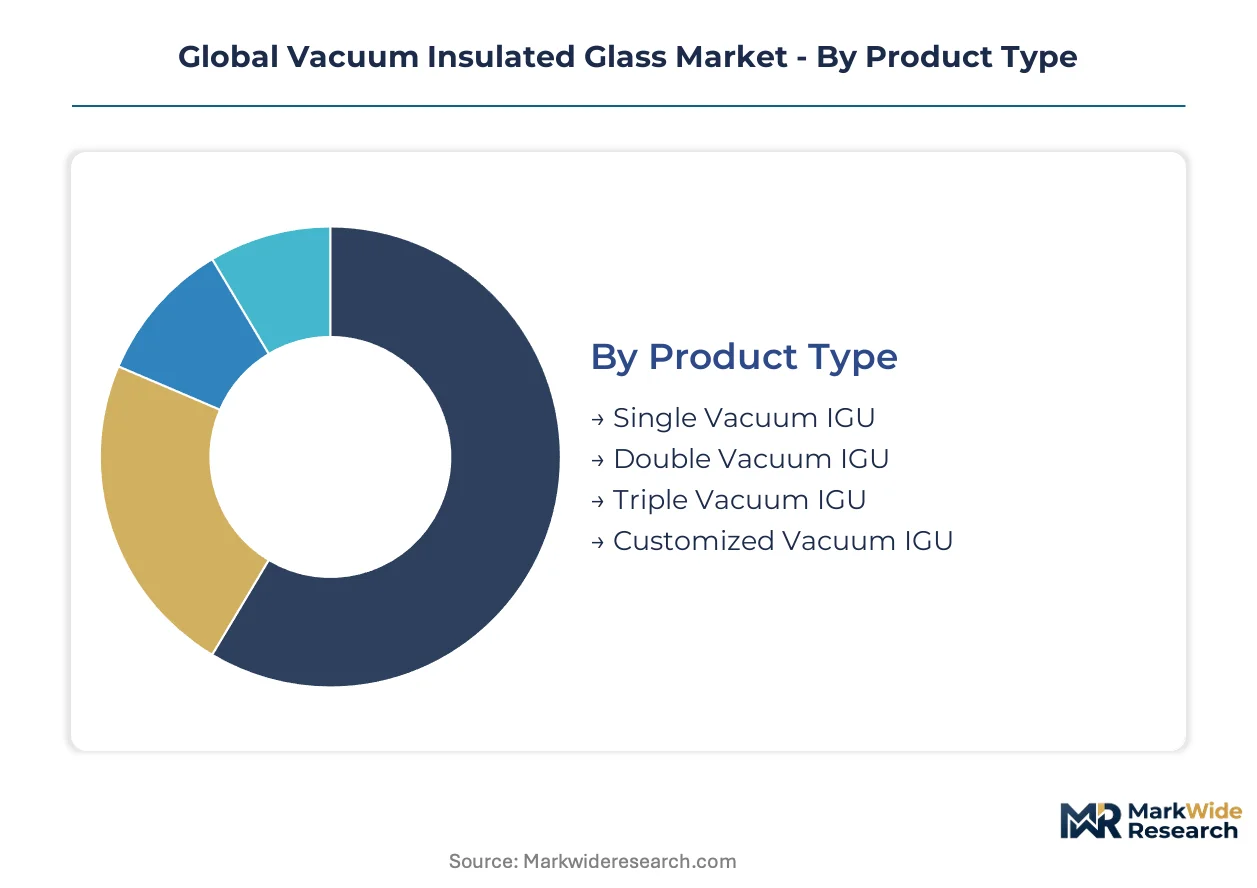
Specification teams decompose vacuum insulated glass procurement across four intersecting dimensions. Product geometry determines thermal performance thresholds. Technology selection governs durability and optical properties. Application context drives structural loading requirements. End-user category shapes warranty terms and supply chain access.
Product Type:
Facade engineers select cavity configurations based on thermal targets, structural constraints, and lifecycle cost modeling across project portfolios.
- Single Vacuum IGU:One evacuated cavity between two glass lites delivers baseline thermal resistance for residential retrofits and secondary glazing applications. German Passivhaus-certified housing projects in Stuttgart and Hanover specify these units to meet envelope standards without frame replacement.
- Double Vacuum IGU:Twin evacuated chambers separated by a central glass lite achieve center-of-glass U-values approaching 0.4 W/m²K. Commercial curtain wall contractors in Frankfurt and Chicago specify these units for high-rise envelopes where weight reduction matters.
- Triple Vacuum IGU:Three cavities with four glass lites target sub-arctic and cryogenic applications. LNG shipping operators and biomedical cold chain providers in Rotterdam and Singapore pay substantial premiums for marginal insulation gains.
- Customized Vacuum IGU:Bespoke geometries accommodate irregular facade panels and heritage building retrofits. Conservation architects in London and Vienna commission shaped units for listed building upgrades.
The dominant share belongs to Double Vacuum IGU, while Triple Vacuum IGU is gaining share fastest in specialized cold-chain applications.
Technology:
Surface treatments and interlayer technologies differentiate supplier offerings through optical performance, mechanical durability, and active functionality.
- Laminated:Polyvinyl butyral or ionoplast interlayers bond glass lites for post-breakage retention and acoustic damping. Museum facade specifications in Paris and New York mandate laminated constructions for artifact protection.
- Tempered:Thermal or chemical strengthening increases surface compression for wind load and impact resistance. Florida hurricane-rated applications and Tokyo seismic zones require tempered outer lites.
- Coated:Hard-coat pyrolytic or soft-coat sputtered layers modify emissivity and solar control. Solar heat gain coefficient tuning dominates Middle Eastern commercial specifications.
- Low-E:Proprietary silver-stack sputtered coatings concentrate margin pools through thermal radiation suppression. European suppliers differentiate through multi-layer spectral selectivity.
- Electrically Heated:Transparent conductive oxide layers enable active defrosting and condensation control. Cold storage operators in Denmark and Sweden specify heated units for freezer door applications.
Low-E coating technology commands the widest specification footprint, though Electrically Heated variants are expanding most quickly in refrigerated logistics infrastructure.
Application:
Environmental loading, occupancy patterns, and regulatory exposure vary sharply across installation contexts.
- Commercial Buildings:Office towers, retail centers, and institutional facilities drive volume through large curtain wall installations. EU Green Deal renovation targets in France and Germany accelerate facade replacement cycles.
- Residential Properties:Single-family and multi-family housing prioritize cost-effective thermal upgrades. Japan's METI standards for commercial structures above specific floor areas indirectly boost residential specification through technology spillover.
- Cold Storage:Warehouses and distribution centers demand maximum insulation with minimal envelope thickness. Automated logistics facilities near Rotterdam and Hamburg specify vacuum units to maximize cubic storage capacity.
- Transport Vehicles:Refrigerated trucks, rail cars, and shipping containers require lightweight, vibration-resistant glazing. LNG carrier superstructures in South Korean shipyards represent emerging demand.
- Museums:Climate-controlled exhibition spaces combine thermal stability with UV filtration. Conservation-grade specifications in London, New York, and Tokyo mandate ultra-low U-values for artifact preservation.
Commercial Buildings absorb the largest project volume, while Cold Storage applications show the steepest expansion trajectory as automated logistics scales.
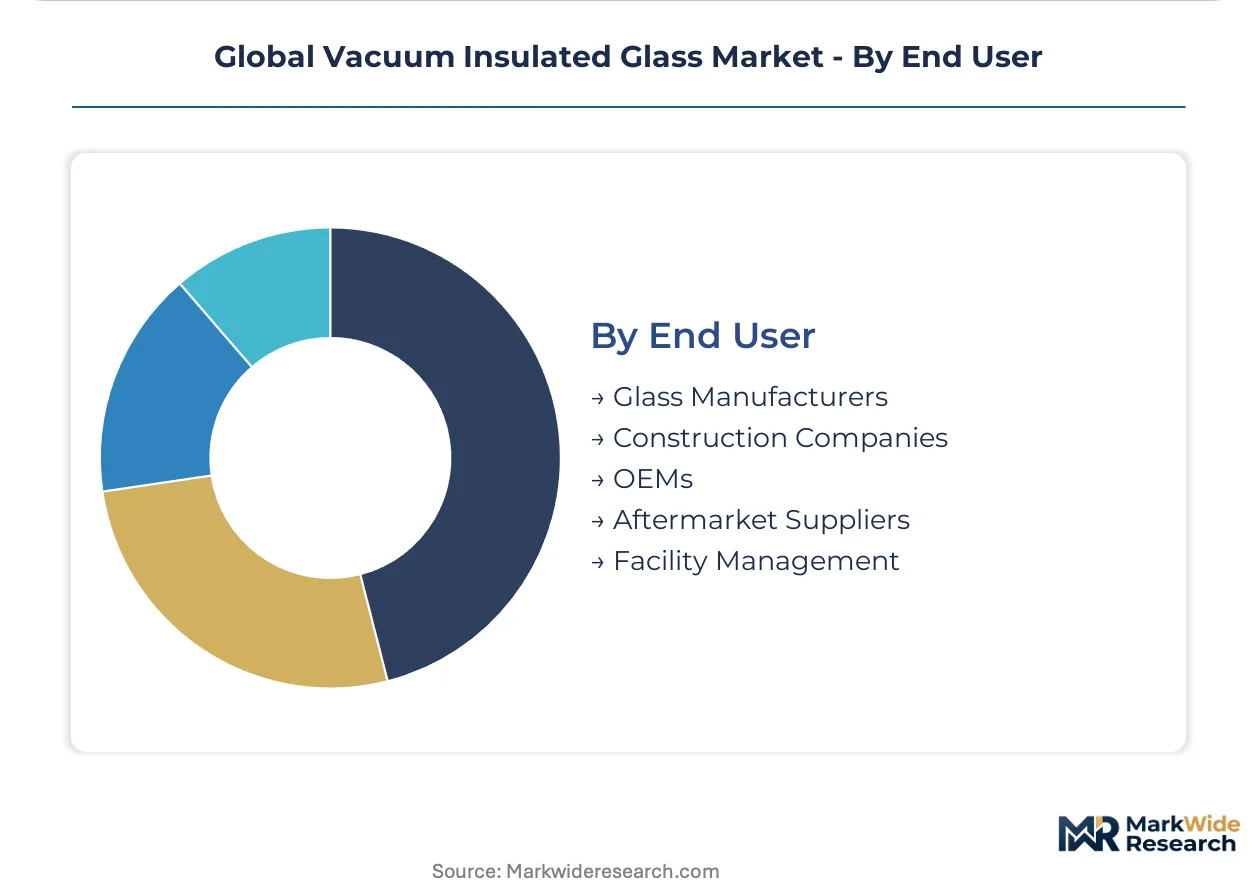
End User:
Procurement authority and technical capability determine channel structure and contract terms.
- Glass Manufacturers:Float glass producers backward-integrate into fabrication to capture value-added margin. Guardian Glass and Saint-Gobain operate captive vacuum IGU lines.
- Construction Companies:Engineering-led procurement teams at Skanska, Hochtief, and Obayashi demand 25-year thermal warranties. Direct manufacturer relationships displace distributor channels.
- OEMs:Window and door system manufacturers specify vacuum units for premium product lines. European facade system suppliers integrate vacuum IGU into certified component assemblies.
- Aftermarket Suppliers:Replacement glazing contractors serve retrofit and repair demand. Regional fabricators in secondary cities compete on lead time and customization.
- Facility Management:Building operators procure vacuum units for envelope maintenance and energy upgrade programs. Corporate real estate departments in London and Singapore specify performance-guaranteed supply contracts.
Construction Companies direct the largest procurement volume, though Facility Management is climbing fastest as building lifecycle service contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's building renovation targets and Japan's METI energy conservation standards are accelerating specification of vacuum insulated glass across commercial construction sectors. National building codes in Germany, Japan, and the United States now mandate thermal performance thresholds that conventional insulating glass units cannot satisfy.
Germany
Passivhaus-certified housing projects in Stuttgart and Hanover specify single vacuum IGU configurations to meet envelope standards without frame replacement. The Building Energy Act imposes thermal bridge-free requirements that compress allowable U-values below conventional triple-glazing capabilities. Curtain wall contractors in Frankfurt increasingly source double vacuum units from Bavarian fabrication clusters to reduce glazing weight in high-rise envelopes.
Japan
Seismic-rated high-rise construction in Tokyo and Osaka drives specification of vacuum units to achieve thermal targets with reduced mass. METI mandates progressive energy conservation standards for commercial structures exceeding specific floor areas, forcing envelope upgrades in existing building stock. Yokohama fabricators deploy laser-sealed perimeter edges with passive vacuum maintenance to eliminate long-term degradation risk.
United States
Institutional owners leverage Section 179D deductions from the Inflation Reduction Act to accelerate payback calculations for building envelope improvements. ASHRAE 90.1 baseline evolution reshapes specification criteria for high-performance buildings in Chicago and New York. Hurricane-rated applications in Florida face structural glazing thickness limitations that restrict maximum pane sizes for current vacuum cavity geometries.
France
RE2020 environmental regulation imposes lifecycle carbon limits on new construction that favor thin-profile vacuum units over thick triple-glazing alternatives. Deep energy retrofits mandated by EU Green Deal targets concentrate procurement in Paris commercial facade replacement programs. Residential and commercial contractors substitute vacuum units to meet thickness constraints in historic building envelopes.
United Kingdom
Conservation architects in London commission customized vacuum IGU geometries for listed building upgrades where heritage constraints prohibit frame modifications. Building regulation tightening on thermal transmittance values drives specification toward vacuum-sealed alternatives in commercial retrofits. Engineering-led procurement teams at major construction firms demand 25-year thermal warranty backing, concentrating authority toward direct manufacturer relationships.
Global Vacuum Insulated Glass Market Competitive Landscape
On the supply side, the industry is consolidating around integrated float-to-fabrication operations and specialized vacuum sealing technology providers. The vendor base separates into three strategic archetypes: multinational glass conglomerates with captive vacuum IGU lines, regional fabrication specialists with proprietary spacer technology, and equipment-technology licensors serving emerging market entrants. Dominant competitive moves include backward integration into low-E coating capacity and strategic partnerships with curtain wall engineering firms to secure specification lock-in.
Among multinational glass conglomerates, AGC Inc., Saint-Gobain S.A., and Nippon Sheet Glass Co., Ltd. anchor the premium-tier supply position through integrated manufacturing footprints spanning multiple countries. These Tokyo-based and Paris-based entities exemplify the scale-driven archetype, leveraging captive float glass production to control raw material cost volatility. Regional specialists such as Guardian Glass and Vitro Architectural Glass occupy positions within the North American fabrication tier, while Schott AG and Panasonic Corporation represent technology-intensive players with advanced vacuum maintenance capabilities.
| Leading Market Players |
|---|
| AGC Inc. |
| Guardian Glass |
| Nippon Sheet Glass Co., Ltd. |
| Saint-Gobain S.A. |
| Panasonic Corporation |
| LandGlass Technologies Co., Ltd. |
| Vitro Architectural Glass |
| Schott AG |
| Xinyi Glass Holdings Limited |
| Others |
Supply & Pricing Matrix
German and Japanese equipment suppliers dominate evacuation pump and non-evaporable getter production, anchoring margin capture downstream at fabrication specialists who control laser-sealing technology and proprietary spacer systems.
Pricing Analysis
Volume-discount tiering separates project-scale curtain wall contracts from aftermarket replacement orders. Pricing stratifies across premium, standard, and economy tiers based on Low-E coating complexity and 25-year thermal warranty backing. Cost compression in standard-grade double vacuum units is intensifying because Chinese fabricators are scaling tempered glass processing capacity. Cold storage operators show least price sensitivity due to cubic-capacity payback calculations, while residential retrofit contractors remain highly price-sensitive.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts specialty glass frit supply flows for edge seal materials. Manufacturing concentrates in Germany, Japan, and China, with raw material dependencies spanning rare earth metals for getters, silver sputtering targets for Low-E coatings, and ionoplast interlayers for laminated configurations. Single-source vulnerability clusters in Bavarian and Yokohama equipment suppliers who control laser-sealing technology. Distribution runs through direct manufacturer relationships with engineering-led procurement teams at major construction firms, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum insulated glass sits in early-cycle expansion as EU Green Deal renovation mandates and Japan METI standards force specification migration from conventional triple-glazing before local fabrication scales in emerging markets.
For Market Incumbents: Pre-empt Chinese fabricator scale-up by securing captive Low-E coating capacity and locking 25-year thermal warranty terms with Skanska, Hochtief, and Obayashi procurement departments. Backward integration into silver-stack sputtering technology defends margin pools against emerging Asian suppliers. For New Entrants and Emerging Players: Establish a beachhead in India's commercial building sector before local fabrication scales, targeting Green Building Council certification projects in Mumbai and Bangalore. Partner with European facade system suppliers for certified component assembly integration rather than competing on project-scale curtain wall contracts. For Investors and Strategic Acquirers: Capital is best deployed toward regional fabrication specialists with proprietary laser-sealing technology and established METI or Passivhaus certification pathways. Long-term viability hinges on vacuum retention testing protocol harmonization across jurisdictions. Watch for inflection when Indian or Southeast Asian building codes adopt thermal transmittance thresholds below conventional IGU capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-E Coating | Captures margin pools concentrated in proprietary silver-stack sputtering technology. |
| 25-Year Thermal Warranty Programs | Locks specification authority with engineering-led procurement at major construction firms. |
| Laser-Sealing Technology Licensing | Enables getter-free evacuation for passive vacuum maintenance without German equipment dependency. |
| Regional Fabrication Scale-Up | Reduces logistics costs and tariff exposure for EU Green Deal renovation targets. |
| Certified Component Assembly Partnerships | Integrates vacuum IGU into OEM window and door systems for premium product lines. |
Research Methodology
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings. The research team conducted structured discussions with curtain wall engineering directors, facade procurement managers at major construction firms, glass fabrication plant managers, and cold storage facility operators. Secondary validation drew from EU F-Gas Regulation filings, Japan METI energy conservation standard updates, ASHRAE 90.1 baseline documentation, and SEC 10-K disclosures from listed glass manufacturers. Bottom-up project pipeline analysis triangulated against top-down building stock renovation targets.
Calibration against historical penetration curves in Germany and Japan informs the analytical framework across the projection horizon. Segmentation modeling covers cavity configuration, coating technology, application context, and end-user procurement authority. CAGRs derive from fitting adoption curves to regulatory mandate timelines and local fabrication capacity buildouts. Industry-specific inputs include Passivhaus certification volumes, METI commercial floor-area thresholds, and Section 179D deduction utilization rates.
Sensitivities concentrate around vacuum retention certification timeline extensions, edge seal fire-safety reclassification, and rare earth metal price volatility. Forecasts reflect documented assumptions on regulatory ratcheting speed and equipment supplier capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Advanced Glass Market
Glass
Global Glassware Market
Glass
North America Glass Insulators Market
Glass
Glass Tableware Market
Glass
Solar Control Glass Market
Glass
Spherical Silica Market
Glass
Global Self-Cleaning Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Europe Silica Sand for Glass Making Market
Glass
3D Glass Market
Glass
Glass Recycling Market
Glass
Shatterproof Glass Market
Glass
Heat Resistant Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Low-E Glass Market