
 Cell Culture Market | 2026-2036
Cell Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Culture Market Intelligence
The transition from animal-derived sera to chemically defined, serum-free media is repositioning the economic and ethical landscape of biopharmaceutical research. This move reduces variability and enhances regulatory compliance. Thermo Fisher Scientific leverages its extensive portfolio to lead this transition, while Lonza Group specializes in custom media development for complex biologics. Merck KGaA anchors its competitive strategy in providing end-to-end bioprocessing solutions, including advanced filtration and purification technologies.
Cell culture involves the in vitro propagation of prokaryotic or eukaryotic cells in a controlled environment. This process requires maintaining specific conditions, including temperature, humidity, pH, and a precise mixture of gases like CO2, within an incubator or bioreactor. Consumable products such as media and reagents constitute the largest revenue segment due to recurring purchases by research labs and biomanufacturers. Within technology, 3D culture models represent the fastest-growing area, offering more physiologically relevant data for drug discovery compared to traditional 2D culture.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) heavily influence market standards for therapeutic applications. These agencies mandate strict Good Manufacturing Practice (GMP) guidelines for all materials, ensuring product safety and consistency. Conformance with ISO standards for quality management is also critical for equipment and consumables suppliers. Navigating the validation pathways for novel cell culture technologies will be a key determinant of future market leadership.
Market Dynamics
The push for reproducibility and scalability in biopharmaceutical manufacturing is the central force shaping the cell culture market. This demand requires chemically defined media and automated systems to meet stringent regulatory standards for cell-based therapies and other biologics.
Growth Catalysts
- 3D Culture Models:These systems provide more physiologically relevant data for drug discovery and toxicology, accelerating preclinical research and reducing reliance on animal testing.
- Biopharmaceutical Expansion:The expanding pipeline of monoclonal antibodies, vaccines, and cell-based therapies creates sustained demand for large volumes of high-quality cell culture media and reagents.
- Favorable Regulatory Pathways:The US FDA's RMAT designation and the EMA's PRIME scheme expedite the development and review of novel cell therapies, stimulating research investment.
Market Restraints
- High Cost of Consumables:The expense of GMP-grade serum-free media and growth factors creates a significant financial barrier for academic labs and early-stage biotechnology companies, limiting experimental scale.
- Contamination Risks:Microbial and viral contamination remains a persistent operational risk, leading to batch failure, significant financial loss, and project delays, especially in large-scale bioreactors.
- Supply Chain Vulnerability:The concentration of raw material suppliers for critical components like fetal bovine serum in specific geographies creates price volatility and supply chain instability.
Strategic Opportunities
- Cultured Meat Production:The emerging field of cellular agriculture presents a vast new application for cell culture technology, requiring novel media formulations and large-scale bioreactor designs to achieve commercial viability.
- AI-Powered Process Optimization:Integrating artificial intelligence with bioreactor sensor data offers an opportunity to automate process control, predict culture outcomes, and optimize media feeding strategies.
- Biomanufacturing in India:India's PLI scheme for pharmaceuticals and its growing biotechnology sector create an opportunity for localized production of cell culture media to serve both domestic and export markets.
Industry Challenges
- Specialized Skill Gaps:A shortage of technicians trained in large-scale bioprocessing, cell line engineering, and GMP-compliant manufacturing protocols constrains the expansion of biopharmaceutical production capacity.
- Lack of Standardization in 3D Models:The absence of standardized protocols and validation criteria for complex 3D cell culture and organoid systems hinders their broader adoption in regulated drug screening and safety assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Culture Market |
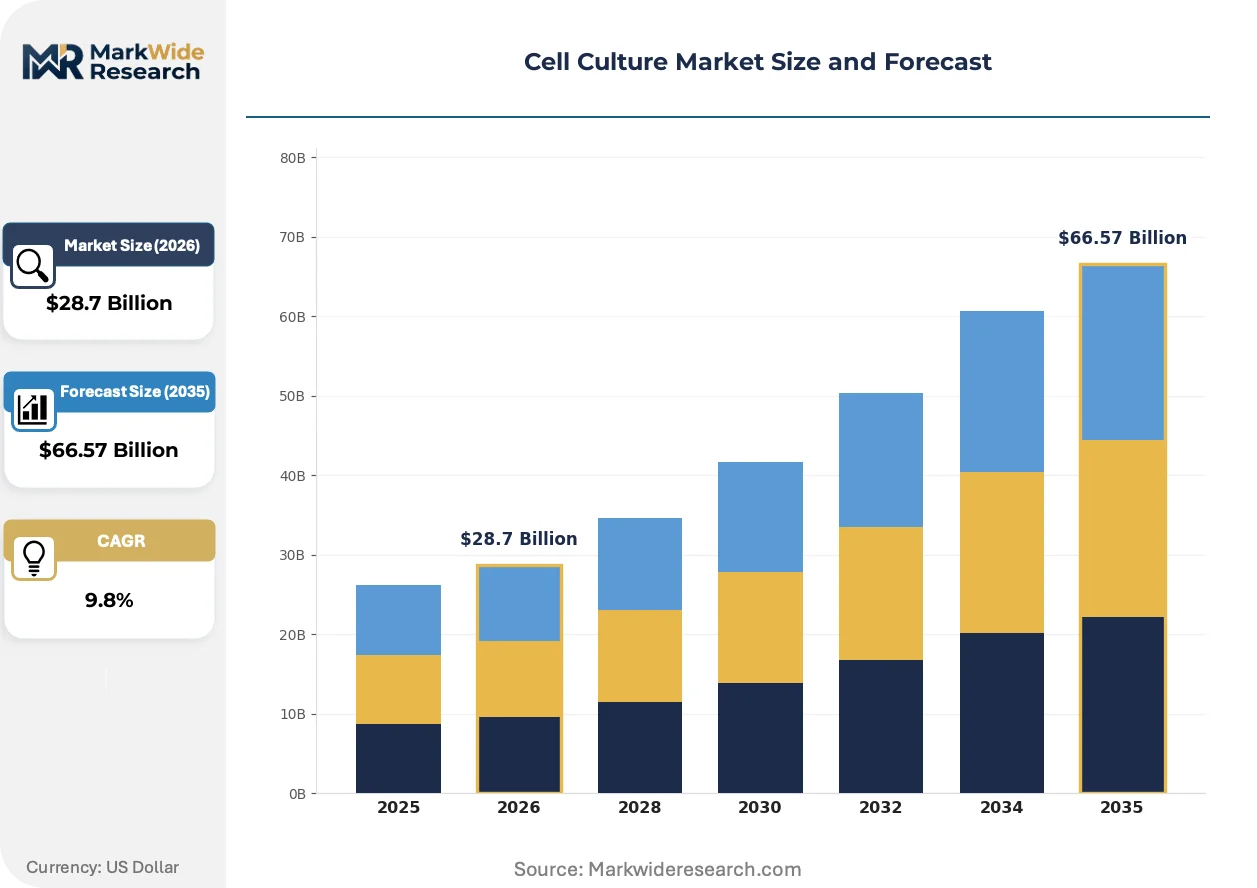
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $66.57 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media, Reagents, Sera, Vessels, Instruments, Others Technology: 2D Culture, 3D Culture, Bioreactor Systems, Microcarrier Culture, Organ-on-Chip, Perfusion Culture Application: Drug Discovery, Toxicology Testing, Vaccine Production, Tissue Engineering, Stem Cell Research, Gene Therapy End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutes, Contract Research Organizations, Diagnostic Labs, Regenerative Medicine Centers |
| Companies Covered | Thermo Fisher Scientific, Danaher, Merck KGaA, Sartorius AG, Corning Incorporated, Lonza Group, Becton, Dickinson and Company, Eppendorf SE, Avantor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Culture Market Strategic Shifts & Innovations
Automation and data integration are fundamentally changing cell culture workflows from a manual art to an engineered science. This evolution supports the industrialization of cell-based manufacturing and enhances the predictive power of preclinical models.
Closed, automated cell processing systems integrate multiple steps like cell isolation, expansion, and harvesting into a single, sterile unit. Biopharmaceutical companies are adopting these systems for cell therapy manufacturing to reduce manual handling errors and ensure process consistency. This technology is consolidating the previously fragmented and labor-intensive workflow into a more streamlined, GMP-compliant industrial process.
The ICH Q5A(R2) guideline on viral safety evaluation of biotechnology products is undergoing revision. This update emphasizes a more holistic risk-based approach, encouraging the use of advanced analytical methods for virus detection over traditional in vivo assays. It affects developers of biologics and cell therapies, prompting investment in next-generation sequencing and other molecular techniques for raw material and final product testing.
A shift from off-the-shelf media to custom-formulated, cell-specific media is becoming standard practice in late-stage process development for biologics. This disrupts the traditional catalog-based sales model, forcing suppliers to build out process development and small-batch manufacturing services. This trend is most visible in the development of biosimilars, where media optimization is critical for matching originator product quality attributes.
Cell Culture Market Segmentation
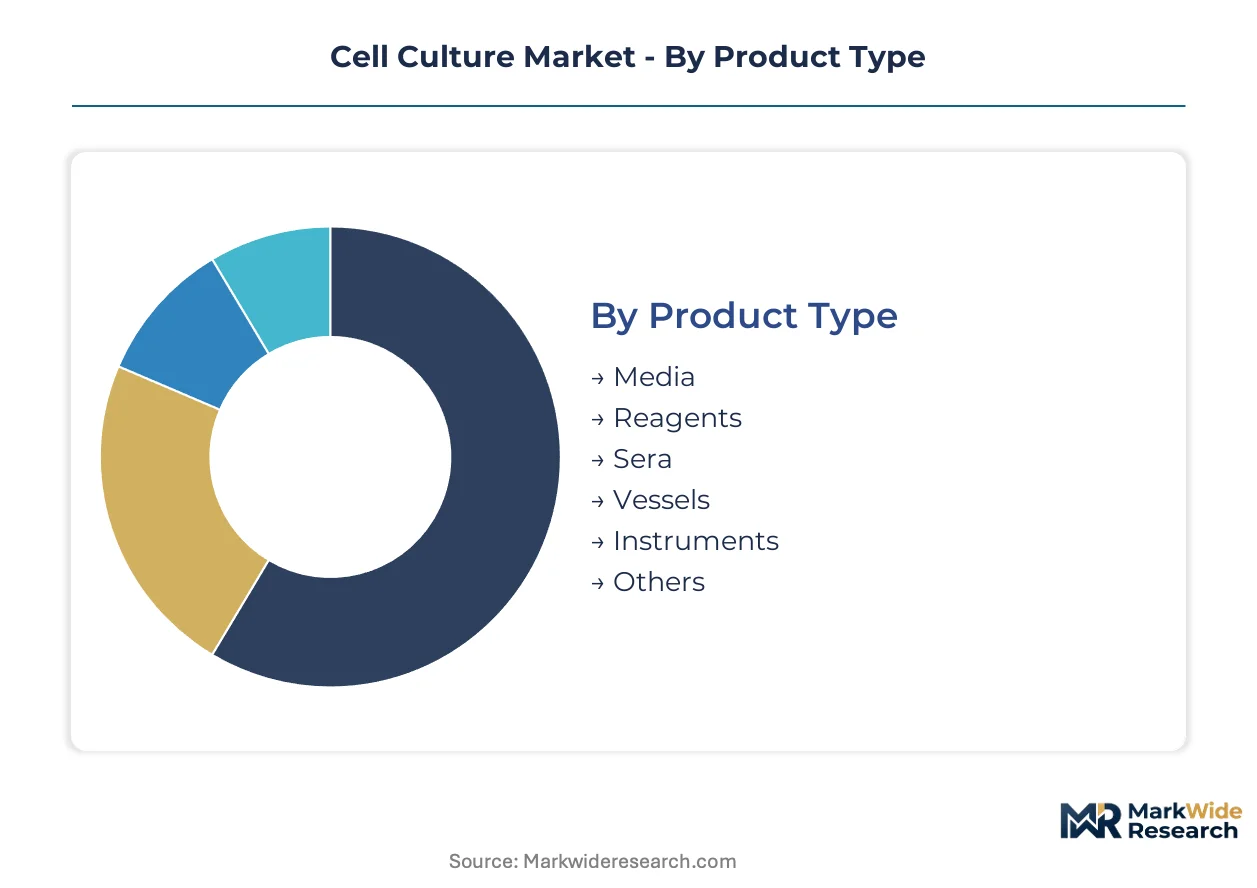
The Cell Culture Market's segmentation illuminates the diverse operational requirements and strategic investment priorities across its value chain. Understanding these distinct segments allows stakeholders to identify areas of concentrated demand and emerging technological shifts. This granular analysis provides clarity on where product innovation and service differentiation will yield the greatest impact.
Product Type:
The capital intensity of cell culture operations varies significantly across product types, with some requiring substantial upfront investment in specialized equipment.
- Media:Chemically defined formulations provide essential nutrients, growth factors, and buffers for cell proliferation and maintenance. Demand for Media concentrates in biopharmaceutical manufacturing, driven by the need for consistent product quality and regulatory compliance.
- Reagents:These include enzymes, antibiotics, and supplements critical for cell isolation, passaging, and cryopreservation. Biopharmaceutical companies and academic research labs drive demand for high-purity reagents to ensure experimental reproducibility.
- Sera:Fetal bovine serum (FBS) and other animal-derived sera supply growth factors and hormones.
- Vessels:Flasks, plates, and dishes provide sterile environments for cell growth in laboratory settings.
- Instruments:Incubators, centrifuges, and microscopes are essential for maintaining and monitoring cell cultures.
- Others:This category encompasses miscellaneous consumables like filters, pipettes, and cryovials.
Most installed capacity flows through Media. Expansion is steepest in Reagents.
Technology:
Cell culture technology choices are primarily dictated by the specific application, ranging from basic research to complex therapeutic development.
- 3D Culture:These models, including spheroids and organoids, mimic in vivo tissue architecture, providing more physiologically relevant data for drug screening. Demand for these advanced systems is strong in oncology research and toxicology testing, accelerating preclinical development.
- Bioreactor Systems:Large-scale automated vessels support high-density cell growth for industrial biopharmaceutical production, ensuring scalability and process control. Demand for bioreactor solutions is concentrating in vaccine manufacturing and monoclonal antibody production, requiring consistent yields.
- 2D Culture:Traditional monolayer cell growth on flat surfaces remains fundamental for routine laboratory experiments.
- Microcarrier Culture:Cells attach to small beads within bioreactors, increasing surface area for suspension culture.
- Organ-on-Chip:Microfluidic devices simulate organ functions, enabling advanced drug testing and disease modeling.
- Perfusion Culture:Continuous media exchange in bioreactors maintains cell viability and productivity over extended periods.
The largest volume uptake occurs in 2D Culture, while 3D Culture shows the most rapid adoption.
Application:
Different applications for cell culture technology directly correlate with the specific research and development needs of various customer types.
- Vaccine Production:Cell culture provides the substrate for viral propagation and antigen generation, crucial for both traditional and novel vaccine development. Demand for cell culture in vaccine manufacturing is strong globally due to pandemic preparedness and routine immunization programs.
- Drug Discovery:Cell-based assays and models are essential for identifying potential therapeutic compounds and understanding disease mechanisms. Pharmaceutical companies drive demand for cell culture in drug discovery to accelerate lead identification and optimization.
- Toxicology Testing:In vitro cell models offer ethical and cost-effective alternatives to animal testing for assessing compound safety.
- Tissue Engineering:Cell culture is fundamental for growing tissues and organs for regenerative medicine and reconstructive surgery.
- Stem Cell Research:Pluripotent and multipotent stem cells are expanded and differentiated for therapeutic and research purposes.
- Gene Therapy:Viral vectors for gene delivery are produced using cell culture platforms, driving demand for specialized media.
Demand for Drug Discovery drives significant revenue. Gene Therapy is gaining market share.
End User:
The maturity of cell culture adoption varies across end-user segments, reflecting their differing regulatory landscapes and operational scales.
- Pharmaceutical Companies:These large enterprises utilize cell culture extensively for drug development, manufacturing biologics, and toxicology screening. Their demand for GMP-compliant media and automated systems is driven by stringent regulatory requirements and large-scale production needs.
- Biotechnology Firms:Often focused on novel therapeutic modalities like cell and gene therapies, these firms require specialized cell culture solutions for research and early-stage production. Demand from biotechnology firms is focusing on advanced 3D culture and custom media development for complex biologics.
- Academic Institutes:Universities and research centers use cell culture for fundamental biological studies and early-stage scientific discovery.
- Contract Research Organizations:CROs provide cell culture services for drug screening and preclinical testing to pharmaceutical clients.
- Diagnostic Labs:Cell culture is employed for viral diagnostics, pathogen isolation, and certain genetic testing applications.
- Regenerative Medicine Centers:These facilities focus on culturing cells for therapeutic applications, including tissue repair and organ regeneration.
The largest procurement budgets reside with Pharmaceutical Companies. Regenerative Medicine Centers exhibit the highest growth in research investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors a significant portion of cell culture market demand, driven by its expansive biotechnology and pharmaceutical research base. This region benefits from substantial investment in biopharmaceutical manufacturing and advanced therapeutic development. Global biomanufacturing hubs are emerging across several key countries.
United States
United States biopharmaceutical manufacturing drives substantial demand for cell culture media and reagents. The US FDA's RMAT designation actively accelerates novel cell therapy development, stimulating research investment. The Boston-Cambridge biotech cluster, alongside California's Bay Area, pioneers advanced 3D culture models and organ-on-chip technologies.
Germany
Germany's robust biopharmaceutical production and extensive academic research fuel consistent cell culture demand. The European Medicines Agency (EMA) guidelines heavily influence Good Manufacturing Practice (GMP) standards for materials. Biotech parks around Munich and Heidelberg concentrate significant cell therapy research and bioprocessing innovation.
China
China's expanding vaccine production and aggressive biosimilar development programs generate high cell culture volumes. The NMPA's strengthening regulations for biologics ensure product safety and consistency. Major biopharma clusters in Shanghai and Suzhou are rapidly expanding manufacturing capacity for cell-based products.
India
India's growing biopharmaceutical sector, particularly in vaccine manufacturing, increases demand for cell culture media. The Indian government's PLI scheme for pharmaceuticals creates opportunities for localized media production. Hyderabad and Bengaluru are emerging as significant biomanufacturing hubs, attracting investment in cell culture technologies.
Japan
Japan's focus on regenerative medicine and advanced biopharmaceutical research sustains high-value cell culture demand. The PMDA expedites the review process for innovative regenerative medical products, fostering development. Research institutions in the Tokyo and Osaka regions lead cutting-edge stem cell research and therapeutic applications.
Cell Culture Market Key Industry Players
Portfolio diversification dominates the current landscape, with established players expanding their offerings to meet complex bioprocessing needs. The cell culture market exhibits a tiered structure, featuring large, integrated solution providers alongside specialized niche players. Strategic archetypes include end-to-end bioprocessing suppliers, custom media developers, and advanced instrument manufacturers catering to diverse research and manufacturing demands. Capacity expansion and strategic partnerships are also central competitive moves, particularly for serving emerging cell and gene therapy applications and expanding geographic reach.
On the premium-tier vector, Thermo Fisher Scientific, a US-based corporation, exemplifies a comprehensive portfolio approach across instruments, media, and reagents. Lonza Group, a Swiss multinational, represents a specialized archetype focused on custom media development and biomanufacturing services for complex biologics. Merck KGaA, a German life science company, anchors its market presence by providing end-to-end bioprocessing solutions, including advanced filtration technologies. These entities collectively shape industry standards and drive innovation across various segments of the cell culture market.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher |
| Merck KGaA |
| Sartorius AG |
| Corning Incorporated |
| Lonza Group |
| Becton, Dickinson and Company |
| Eppendorf SE |
| Avantor |
| Others |
Cost & Logistics Intelligence
Pharmaceutical companies' large-scale procurement of cell culture media and reagents directly influences the market's pricing structure, favoring long-term contracts and value-based agreements over spot purchases. This concentration of buying power shapes supplier strategies, emphasizing consistency and regulatory compliance.
Pricing Analysis
Input cost pass-through significantly impacts cell culture media pricing, particularly for specialized growth factors and GMP-grade raw materials. The dominant pricing model involves contract-based long-term offtake agreements for large biopharmaceutical manufacturers. Price differentiation stems from GMP certification levels and the degree of media customization required for specific cell lines. Pricing softness affects standard, off-the-shelf catalog products due to increased competition. Academic labs and early-stage biotechnology companies exhibit the highest price sensitivity for consumables.
Supply Chain Analysis
Direct sales channels from major suppliers handle the bulk of demand from large biopharmaceutical companies, ensuring technical support and consistent delivery. Geographic supply concentration for critical raw materials like fetal bovine serum (FBS) creates vulnerabilities, with key production regions influencing global availability. Raw material dependencies include specialized amino acids and growth factors. Single-source vulnerability for specific media components represents a structural supply chain risk. Specialized distributors serve smaller research institutions and niche biotechnology firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell culture market is a stable compounder, driven by the expanding biopharmaceutical pipeline and continuous innovation in therapeutic modalities.
For Market Incumbents: Anticipate continued demand for integrated, end-to-end bioprocessing solutions by diversifying product portfolios across instruments, media, and services. Invest in R&D for advanced 3D culture technologies to counter the threat from specialized niche players. Deepen vertical integration into critical raw material supply chains to mitigate geopolitical supply chain vulnerability. Reinforce GMP-compliant manufacturing capabilities to maintain leadership in regulated markets.
For New Entrants and Emerging Players: Enter via specialized technology niches such as organ-on-chip systems or AI-powered process optimization tools. The most penetrable segment remains early-stage biotechnology firms requiring custom media development for novel biologics. A strong go-to-market angle involves offering highly customized, cell-specific media formulations with rapid development cycles. Focus on solutions that address the lack of standardization in complex 3D models.
For Investors and Strategic Acquirers: Biopharmaceutical and life science conglomerates are the most active acquirers in this space, seeking to consolidate capabilities and expand market reach. The market presents strong long-term viability over the next 5-10 years, supported by ongoing therapeutic innovation. Target acquisition archetypes include specialized developers of 3D culture platforms or companies with proprietary chemically defined media formulations. The signal to watch is the successful validation of novel cell culture technologies for clinical applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ensures large-scale production of media and reagents for growing biopharmaceutical manufacturing needs. |
| R&D in Custom Media | Addresses the specific requirements of novel cell therapies and biosimilars, enhancing product performance. |
| Strategic Partnerships | Facilitates access to advanced technologies and expands market reach for specialized cell culture products. |
| Automation Integration | Reduces manual handling errors and increases process consistency in cell-based manufacturing workflows. |
| Geographic Market Entry | Captures demand in emerging biomanufacturing hubs like India and China, leveraging local incentives. |
Research Approach
Direct dialogue with biopharmaceutical R&D leads, cell culture scientists, procurement managers, and regulatory affairs specialists informed the qualitative grounding of this analysis. This primary research was validated against extensive secondary data from US FDA filings, EMA guidelines, scientific literature databases, and company annual reports. Both bottom-up market sizing and top-down revenue validation approaches were employed for comprehensive market understanding.
The quantitative model produced market size and growth forecasts across the analysis window, integrating various data points. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected market forces. Biopharmaceutical pipeline growth and 3D culture adoption rates served as key industry-specific forecast inputs.
Inputs from published scientific literature and company disclosures were available through the study window; gaps in comprehensive global raw material production data introduce uncertainty bands for specific components. All forecasts reflect assumptions regarding technological advancements and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Apoptosis Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market