
 Plant Tissue Culture Products Market | 2026-2036
Plant Tissue Culture Products Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Tissue Culture Products Market Insights
Synthetic auxin formulations are recalibrating cost structures in commercial micropropagation as laboratories substitute traditional IBA and NAA sources with stabilized analogues. Syngenta leverages its agrochemical R&D pipeline to integrate proprietary growth regulator portfolios with tissue culture service contracts. HIMEDIA LABORATORIES anchors South Asian supply chains through in-house production of plant tissue culture media and biochemical reagents.
Plant tissue culture products comprise sterile media formulations, explant materials, plant growth regulators, and protectants engineered to support in vitro cellular differentiation and organogenesis under controlled physicochemical conditions; these products enable mass propagation of genetically identical, pathogen-free plantlets for commercial agriculture and germplasm conservation. Media formulations occupy the largest value share due to recurring consumption and formulation complexity, while growth regulators command premium pricing owing to patent-protected synthetic analogues and dosage precision requirements. Micropropagation dominates application volumes as banana, potato, and ornamental producers adopt stage III and stage IV hardening protocols at scale.
India's CDSCO and BIS regulate phytosanitary standards for culture media imports, while the EU REACH framework governs chemical registrations for growth regulators entering European horticulture markets. The USDA and EPA coordinate on virus-indexing protocols that determine market access for exported plantlets. Stakeholders must monitor evolving genome-editing policy intersections with tissue culture, as regulatory clarity on CRISPR-derived explants will reshape product categorization and commercialization pathways.
Market Dynamics
Commercial micropropagation laboratories in Maharashtra and Karnataka are consolidating around automated bioreactor systems, compressing production timelines for virus-free banana and sugarcane plantlets while reshaping supplier relationships for culture media and growth regulators.
Growth Catalysts
- India's PLI scheme for agriculture biotechnology:Domestic manufacturing incentives are accelerating in-house production capacity for culture media and biochemical reagents, reducing import dependency for commercial laboratories.
- Orchard and plantation sector expansion:Southeast Asian commercial growers are scaling stage III and stage IV hardening protocols for orchid and ornamental exports, driving recurring consumption of sterile media formulations.
- Synthetic auxin stabilization:Patent-protected analogues are substituting traditional IBA and NAA sources, enabling dosage precision that reduces explant mortality rates in contract tissue culture facilities.
Market Restraints
- Patent-protected growth regulator pricing:Premium positioning of synthetic auxin formulations constrains margin flexibility for mid-scale laboratories dependent on imported biochemical inputs.
- Supply concentration in Western India:Maharashtra and Karnataka dominate domestic culture media manufacturing, creating geographic vulnerability for laboratories in eastern and southern states.
- Phytosanitary certification timelines:CDSCO and BIS import clearance protocols for sterile media introduce procurement lead times that disrupt synchronized micropropagation cycles.
Strategic Opportunities
- Underpenetrated eastern state markets:Odisha and West Bengal horticulture export zones lack proximate contract tissue culture laboratories, creating white space for satellite production facilities.
- CRISPR-derived explant integration:Regulatory clarity on genome-edited plantlets will reshape product categorization, enabling new commercialization pathways for disease-resistant germplasm.
- Direct-to-farmer distribution channels:Digital platforms connecting laboratories with commercial growers are disintermediating traditional agricultural input distributors in Karnataka's banana belt.
Industry Challenges
- Skilled technician scarcity:Aseptic technique proficiency and contamination control expertise remain concentrated in established Maharashtra laboratories, constraining workforce scalability for new entrants.
- Bioreactor capex intensity:Automated liquid culture systems require capital deployment that exceeds balance sheet capacity for tier-2 and tier-3 contract laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Tissue Culture Products Market |
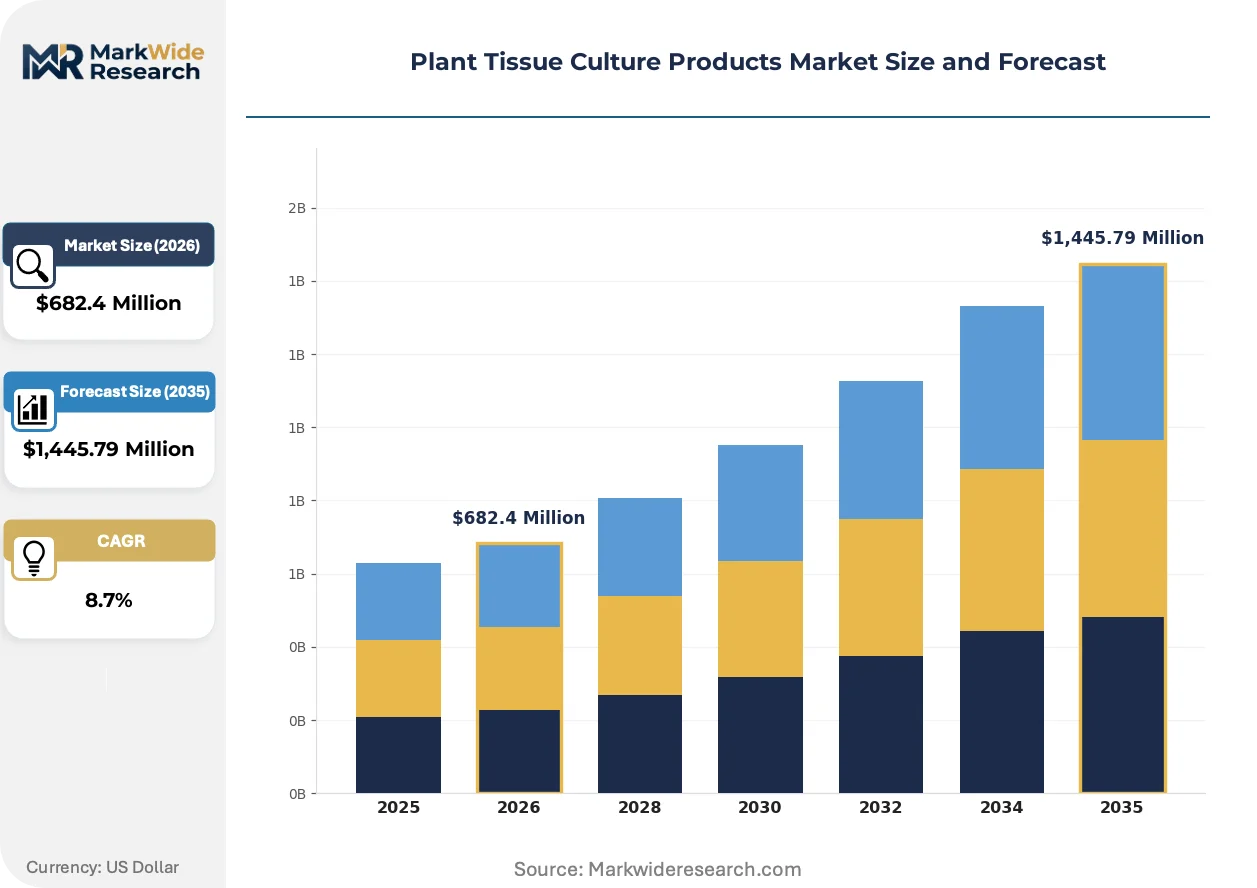
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,445.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media, Explants, Growth Regulators, Protectants Application: Micropropagation, Somatic Embryogenesis, Callus Culture, Organogenesis End User: Research Institutions, Commercial Growers, Tissue Culture Labs, Universities Packaging Type: Flasks, Bags, Jars, Kits |
| Companies Covered | Melford Laboratories, Syngenta, Caisson Labs Inc, Iribov, DP-Deroose Plants, Phytoclone Inc, Duchefa Biochemie, Plant Cell Technology, HIMEDIA LABORATORIES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Tissue Culture Products Market Trends and Innovations
Automation and digital traceability are compressing production cycles while regulatory frameworks scramble to categorize emerging biological inputs, fundamentally altering how commercial laboratories structure quality assurance and supplier relationships.
Automated bioreactor systems with sensor-integrated liquid culture monitoring are modularizing stage II multiplication protocols for banana and potato micropropagation. Commercial laboratories in Karnataka's horticulture export zones are adopting these systems at accelerated pace to meet virus-free planting material contracts. This technology is modularizing the previously linear tissue culture workflow, enabling parallel batch processing that reduces facility footprint requirements.
REACH framework registrations for synthetic growth regulator analogues entering European horticulture markets are tightening documentation requirements for chemical safety profiles. Indian exporters must now coordinate dual compliance with CDSCO domestic standards and ECHA chemical registrations, extending product launch timelines. Growth regulator portfolios face the most pronounced compliance burden, with laboratories reformulating media to reduce regulated substance concentrations.
Certification-driven procurement preferences are displacing price-first purchasing among export-oriented commercial growers. Virus-indexing protocols demanded by USDA-coordinated import inspections are reshaping laboratory selection criteria in Maharashtra's banana production clusters. This behavioral shift concentrates contract awards on laboratories with documented phytosanitary compliance histories, marginalizing uncertified competitors in India's western horticulture belt.
Plant Tissue Culture Products Market Segmentation
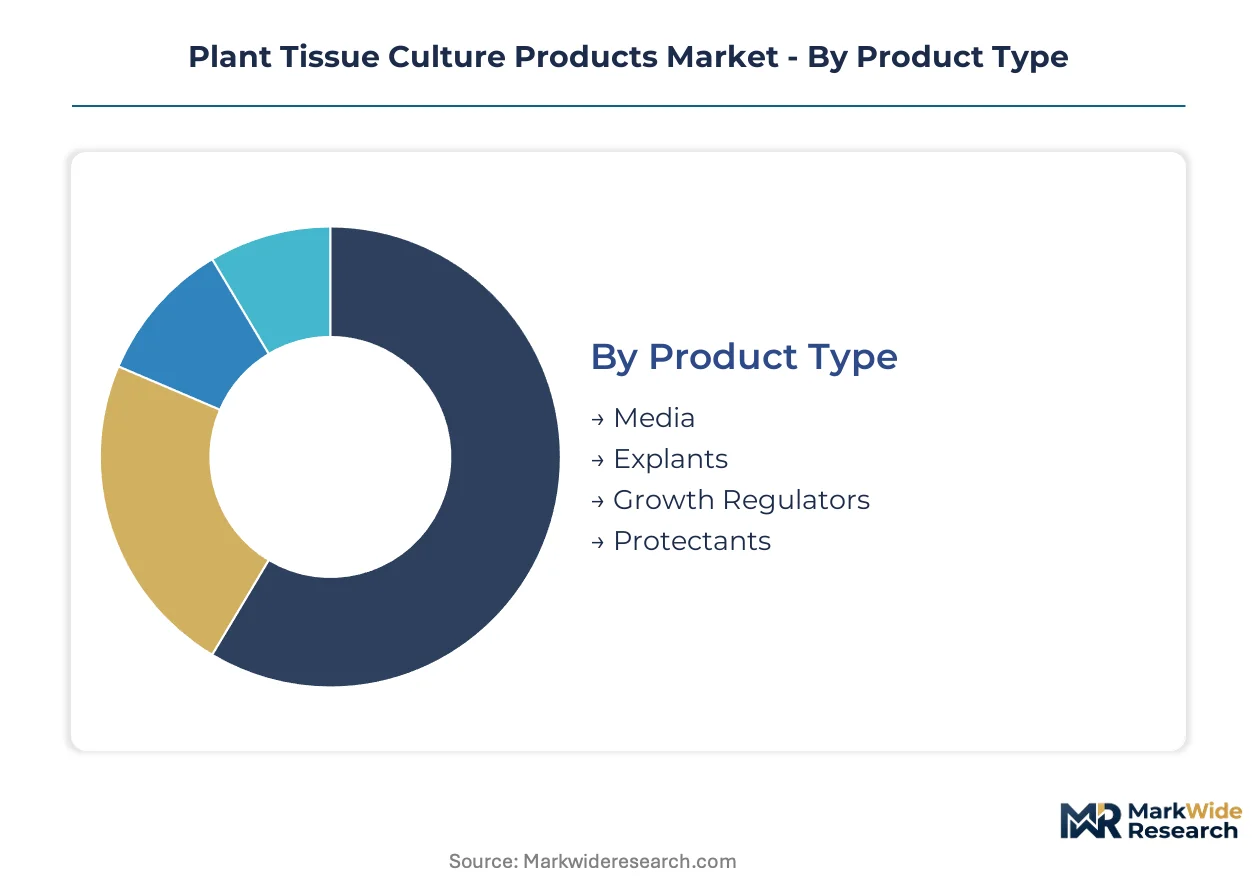
Segmentation in plant tissue culture products reflects divergent cost structures and technical specifications across laboratory workflows. Product categories separate high-volume consumables from precision biochemical inputs, while application segments track the progression from research-grade protocols to industrial-scale propagation systems.
Product Type:
Media formulations dominate procurement volumes through recurring consumption cycles, while growth regulators extract premium margins via patent-protected synthetic analogues.
- Media:Sterile basal salt mixtures with agar-solidified or liquid formulations constitute the largest recurring expenditure for commercial laboratories. Maharashtra and Karnataka contract facilities consume bulk quantities for stage II multiplication and stage III rooting protocols in banana and sugarcane micropropagation.
- Growth Regulators:Patent-protected synthetic auxin analogues command pricing multiples over traditional IBA and NAA sources. Dosage precision requirements in automated bioreactor systems concentrate demand for stabilized formulations that reduce explant mortality.
- Explants:Meristematic tissue segments and nodal cuttings sourced from virus-indexed mother plants.
- Protectants:Antimicrobial and antioxidant additives that extend culture viability during extended subculture intervals.
Today's leader: Media. Tomorrow's challenger: Growth Regulators.
Application:
Commercial scale tilts toward multiplication-intensive protocols, while research applications sustain demand for embryogenic and organogenic systems.
- Micropropagation:Stage I through Stage IV protocols for mass clonal propagation dominate commercial volumes. Southeast Asian orchid exporters and India's banana belt drive adoption of automated liquid culture systems for virus-free plantlet production.
- Somatic Embryogenesis:Suspension culture protocols for synthetic seed development and germplasm cryopreservation. Oil palm and coffee breeding programs in Indonesia and Vietnam apply embryogenic callus induction for genetic conservation.
- Callus Culture:Dedifferentiated cell mass maintenance for secondary metabolite extraction and mutation breeding.
- Organogenesis:Direct shoot and root induction from explant tissues without intervening callus phase.
Micropropagation holds volume dominance. Somatic embryogenesis climbs fastest in plantation crop applications.
End User:
Procurement authority separates bulk consumables buyers from specialized reagent purchasers with divergent specification requirements.
- Commercial Growers:Large-scale banana, potato, and ornamental producers in India's export zones purchase hardened plantlets through contract laboratory arrangements rather than direct media procurement.
- Tissue Culture Labs:Dedicated micropropagation facilities in Maharashtra and Karnataka represent the primary direct purchasers of sterile media formulations and growth regulators.
- Research Institutions:Public agricultural universities and ICAR centers drive demand for experimental-grade biochemical reagents.
- Universities:Undergraduate and postgraduate training programs in plant biotechnology.
Tissue Culture Labs anchor current demand. Commercial Growers are consolidating procurement influence through backward integration.
Packaging Type:
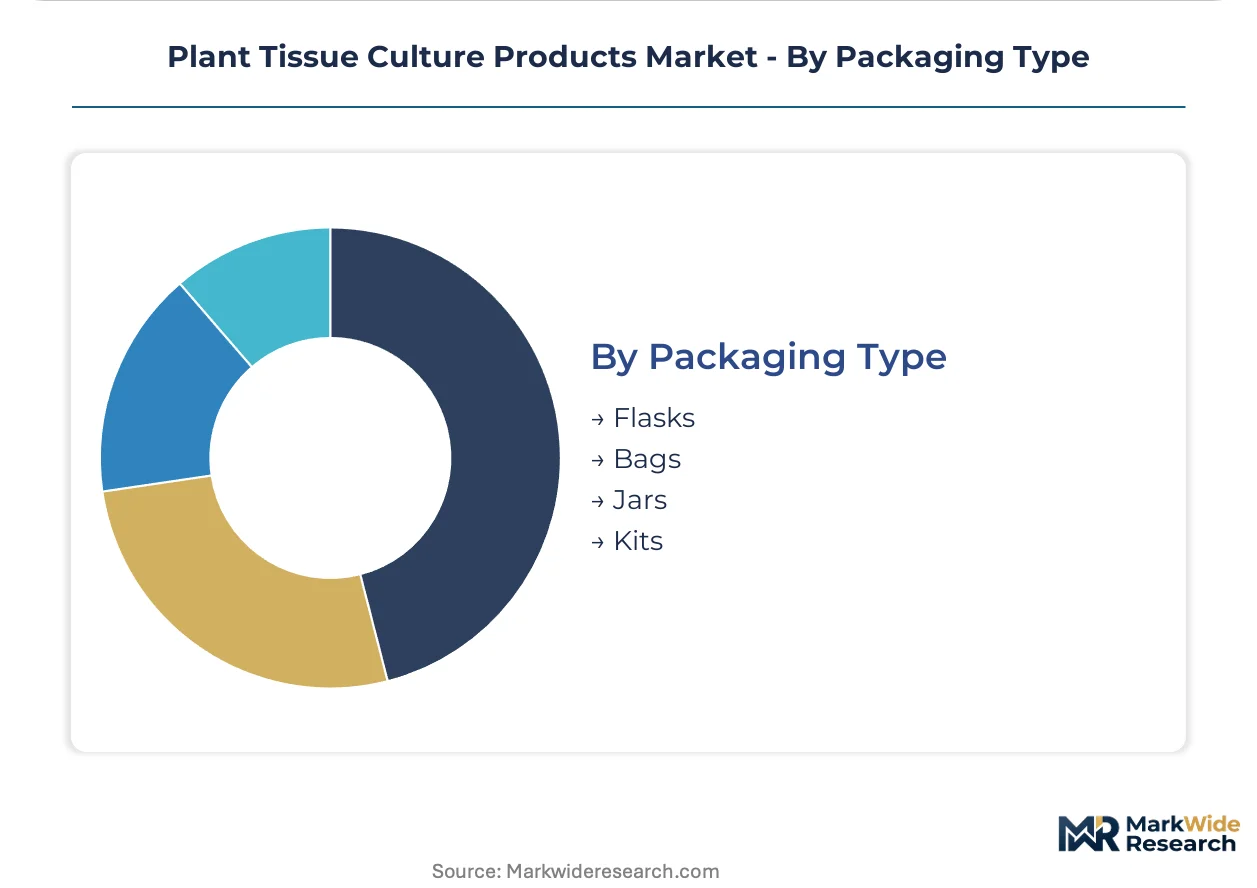
Containment specifications track automation compatibility and contamination risk profiles across laboratory workflows.
- Flasks:Borosilicate and polycarbonate vessels for agar-solidified media storage and manual subculture operations.
- Bags:Flexible film containers for liquid culture media in automated bioreactor systems.
- Jars:Wide-mouth glass containers optimized for stage III and stage IV hardening protocols.
- Kits:Pre-formulated complete media packages with segregated growth regulator aliquots.
Flasks retain installed base dominance. Bags expand most quickly with bioreactor automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Karnataka anchor commercial micropropagation capacity in India, with contract laboratories supplying virus-free planting material to banana and sugarcane export zones. Southeast Asian orchid producers scale stage III hardening protocols. European REACH compliance tightens growth regulator registrations.
India
Commercial banana and sugarcane growers in Maharashtra and Karnataka drive recurring demand for sterile media formulations and synthetic auxin analogues. CDSCO and BIS phytosanitary standards govern culture media imports, introducing procurement lead times for eastern state laboratories. Contract tissue culture facilities in Pune and Bengaluru consolidate around automated bioreactor systems to compress production timelines.
Thailand
Orchid exporters in the central plains and Chiang Mai province scale stage IV hardening protocols for European and Japanese markets. The country's national agricultural biotechnology regulator coordinates with EU REACH documentation requirements for growth regulator residues. Bangkok-based laboratories supply virus-free dendrobium and vanda plantlets to contract farming networks.
Netherlands
Ornamental propagation companies in Westland and Aalsmeer import stabilized synthetic auxin formulations for automated liquid culture systems. ECHA chemical registration protocols under REACH govern growth regulator analogue approvals, extending product launch timelines for Indian exporters. Wageningen University research spin-offs develop embryogenic protocols for plantation crop applications.
United States
Potato seed certification programs in Idaho and Washington state demand virus-indexed plantlets from contract micropropagation laboratories. USDA and EPA coordinate import inspection protocols that determine market access for foreign-sourced explants. California strawberry nurseries adopt stage II multiplication systems to supply protected agriculture operations.
Brazil
Sugarcane breeding programs in São Paulo state apply somatic embryogenesis for elite variety multiplication. ANVISA phytosanitary regulations govern culture media imports for commercial laboratories serving the Center-South ethanol belt. Campinas-based research institutions develop cryopreservation protocols for germplasm conservation.
Plant Tissue Culture Products Market Competitive Landscape
Global majors compete with regional champions across biochemical supply and service contract dimensions. The vendor base separates into three tiers: multinational agrochemical conglomerates with integrated growth regulator portfolios, regional media manufacturers with in-house production capabilities, and specialized contract laboratories with propagation service expertise. Consolidation pressures concentrate among mid-scale laboratories seeking bioreactor automation. Strategic moves center on backward integration into culture media manufacturing and geographic expansion into underpenetrated eastern Indian states.
Within the South Asian biochemical supply tier, HIMEDIA LABORATORIES represents regional manufacturing capacity for culture media and reagents. Among European propagation specialists, Duchefa Biochemie and DP-Deroose Plants exemplify service-contract archetypes with established virus-indexing protocols. Syngenta occupies a position bridging agrochemical R&D with tissue culture service integration.
| Leading Market Players |
|---|
| Melford Laboratories |
| Syngenta |
| Caisson Labs Inc |
| Iribov |
| DP-Deroose Plants |
| Phytoclone Inc |
| Duchefa Biochemie |
| Plant Cell Technology |
| HIMEDIA LABORATORIES |
| Others |
Pricing and Supply Chain Analysis
Aseptic technique proficiency concentrated in Maharashtra laboratories generates labor-cost differentials that widen pricing-tier spreads between certified export-grade facilities and uncertified domestic suppliers. CDSCO import clearance timelines for sterile media formulations compound cost structures for eastern state laboratories lacking proximate manufacturing.
Pricing Analysis
Input-cost pass-through from patent-protected synthetic auxin analogues drives contract-based long-term offtake arrangements between growth regulator suppliers and automated bioreactor operators. Price differentiation separates virus-indexed certification tier from standard domestic grade, with USDA-compliant laboratories commanding premium positioning. Cost compression in mid-scale facilities is intensifying because import dependency for stabilized IBA and NAA sources exposes balance sheets to currency volatility. Commercial growers in Karnataka's banana belt exhibit highest price sensitivity, while European orchid exporters demonstrate lowest sensitivity due to phytosanitary compliance requirements.
Supply Chain Analysis
Certification/qualification gating through CDSCO and BIS phytosanitary standards restricts culture media import channels to approved biochemical manufacturers. Geographic supply concentration centers on India, the Netherlands, and Thailand for sterile media formulations and growth regulator analogues. Raw material dependencies draw from agar-agar sources, basal salt precursors, and synthetic auxin active pharmaceutical ingredients. Single-source vulnerability characterizes patent-protected growth regulator supply, with Syngenta's proprietary portfolios creating concentration risk. Distribution runs through contract laboratory networks serving horticulture export zones rather than direct-to-farmer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with India's PLI scheme for agriculture biotechnology accelerating domestic manufacturing capacity and reshaping competitive access for imported biochemical inputs.
For Market Incumbents: Lock in backward integration into culture media manufacturing to defend margin position against emerging regional champions in South Asia. Secure CDSCO and BIS certification renewals ahead of regulatory tightening on synthetic growth regulator residues. Prioritize workforce development partnerships with Maharashtra agricultural universities to sustain aseptic technique proficiency advantages that constrain new entrant scalability. For New Entrants and Emerging Players: Automated liquid culture monitoring systems present a technology-first wedge for laboratories seeking differentiation in Odisha and West Bengal horticulture export zones. Target satellite production facilities in underpenetrated eastern Indian states lacking proximate contract tissue culture capacity. Pursue direct-to-farmer digital platform partnerships to disintermediate traditional agricultural input distributors in Karnataka's banana belt. For Investors and Strategic Acquirers: Agrochemical conglomerates with integrated growth regulator portfolios represent the most active acquirer in this space, seeking service-contract integration to capture recurring revenue streams. Mid-scale laboratories with bioreactor automation capability and documented phytosanitary compliance histories offer the strongest acquisition target archetype over the medium-term horizon. Monitor regulatory clarity on CRISPR-derived explant commercialization as the critical inflection indicator for germplasm innovation valuations. Deviation in genome-editing policy timelines would shift capital deployment toward conventional micropropagation capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Culture Media Manufacturing | Reduces import dependency for Maharashtra laboratories facing CDSCO clearance delays. |
| Bioreactor Automation Deployment | Compresses production timelines for Karnataka banana exporters meeting USDA virus-indexing protocols. |
| Phytosanitary Certification Investment | Enables market access for Indian laboratories supplying European orchid importers under REACH requirements. |
| Direct-to-Farmer Digital Platform Launch | Disintermediates traditional distributors in Karnataka's contract farming networks. |
| CRISPR Explant Regulatory Pathway Development | Positions laboratories for disease-resistant germplasm commercialization upon policy clarity. |
Research Methodology
Bottom-up tissue culture laboratory modeling reconciled against top-down biochemical supply tracking forms the analytical core of this study. Primary interviews with laboratory operations directors, agrochemical procurement managers, horticulture export zone coordinators, and CDSCO regulatory affairs specialists were combined with secondary validation from BIS standards documentation, CDSCO import clearance records, and ECHA REACH registration databases. Trade flow analysis of sterile media formulations and growth regulator analogues anchored supply-side calibration against end-use consumption patterns in Maharashtra and Karnataka commercial micropropagation facilities.
Input-output matrix framing connects segment-level demand drivers to supply-side capacity constraints across the projection horizon. Segmentation dimensions modeled include product type, application protocol, end-user procurement authority, and packaging automation compatibility. CAGRs were derived through iterative reconciliation of laboratory expansion plans, PLI scheme disbursement schedules, and export contract growth trajectories. Industry-specific forecast inputs incorporate bioreactor adoption rates and phytosanitary certification timelines.
The model holds under stable regulatory enforcement of CDSCO and BIS standards; deviation in genome-editing policy clarity or REACH analogue registration tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Global Qpcr Reagents Market