
 TSG6 Antibody Market | 2026-2036
TSG6 Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
TSG6 Antibody Market Analytics
The EU Green Deal's biopharmaceutical sustainability mandates is consolidating procurement standards for research-grade antibodies across European contract research organizations. Thermo Fisher Scientific leverages its global distribution infrastructure to sustain bulk supply contracts with major academic medical centers. Abcam specializes in recombinant monoclonal validation protocols that differentiate its catalog from polyclonal alternatives in inflammation research workflows.
TSG6 antibody refers to an immunoglobulin reagent targeting tumor necrosis factor-stimulated gene-6, a hyaluronan-binding protein implicated in inflammatory resolution and tissue remodeling, typically produced through hybridoma or recombinant expression systems with protein A/G purification achieving greater than 95% purity. Monoclonal antibodies occupy the premium tier due to batch-to-batch consistency requirements in regulated diagnostic assays, while conjugated antibodies represent the fastest-growing format as multiplex imaging platforms expand in cancer therapy research. Research institutions dominate volume procurement through centralized core facility budgets, whereas pharmaceutical companies generate higher per-unit margins through custom validation services.
FDA oversight of in vitro diagnostic reagents and ISO 13485 quality management systems shape manufacturing documentation requirements for antibodies entering clinical assay supply chains. EMA's In Vitro Diagnostic Regulation and REACH chemical substance frameworks further constrain raw material sourcing and conjugation chemistry options for European suppliers. Stakeholders must monitor evolving companion diagnostic partnership structures between antibody vendors and oncology drug developers to anticipate shifts in specification requirements and long-term supply agreements.
Market Dynamics
NIH-funded inflammation research programs are consolidating antibody procurement around diagnostic-grade certification requirements, forcing suppliers to restructure manufacturing documentation and validation protocols.
Growth Catalysts
- ISO 13485 Certification Mandates:Diagnostic assay developers in the United States now require quality management documentation for all antibody inputs, elevating premium-tier monoclonal demand.
- Multiplex Imaging Platform Expansion:Cancer therapy research workflows are electrifying adoption of conjugated antibody formats across academic medical centers.
- Autoimmune Disease Pipeline Investment:Pharmaceutical companies are scaling TSG6 antibody procurement for preclinical inflammation resolution studies.
Market Restraints
- Hybridoma Cell Line Instability:Traditional monoclonal production systems generate batch-to-batch variability that complicates diagnostic assay validation timelines.
- Protein A/G Purification Input Concentration:Chromatography resin supply chains concentrate among three dominant chemical manufacturers, creating price volatility for 95% purity-grade reagents.
- REACH Chemical Substance Constraints:ECHA frameworks limit conjugation chemistry options for European suppliers developing fluorescent and enzymatic antibody formats.
Strategic Opportunities
- Companion Diagnostic Partnership Structures:Oncology drug developers are negotiating long-term supply agreements with validated antibody vendors ahead of therapeutic approval pathways.
- Recombinant Expression System Migration:Chinese contract manufacturers are electrifying capacity for serum-free monoclonal production, displacing hybridoma-dependent suppliers in cost-sensitive research segments.
- Core Facility Centralization:University procurement offices are consolidating antibody purchasing through shared service budgets, creating volume contract opportunities for catalog suppliers.
Industry Challenges
- Cross-Reactivity Validation Burden:Inflammation research applications require extensive specificity testing against hyaluronan-binding protein families, extending product development cycles.
- FDA In Vitro Diagnostic Reagent Documentation:Clinical assay supply chain entry demands extensive manufacturing traceability records that smaller research-grade suppliers struggle to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TSG6 Antibody Market |
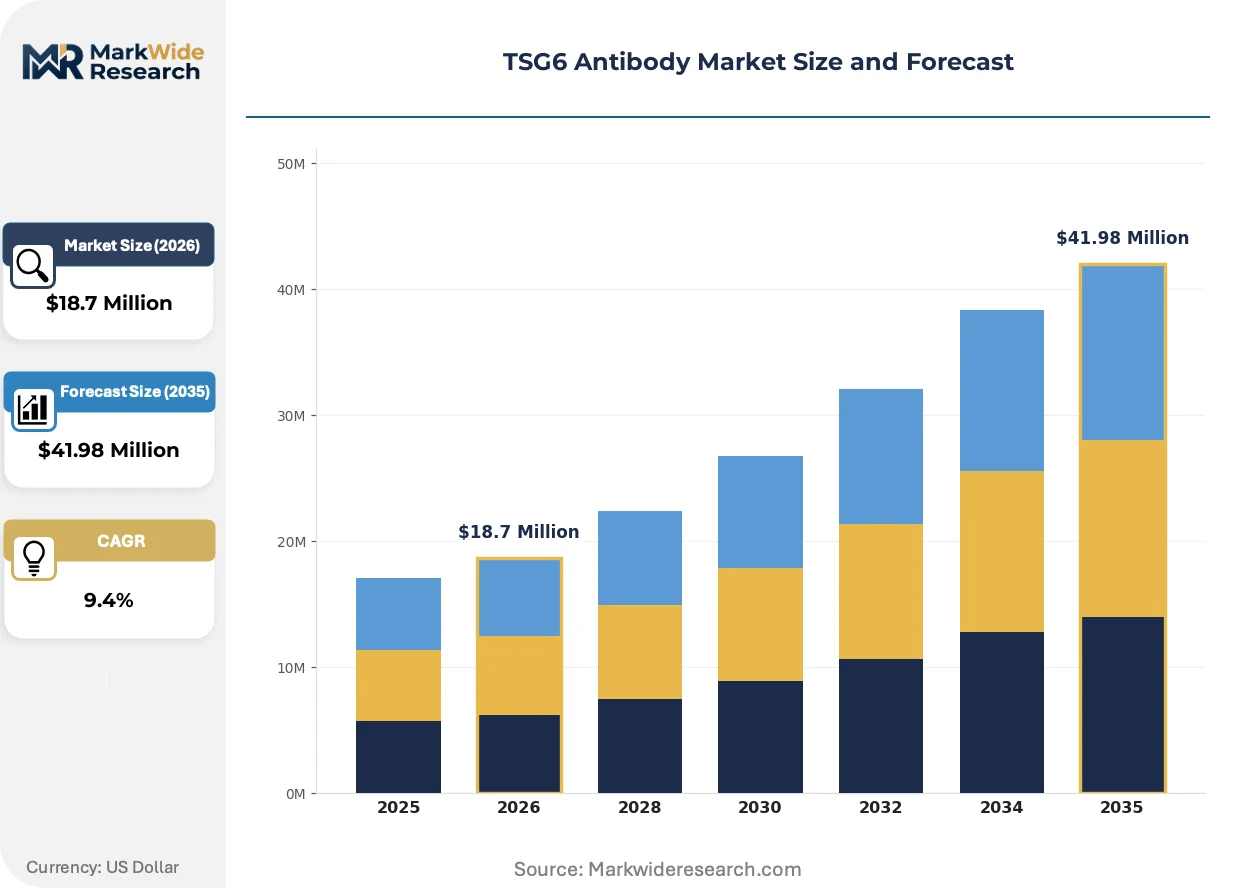
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Conjugated Antibodies, Unconjugated Antibodies Application: Cancer Therapy, Inflammation Research, Autoimmune Disease Research, Diagnostic Assays End User: Pharmaceutical Companies, Research Institutions, Diagnostic Laboratories, Biotech Firms Distribution Channel: Online Retailers, Direct Sales, Distributors, Others |
| Companies Covered | Thermo Fisher Scientific, R&D Systems, Abcam, Bio-Techne, Cell Signaling Technology, Santa Cruz Biotechnology, GenScript, Novus Biologicals, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TSG6 Antibody Market Evolving Landscape
Antibody production workflows are electrifying toward recombinant expression platforms while regulatory documentation requirements tighten across diagnostic supply chains.
Recombinant monoclonal antibody production is electrifying consistency standards for inflammation research reagents. Academic medical centers are adopting these validated formats for longitudinal studies requiring batch reproducibility. The technology is electrifying displacement of polyclonal alternatives in regulated assay development.
EMA's In Vitro Diagnostic Regulation is compressing raw material sourcing flexibility for European contract research organizations. Suppliers must now document conjugation chemistry components under REACH substance frameworks. Diagnostic-grade antibody manufacturers are responding by dual-sourcing resin and dye inputs from certified chemical vendors.
Centralized core facility budgets are consolidating volume procurement decisions at fewer research institutions. Traditional distributor relationships are giving way to direct manufacturer contracts with specialized validation services. This concentration is most visible in United States NIH-funded inflammation research programs where bulk purchasing agreements now specify ISO 13485-certified suppliers exclusively.
TSG6 Antibody Market Segmentation
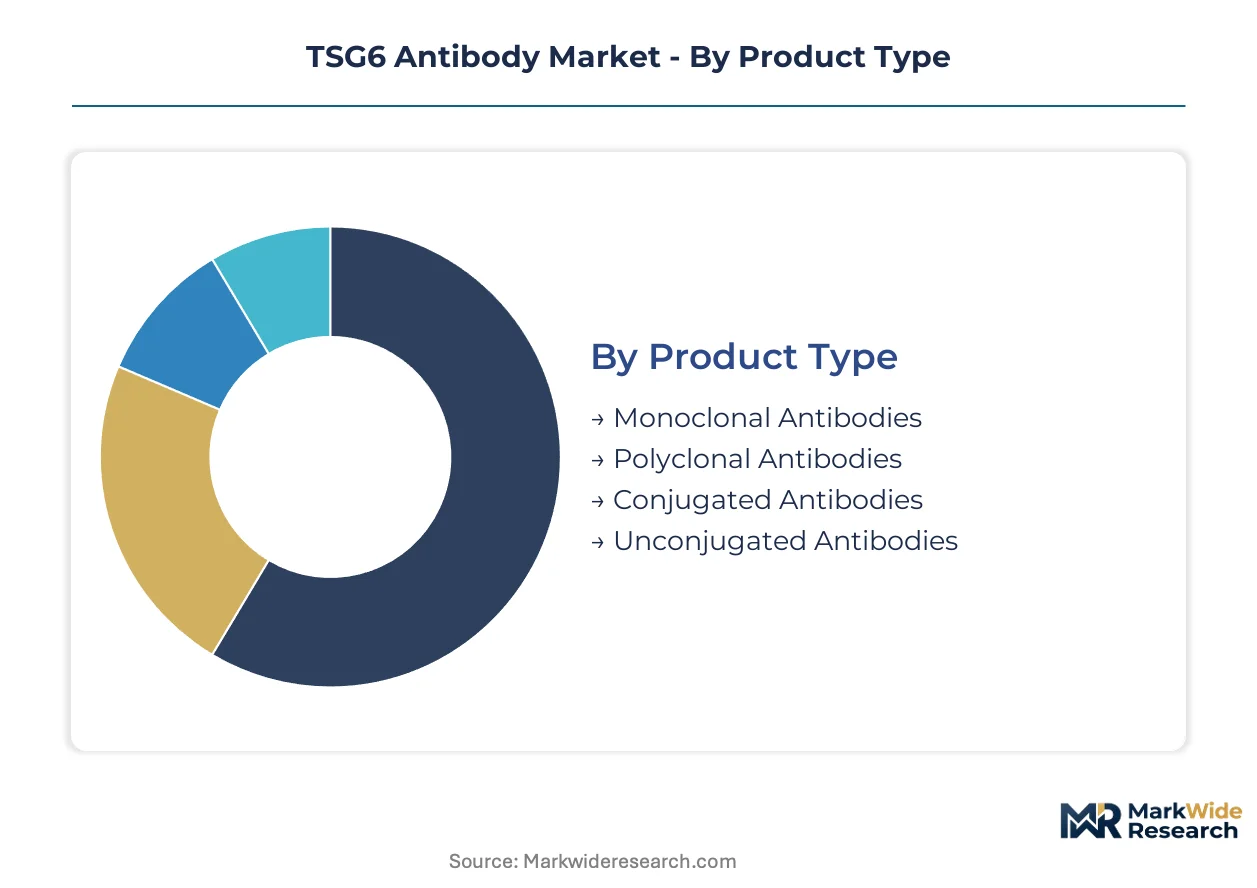
TSG6 antibody procurement decisions pivot on validation requirements, regulatory certification tiers, and workflow integration needs. Pharmaceutical companies prioritize batch consistency for longitudinal studies while diagnostic laboratories demand ISO 13485 documentation for clinical assay deployment.
Product Type:
Pricing stratification across premium, standard, and economy tiers reflects purification grade and reproducibility guarantees rather than raw material costs alone.
- Monoclonal Antibodies:Hybridoma-derived or recombinant immunoglobulins with protein A/G purification achieving 95% purity. United States NIH-funded inflammation programs mandate these for diagnostic-grade assays requiring batch-to-batch consistency documentation.
- Conjugated Antibodies:Fluorescent or enzymatic labels attached via chemical cross-linking for multiplex imaging platforms. Cancer therapy research at academic medical centers drives steepest expansion trajectory as imaging panel complexity increases.
- Polyclonal Antibodies:Multi-epitope reagents from immunized animal sera with broader reactivity profiles. Cost-sensitive screening applications in early-stage biotech discovery programs sustain residual demand despite reproducibility limitations.
- Unconjugated Antibodies:Primary detection reagents requiring secondary antibody amplification. Core facility bulk purchasing concentrates volume in research institutions running standardized Western blot and ELISA workflows.
Volume sits with Monoclonal Antibodies; growth tilts toward Conjugated Antibodies.
Application:
End-use specification intensity varies directly with regulatory proximity to clinical decision-making.
- Inflammation Research:Hyaluronan-binding protein family studies requiring cross-reactivity validation against related TSG family members. NIH program funding in the United States sustains bulk procurement through centralized core facility budgets.
- Diagnostic Assays:FDA-regulated in vitro diagnostic reagents demanding manufacturing traceability records and ISO 13485 quality management documentation. Clinical laboratory networks pay premium multiples for validated antibody inputs.
- Cancer Therapy:Companion diagnostic development partnering antibody vendors with oncology drug developers ahead of therapeutic approval pathways. Multiplex imaging platform expansion electrifies conjugated format specification.
- Autoimmune Disease Research:Preclinical pipeline studies examining TSG6-mediated inflammation resolution mechanisms. Pharmaceutical companies generate higher per-unit margins through custom validation services.
Revenue concentrates in Diagnostic Assays; pipeline investment accelerates fastest in Autoimmune Disease Research.
End User:
Procurement authority centralization determines contract structure and service bundling requirements.
- Research Institutions:University core facilities managing shared service budgets for multiple principal investigators. Direct manufacturer relationships replace traditional distributor channels as validation service demands intensify.
- Pharmaceutical Companies:Preclinical and clinical assay development groups with companion diagnostic partnership negotiation authority. Long-term supply agreements specify exclusive validation protocols and batch reserve commitments.
- Diagnostic Laboratories:Clinical reference labs and hospital systems requiring FDA-compliant reagent documentation. ISO 13485 certification filters supplier eligibility to a narrow tier of documented manufacturers.
- Biotech Firms:Venture-funded discovery operations prioritizing cost efficiency in early-stage screening. Chinese contract manufacturers penetrate this segment with serum-free recombinant production capacity.
Transaction volume dominates Research Institutions; margin expansion concentrates with Pharmaceutical Companies.
Distribution Channel:
Channel selection reflects urgency requirements, technical support needs, and procurement system integration.
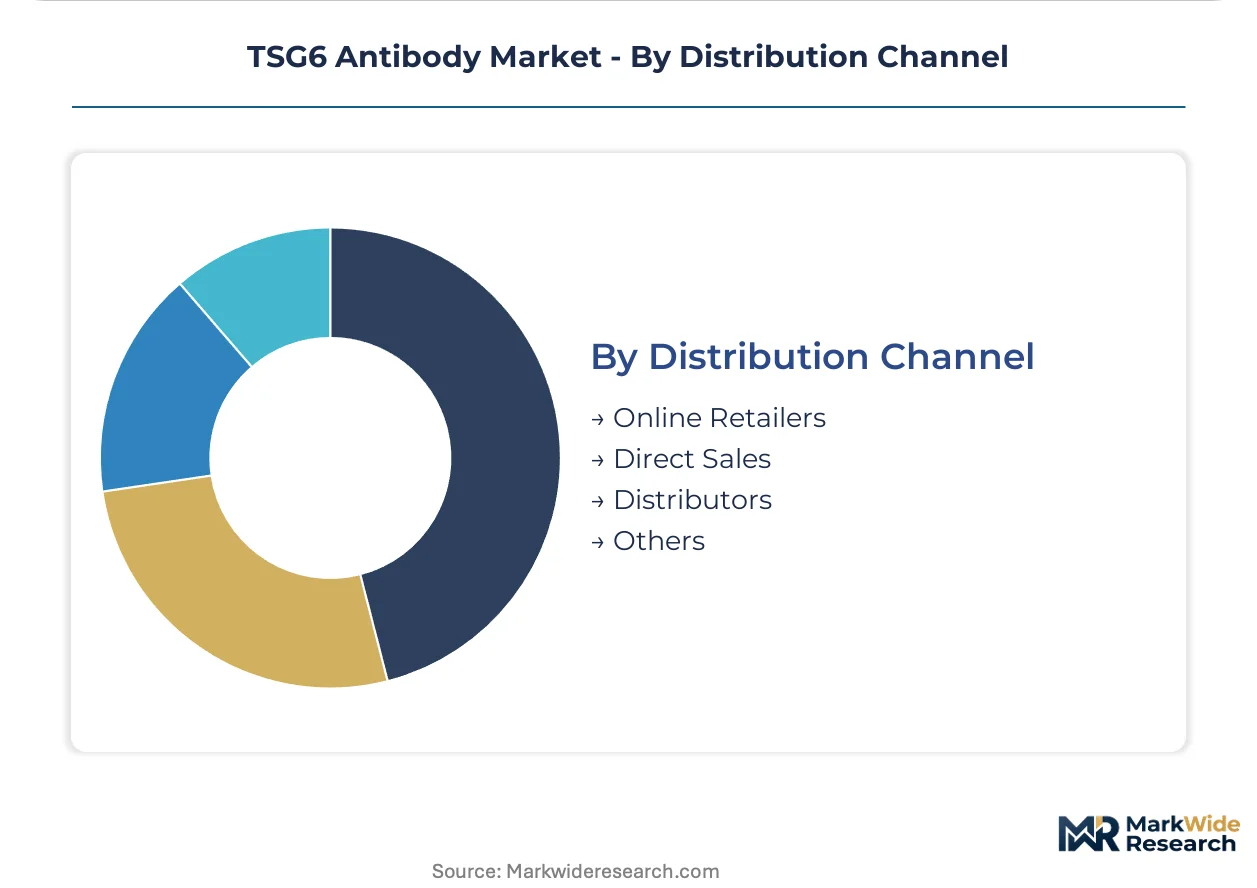
- Direct Sales:Manufacturer field teams managing multi-year supply agreements with diagnostic-grade certification requirements. Thermo Fisher Scientific leverages global infrastructure to sustain bulk contracts with academic medical centers.
- Distributors:Regional inventory hubs serving fragmented research institution procurement with catalog breadth. Traditional relationships erode as core facility centralization consolidates purchasing authority.
- Online Retailers:E-commerce platforms with immediate availability for standard catalog items and credit card purchasing. Small biotech firms and individual research groups prioritize speed over technical consultation.
- Others:Group purchasing organizations and consortium arrangements aggregating demand across multiple institutions. University procurement offices exploit collective bargaining for volume pricing on validated reagents.
Contract value concentrates in Direct Sales; transaction frequency expands fastest through Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biopharmaceutical corridor concentrates TSG6 antibody procurement through NIH-funded inflammation research programs at Harvard-affiliated medical centers and Massachusetts General Hospital core facilities.
United States
NIH-funded inflammation research programs at Boston and San Diego academic medical centers sustain bulk purchasing agreements with ISO 13485-certified suppliers. FDA oversight of in vitro diagnostic reagents mandates manufacturing traceability documentation for clinical assay deployment. The Greater Boston biotech cluster anchors preclinical autoimmune disease pipeline investment from pharmaceutical companies seeking validated antibody inputs.
Germany
Heidelberg and Munich research institutions drive diagnostic-grade antibody procurement for inflammation resolution studies. EMA's In Vitro Diagnostic Regulation compresses raw material sourcing flexibility under REACH chemical substance frameworks. The Baden-Württemberg pharmaceutical manufacturing belt concentrates contract research organization demand for validated monoclonal reagents.
United Kingdom
Cambridge and Oxford university core facilities consolidate antibody purchasing through centralized procurement offices serving multiple principal investigators. MHRA alignment with EMA diagnostic regulations shapes supplier certification requirements for clinical laboratory networks. The London biomedical research corridor generates companion diagnostic partnership negotiations between antibody vendors and oncology drug developers.
China
Shanghai and Beijing contract manufacturers electrify serum-free recombinant monoclonal production capacity for cost-sensitive research segments. NMPA diagnostic reagent regulations tighten quality management documentation requirements for imported antibody inputs. The Yangtze River Delta biopharmaceutical zone concentrates biotech firm demand for economy-tier polyclonal screening reagents.
Japan
Tokyo and Osaka academic medical centers adopt validated recombinant formats for longitudinal inflammation studies requiring batch reproducibility. PMDA oversight of companion diagnostics shapes specification requirements for antibody vendors partnering with oncology drug developers. The Kanto pharmaceutical research cluster sustains premium-tier monoclonal demand for multiplex imaging platform expansion.
TSG6 Antibody Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and validation-service dimensions. The vendor base stratifies between ISO 13485-certified diagnostic-grade suppliers and research-grade catalog providers serving cost-sensitive screening applications. Three archetypes dominate: diversified life science conglomerates with global distribution infrastructure, specialized antibody validation houses with recombinant expression expertise, and contract manufacturers exploiting serum-free production scale. Competitive moves concentrate on companion diagnostic partnership structures and manufacturing documentation upgrades for clinical assay supply chain entry.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies the scale-driven archetype through global distribution infrastructure sustaining bulk supply contracts. Specialized validation houses include Abcam and R&D Systems, occupying positions within the premium-tier recombinant monoclonal segment where batch-to-batch consistency documentation commands pricing multiples. These three anchors represent the structural tension between catalog breadth and custom validation depth across procurement decision frameworks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| R&D Systems |
| Abcam |
| Bio-Techne |
| Cell Signaling Technology |
| Santa Cruz Biotechnology |
| GenScript |
| Novus Biologicals |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Captive purification infrastructure among ISO 13485-certified manufacturers anchors supply positions and sustains pricing power for diagnostic-grade reagents. Protein A/G resin supply concentration among three dominant chemical manufacturers creates input cost rigidity that propagates through antibody pricing tiers, while NIH-funded bulk purchasing agreements in the United States lock volume commitments that insulate premium-tier suppliers from spot-market volatility.
Pricing Analysis
Batch-to-batch consistency documentation anchors value-based pricing for monoclonal antibodies entering FDA-regulated diagnostic workflows. Pricing stratifies across premium, standard, and economy tiers based on certification grade and validation depth rather than raw material costs alone. Cost compression in polyclonal screening reagents intensifies as Chinese contract manufacturers electrify serum-free recombinant capacity for biotech discovery segments. Academic medical centers demonstrate lowest price sensitivity for validated monoclonals, while venture-funded biotech firms drive economy-tier procurement.
Supply Chain Analysis
Domestic-content mandates under EMA's In Vitro Diagnostic Regulation are reshaping raw material sourcing for European contract research organizations. Manufacturing gravity centers on the United States, Germany, and China, with hybridoma cell line repositories and recombinant expression facilities drawing from protein A/G resins, fluorescent dyes, and enzymatic conjugation chemistries. Single-source vulnerability concentrates in chromatography resin supply chains. Distribution runs through direct manufacturer contracts with academic medical centers and diagnostic laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybridoma cell line instability constrains serum-dependent monoclonal capacity, propping pricing for validated recombinant alternatives across diagnostic-grade tiers.
For Market Incumbents: Anticipate margin compression from Chinese contract manufacturers electrifying serum-free recombinant production scale. Defensive consolidation through backward integration into protein A/G resin supply relationships and captive validation service capacity will preserve pricing power. ISO 13485 certification depth remains the critical lever for clinical assay supply chain exclusion. For New Entrants and Emerging Players: Enter via economy-tier polyclonal supply to venture-funded biotech discovery segments where price sensitivity outweighs batch consistency requirements. The Yangtze River Delta biopharmaceutical zone offers the most penetrable geography for cost-positioned entrants. A direct e-commerce go-to-market angle bypasses entrenched distributor relationships at research institutions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking recombinant validation expertise. Long-term viability hinges on companion diagnostic partnership structures with oncology drug developers. Watch for FDA companion diagnostic approval timelines as the inflection signal for valuation step-ups in validated antibody vendors.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Diagnostic-grade documentation unlocks NIH-funded bulk purchasing agreements at academic medical centers. |
| Recombinant Expression Migration | Serum-free monoclonal production displaces hybridoma-dependent suppliers in cost-sensitive research segments. |
| Companion Diagnostic Partnership | Long-term supply agreements with oncology drug developers secure revenue visibility ahead of therapeutic approvals. |
| Core Facility Direct Contracting | Centralized university procurement offices consolidate volume purchasing through shared service budgets. |
| Dual-Sourcing Chemistry Inputs | REACH-compliant resin and dye sourcing preserves European market access under EMA substance frameworks. |
Research Methodology
Document review covered FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance, NIH RePORTER grant databases, and ISO 13485 certification registries, complemented by interviews with antibody manufacturing directors, diagnostic assay development leads, university core facility managers, pharmaceutical preclinical procurement officers, and contract research organization sourcing executives. Secondary validation drew from ClinicalTrials.gov antibody reagent specifications, SEC 10-K life science segment disclosures, and customs trade data for chromatography resin imports. Bottom-up volume estimates triangulated against top-down market sizing from procurement spend analysis.
Historical pricing trajectories cross-referenced against expert panel input on certification cost structures and resin input inflation. Segmentation modeling spanned product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from weighted scenario analysis incorporating NIH funding appropriation trends, EMA regulatory implementation timelines, and Chinese biopharmaceutical capacity expansion announcements. Forecast inputs included companion diagnostic partnership pipeline tracking and academic medical center core facility budget allocations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hybridoma cell line contamination events or REACH chemical substance restriction expansions. Assumptions reflect current regulatory frameworks and funding appropriation levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Global Bioprocess Validation Market