
 Custom Assays Market | 2026-2036
Custom Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Assays Market Analysis
Multiplexed detection architecture is tilting custom assay development away from single-analyte formats toward high-throughput panel configurations. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to dominate workflow standardization across clinical and research segments. QIAGEN anchors its position through bioinformatics-linked assay design, while Charles River Laboratories competes on regulatory-compliant GLP validation services for preclinical programs.
Custom assays comprise laboratory-developed or contract-manufactured biochemical protocols configured to measure specific analytes, typically achieving detection sensitivities in the picogram-per-milliliter range through optimized antibody-antigen binding or nucleic acid hybridization chemistry. Their primary commercial purpose centers on generating proprietary data streams for drug candidate selection, companion diagnostic qualification, and environmental contaminant surveillance. Cell-based assays command premium pricing due to complex culture handling and phenotypic readout requirements, while microfluidic assays represent the fastest-expanding product category as miniaturization reduces reagent consumption and turnaround times. Among applications, biomarker identification attracts disproportionate R&D investment because assay validation directly enables regulatory submissions and licensing revenue.
FDA biomarker qualification programs, EPA analytical method validation requirements, and ISO 13485 quality management standards collectively determine market access thresholds and product development timelines for custom assay providers. These frameworks elevate compliance costs but simultaneously create defensible positions for vendors with established regulatory track records. Stakeholders must monitor how evolving FDA guidance on laboratory-developed tests reshapes the boundary between research-use-only and clinically validated assay tiers.
Market Dynamics
Multiplexed detection architecture is compressing development cycles for custom assay providers, forcing single-analyte specialists to reconfigure workflows or exit clinical segments entirely. FDA biomarker qualification guidance accelerates this structural shift by privileging panel-ready validation data in regulatory submissions.
Growth Catalysts
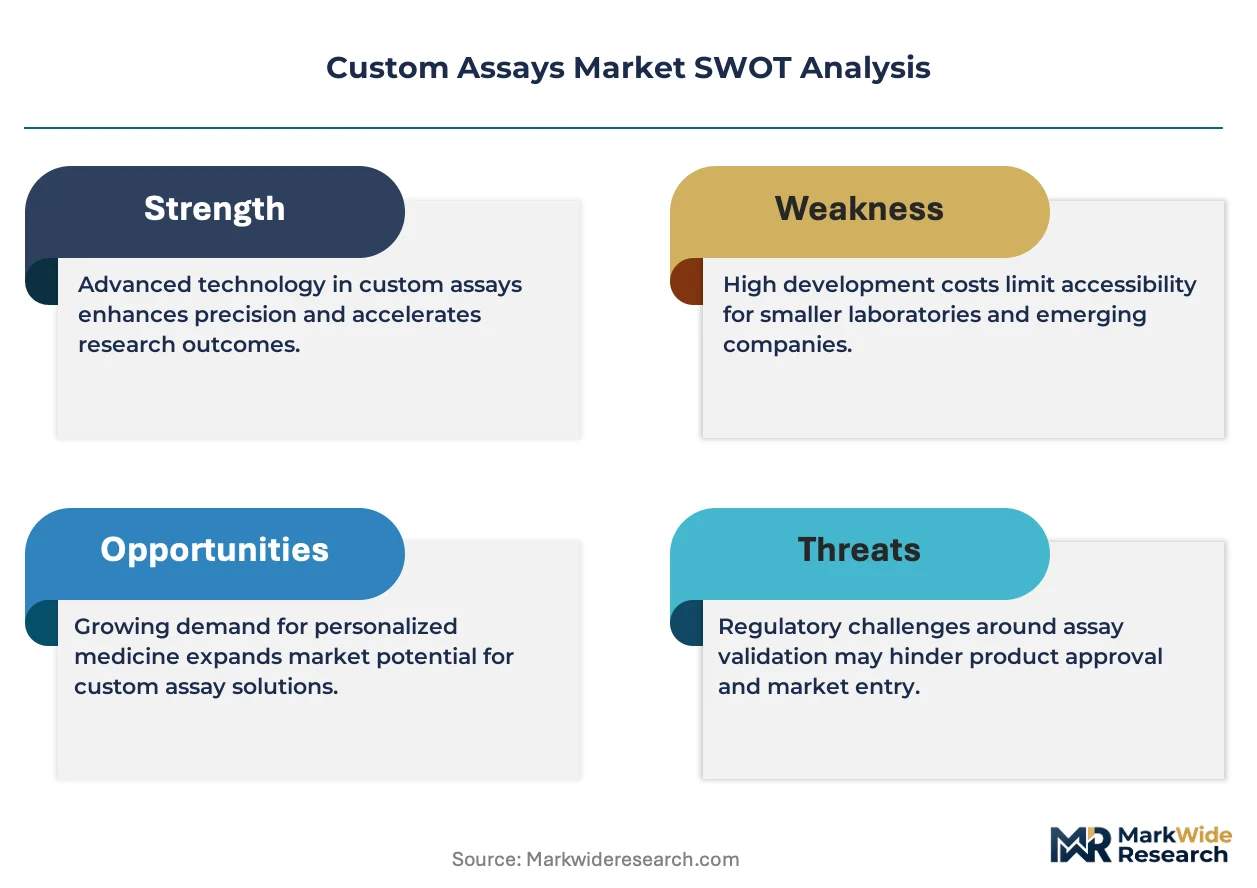
- Companion diagnostic mandates:FDA's expanded guidance on biomarker qualification requires drug sponsors to co-develop assays, pulling contract research spending toward GLP-validated service providers.
- Microfluidic miniaturization:Reduced reagent consumption and turnaround times expand addressable volume in environmental surveillance and point-of-care testing.
- Biotech cluster concentration:Boston and San Francisco anchor outsized contract research demand, concentrating specialized talent pools and accelerating protocol iteration cycles.
Market Restraints
- Antibody supply concentration:Critical binding reagents source from limited GMP-certified manufacturers, exposing assay developers to lot-to-lot variability and extended lead times.
- ISO 13485 compliance costs:Quality management system certification demands sustained audit readiness, elevating fixed overhead for mid-scale providers.
- Cell-based assay complexity:Phenotypic readout requirements and culture handling protocols limit automation penetration, constraining throughput scalability.
Strategic Opportunities
- Asia-Pacific regulatory harmonization:PMDA and NMPA convergence on ICH biomarker standards creates pathway for validated assay transfer into Japan and China clinical trials.
- CRISPR-edited cell lines:Engineered reporter systems enable standardized phenotypic assays, reducing donor variability in immuno-oncology applications.
- Distributed manufacturing networks:Regional CDMO partnerships shorten logistics chains for temperature-sensitive reagent kits serving decentralized clinical sites.
Industry Challenges
- Bioinformatics talent scarcity:Assay design now requires computational biology expertise for panel optimization and data interpretation, outstripping training pipeline output.
- LDT-to-IVD transition friction:FDA guidance reshaping laboratory-developed test boundaries forces research-stage providers to rebuild quality systems for clinical validation tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Assays Market |
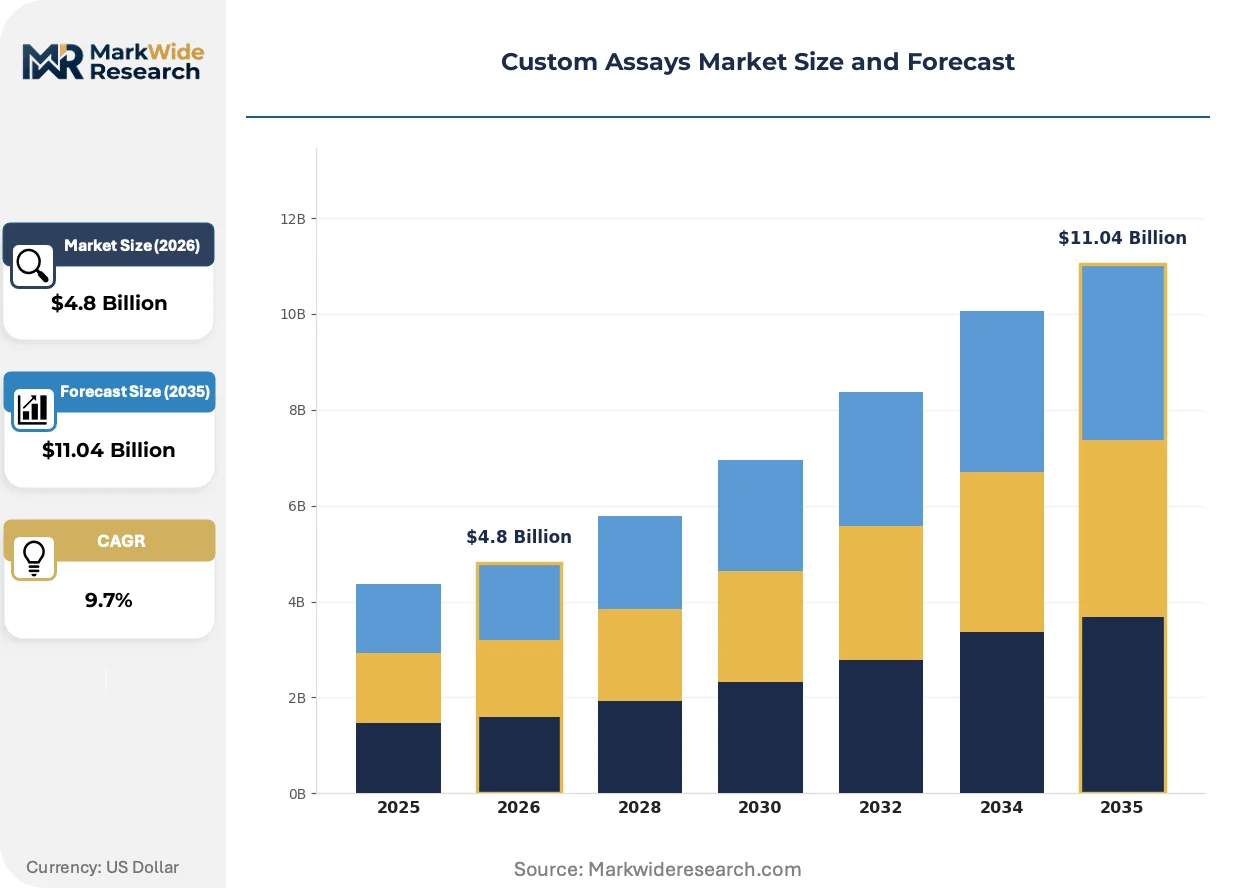
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Microfluidic Assays, Protein Assays, Cell-based Assays Application: Disease Diagnosis, Drug Discovery, Biomarker Identification, Environmental Testing End User: Pharmaceutical Companies, Academic Research Institutions, Diagnostic Laboratories, Biotechnology Firms Technology: Flow Cytometry, Mass Spectrometry, PCR, Sequencing |
| Companies Covered | Luminex Corporation, QIAGEN, Thermo Fisher Scientific, R&D Systems, Bioassay Systems, PerkinElmer, Eurofins Discovery, Charles River Laboratories, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Assays Market Emerging Trajectories
Next-generation sequencing integration is restructuring how custom assays generate quantitative readouts, compressing the boundary between nucleic acid detection and protein-level validation. This convergence demands new skill configurations and instrument partnerships across the vendor base.
Digital PCR platforms is collapsing the sensitivity floor for rare allele detection, enabling picogram-per-milliliter quantification without standard curve dependency. Oncology biomarker programs in the United States adopt these systems fastest, displacing quantitative PCR for liquid biopsy validation where absolute copy number matters. The shift compresses assay development timelines by eliminating cross-platform correlation studies.
EMA's In Vitro Diagnostic Regulation implementation is redrawing conformity assessment requirements for European clinical sites, forcing research-use-only suppliers to engage notified bodies earlier. Commercial laboratories in Germany and France now demand CE-marked components even for preclinical feasibility work. This regulatory friction advantages vendors with established quality management documentation.
Consolidated procurement through integrated delivery networks is concentrating purchasing power among US health systems, squeezing standalone assay developers on price and service bundling. IDN laboratory directors increasingly specify instrument-reagent lock-in contracts that exclude third-party protocol modifications. This channel compression pushes specialized providers toward direct pharmaceutical sponsor relationships.
Custom Assays Market Segmentation
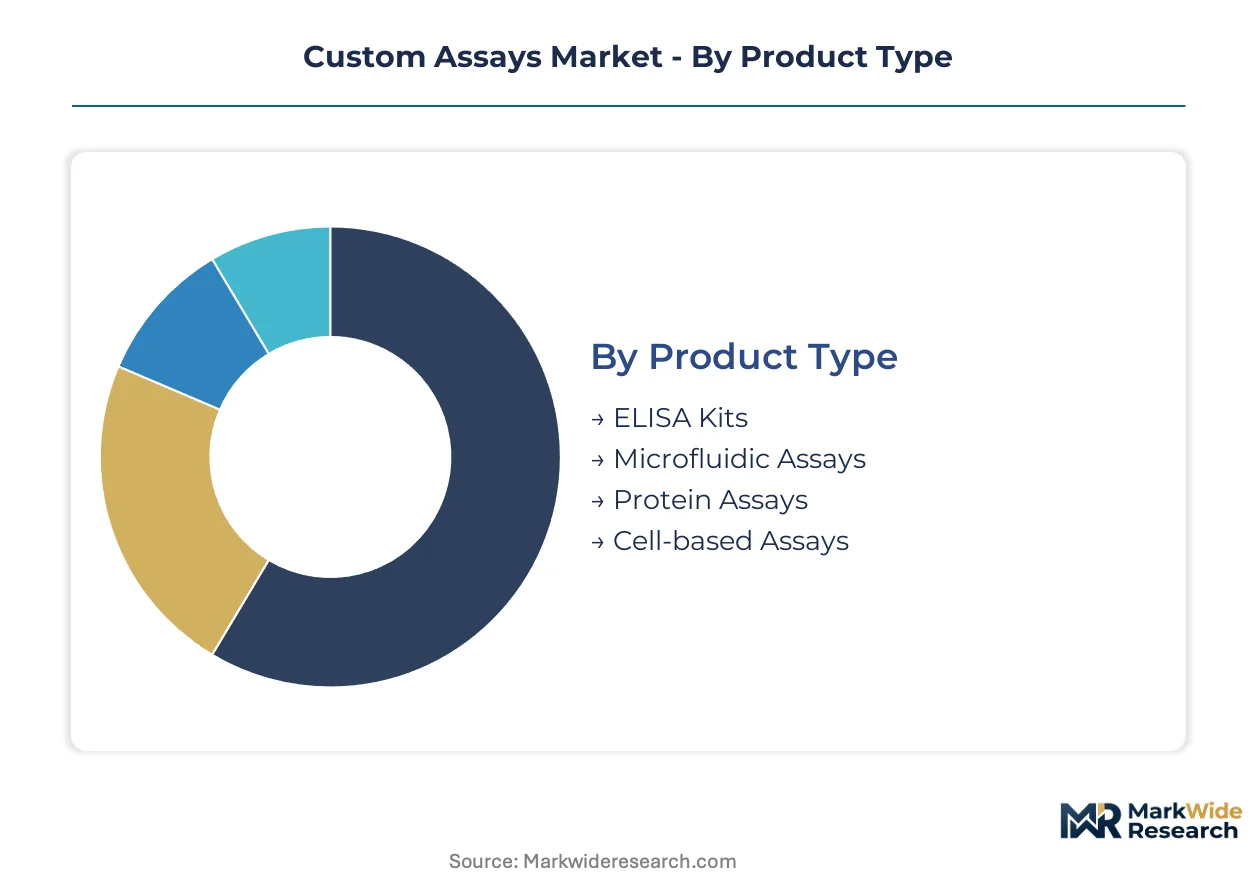
Custom assay architectures vary sharply across detection chemistry, throughput requirements, and regulatory validation tiers. Segmentation reveals where pricing power concentrates and which technical configurations command premium positioning in pharmaceutical versus environmental end-uses.
Product Type:
End-use requirements span single-analyte screening through multiplexed panel deployment, with complexity determining automation feasibility and reagent cost structures.
- Cell-based Assays:Live culture protocols with phenotypic readouts achieve detection sensitivities in the picogram-per-milliliter range for immuno-oncology applications. Boston biotech clusters absorb premium pricing due to complex handling requirements and GLP validation mandates.
- Microfluidic Assays:Miniaturized reaction chambers reduce reagent consumption by orders of magnitude while compressing turnaround times. Environmental surveillance programs in California and point-of-care testing networks drive volume expansion.
- ELISA Kits:Enzyme-linked immunosorbent protocols dominate standardized antibody-antigen binding applications with established regulatory pathways.
- Protein Assays:Quantification methods for total protein concentration support downstream bioprocessing and quality control workflows.
The dominant share belongs to Cell-based Assays, while Microfluidic Assays is closing the gap fastest.
Application:
Revenue concentration aligns with regulatory submission timelines and licensing revenue potential across therapeutic development stages.
- Biomarker Identification:Assay validation directly enables companion diagnostic qualification and FDA submission packages. Pharmaceutical sponsors in the United States direct disproportionate R&D investment toward panel-ready validation data.
- Drug Discovery:High-throughput screening protocols demand rapid iteration cycles and flexible assay configurations. San Francisco Bay Area contract research organizations anchor demand for scalable detection architectures.
- Disease Diagnosis:Clinical validation tiers require ISO 13485 quality systems and documented traceability for patient sample analysis.
- Environmental Testing:EPA analytical method validation requirements govern contaminant surveillance applications with standardized reporting protocols.
Biomarker Identification commands the steepest expansion trajectory as FDA guidance tightens co-development requirements.
End User:
Procurement authority and technical specifications diverge between centralized pharmaceutical sponsors and distributed academic laboratories.
- Pharmaceutical Companies:Outsourced assay development for precision medicine pipelines drives contract research spending toward GLP-validated service providers with established regulatory track records.
- Biotechnology Firms:Venture-backed development programs prioritize rapid protocol iteration and flexible intellectual property arrangements over standardized vendor relationships.
- Academic Research Institutions:Grant-funded investigators favor research-use-only tiers with lower compliance overhead and publication-friendly data terms.
- Diagnostic Laboratories:Integrated delivery network consolidation concentrates purchasing power and favors instrument-reagent bundled contracts.
Pharmaceutical Companies retain the largest procurement volumes, though Biotechnology Firms are gaining share fastest through precision medicine pipelines.
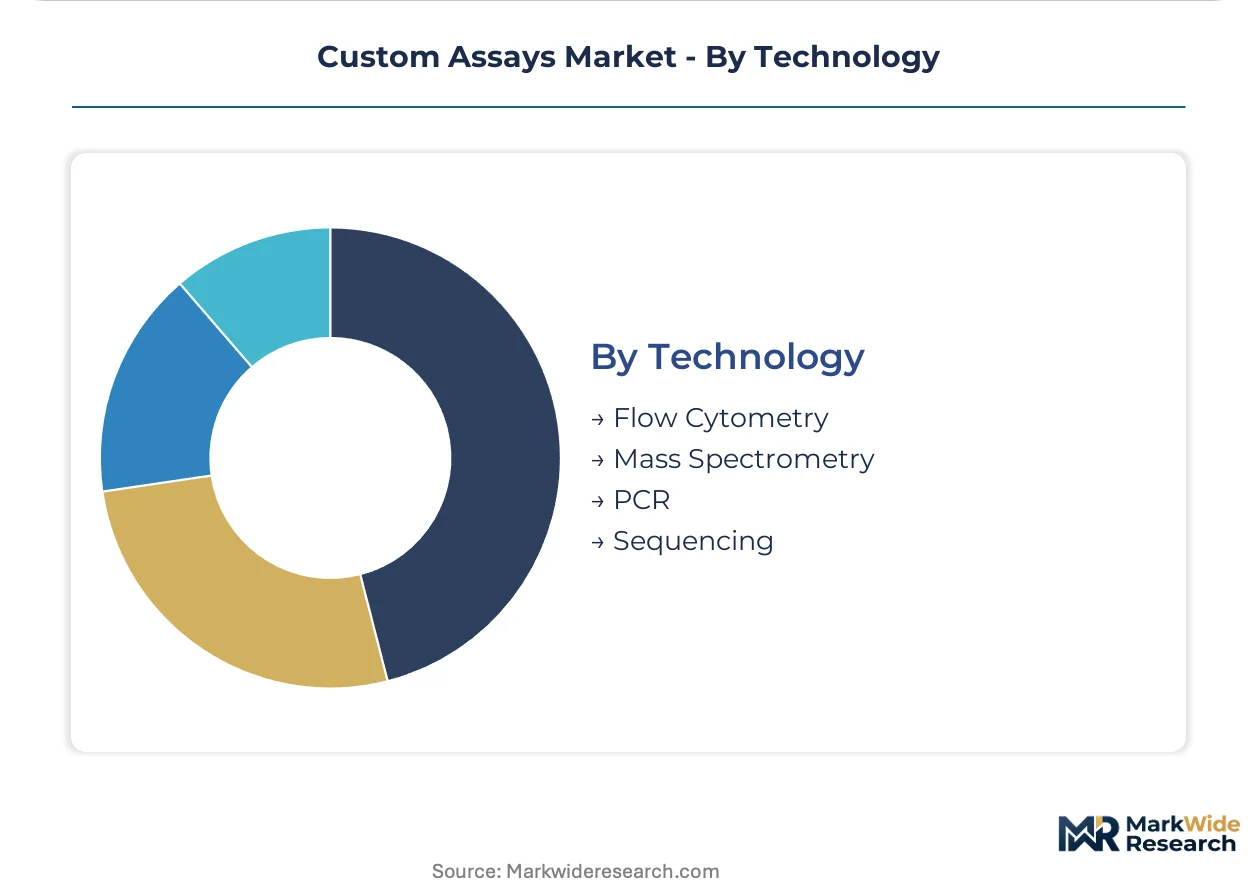
Technology:
Detection modality selection determines sensitivity floors, throughput ceilings, and capital equipment requirements.
- PCR:Polymerase chain reaction amplification remains the workhorse for nucleic acid quantification with established assay design protocols. Digital PCR platforms in United States oncology programs displace quantitative methods for liquid biopsy validation.
- Sequencing:Next-generation integration collapses boundaries between nucleic acid detection and protein-level validation. Next-generation sequencing restructuring demands new vendor skill configurations and instrument partnerships.
- Flow Cytometry:Multiparameter cell analysis supports immunophenotyping and cell sorting applications with single-cell resolution.
- Mass Spectrometry:Label-free detection enables absolute quantification without antibody dependency for metabolite and protein analysis.
PCR maintains installed base dominance, while Sequencing is climbing the fastest as convergence with protein validation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision instrument manufacturers export multiplexed detection platforms to pharmaceutical sponsors in the United States and Japan, anchoring transatlantic trade flows in high-sensitivity assay hardware.
United States
FDA biomarker qualification mandates pull contract research spending toward Boston and San Francisco biotech clusters. The agency's expanded guidance on companion diagnostic co-development accelerates validation requirements for GLP-compliant service providers. Massachusetts and California anchor outsized demand for cell-based assay development supporting precision medicine pipelines.
Germany
EMA In Vitro Diagnostic Regulation implementation forces research-use-only suppliers to engage notified bodies earlier for CE-marked components. Commercial laboratories in Berlin and Munich now demand certified reagents even for preclinical feasibility work. Bavaria's industrial base concentrates quality management documentation capabilities serving European clinical trial networks.
Japan
PMDA convergence on ICH biomarker standards creates regulatory pathways for validated assay transfer into domestic clinical trials. Tokyo and Osaka pharmaceutical sponsors drive adoption of digital PCR platforms for liquid biopsy validation. The Kanto region anchors specialized talent pools for multiplexed panel optimization.
China
NMPA alignment with international biomarker qualification frameworks accelerates local assay validation requirements for imported oncology diagnostics. Shanghai and Beijing biotech parks attract contract research investment from multinational sponsors seeking regulatory-compliant development partners. Yangtze River Delta manufacturing clusters scale microfluidic consumable production.
United Kingdom
MHRA post-Brexit regulatory autonomy reshapes conformity assessment timelines for assay components entering British clinical sites. London and Cambridge life science corridors concentrate bioinformatics talent for panel design and data interpretation. The Golden Triangle anchors venture-backed biotechnology programs prioritizing rapid protocol iteration.
Custom Assays Market Vendor Landscape
On the supply side, the industry is consolidating around integrated instrument-reagent ecosystems and specialized regulatory validation services. Tiered competitive dynamics separate workflow standardization leaders from niche protocol developers. Two strategic archetypes dominate: diversified life science conglomerates leveraging captive hardware platforms, and focused contract research organizations competing on GLP compliance track records. Dominant competitive moves include strategic instrument-reagent bundling contracts and geographic expansion through regional CDMO partnerships.
Within the integrated platform tier, Thermo Fisher Scientific and QIAGEN occupy positions spanning instrument manufacturing through bioinformatics-linked assay design. Charles River Laboratories exemplifies the regulatory-centric archetype, anchoring preclinical validation services with established quality management documentation. These three entities represent contrasting pathways for market positioning—hardware ecosystem control versus compliance-specialized service depth.
| Leading Market Players |
|---|
| Luminex Corporation |
| QIAGEN |
| Thermo Fisher Scientific |
| R&D Systems |
| Bioassay Systems |
| PerkinElmer |
| Eurofins Discovery |
| Charles River Laboratories |
| Promega Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in legacy ELISA manufacturing across China and India is compressing margins for standardized reagent suppliers while simultaneously elevating pricing power for GMP-certified antibody producers in the United States and Germany. This utilization divergence forces assay developers to absorb input cost volatility or migrate toward higher-margin multiplexed panel configurations.
Pricing Analysis
Current-generation digital PCR platforms command three-to-five-fold premiums over prior-generation quantitative PCR systems, while next-generation sequencing-integrated assays sit at the apex of the pricing hierarchy. The dominant model rests on project-based contracting for custom development, with price differentiation driven by GLP certification tier and customization depth. Pricing pressure stems from integrated delivery network procurement consolidation favoring instrument-reagent bundled contracts. Academic research institutions exhibit highest price sensitivity, while pharmaceutical sponsors prioritize regulatory track record over unit cost.
Supply Chain Analysis
Export control regimes restricting CRISPR reagent flows from the United States to Chinese biotechnology firms are fragmenting global supply networks and forcing regional sourcing strategies. Critical binding reagents concentrate in the United States, Germany, and China, with monoclonal antibody production drawing from GMP-certified manufacturers in Massachusetts and Bavaria. Supply chain risk centers on single-source vulnerability for validated cell lines. Distribution runs through regional CDMO partnerships serving decentralized clinical trial sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The custom assays market is approaching a platform-economics inflection where instrument-reagent ecosystem control determines margin capture, with interoperability standards increasingly dictating vendor selection criteria.
For Market Incumbents: Pre-empt emerging entrant disruption in microfluidic assay services by acquiring regional CDMO capabilities in the Asia-Pacific corridor. Anchor defensive positioning through backward integration into GMP-certified antibody manufacturing to secure supply continuity against lot-to-lot variability risks. For New Entrants and Emerging Players: Pursue white-space opportunities in CRISPR-edited cell line standardization for immuno-oncology applications, where phenotypic assay complexity limits incumbent automation penetration. Target biotechnology firms in Boston and San Francisco with flexible intellectual property arrangements and rapid protocol iteration capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sequencing-integrated assay development, favoring scaled platform providers over point-solution specialists. Long-term viability hinges on regulatory validation track records spanning FDA and EMA jurisdictions. Monitor PMDA-NMPA convergence timelines as the signal for Asia-Pacific assay transfer inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Validation Service Expansion | Charles River Laboratories extends preclinical compliance depth into companion diagnostic co-development pipelines. |
| Instrument-Reagent Ecosystem Lock-in | Thermo Fisher Scientific bundles proprietary hardware with customized panel configurations to exclude third-party modifications. |
| Bioinformatics Platform Integration | QIAGEN links assay design software to downstream data interpretation workflows for pharmaceutical sponsors. |
| Regional CDMO Partnership Network | Eurofins Discovery shortens logistics chains for temperature-sensitive reagent kits serving decentralized oncology trials. |
| Digital PCR Platform Adoption | Oncology biomarker programs displace quantitative methods for liquid biopsy validation requiring absolute copy number precision. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA biomarker qualification guidance documents, EPA analytical method validation protocols, and ISO 13485 audit records. Conversations with drug development executives, regulatory affairs leads, contract research procurement managers, and GLP laboratory directors informed demand-side assumptions. Secondary validation drew from ClinicalTrials.gov assay specification databases, SEC 10-K filings of publicly traded life science conglomerates, and EMA In Vitro Diagnostic Regulation implementation notices. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation estimates.
Forecast inputs span product type segmentation across cell-based, microfluidic, ELISA, and protein assay architectures; application tiers from biomarker identification through environmental testing; and technology modalities including PCR, sequencing, flow cytometry, and mass spectrometry. CAGRs were derived from regression analysis against historical contract research spending patterns and projected precision medicine pipeline expansion. Modeling incorporated FDA guidance evolution timelines and ICH biomarker standard harmonization trajectories across regulatory jurisdictions.
Sensitivities concentrate around FDA laboratory-developed test boundary revisions and EMA MDR implementation enforcement intensity. Forecasts reflect documented assumptions regarding biomarker qualification program maturation and companion diagnostic mandate expansion. Material shifts in EPA environmental surveillance funding or PMDA-NMPA regulatory convergence velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market