
 Antibodies Contract Manufacturing Market | 2026-2036
Antibodies Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Antibodies Contract Manufacturing Market Intelligence
Single-use bioreactor systems is recalibrating capital deployment across antibody manufacturing networks. Lonza leverages its Swiss manufacturing base to sustain high-volume monoclonal antibody supply for global pharmaceutical clients. Samsung Biologics anchors capacity expansion in South Korea through purpose-built facilities designed for mammalian cell culture at scale. WuXi Biologics competes on integrated discovery-to-commercial platforms that reduce program transfer risk for biotechnology sponsors.
Antibodies contract manufacturing encompasses the outsourced production of immunoglobulin-based therapeutics using mammalian or microbial expression systems, with upstream bioreactor titers and downstream purification yields defining unit economics. The primary purpose is enabling pharmaceutical and biotechnology developers to access specialized bioprocessing capacity without owning fixed manufacturing assets. Monoclonal antibodies and biosimilars occupy the largest revenue pools given their established clinical validation and reimbursement pathways, while antibody-drug conjugates represent the fastest-growing product category due to complex conjugation chemistry requirements that favor specialist contractors. Process development and fill-and-finish services capture disproportionate margin concentration because these stages determine final product quality and regulatory acceptance.
FDA cGMP guidelines, EMA GMP Annex 2 for biologicals, and ISO 13485 quality management standards collectively govern facility qualification, batch release, and cross-border supply of antibody drug substances. These frameworks create compliance barriers that favor incumbent contract manufacturers with established regulatory inspection histories and validated quality systems. Stakeholders must evaluate capacity reservation strategies against evolving FDA and EMA guidance on continuous manufacturing and real-time release testing.
Market Dynamics
Single-use bioreactor technology is compressing capital deployment timelines across antibody manufacturing networks, enabling sponsors to reserve capacity without committing to multi-year stainless-steel facility builds. This shift redistributes power toward contract manufacturers with modular platform architectures.
Growth Catalysts
- EMA GMP Annex 2 for biologicals:Harmonized quality standards across European manufacturing sites reduce regulatory friction for cross-border antibody supply, accelerating sponsor decisions to outsource production to qualified contractors.
- Antibody-drug conjugate complexity:Specialized conjugation chemistry and linker-payload handling requirements push biotechnology developers toward contractors with validated ADC suites rather than in-house investment.
- United States demand concentration:The world's largest therapeutic antibody market generates sustained capacity reservation pressure, with domestic sponsors prioritizing FDA-inspected contract facilities for commercial supply security.
Market Restraints
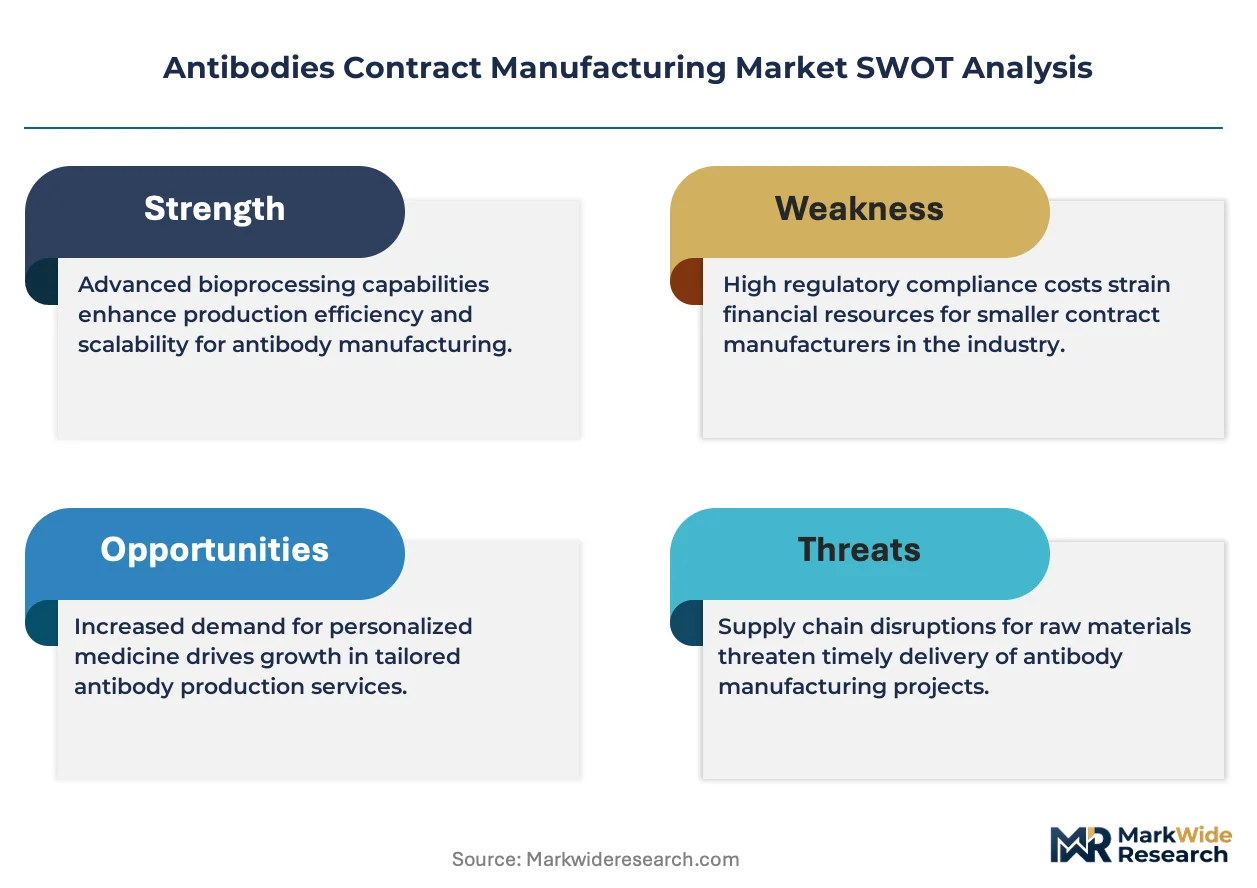
- Plasma-derived raw material volatility:Serum and albumin price swings compress downstream margin predictability for mammalian cell culture processes.
- Swiss supply node concentration:Heavy reliance on Alpine manufacturing corridors creates geographic vulnerability for global monoclonal antibody supply chains.
- Continuous manufacturing guidance uncertainty:Pending FDA position papers on real-time release testing delay sponsor migration from batch-based validation frameworks.
Strategic Opportunities
- Indian biologics manufacturing:CDSCO regulatory pathway maturation and PLI scheme incentives attract capacity investment for cost-sensitive biosimilar production.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with single-use chromatography skids enables 24/7 antibody output with reduced facility footprint.
- Digital supply chain platforms:Blockchain-enabled batch traceability from cell bank to fill-finish addresses sponsor risk management requirements.
Industry Challenges
- Process analytical technology integration:Legacy quality control laboratories struggle to embed real-time monitoring into validated batch release workflows.
- Specialized bioprocess engineering talent:Scarcity of mammalian cell culture scale-up expertise constrains facility expansion timelines across contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibodies Contract Manufacturing Market |
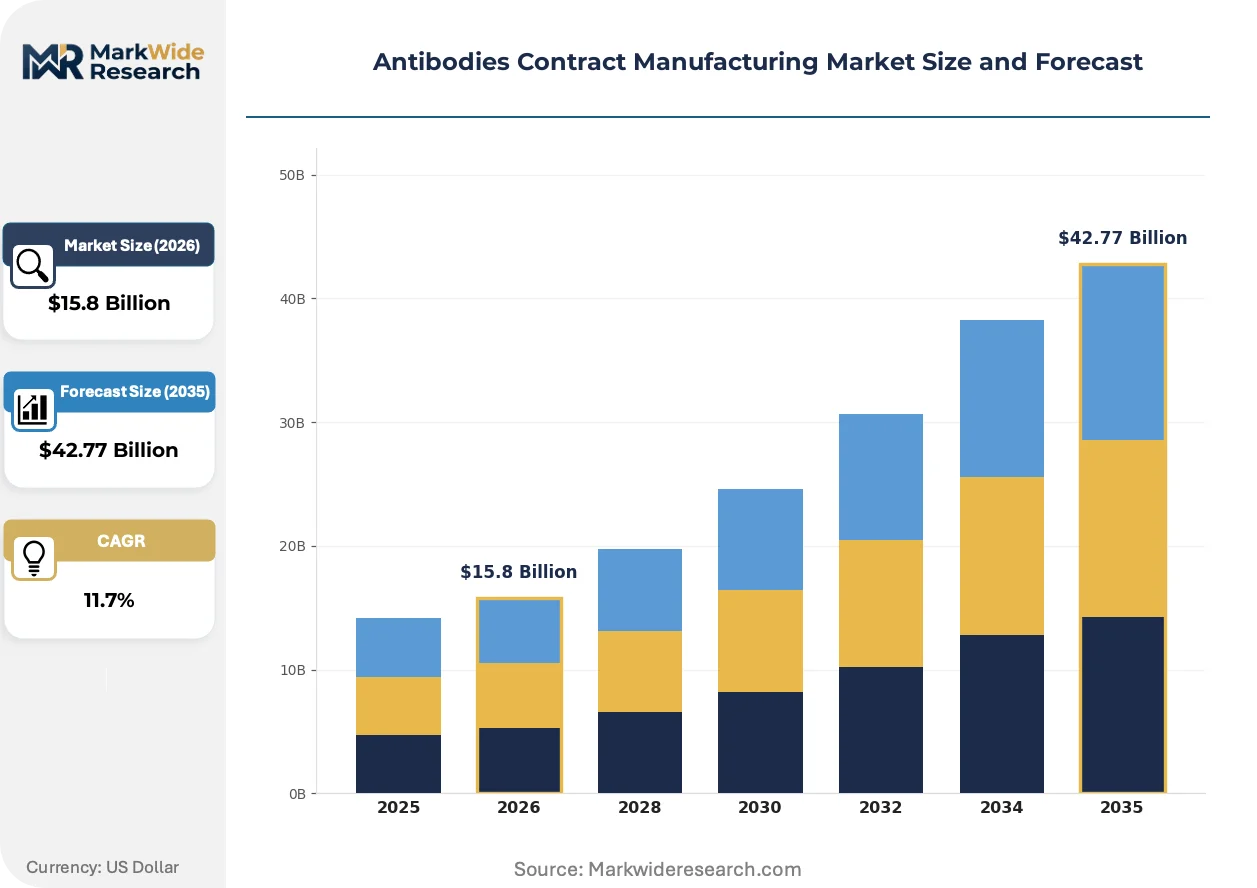
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $42.77 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Biosimilars, Antibody-Drug Conjugates Delivery Mode: Injectable, Infusion, Oral, Transdermal End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Hospitals Service Type: Process Development, Fill & Finish, Quality Control, Regulatory Affairs |
| Companies Covered | Lonza, Samsung Biologics, WuXi Biologics, Charles River Laboratories, AGC Biologics, Catalent, Boehringer Ingelheim, FUJIFILM Diosynth Biotechnologies, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibodies Contract Manufacturing Market Strategic Shifts & Innovations
Antibody contract manufacturing is pivoting toward platform standardization and digital integration, with technology choices increasingly dictated by speed-to-IND requirements rather than legacy process familiarity.
Single-use bioreactor systems is consolidating upstream manufacturing flexibility for biotechnology sponsors seeking rapid campaign turnover. Mid-cap developers with fragmented clinical pipelines now specify disposable stirred-tank configurations as standard, compressing equipment qualification timelines from months to weeks. This technology is consolidating competitive advantage around contractors with validated platform processes that eliminate process transfer risk between discovery and commercial phases.
FDA draft guidance on continuous manufacturing is pressuring established contractors to revalidate legacy batch processes ahead of sponsor demand. Facilities with stainless-steel infrastructure face disproportionate retrofit costs compared to greenfield single-use sites. Mammalian cell culture specialists in Switzerland and South Korea are investing in perfusion-ready suites to preempt regulatory preference shifts.
Sponsor procurement teams are unbundling fill-finish services from drug substance contracts, creating specialized demand for standalone aseptic processing facilities. Biotechnology developers now separately negotiate formulation and packaging, treating these as distinct capability purchases. This pattern is most visible among US-based sponsors with complex delivery device requirements for subcutaneous antibody formulations.
Antibodies Contract Manufacturing Market Segmentation
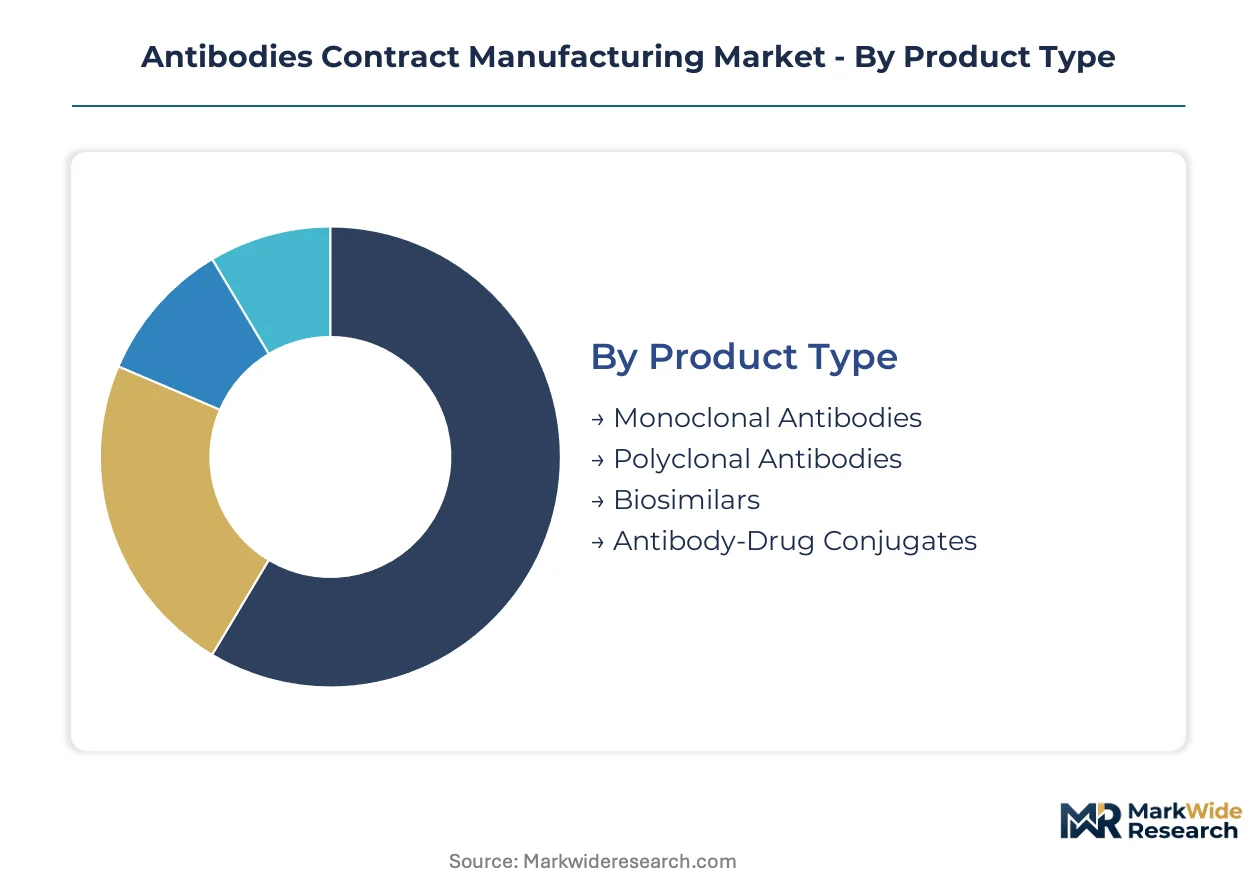
Segmentation in antibody contract manufacturing reveals how capital deployment, technical complexity, and regulatory burden concentrate across distinct service and product categories. Understanding these divisions enables sponsors to match outsourcing strategies with the specific capability requirements of their therapeutic programs.
Product Type:
Capital intensity varies sharply across antibody formats, with conjugation chemistry and cell-line development demanding markedly different facility investments.
- Monoclonal Antibodies:Mammalian cell culture in fed-batch or perfusion bioreactors remains the dominant production platform. United States-based sponsors reserve the majority of stainless-steel and single-use capacity for commercial mAb supply security under FDA cGMP oversight.
- Antibody-Drug Conjugates:Cytotoxic linker-payload handling requires segregated high-containment suites with specialized HVAC and waste management systems. South Korean contractors are expanding ADC-dedicated capacity to capture demand from oncology-focused biotechnology developers.
- Biosimilars:Cost-sensitive production favors high-titer platform processes with minimized resin and media consumption.
- Polyclonal Antibodies:Plasma-derived sourcing constrains margin predictability for hyperimmune globulin manufacturing.
Monoclonal antibodies absorb the bulk of installed capacity; antibody-drug conjugates are expanding most quickly.
Delivery Mode:
Formulation complexity and aseptic processing requirements create divergent margin profiles across administration routes.
- Injectable:Subcutaneous and intravenous formulations dominate antibody therapeutics, requiring sterile fill-finish lines with isolator technology and automated visual inspection. Swiss facilities specialize in high-viscosity monoclonal antibody formulations for prefilled syringe delivery.
- Infusion:Large-volume parenteral bags demand specialized compounding suites with controlled particulate environments. Hospital and clinic networks in the United States drive concentrated demand for outsourced infusion drug product manufacturing.
- Oral:Gastrointestinal stability challenges limit antibody bioavailability through this route.
- Transdermal:Microneedle and patch technologies remain experimental for large-molecule delivery.
Injectable formats command the highest capacity reservation rates; infusion manufacturing is gaining share fastest among hospital-centric sponsors.
End User:
Sponsor size and internal manufacturing footprint determine outsourcing depth and service bundling preferences.
- Pharmaceutical Companies:Large developers with legacy biologics assets selectively outsource overflow capacity and specialized modalities. These sponsors unbundle fill-finish from drug substance contracts to optimize device compatibility and packaging flexibility.
- Biotechnology Firms:Mid-cap and emerging developers rely entirely on contract manufacturers for commercial supply, prioritizing integrated discovery-to-commercial platforms that eliminate technology transfer risk.
- Research Institutions:Academic sponsors generate fragmented, small-batch demand for preclinical and Phase I material.
- Hospitals:Compounding pharmacy requirements for investigational antibodies create niche outsourcing demand.
Pharmaceutical companies commit the largest absolute capacity volumes; biotechnology firms are driving the steepest expansion trajectory in outsourced service adoption.
Service Type:
Margin concentration and talent scarcity vary across the manufacturing value chain, with downstream stages capturing disproportionate value.
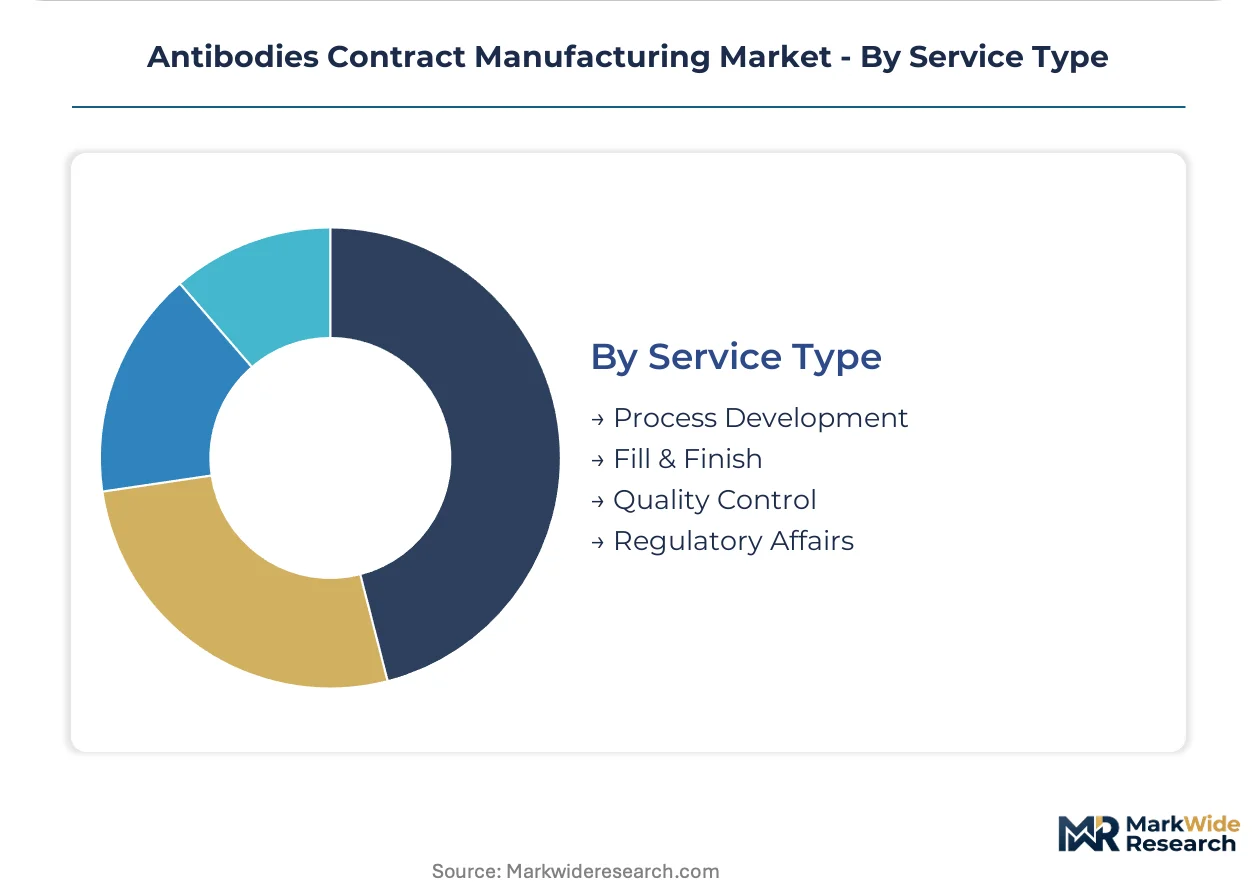
- Process Development:Cell-line engineering, media optimization, and scale-up validation define product quality and regulatory acceptance. Contractors with platform processes for Chinese hamster ovary expression systems command premium pricing from sponsors seeking reduced timeline risk.
- Fill & Finish:Aseptic processing, lyophilization, and device assembly represent the most capacity-constrained segment. United States facilities face particular pressure as sponsors separately negotiate formulation and packaging services.
- Quality Control:Release testing, stability studies, and method validation require specialized analytical instrumentation and regulatory inspection histories.
- Regulatory Affairs:CMC documentation, agency correspondence, and inspection readiness support complete the service portfolio.
Fill & finish operations absorb the bulk of sponsor quality risk attention; process development is expanding most quickly as sponsors front-load manufacturing readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel-Stadt's cantonal tax incentives and Switzerland's patent box regime concentrate high-value antibody manufacturing in the Alpine corridor. This fiscal architecture attracts contract manufacturers seeking operational cost advantages alongside EMA-aligned regulatory pathways.
United States
FDA cGMP inspections drive sponsor preference for domestic fill-finish capacity. The Inflation Reduction Act's biologics pricing provisions accelerate outsourcing decisions as developers seek manufacturing cost predictability. Greater Boston's Kendall Square corridor hosts the densest cluster of sponsor-contractor relationships for early-phase monoclonal antibody programs.
Switzerland
Swissmedic's streamlined biological license procedures reduce time-to-market for commercial antibody supply. Federal tax rulings on royalty income sustain the country's position as a high-margin manufacturing node. The Basel region aggregates Lonza's mammalian cell culture infrastructure with specialized ADC conjugation capabilities.
South Korea
MFDS accelerated approval pathways for biosimilars expand contract manufacturing demand from domestic and Japanese sponsors. Government-designated free economic zones in Songdo offer ten-year corporate tax holidays for biologics investment. Samsung Biologics anchors capacity expansion through purpose-built facilities in Incheon.
Germany
Paul-Ehrlich-Institut oversight of biologicals maintains stringent batch release standards that favor established contractors. Federal Ministry of Health funding for continuous manufacturing research preempts regulatory technology shifts. The Heidelberg-Mannheim biotech corridor concentrates process development talent for mammalian expression systems.
India
CDSCO's biosimilar approval pathway maturation attracts cost-sensitive capacity investment from global sponsors. Production-linked incentive schemes for biopharmaceuticals offset capital deployment risks for greenfield facilities. Hyderabad's Genome Valley clusters contract research organizations with emerging drug substance manufacturers.
Antibodies Contract Manufacturing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning in early-phase services and pure-play manufacturers dominating late-stage commercial supply. The vendor base concentrates around three strategic archetypes: Swiss-based high-containment specialists, Korean scale-driven facilities, and Chinese integrated discovery-to-commercial platforms. Capacity reservation agreements and technology licensing partnerships represent the dominant competitive moves as sponsors seek to lock in manufacturing slots ahead of regulatory milestones.
Within the integrated platform tier, WuXi Biologics exemplifies end-to-end service bundling that reduces technology transfer friction for biotechnology sponsors. Samsung Biologics anchors the scale-driven archetype through its Korean corporate structure and purpose-built mammalian cell culture infrastructure. Lonza occupies a position as the Swiss-based incumbent with established EMA and FDA inspection histories that validate quality system reliability for commercial antibody supply.
| Leading Market Players |
|---|
| Lonza |
| Samsung Biologics |
| WuXi Biologics |
| Charles River Laboratories |
| AGC Biologics |
| Catalent |
| Boehringer Ingelheim |
| FUJIFILM Diosynth Biotechnologies |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Single-use bioreactor adoption is compressing capital barriers for mid-cap biotechnology sponsors while simultaneously concentrating supply power among contractors with validated platform processes and FDA inspection histories. This technology transition rewards early movers with modular capacity configurations, creating pricing premiums for stainless-steel alternatives and squeezing margins for legacy facilities facing retrofit costs.
Pricing Analysis
Volume contracts for commercial monoclonal antibodies absorb capacity at compressed margins, while process development and fill-finish services capture disproportionate value through quality risk concentration. Price differentiation rests on FDA cGMP certification tier and EMA inspection history, with Swiss and South Korean facilities commanding premiums over emerging Indian alternatives. Cost compression in biosimilar manufacturing is intensifying because CDSCO pathway maturation attracts cost-sensitive sponsors to Hyderabad-based contractors. Biotechnology firms with single-asset pipelines exhibit highest price sensitivity; large pharmaceutical companies with portfolio diversification prioritize supply security over unit cost.
Supply Chain Analysis
Facility qualification and regulatory inspection history gate supply access more than geographic proximity, with Switzerland, South Korea, and the United States hosting the preponderance of validated antibody manufacturing nodes. Raw material dependencies draw from Chinese-sourced media components, German-engineered chromatography resins, and US-sourced reference standards for batch release. Single-source vulnerability concentrates in Alpine manufacturing corridors where Lonza anchors global monoclonal antibody supply. Distribution runs through temperature-controlled logistics networks with validated cold-chain documentation for cross-border drug substance transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibodies contract manufacturing is consolidating around platform-standardized specialists with regulatory inspection histories, as pending FDA continuous manufacturing guidance forces capital-intensive revalidation decisions that weaker players cannot absorb.
For Market Incumbents: Hedge against regulatory technology shifts by investing in perfusion-ready single-use suites ahead of formal FDA guidance release. Lock in biotechnology sponsors through integrated discovery-to-commercial platforms that eliminate transfer risk. Prioritize fill-finish capacity expansion in United States locations to capture unbundled procurement demand from device-complex subcutaneous formulations. For New Entrants and Emerging Players: Begin with antibody-drug conjugate conjugation chemistry as the most penetrable white-space segment, where cytotoxic handling requirements create specialist barriers that generalist competitors avoid. Target Indian biosimilar production under CDSCO pathway maturation and PLI scheme incentives. Establish go-to-market credibility through technology licensing partnerships with established mammalian cell culture platform providers rather than greenfield process development. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical companies seeking captive manufacturing capacity and by scale-driven Korean contractors pursuing geographic diversification. Long-term viability favors contractors with FDA and EMA dual-inspection histories and validated ADC suites. Watch FDA draft guidance finalization on real-time release testing as the critical inflection signal for batch-to-continuous process migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA GMP Annex 2 compliance accelerates cross-border antibody supply for European commercialization. |
| Manufacturing Scale-Up | Single-use bioreactor deployment compresses campaign turnover timelines for fragmented clinical pipelines. |
| Capacity Expansion | Songdo free economic zone tax holidays offset greenfield facility investment risk in South Korea. |
| Backward Integration | In-house cell-line engineering reduces platform process licensing dependence for discovery-stage sponsors. |
| Strategic Partnership | Blockchain-enabled batch traceability addresses sponsor risk management requirements across distributed supply networks. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with bioprocess engineering directors, regulatory affairs leads at contract manufacturers, biotechnology CMC executives, and hospital pharmacy procurement managers. FDA 483 inspection observations, EMA GMP non-compliance reports, and MFDS manufacturing licensing databases provided facility-level validation. Bottom-up capacity aggregation across named contractor networks was cross-checked against top-down therapeutic antibody demand modeling.
Granularity-level modeling distinguished mammalian versus microbial expression systems, monoclonal antibody versus antibody-drug conjugate product categories, and drug substance versus fill-finish service segments across the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions calibrated to disclosed capacity reservation patterns. Forecast inputs incorporated perfusion cell culture adoption curves, continuous manufacturing regulatory pathway uncertainty, and biosimilar approval velocity by national regulator.
Underlying measurement precision varies by segment; monoclonal antibody capacity utilization carries tighter precision than emerging antibody-drug conjugate demand given established clinical validation timelines. Forecasts reflect assumptions regarding FDA guidance finalization timing and EMA inspection resource allocation that material changes in either would revise. A model refresh is warranted upon material change in continuous manufacturing regulatory position or significant plasma-derived raw material price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market