
 Cell Lysis and Dissociation Market | 2026-2036
Cell Lysis and Dissociation Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Lysis and Dissociation Market Outlook
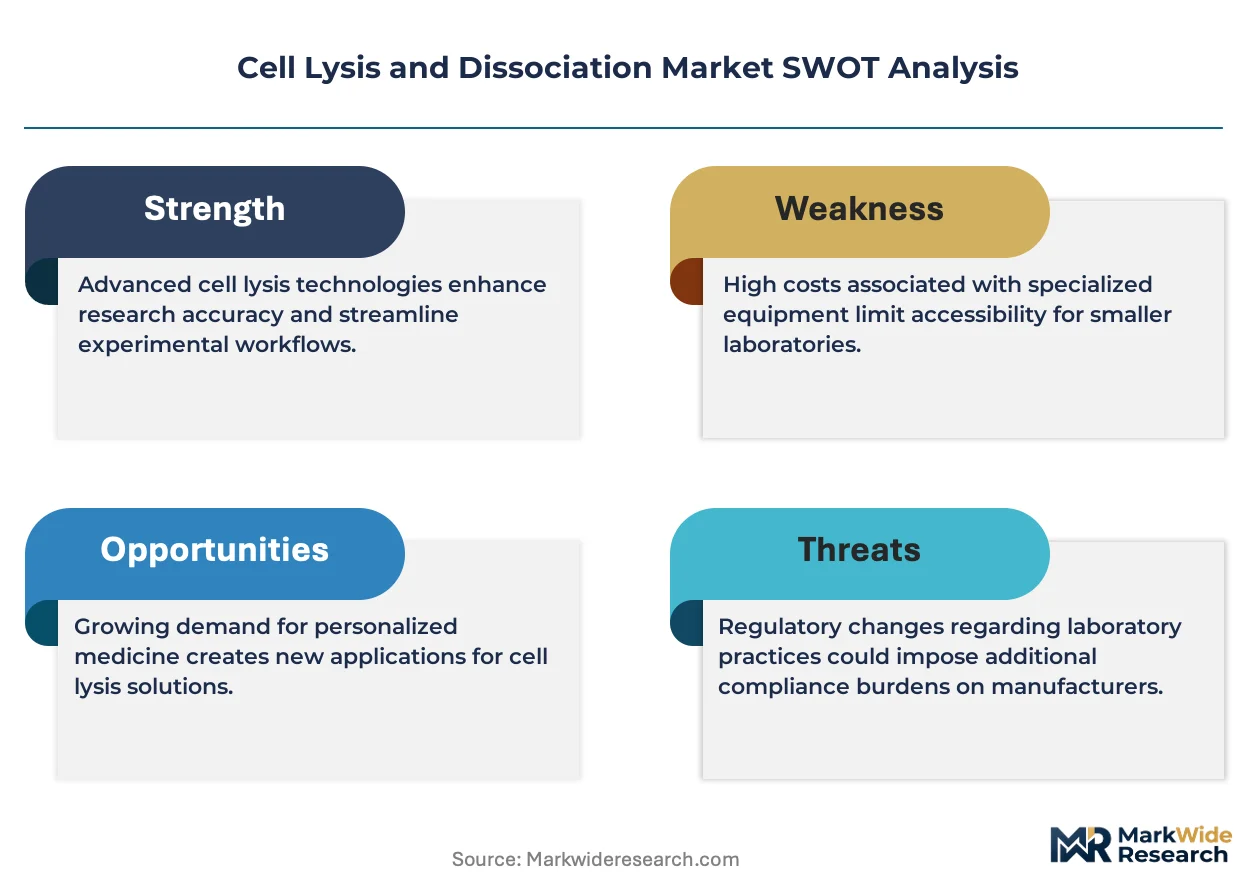
EU MDR is restructuring the cost-of-entry calculus for cell lysis device manufacturers serving European pharmaceutical clients. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to sustain premium positioning across automated workflows. Danaher Corporation anchors its competitive stance through Beckman Coulter's centrifugation-lysis platform specialization in bioprocessing applications. Merck KGaA differentiates via Sigma-Aldrich's deep chemical lysis portfolio and global distribution density in academic channels.
Cell lysis and dissociation encompasses mechanical, chemical, enzymatic, and thermal methods for rupturing cell membranes to release intracellular biomolecules, with critical parameters including shear force tolerance, temperature thresholds, and buffer ionic strength tailored to protein stability or nucleic acid integrity. The primary commercial purpose spans downstream purification of DNA, RNA, and proteins for therapeutic manufacturing, diagnostic assay development, and fundamental research. Reagents and kits capture the dominant revenue share due to recurring consumable demand, while instruments command higher per-unit margins as laboratories automate high-throughput sample processing. Enzymatic breakdown methods represent the fastest-growing technology segment, driven by gentler handling requirements for live-cell analysis and single-cell sequencing workflows.
FDA, EMA, and ISO 13485 collectively shape product validation pathways, with FDA's Quality by Design framework for biologics manufacturing directly influencing lysis protocol documentation requirements in commercial cell therapy production. REACH and RoHS constraints in Europe restrict certain detergent chemistries, prompting reformulation investments among reagent suppliers. Stakeholders must monitor evolving cell therapy regulatory harmonization between FDA and EMA, as divergent validation standards threaten to fragment R&D investment and manufacturing location decisions.
Market Dynamics
Automated dissociation platforms are restructuring competitive advantage in biologics manufacturing, as pharmaceutical producers prioritize walkaway sample processing over manual reagent workflows. FDA's Quality by Design framework now mandates documented lysis protocols for commercial cell therapy batches, forcing reagent suppliers to validate performance under GMP conditions.
Growth Catalysts
- Cell therapy commercialization:Autologous and allogeneic manufacturing pipelines in the United States require scalable enzymatic dissociation for CAR-T expansion workflows.
- REACH reformulation mandates:European reagent suppliers are investing in biodegradable detergent alternatives ahead of 2025 restriction deadlines on ionic surfactants.
- Single-cell sequencing:Academic core facilities and CROs are standardizing gentle lysis methods to preserve transcriptomic integrity in multiomic studies.
Market Restraints
- Enzyme supply concentration:Recombinant protease production clusters in Danish and German fermentation facilities, creating geographic vulnerability for global kit manufacturers.
- Protein stabilization costs:Cold-chain requirements for temperature-sensitive lysis buffers add 15-25% to consumable logistics spend in tropical climates.
- CRISPR off-target liability:Gene editing workflows require ultra-pure nucleic acid yields, disqualifying harsher chemical lysis methods from clinical-grade applications.
Strategic Opportunities
- India bioprocessing expansion:CDSCO's streamlined biologics approval pathway is attracting multinational investment in regional reagent formulation plants.
- AI-guided protocol optimization:Machine learning platforms that predict lysis efficiency from cell density and membrane composition are reducing R&D iteration cycles.
- Point-of-care diagnostics:Miniaturized mechanical lysis devices for nucleic acid extraction at the bedside bypass cold-chain dependencies in rural health systems.
Industry Challenges
- GMP compliance timelines:ISO 13485 certification for automated lysis instruments requires 18-24 month validation cycles, delaying product launches.
- Cross-platform integration:Proprietary consumable lock-in from major instrument vendors complicates third-party reagent compatibility testing.
- Specialized field service:Automated dissociation platforms demand mechatronics expertise scarce in emerging market service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Lysis and Dissociation Market |
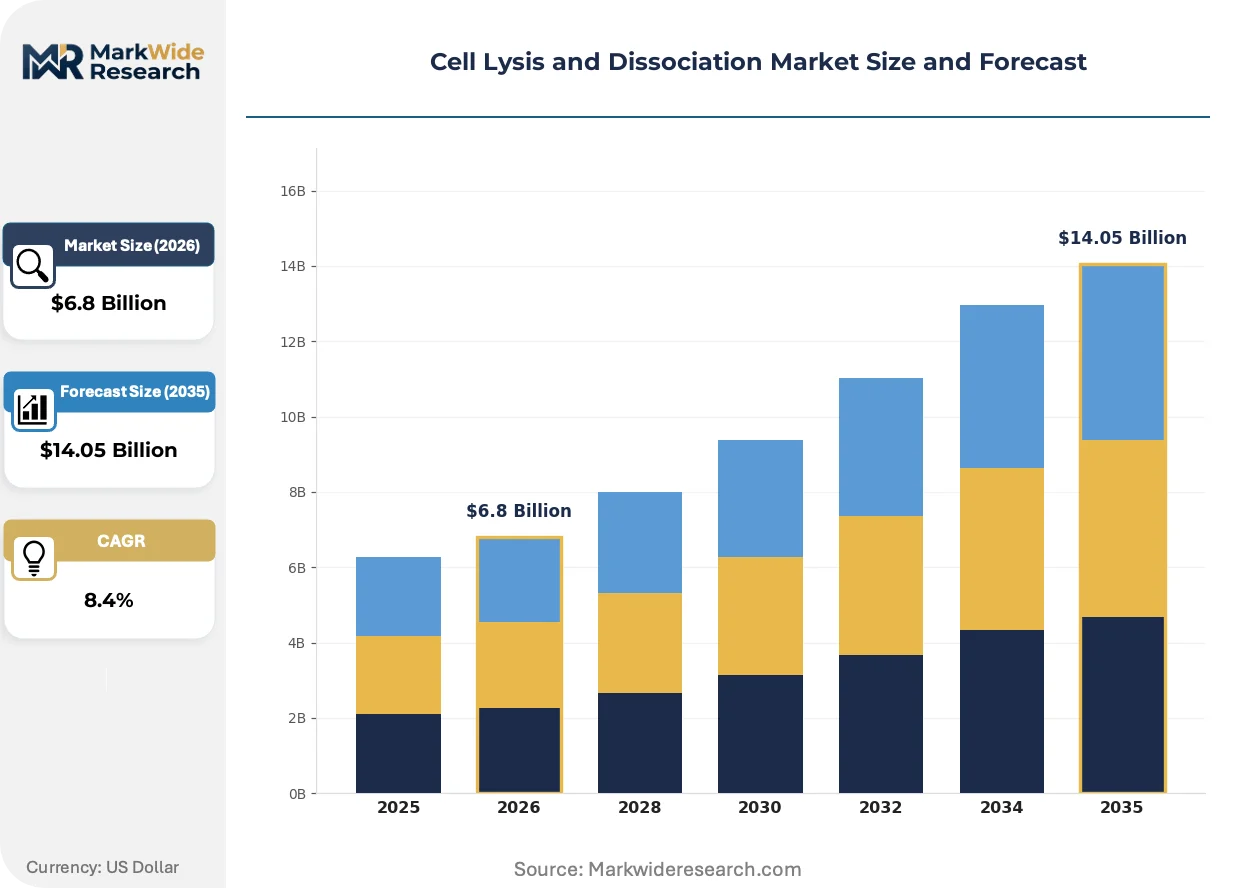
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical Disruption, Chemical Lysis, Enzymatic Breakdown, Thermal Lysis End User: Research Laboratories, Pharmaceutical Companies, Biotechnology Firms, Academic Institutions Application: Protein Extraction, Nucleic Acid Isolation, Cell Culture, Drug Discovery Product Type: Reagents, Instruments, Kits, Accessories |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, F. Hoffmann-La Roche, BD (Becton, Dickinson and Company), STEMCELL Technologies, Miltenyi Biotec, Bio-Rad Laboratories, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Lysis and Dissociation Market Strategic Shifts
Digitalization of protocol development is compressing the gap between research-grade and clinical-grade lysis methods. Vendors now embed sensors and cloud connectivity into benchtop instruments to capture real-time shear-force and temperature data for regulatory submissions.
Microfluidic lysis chips are decentralizing sample preparation from centralized core facilities to individual research benches. Pharmaceutical discovery groups in Boston and San Diego are piloting disposable cartridge systems that eliminate cross-contamination risks in high-throughput screening. This architecture is decentralizing capital expenditure models, shifting revenue from six-figure capital equipment to recurring consumable contracts.
EMA's updated Annex 1 guidelines on sterile manufacturing are mandating closed-system lysis for cell therapy production. The directive requires physical separation between operators and living cell material, accelerating adoption of functionally closed dissociation instruments. European CMOs are retrofitting existing suites or selecting new platforms specifically for isolator compatibility.
Consolidated procurement through group purchasing organizations is squeezing standalone reagent vendors. Academic medical centers in Texas and California now negotiate enterprise licenses covering mechanical, chemical, and enzymatic methods under single contracts. This behavior concentrates purchasing power with distributors capable of bundling across technology categories.
Cell Lysis and Dissociation Market Segmentation
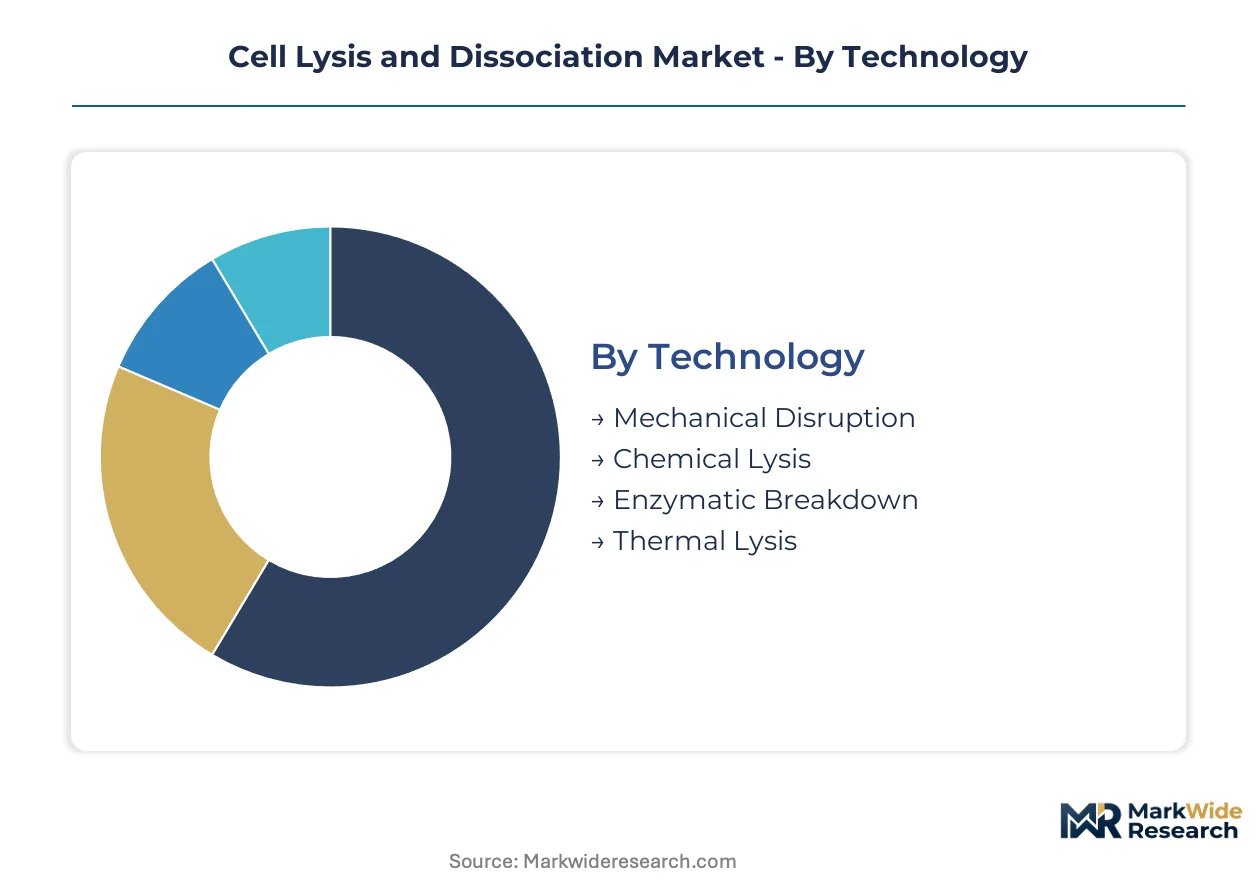
Segmentation in cell lysis and dissociation reveals how technology choices cascade through procurement decisions, with enzymatic methods commanding premium pricing while mechanical systems dominate volume. Understanding these splits exposes where vendor consolidation concentrates and where niche specialists retain defensible positions.
Technology:
Supply concentration in protease manufacturing clusters around specialized fermentation facilities in Northern Europe, shaping availability and pricing volatility across enzymatic workflows.
- Mechanical Disruption:Physical force methods including bead milling, sonication, and high-pressure homogenization rupture cell walls through shear stress. Demand concentrates in United States vaccine manufacturing facilities where scalability and absence of chemical contaminants outweigh capital equipment costs.
- Enzymatic Breakdown:Recombinant proteases and collagenases selectively digest extracellular matrices while preserving intracellular components. CAR-T production workflows at pharmaceutical companies in Massachusetts and California drive demand for GMP-validated enzyme formulations with documented lot-to-lot consistency.
- Chemical Lysis:Detergent-based buffers disrupt lipid bilayers through solubilization. REACH regulatory deadlines in Europe are forcing reformulation investments away from ionic surfactants toward biodegradable alternatives.
- Thermal Lysis:Heat-induced membrane destabilization offers simplicity but risks protein denaturation. Academic researchers in budget-constrained settings favor this approach for PCR-ready DNA extraction.
Today's leader: Mechanical Disruption. Tomorrow's challenger: Enzymatic Breakdown.
End User:
Procurement authority splits between centralized purchasing departments at multinational pharmaceutical firms and decentralized principal investigator budgets at research universities.
- Pharmaceutical Companies:Commercial cell therapy manufacturers require validated, scalable dissociation platforms with full regulatory documentation. FDA Quality by Design mandates force these buyers toward instrument-reagent bundled contracts with single vendors.
- Biotechnology Firms:Mid-stage companies prioritize flexibility over standardization, mixing vendor sources to avoid lock-in. Boston and San Diego clusters show highest concentration of automated platform adoption.
- Research Laboratories:Core facilities at academic medical centers manage high-throughput sample processing across multiple principal investigators. Group purchasing organization consolidation in Texas and California squeezes standalone reagent vendors.
- Academic Institutions:Individual laboratories operate on constrained budgets favoring kit-based chemical lysis over capital-intensive instrumentation. Publication pressure drives preference for established methods with traceable citations.
Pharmaceutical Companies capture the highest per-account value. Biotechnology Firms are gaining share fastest.
Application:
Margin profiles diverge sharply between clinical-grade nucleic acid isolation and research-grade protein extraction, with regulatory burden determining pricing power.
- Nucleic Acid Isolation:Purification of DNA and RNA for sequencing, cloning, and diagnostic applications demands high integrity yields. mRNA vaccine production infrastructure in United States and Germany requires automated, high-throughput platforms with minimal cross-contamination risk.
- Protein Extraction:Release of intracellular and membrane proteins for structural analysis or therapeutic manufacturing. Biologics CMOs in Switzerland and Singapore prioritize gentle lysis methods preserving post-translational modifications.
- Cell Culture:Dissociation of adherent cells for subculture or analysis. Stem cell research workflows require enzyme formulations free of animal-derived components.
- Drug Discovery:High-throughput screening of compound libraries against cellular targets. Pharmaceutical discovery groups in Boston pilot microfluidic cartridge systems eliminating cross-contamination.
Nucleic Acid Isolation commands premium pricing. Protein Extraction offers the steepest expansion trajectory.
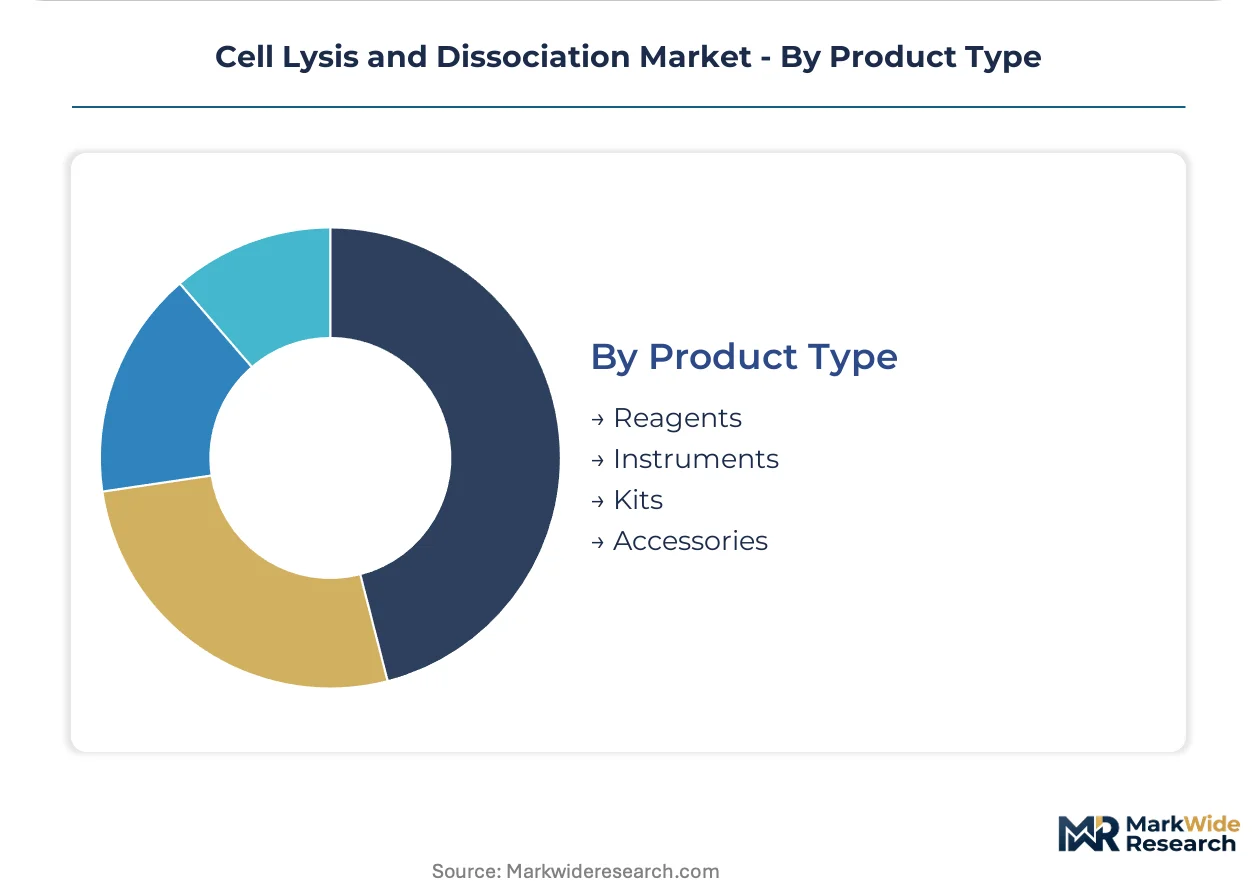
Product Type:
Revenue concentration in consumables creates predictable recurring streams, while instrument placements establish competitive moats through proprietary cartridge lock-in.
- Reagents:Buffers, detergents, and enzyme formulations constitute the largest revenue category. Cold-chain logistics add 15-25% to consumable costs in tropical climates, favoring regional formulation plants.
- Instruments:Automated dissociation platforms and homogenizers command highest per-unit margins. GMP validation cycles of 18-24 months delay competitive entry.
- Kits:Pre-packaged reagent-instrument combinations simplify procurement for non-specialist users. Academic medical centers increasingly negotiate enterprise licenses covering multiple kit categories.
- Accessories:Consumables including beads, tubes, and cartridges tied to specific instrument platforms. Proprietary cartridge architectures shift revenue from capital equipment to recurring contracts.
Reagents dominate current revenue. Instruments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cell lysis and dissociation industry traces its commercial origins to post-war biochemical reagent manufacturing in the United States and Germany, where standardized enzyme production first enabled scalable cell culture workflows.
United States
CAR-T manufacturing facilities in Massachusetts and California drive enzymatic dissociation demand for autologous cell therapy production. FDA's Quality by Design framework mandates documented lysis protocols for commercial batches, forcing GMP validation investments. The Boston-Cambridge biotech corridor hosts the highest concentration of automated platform pilots for high-throughput screening.
Germany
REACH deadlines on ionic surfactants are accelerating biodegradable detergent reformulation investments among reagent suppliers. EMA's updated Annex 1 guidelines mandate closed-system lysis for cell therapy production, requiring physical separation between operators and living cell material. Heidelberg and Munich academic medical centers lead adoption of microfluidic cartridge systems for decentralized sample preparation.
China
NMPA's streamlined biologics approval pathway is attracting multinational investment in regional reagent formulation plants. The country's national pharmaceutical regulator is harmonizing cell therapy validation standards with international benchmarks. Yangtze River Delta bioprocessing clusters are scaling mRNA vaccine production infrastructure requiring automated nucleic acid isolation platforms.
India
CDSCO's expedited biologics pathway is drawing contract manufacturing organization investment into regional enzyme formulation capacity. Cold-chain limitations in tropical climates favor localized buffer production to mitigate logistics costs. Maharashtra and Karnataka host emerging clusters of academic core facilities standardizing gentle lysis methods for single-cell sequencing workflows.
Switzerland
Swissmedic's alignment with EMA standards positions the country as a validation reference for global cell therapy manufacturers. Biologics contract manufacturing organizations prioritize gentle lysis methods preserving post-translational modifications for therapeutic protein production. Basel and Zurich academic-industry partnerships are piloting AI-guided protocol optimization platforms.
Cell Lysis and Dissociation Market Competitive Environment
The competitive structure tilts toward integrated reagent-instrument ecosystems rather than standalone component suppliers. Three player archetypes dominate: diversified life science conglomerates with bundled workflow offerings, specialized enzyme manufacturers with fermentation-scale advantages, and regional kit assemblers serving price-sensitive academic segments. Consolidation pressure intensifies as group purchasing organizations concentrate procurement authority at academic medical centers, while GMP validation timelines of 18-24 months deter new instrument entrants.
Within the diversified conglomerate tier, Thermo Fisher Scientific, Danaher Corporation, and Merck KGaA occupy positions defined by integrated platform ecosystems rather than individual product lines. Thermo Fisher Scientific exemplifies the reagent-instrument bundling archetype through its consumable-recurring revenue model. Danaher Corporation anchors the centrifugation-lysis specialization vector via its Beckman Coulter subsidiary structure. Merck KGaA represents the chemical portfolio breadth archetype through its Sigma-Aldrich distribution density. These three entities collectively illustrate how competitive advantage in this market derives from captive consumable streams tied to instrument placements rather than standalone product performance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Danaher Corporation |
| F. Hoffmann-La Roche |
| BD (Becton, Dickinson and Company) |
| STEMCELL Technologies |
| Miltenyi Biotec |
| Bio-Rad Laboratories |
| QIAGEN |
| Others |
Value Chain & Pricing Dynamics
Recombinant protease spot pricing indices in Northern Europe cascade through three distinct procurement tiers, with GMP-validated enzyme formulations commanding substantial premiums over research-grade alternatives while cold-chain logistics costs amplify geographic price dispersion in tropical markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FDA-validated GMP tiers separating from ISO-certified research grades and basic kit formulations. Price differentiation hinges on certification depth and cold-chain reliability, with pharmaceutical manufacturers showing lowest sensitivity and academic laboratories highest. Cost compression in economy-tier chemical lysis buffers is intensifying because REACH-mandated surfactant reformulations are raising input costs for European suppliers.
Supply Chain Analysis
Single-source vulnerability sits with Danish and German fermentation facilities for recombinant protease production, creating geographic concentration risk for global kit manufacturers. Supply draws from Denmark, Germany, and emerging formulation plants in India for enzyme and buffer production. Raw material dependencies include specialized fermentation media, pharmaceutical-grade detergents, and temperature-stabilizing excipients. Tariff exposure on cross-border enzyme shipments threatens margin stability. Distribution runs through group purchasing organizations at academic medical centers and direct vendor-managed inventory at pharmaceutical CMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell lysis and dissociation market functions as a stable compounder, with recurring consumable demand from biologics manufacturing pipelines generating predictable revenue streams regardless of therapeutic modality cycles.
For Market Incumbents: Lock in captive consumable streams through proprietary cartridge architectures that tether reagent purchases to installed instrument bases. Deepen backward integration into recombinant protease fermentation capacity to secure supply against Danish and German concentration risk. Prioritize ISO 13485 certification investments for automated platforms to extend validation moats against emerging competitors.
For New Entrants and Emerging Players: Enter via point-of-care diagnostic applications where miniaturized mechanical lysis devices bypass entrenched reagent-instrument ecosystems. Target India's CDSCO-aligned bioprocessing corridor where localized buffer production addresses cold-chain cost disadvantages. Pursue AI-guided protocol optimization software as a service-layer entry point before competing on hardware.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized enzyme manufacturers possessing GMP-validated fermentation scale and documented lot-to-lot consistency for CAR-T workflows. Long-term viability rests on consumable-recurring revenue models rather than capital equipment placements. Watch for EMA-FDA harmonization signals on cell therapy validation standards as the inflection indicator for manufacturing location decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Validation Investment | ISO 13485 certification for automated lysis instruments creates 18-24 month competitive moats against new entrants. |
| Backward Integration into Fermentation | In-house protease production secures supply chains against Danish and German geographic concentration risks. |
| AI-Guided Protocol Optimization | Machine learning platforms reduce R&D iteration cycles for lysis efficiency prediction from cell density inputs. |
| Regional Formulation Expansion | Localized buffer production in India and China mitigates cold-chain cost premiums in tropical climates. |
| Closed-System Lysis Development | EMA Annex 1 compliance for sterile manufacturing mandates physical separation between operators and cell material. |
Study Parameters
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with bioprocess engineers, regulatory affairs leads at cell therapy manufacturers, GPO contracts managers at academic medical centers, and reagent procurement directors informed demand-side assumptions. Secondary validation drew from FDA guidance documents, EMA Annex 1 revisions, CDSCO biologics pathway notifications, and SEC filings of diversified life science conglomerates. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped reagent consumption rates to instrument installed bases across the projection horizon. Segmentation dimensions modeled include technology type, end-user category, application purpose, and product format. CAGRs were derived from fitted growth curves applied to disclosed capacity expansions and procurement contract values. Industry-specific forecast inputs incorporated CAR-T manufacturing facility buildouts, mRNA vaccine production infrastructure scaling, and REACH reformulation investment timelines.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time enzyme spot pricing and proprietary GMP validation cycle durations introduce uncertainty bands around competitive dynamics assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Global Vector Control Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
GMO Testing Services Market