
 Biotechnology and Pharmaceutical Services Outsourcing Market | 2026-2036
Biotechnology and Pharmaceutical Services Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Biotechnology and Pharmaceutical Services Outsourcing Market Intelligence
The FDA's quality management system regulation is recalibrating cost-of-entry calculus for small and mid-sized biotech firms pursuing in-house manufacturing. Charles River Laboratories leverages its integrated early-stage discovery platform to anchor client relationships across toxicology and safety assessment. WuXi AppTec sustains geographic diversification across North American and European client bases while maintaining substantial laboratory capacity in China. Lonza Group dominates cell and gene therapy manufacturing through specialized single-use bioreactor infrastructure.
Biotechnology and pharmaceutical services outsourcing encompasses the delegation of R&D, clinical, regulatory, and manufacturing functions to specialized third-party providers operating under current Good Manufacturing Practice (cGMP) and Good Laboratory Practice (GLP) standards, with primary purpose being cost reduction and access to capabilities that would require years of capital-intensive buildout. Clinical research services lead in revenue contribution due to trial complexity and site management requirements, while artificial intelligence within the technology dimension represents the fastest-expanding capability investment as sponsors pursue predictive patient recruitment and adaptive trial design. Regulatory affairs services command premium pricing structures given specialized expertise in navigating multi-jurisdictional submission pathways.
The FDA, EMA, and China's NMPA collectively shape market access through divergent inspection protocols and data integrity requirements that elevate outsourcing vendor qualification standards. India's CDSCO and Japan's PMDA add further compliance layers for sponsors targeting Asia-Pacific commercialization. Stakeholders must monitor regulatory harmonization progress between ICH member agencies to anticipate where centralized outsourcing hubs gain or lose comparative advantage.
Market Dynamics
Biologics pipeline expansion is compressing sponsor timelines while elevating technical capability requirements beyond in-house buildout economics. Contract research and manufacturing organizations capture this structural gap through specialized infrastructure investments.
Growth Catalysts
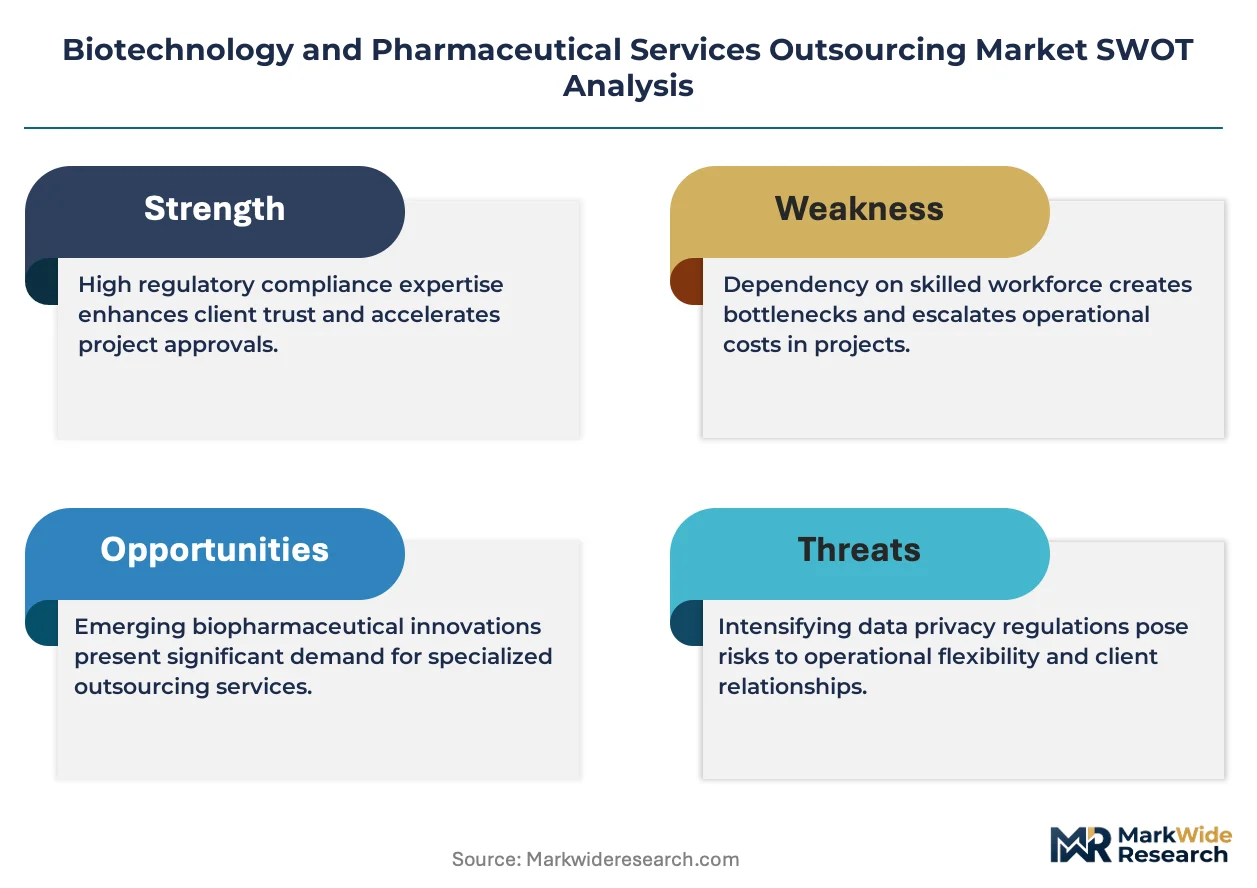
- ICH E6(R2) Good Clinical Practice:Harmonized quality standards across FDA, EMA, and NMPA jurisdictions reduce redundant audit burdens for multi-regional trials, accelerating sponsor outsourcing decisions.
- Cell therapy manufacturing:Autologous and allogeneic cell processing requires closed-system bioreactor infrastructure that few innovators possess, driving demand for specialized CDMO capacity.
- China:Domestic biotech firms advancing novel antibody-drug conjugates and CAR-T assets require outsourced toxicology and regulatory submission support as pipeline maturity outpaces internal capabilities.
Market Restraints
- Single-use consumables cost volatility:Resin and filtration membrane supply concentration among limited vendors creates input cost unpredictability for bioprocessing service providers.
- Data integrity enforcement:FDA's ALCOA+ expectations for electronic records and audit trails elevate compliance infrastructure costs, compressing margins for smaller CRO operations.
- In-house biologics manufacturing:Large-cap pharmaceutical firms with captive capacity at sites in Switzerland, Singapore, and Ireland reduce outsourcing volume for late-stage commercial production.
Strategic Opportunities
- Decentralized clinical trials:Direct-to-patient drug shipment and remote monitoring protocols open site management contracts to technology-enabled CROs beyond traditional hospital networks.
- India:CDSCO's streamlined approval pathways for biosimilars and vaccines position domestic service providers to capture regulatory affairs outsourcing from Western sponsors seeking cost arbitrage.
- Artificial intelligence and real-world evidence convergence:Predictive analytics for patient identification combined with claims database integration creates differentiated service bundles for adaptive trial design.
Industry Challenges
- Qualified cell therapy technicians:Aseptic processing and vector manufacturing expertise scarcity constrains capacity expansion timelines for gene therapy CDMOs.
- cGMP facility qualification:New manufacturing suites require validation runs and regulatory pre-approval inspections that extend revenue recognition by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotechnology and Pharmaceutical Services Outsourcing Market |
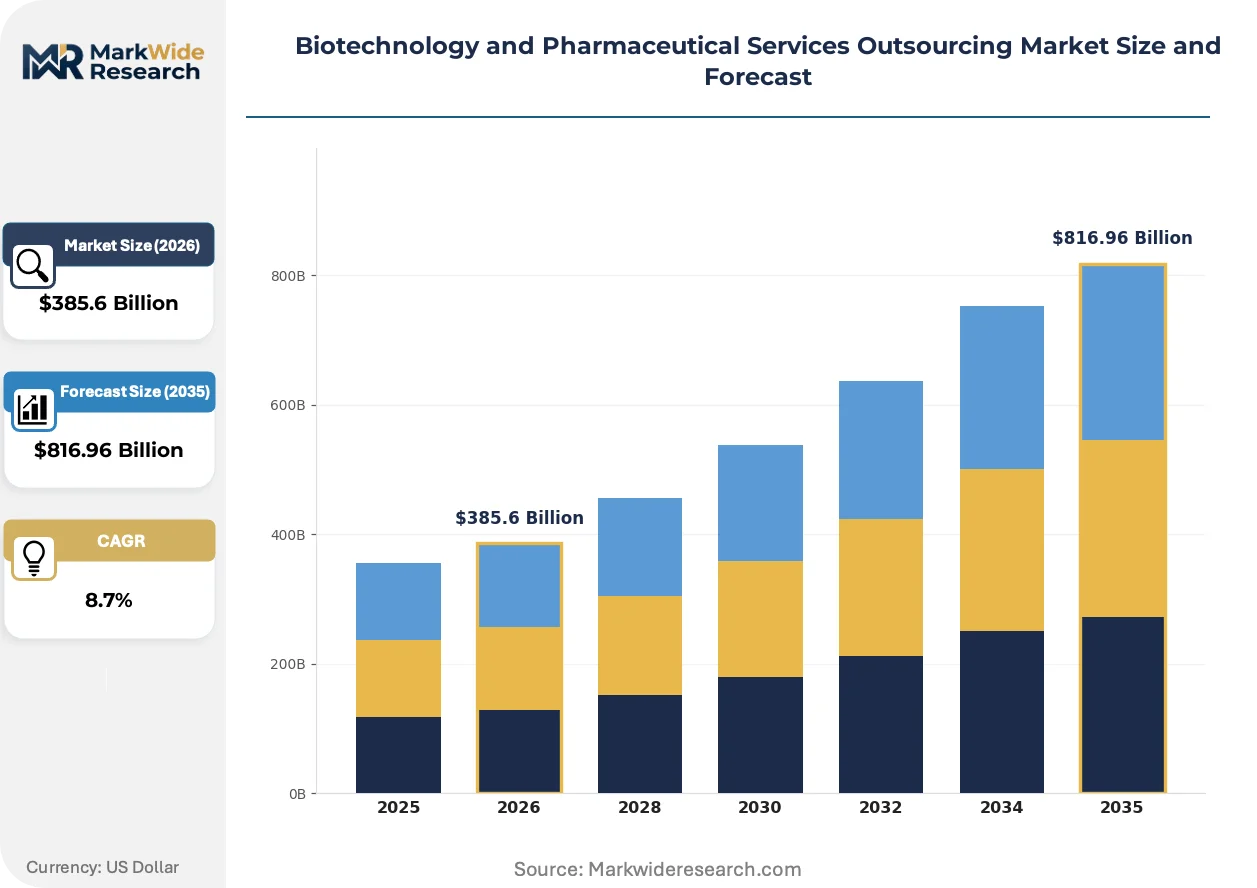
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $816.96 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Research, Data Management, Regulatory Affairs, Pharmacovigilance End User: Biotechnology Companies, Pharmaceutical Manufacturers, Academic Institutions, Contract Research Organizations Technology: Laboratory Automation, Bioinformatics, Artificial Intelligence, Cloud Computing Application: Drug Development, Clinical Trials, Market Access, Quality Assurance |
| Companies Covered | Charles River Laboratories, WuXi AppTec, Lonza Group, Covance, Samsung Biologics, Thermo Fisher Scientific, Parexel International, ICON plc, IQVIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotechnology and Pharmaceutical Services Outsourcing Market Strategic Shifts & Innovations
Digital infrastructure is displacing paper-based quality systems while advanced analytical platforms compress development timelines. Service providers differentiate through technology-enabled capability stacks rather than scale alone.
Single-use bioreactor technology is integrating into mammalian cell culture workflows through modular, disposable vessel systems that eliminate cleaning validation requirements. Mid-sized biotech sponsors adopt these platforms for Phase III commercial readiness without fixed stainless-steel infrastructure commitments. This shift is integrating flexible capacity models that reduce capital lock-up and accelerate tech transfer timelines between development and manufacturing stages.
EMA's Clinical Trial Regulation (EU No 536/2014) mandates centralized EU portal submissions and standardized safety reporting formats across member states. Sponsors face consolidated regulatory intelligence requirements that favor CROs with dedicated Brussels-based affairs teams and established rapport with national competent authorities. Cell and gene therapy trials encounter heightened scrutiny for genetically modified organism containment protocols, driving specialized service demand.
Pharmaceutical sponsors now unbundle functional service provider relationships rather than awarding comprehensive contracts to single vendors. Toxicology, clinical operations, and regulatory submissions frequently route to distinct best-in-class providers selected through competitive capability benchmarking. This fragmentation concentrates in oncology and rare disease programs where specialized expertise outweighs coordination overhead.
Biotechnology and Pharmaceutical Services Outsourcing Market Segmentation
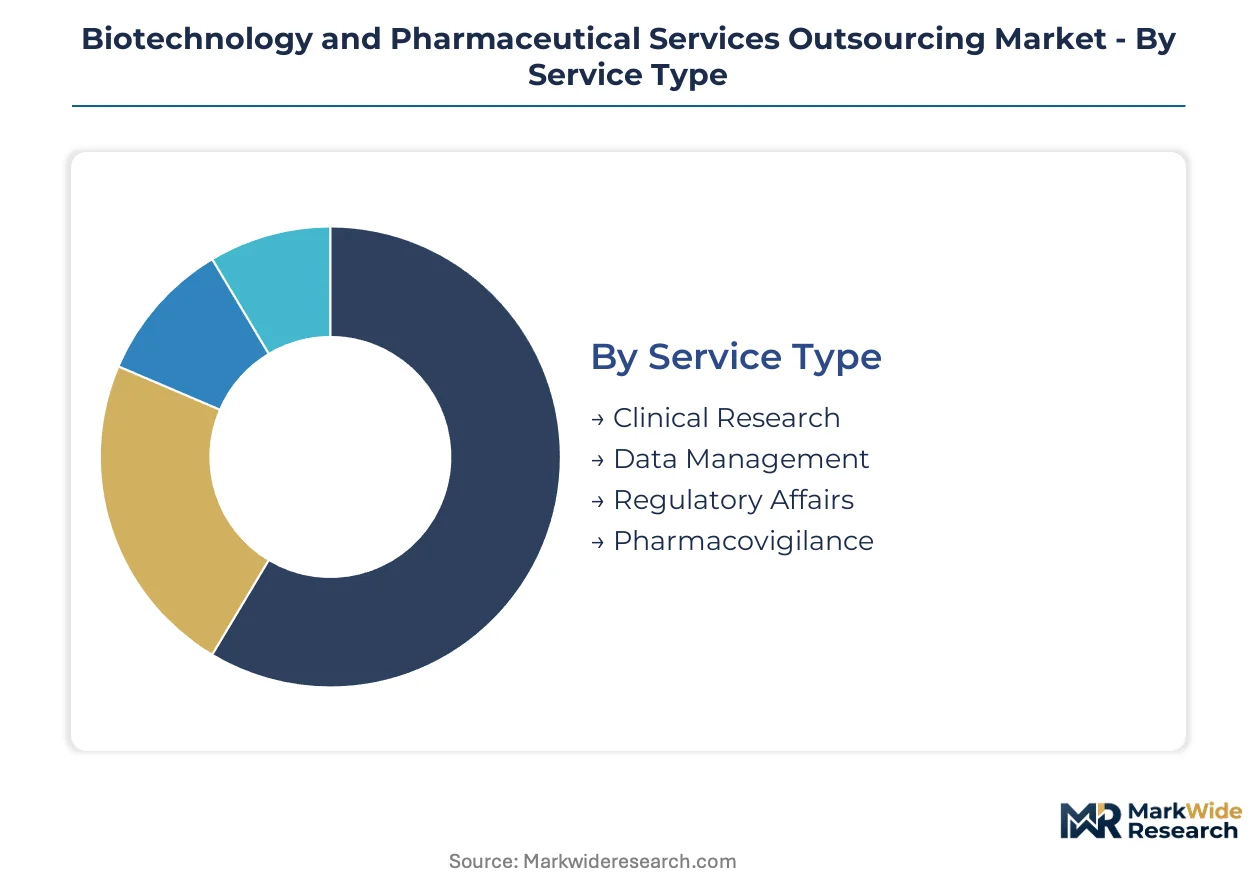
Service specialization determines vendor selection in biotechnology and pharmaceutical outsourcing, with sponsors unbundling contracts across distinct capability providers rather than consolidating with single vendors. Segmentation reveals where pricing power concentrates and where commoditization pressures margins.
Service Type:
Sponsor procurement teams weight technical capability depth against coordination overhead when allocating budgets across functional domains.
- Clinical Research:Site management, patient recruitment, and monitoring services constitute the largest revenue pool. Demand concentrates in oncology and rare disease programs where specialized investigator networks in the United States and Western Europe command premium fees due to protocol complexity.
- Data Management:Electronic data capture, statistical programming, and clinical database administration. Sponsors in China and India are expanding fastest here as domestic trial volumes outpace local biometrics talent supply, driving cross-border outsourcing.
- Regulatory Affairs:Submission strategy and health authority negotiation. FDA and EMA multi-jurisdictional filings require specialized expertise that smaller sponsors cannot maintain in-house.
- Pharmacovigilance:Adverse event processing and safety database maintenance. Cost pressures from India's CDSCO-aligned service providers are compressing pricing for case processing operations.
Clinical Research leads on scale; Data Management leads on momentum.
End User:
Organizational maturity and capital access shape outsourcing intensity and contract structure preferences across buyer categories.
- Biotechnology Companies:Venture-backed and publicly traded innovators lacking captive manufacturing infrastructure. Cell and gene therapy developers in Boston and San Francisco drive specialized CDMO demand for aseptic processing capabilities they cannot build internally.
- Pharmaceutical Manufacturers:Large-cap firms with selective outsourcing for capacity overflow or geographic expansion. Switzerland-based and Singapore-based manufacturing sites reduce external dependence for commercial biologics production.
- Academic Institutions:University medical centers conducting investigator-initiated trials. Funding constraints favor shared-service CRO arrangements rather than dedicated vendor relationships.
- Contract Research Organizations:Tier-2 and regional CROs subcontracting specialized functions to platform providers. This intermediary layer concentrates in India and Eastern Europe where labor arbitrage supports margin preservation.
Biotechnology Companies anchor volume expansion; Pharmaceutical Manufacturers concentrate value per contract.
Technology:
Capital deployment into digital infrastructure separates differentiated platform providers from labor-dependent service models.
- Laboratory Automation:High-throughput screening and analytical robotics. Toxicology service providers in Germany and the United Kingdom are automating histopathology workflows to compress study timelines.
- Bioinformatics:Genomic data processing and variant analysis. Oncology biomarker strategies require computational biology capabilities that smaller CROs access through platform partnerships.
- Artificial Intelligence:Predictive patient recruitment and adaptive trial design. FDA's complex innovative trial designs pilot program validates AI-enabled protocol optimization for sponsors seeking regulatory alignment.
- Cloud Computing:Distributed data storage and real-time analytics collaboration. EMA's Clinical Trial Regulation mandates centralized EU portal submissions that cloud-native CROs navigate more efficiently than legacy infrastructure competitors.
Laboratory Automation dominates current spend; Artificial Intelligence captures investment growth.
Application:
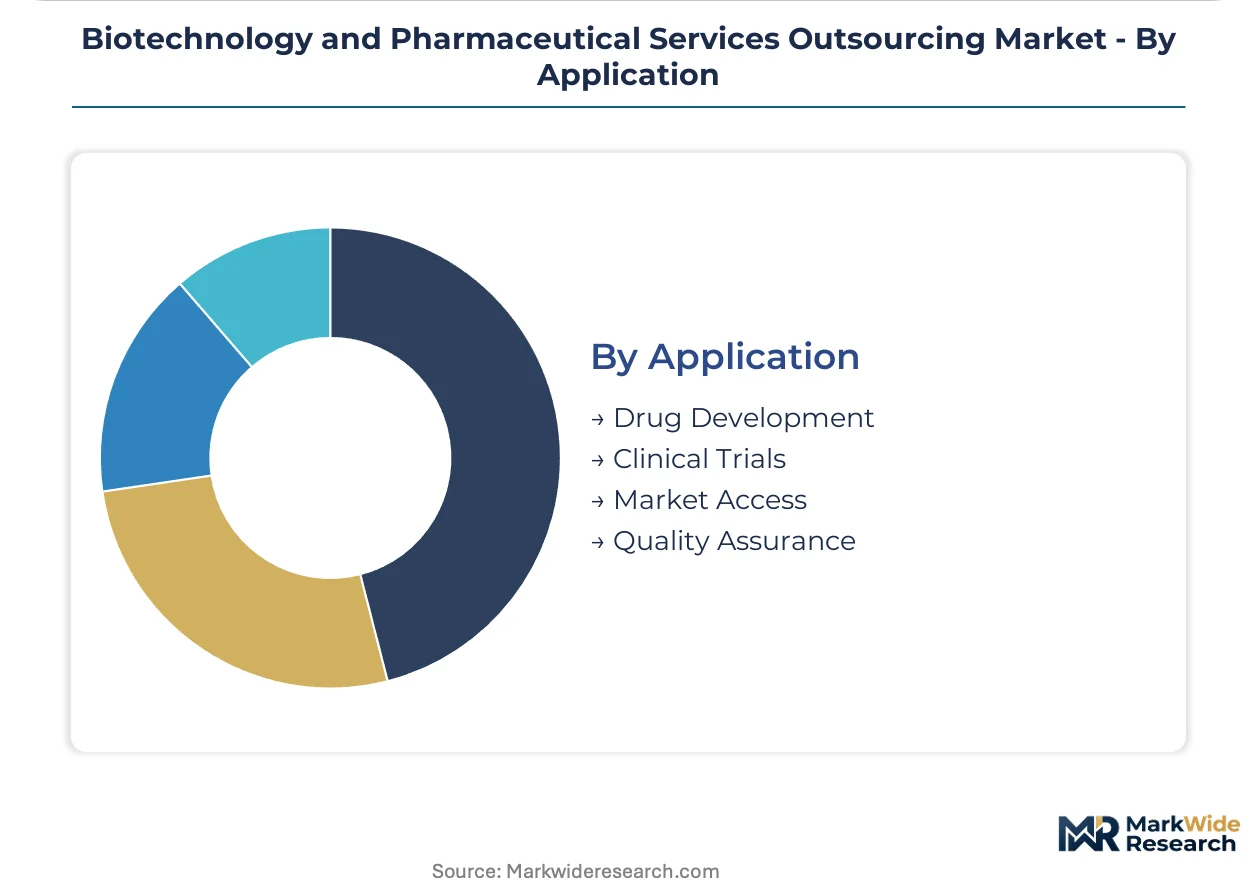
Development stage determines regulatory intensity, timeline pressure, and the specific vendor capabilities sponsors prioritize.
- Drug Development:Discovery through preclinical safety assessment. Charles River Laboratories and WuXi AppTec compete for integrated early-stage platform relationships that anchor long-term client retention.
- Clinical Trials:Phase I through Phase III execution and site management. Decentralized trial protocols are opening site contracts to technology-enabled providers beyond traditional academic medical center networks.
- Market Access:Pricing, reimbursement strategy, and health technology assessment. European markets require specialized Brussels-based affairs teams with established national competent authority relationships.
- Quality Assurance:cGMP compliance auditing and validation services. FDA's quality management system regulation elevates demand for external quality oversight as sponsor compliance costs rise.
Clinical Trials generates the largest contract values; Market Access commands the highest margins per engagement hour.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cell therapy technicians and GLP-certified toxicologists concentrate in Boston, Basel, and Shanghai, anchoring regional outsourcing capacity. These talent clusters shape where sponsors locate development programs and where contract organizations expand laboratory infrastructure.
United States
FDA's complex innovative trial designs pilot program accelerates adaptive protocol adoption among Boston and San Francisco biotech sponsors. Cell and gene therapy developers lacking aseptic processing capabilities drive demand for specialized CDMO partnerships. The Greater Boston corridor anchors toxicology and safety assessment outsourcing volume.
Switzerland
Large-cap pharmaceutical captive manufacturing at Basel and Geneva sites reduces commercial biologics outsourcing intensity. Swissmedic's streamlined quality management system inspections elevate vendor qualification standards for regional service providers. The Basel industrial cluster concentrates cell therapy single-use bioreactor infrastructure investments.
China
Domestic biotech firms advancing antibody-drug conjugates and CAR-T assets outpace internal regulatory capabilities. NMPA's data integrity requirements for electronic records and audit trails compress margins for smaller CRO operations. The Shanghai-Suzhou corridor anchors toxicology laboratory expansion serving both domestic innovators and Western sponsors.
India
CDSCO's streamlined approval pathways for biosimilars position domestic providers to capture regulatory affairs outsourcing from cost-sensitive Western sponsors. Pharmacovigilance case processing operations concentrate in Hyderabad and Bangalore where labor arbitrage supports margin preservation. The Hyderabad biotech cluster specializes in adverse event database maintenance and safety reporting.
Germany
EMA's Clinical Trial Regulation mandates centralized EU portal submissions that favor CROs with dedicated Brussels-based affairs teams. Toxicology service providers automate histopathology workflows in Munich and Frankfurt to compress study timelines. The Munich industrial cluster integrates high-throughput screening robotics into early-stage discovery platforms.
Biotechnology and Pharmaceutical Services Outsourcing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. The market fragments across three strategic archetypes: integrated early-stage discovery platforms, cell therapy manufacturing specialists, and technology-enabled clinical operations providers. Consolidation pressures concentrate among mid-tier CROs facing FDA compliance cost escalation. Dominant competitive moves include strategic partnerships for AI-enabled trial design and geographic expansion into China's domestic biotech client base.
Among the integrated platform providers, Charles River Laboratories and WuXi AppTec exemplify archetypes anchoring client relationships across toxicology and safety assessment. Lonza Group occupies a specialized position in cell and gene therapy manufacturing infrastructure. These three entities represent distinct strategic postures: North American laboratory automation integration, China-based geographic diversification with Western client bases, and European single-use bioreactor specialization respectively.
| Leading Market Players |
|---|
| Charles River Laboratories |
| WuXi AppTec |
| Lonza Group |
| Covance |
| Samsung Biologics |
| Thermo Fisher Scientific |
| Parexel International |
| ICON plc |
| IQVIA |
| Others |
Cost & Logistics Intelligence
FDA's quality management system regulation gates qualified supply access and premium-tier pricing for biotechnology and pharmaceutical services outsourcing, compressing margins for non-compliant operators while elevating certified providers into higher rate bands. This environmental mandate reshapes procurement calculus as sponsors prioritize validated vendors over cost-minimized alternatives.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the outsourcing landscape, with comprehensive platform contracts commanding 40-60% premiums over fragmented multi-vendor arrangements. Price differentiation rests on cGMP certification tier and geographic delivery cost, with FDA-inspected facilities in the United States and Switzerland extracting superior rates versus emerging-market competitors. Cost compression in pharmacovigilance case processing intensifies because India's CDSCO-aligned providers scale automated adverse event handling. Biotechnology companies exhibit highest price sensitivity due to venture-capital funding constraints, while large-cap pharmaceutical manufacturers prioritize capability assurance over rate negotiation.
Supply Chain Analysis
Reverse-logistics frameworks for investigational drug returns and temperature excursion management add complexity layers that specialized courier networks handle through validated cold-chain infrastructure. Single-use bioreactor consumables concentrate supply among vendors in the United States, Germany, and China, with resin and filtration membrane sourcing anchored in petrochemical feedstock corridors. Single-source vulnerability permeates vector manufacturing plasmid supply, where qualified GMP-grade material draws from limited qualified facilities. Distribution runs through sponsor-directed logistics partnerships rather than third-party wholesale channels, preserving chain-of-custody documentation for regulatory inspection readiness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology and pharmaceutical services outsourcing functions as a regulatory compounder, with ICH E6(R2) Good Clinical Practice harmonization accelerating sponsor outsourcing decisions through reduced audit redundancy. This milestone elevates demand for qualified vendors capable of multi-jurisdictional trial execution.
For Market Incumbents: Hedge against margin erosion by securing backward integration into single-use consumables manufacturing, insulating against resin price volatility that compresses bioprocessing service margins. Cell therapy CDMOs must expand aseptic processing technician training pipelines to defend capacity utilization against qualified labor scarcity. Charles River Laboratories and WuXi AppTec demonstrate platform stickiness through integrated early-stage discovery anchoring; competitors should replicate this relationship depth.
For New Entrants and Emerging Players: Direct-to-patient digital channels enable decentralized clinical trial site management without traditional academic medical center infrastructure investments. White-space concentrates in AI-enabled patient recruitment for oncology and rare disease programs, where predictive analytics capabilities remain underdeveloped among mid-tier CROs. India's CDSCO regulatory affairs outsourcing presents penetrable geography for Western sponsors seeking cost arbitrage on biosimilar submissions.
For Investors and Strategic Acquirers: Valuations sit cheapest among technology-enabled clinical operations providers lacking manufacturing scale but possessing FDA-validated AI trial design platforms. Long-term viability over the next decade hinges on adaptive trial infrastructure ownership as protocol complexity accelerates. Acquisition targets should demonstrate Brussels-based EMA affairs capability or Shanghai-Suzhou toxicology laboratory presence. The signal to watch is NMPA inspection backlog clearance rates, indicating where Chinese domestic biotech outsourcing demand materializes.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Investment | EMA centralized portal submission capability reduces multi-state trial initiation timelines for sponsors. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Basel and Singapore captures cell therapy CDMO demand. |
| AI Platform Integration | FDA complex innovative trial designs pilot validation enables predictive patient recruitment service differentiation. |
| Geographic Expansion | Shanghai-Suzhou toxicology laboratory presence accesses China's domestic biotech pipeline scaling. |
| Specialist Acquisition | Vector manufacturing plasmid supply control secures gene therapy CDMO input security. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, clinical operations directors, and CDMO procurement managers grounded qualitative findings, supplemented by FDA 483 inspection observations, EMA centralized portal submission data, ClinicalTrials.gov protocol records, and SEC 10-K segment disclosures. Bottom-up service provider capacity assessments and top-down sponsor outsourcing spend estimates underwent iterative reconciliation to validate market sizing.
Segment-level projections across service type, end user, technology, and application dimensions were generated through driver elasticity modeling over the projection horizon. CAGRs were derived from regression analysis against biologics pipeline expansion rates and regulatory harmonization progress indicators. Forecast inputs incorporated ICH member agency inspection coordination timelines and single-use consumables supply concentration metrics.
The model assumes a particular technology adoption path for artificial intelligence in patient recruitment; alternative pathways for decentralized trial protocol acceptance would alter the outlook. Forecasts reflect documented assumptions regarding NMPA inspection capacity expansion and FDA quality management system enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market