
 Biomarker Research Services Market | 2026-2036
Biomarker Research Services Market Size, Share, and Industry Trends Forecast 2026-2036
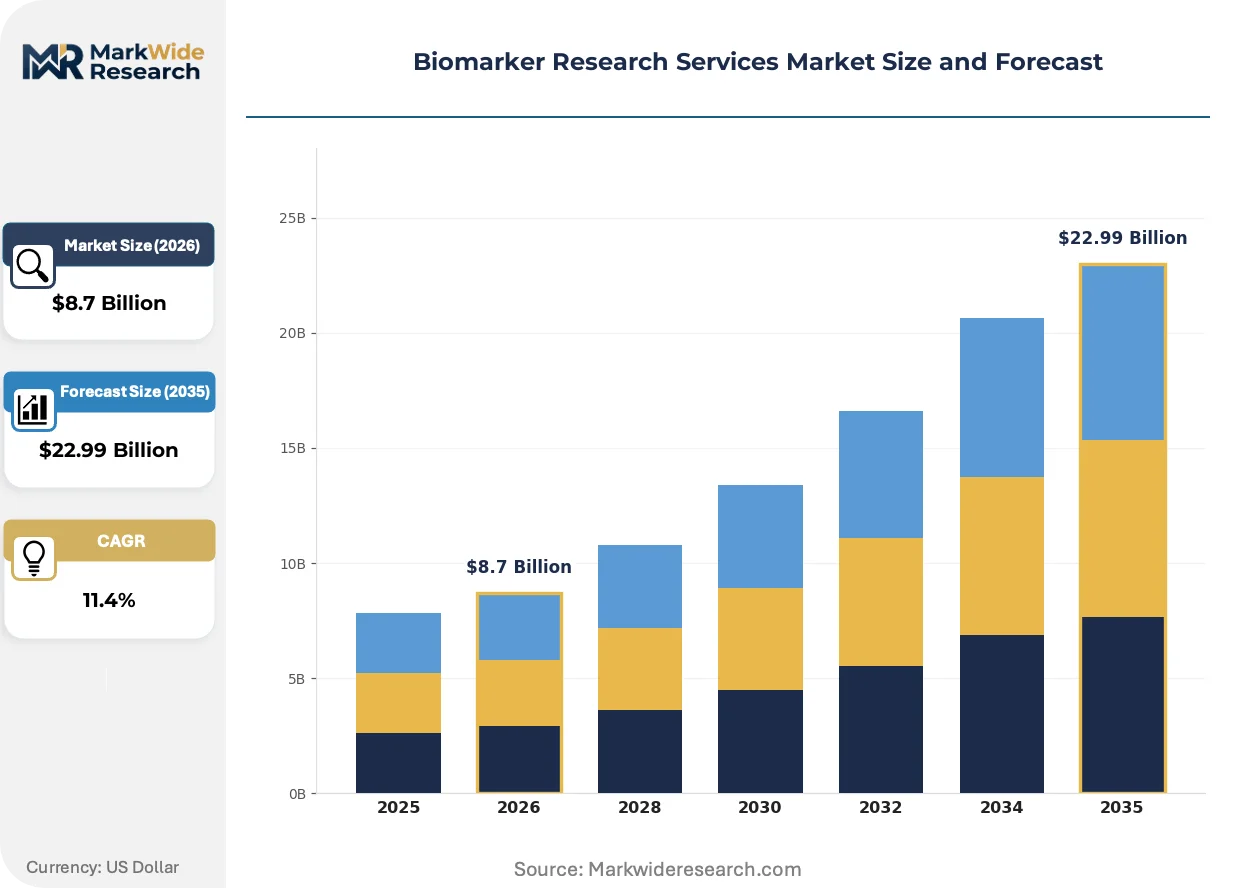
Biomarker Research Services Market Outlook
North America is fragmenting as contract research capacity spreads across specialized biotech corridors. Thermo Fisher Scientific leverages its integrated instrument-to-service workflow to anchor high-throughput genomics contracts. QIAGEN differentiates through sample-to-insight automation platforms that reduce analytical variability. Laboratory Corporation of America Holdings sustains geographic density in clinical trial logistics, competing on patient access networks rather than technology alone.
Biomarker research services encompass the identification, characterization, and clinical qualification of measurable biological indicators, typically employing mass spectrometry, next-generation sequencing, immunoassay platforms, and flow cytometry with sensitivity thresholds reaching picogram-per-milliliter detection. These services enable patient stratification, pharmacodynamic monitoring, and surrogate endpoint validation across therapeutic development. Discovery services occupy the largest revenue pool, though analytical services represent the fastest-expanding segment as sponsors outsource post-approval monitoring. Genomics commands mature infrastructure investment, while metabolomics attracts emerging demand for untargeted profiling in immuno-oncology. Oncology applications dominate current contract volume, yet neurology biomarker programs gain traction as cerebrospinal fluid collection protocols standardize.
The FDA's evolving companion diagnostics framework and the EMA's qualification pathway for novel methodologies jointly reshape service provider capabilities and documentation requirements. ISO 15189 accreditation and CLIA certification now function as baseline market access credentials rather than competitive differentiators. Stakeholders must monitor how decentralized trial models redistribute biomarker collection from central labs to point-of-care settings.
Market Dynamics
Pharmaceutical sponsors now mandate biomarker-guided trial designs as standard practice, compressing timelines for patient stratification and endpoint validation. This structural shift forces service providers to integrate multi-omics platforms with real-time data infrastructure or lose contract eligibility.
Growth Catalysts
- FDA Expanded Companion Diagnostics Guidance:The framework accelerates co-development timelines, requiring service providers to build parallel analytical validation capabilities. Sponsors now embed biomarker strategies into Phase I protocols.
- Immuno-Oncology Pipeline Expansion:Biopharma developers require pharmacodynamic monitoring for checkpoint inhibitors, driving demand for multiplexed immunoassay services with picogram-per-milliliter sensitivity thresholds.
- Decentralized Trial Models:Point-of-care biomarker collection protocols redistribute sample logistics from central laboratories to regional clinical sites, creating infrastructure upgrade requirements across North American CRO networks.
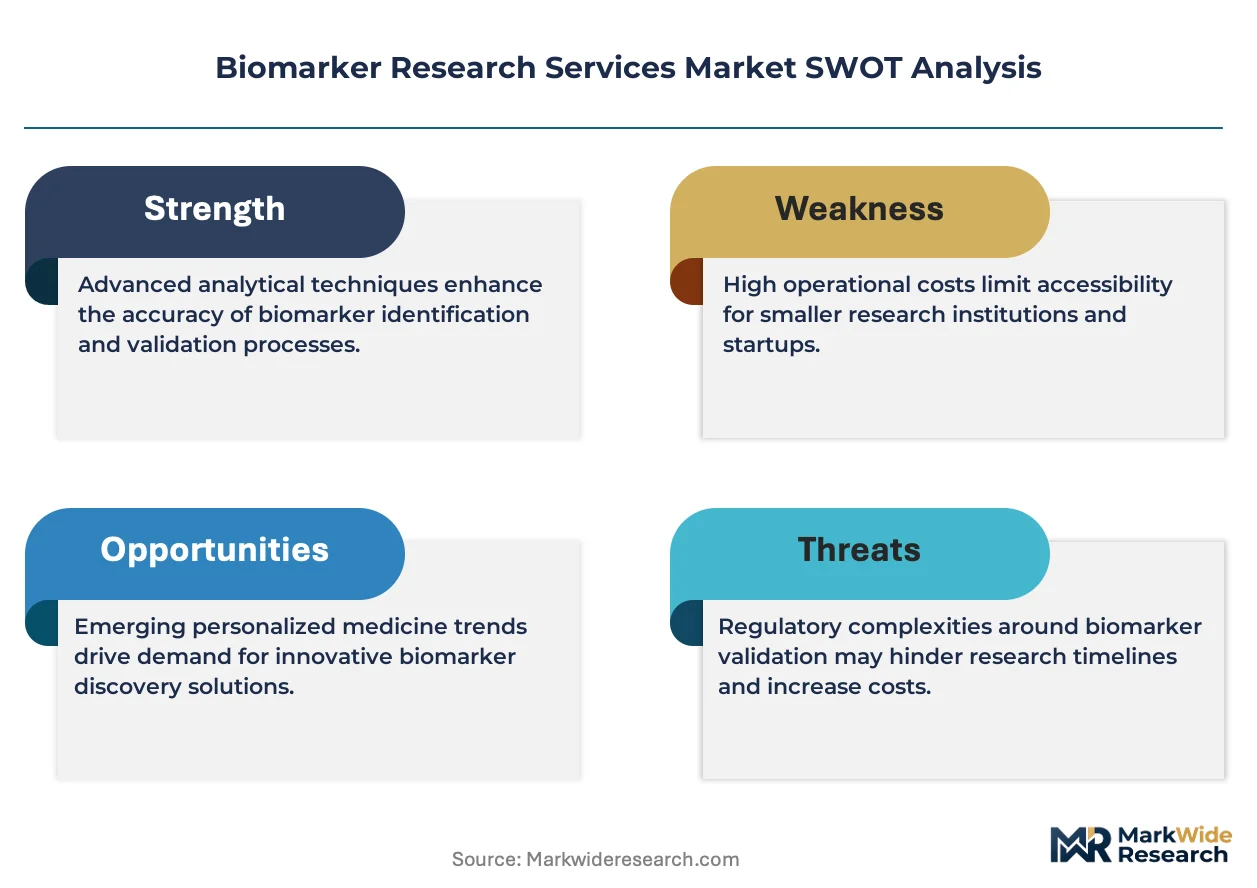
Market Restraints
- Specialized Reagent Supply Concentration:Isotope-labeled standards and affinity reagents for mass spectrometry workflows depend on limited European and North American suppliers, exposing service margins to input volatility.
- ISO 15189 Accreditation Burden:The documentation and proficiency testing requirements for clinical-grade biomarker analysis extend facility qualification timelines, delaying revenue recognition for new service lines.
- Proteomics Platform Substitution:Affinity-based proximity extension assays compete with traditional mass spectrometry for protein quantification, threatening capital-intensive installed base depreciation schedules.
Strategic Opportunities
- Neurology Biomarker Standardization:Cerebrospinal fluid collection protocols for neurodegenerative targets now achieve cross-site harmonization, opening contractable volume in a previously fragmented application area.
- Metabolomics-Untargeted Profiling Convergence:The integration of high-resolution mass spectrometry with machine learning-based annotation tools enables novel biomarker discovery without prior hypothesis constraints.
- EMA Qualification Pathway for Novel Methodologies:The regulatory incentive reduces validation burden for innovative analytical platforms, accelerating commercial deployment of digital pathology and liquid biopsy services.
Industry Challenges
- Multi-Omics Data Integration Expertise:Service providers struggle to recruit computational biologists capable of harmonizing genomics, proteomics, and metabolomics outputs into clinically actionable reports.
- Legacy LIMS Interoperability:Custom-built laboratory information management systems resist API-based connectivity with sponsor electronic data capture platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomarker Research Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Discovery Services, Development Services, Validation Services, Analytical Services End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Technology: Genomics, Proteomics, Metabolomics, Transcriptomics Application: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific, Abbott Laboratories, QIAGEN, Bio-Rad Laboratories, Laboratory Corporation of America Holdings, IQVIA, Agilent Technologies, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomarker Research Services Market Strategic Shifts
Next-generation sequencing platforms and cloud-native bioinformatics pipelines are compressing the analytical turnaround times that previously defined competitive positioning. Service differentiation now hinges on real-time data delivery rather than raw instrument throughput.
Single-cell RNA sequencing is migrating from exploratory research applications into regulated clinical trial contexts. Large pharmaceutical sponsors now require single-cell resolution for patient stratification in immuno-oncology studies. The technology is migrating from academic service contracts into GLP-validated workflows, forcing providers to rebuild quality management systems around cell-level traceability.
The FDA's draft guidance on artificial intelligence-enabled biomarker algorithms imposes premarket validation requirements on machine learning-based diagnostic outputs. Device manufacturers must now submit training dataset documentation and algorithm change control protocols. Oncology companion diagnostic developers face the steepest compliance burden, with several sponsors restructuring development programs to segregate locked-algorithm from adaptive-learning components.
Sponsor procurement teams now unbundle biomarker discovery from clinical validation services, awarding separate contracts to specialized providers. This disintermediation fragments revenue concentration previously captured by integrated CROs. The pattern is most visible in United States-based Phase II trials, where biotech sponsors prioritize scientific expertise over geographic convenience.
Biomarker Research Services Market Segmentation
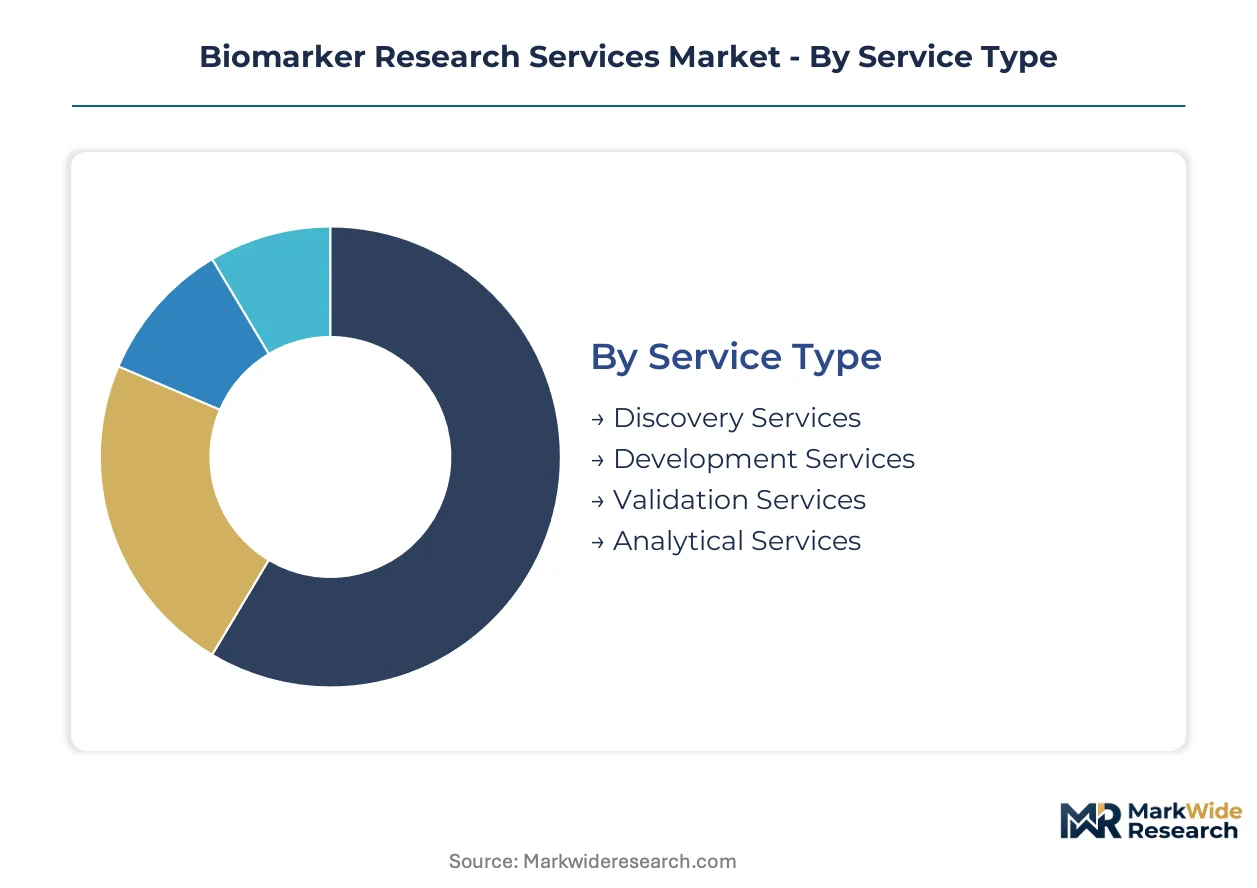
Biomarker research services fragment across four intersecting dimensions that determine contract specifications, regulatory pathways, and pricing structures. Service providers must align platform investments with the maturity curves of each segment combination.
Service Type:
Mature analytical workflows now dominate contract volume while emerging discovery methodologies capture premium pricing.
- Discovery Services:Hypothesis-free biomarker identification employs mass spectrometry, next-generation sequencing, and high-content screening to surface novel targets. Pharmaceutical sponsors in the United States concentrate demand here for immuno-oncology programs requiring de novo target elucidation. The segment commands extended timelines and milestone-based payment structures.
- Analytical Services:GLP-validated quantification of established biomarkers supports pharmacodynamic monitoring and patient stratification. Biotechnology firms outsource these functions to reduce fixed cost exposure on mass spectrometry and immunoassay platforms. Real-time data delivery now differentiates providers more than raw instrument throughput.
- Development Services:Assay optimization and pre-validation for clinical trial deployment.
- Validation Services:Regulatory-grade analytical qualification for companion diagnostic submissions.
Discovery Services retains volume leadership; Analytical Services holds the steepest expansion curve.
End User:
Customer procurement sophistication spans from centralized outsourcing mandates to fragmented academic purchasing.
- Pharmaceutical Companies:Integrated sponsors now embed biomarker strategies into Phase I protocols, requiring service providers to build parallel analytical validation capabilities. FDA companion diagnostics guidance accelerates co-development timelines. These buyers unbundle discovery from validation, fragmenting contracts across specialized providers.
- Biotechnology Firms:Capital-constrained developers prioritize scientific expertise over geographic convenience, concentrating procurement in United States-based Phase II trials. Single-cell RNA sequencing requirements for patient stratification drive demand for GLP-validated workflows.
- Academic Institutions:Exploratory research contracts with flexible deliverables and publication rights.
- Research Organizations:Non-profit and government-funded studies with standardized procurement protocols.
Pharmaceutical Companies anchor contract value; Biotechnology Firms are climbing the fastest as pipeline expansion accelerates outsourcing.
Technology:
Infrastructure investment intensity varies from commoditized genomics platforms to capital-light metabolomics entry points.
- Genomics:Mature next-generation sequencing infrastructure supports patient stratification and surrogate endpoint validation. The installed base of Illumina and Thermo Fisher platforms creates price compression for standard contracts. Cloud-native bioinformatics pipelines now compress analytical turnaround times.
- Metabolomics:Untargeted profiling via high-resolution mass spectrometry attracts emerging demand from immuno-oncology developers seeking pharmacodynamic markers without prior hypothesis constraints. Machine learning-based annotation tools reduce specialist labor requirements.
- Proteomics:Affinity-based proximity extension assays compete with traditional mass spectrometry for protein quantification.
- Transcriptomics:Single-cell RNA sequencing migrates from academic contexts into regulated clinical trial workflows.
Genomics maintains revenue concentration; Metabolomics shows the steepest trajectory as untargeted methods standardize.
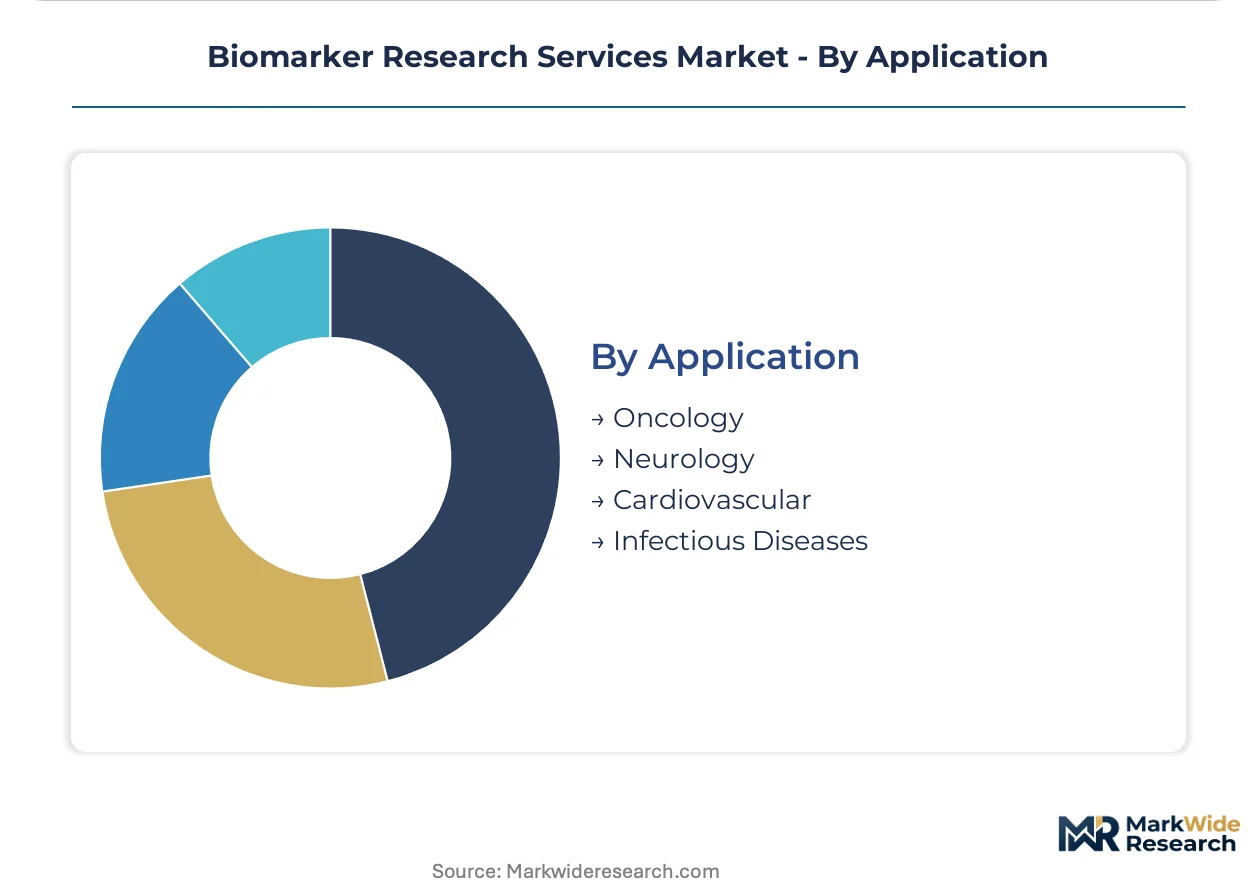
Application:
Disease-area maturity determines sample collection logistics and regulatory validation requirements.
- Oncology:Companion diagnostic co-development dominates current contract volume, with checkpoint inhibitor programs driving multiplexed immunoassay demand. FDA draft guidance on AI-enabled biomarker algorithms imposes premarket validation requirements on machine learning-based diagnostic outputs.
- Neurology:Cerebrospinal fluid collection protocols for neurodegenerative targets achieve cross-site harmonization, opening contractable volume in a previously fragmented application area. Biogen and Eli Lilly sponsors now require standardized tau and amyloid quantification across multi-site trials.
- Cardiovascular:Established biomarker panels for risk stratification with mature regulatory pathways.
- Infectious Diseases:Host response biomarker programs for sepsis and antimicrobial resistance monitoring.
Oncology commands the largest revenue pool; Neurology gains share fastest as protocol standardization reduces site qualification friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider capacity clusters in the United States, Germany, and Switzerland, with emerging nodes in China and India attracting contract migration for cost-sensitive discovery programs. Regulatory divergence between FDA and EMA qualification pathways creates arbitrage opportunities for sponsors selecting validation sites.
United States
Academic medical centers in Boston and the San Francisco Bay Area anchor high-complexity biomarker discovery contracts for immuno-oncology developers. FDA expanded companion diagnostics guidance accelerates co-development timelines, forcing service providers to build parallel analytical validation capabilities. The Research Triangle Park corridor in North Carolina concentrates CRO logistics infrastructure for decentralized trial sample collection.
Germany
EMA qualification pathway for novel methodologies reduces validation burden for innovative analytical platforms, drawing sponsors seeking accelerated commercial deployment. Munich and Heidelberg host specialized proteomics service clusters serving mid-cap European biotech firms. The country's national pharmaceutical regulator maintains stringent ISO 15189 accreditation requirements that extend facility qualification timelines.
Switzerland
Basel's pharmaceutical hub generates concentrated demand for GLP-validated biomarker quantification supporting neurodegenerative drug development. Swissmedic oversight harmonizes with EMA frameworks while preserving national flexibility for digital pathology validation. The Lake Geneva region attracts precision medicine startups requiring integrated genomics and metabolomics service bundles.
China
NMPA reform of clinical trial approval processes compresses study initiation timelines, redirecting regional sponsor demand toward domestic service providers. Shanghai and Suzhou biotech corridors build mass spectrometry capacity for pharmacodynamic monitoring of checkpoint inhibitors. The country's national pharmaceutical regulator increasingly recognizes ISO standards for biomarker assay validation.
India
CDSCO streamlined clinical trial regulations attract Western sponsors seeking cost-efficient biomarker discovery for exploratory programs. Hyderabad and Bengaluru CRO clusters specialize in genomics data generation with cloud-native bioinformatics pipelines. The country's national pharmaceutical regulator mandates local ethical review for sample export, creating infrastructure requirements for in-country analytical capacity.
Biomarker Research Services Market Competitive Environment
Integrated instrument-to-service providers and specialized analytical CROs split the market between platform ownership and scientific expertise. Thermo Fisher Scientific and QIAGEN anchor the consolidated tier through workflow integration, while mid-cap specialists compete on disease-area depth. Two strategic archetypes dominate: capital-intensive platform operators competing on throughput, and boutique providers competing on regulatory navigation. M&A activity concentrates in metabolomics capability acquisition and GLP certification expansion.
Among diversified life science conglomerates, F. Hoffmann-La Roche Ltd. and Thermo Fisher Scientific exemplify the integrated platform archetype, while Laboratory Corporation of America Holdings occupies a position emphasizing geographic density and patient access networks over instrument ownership. QIAGEN represents the automation-focused tier competing on sample-to-insight workflow standardization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| QIAGEN |
| Bio-Rad Laboratories |
| Laboratory Corporation of America Holdings |
| IQVIA |
| Agilent Technologies |
| Illumina |
| Others |
Value Chain & Pricing Dynamics
The Boston-San Francisco air freight corridor governs cold-chain logistics costs for time-sensitive biospecimens, concentrating pricing power with carriers serving academic medical centers while forcing service providers to absorb transport premiums or pass differential rates to sponsors based on collection site geography.
Pricing Analysis
ISO 15189 accreditation dictates the pricing tier structure across the biomarker research services landscape. Three-tier pricing structure across premium, standard, and economy levels separates GLP-validated companion diagnostic workflows from exploratory discovery services and basic analytical screening. Cost compression in the standard tier is intensifying because sponsor procurement teams now unbundle discovery from validation, fragmenting contract value. Biotechnology firms exhibit the highest price sensitivity, prioritizing scientific expertise over bundled service convenience, while pharmaceutical companies absorb premium rates for regulatory-grade documentation.
Supply Chain Analysis
Isotope-labeled standards and affinity reagents draw from concentrated European and North American specialty chemical manufacturers. Germany, Switzerland, and the United States anchor production of mass spectrometry-grade reagents, while China builds capacity for basic immunoassay components. Single-source vulnerability persists for deuterated internal standards used in quantitative proteomics. Distribution runs through CRO logistics networks that coordinate multi-site sample collection for decentralized trial models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent service providers face substitution pressure from cloud-native bioinformatics platforms that enable sponsor in-house analytics, requiring defensive capability investments to retain contract eligibility.
For Market Incumbents: Entrench platform stickiness by embedding real-time data delivery infrastructure with sponsor electronic data capture systems, countering the unbundling trend that fragments revenue concentration. Deepen backward integration into specialty reagent manufacturing to reduce exposure to European supply concentration. The priority lever centers on metabolomics capability acquisition that captures emerging demand from immuno-oncology developers.
For New Entrants and Emerging Players: Neurology biomarker standardization in cerebrospinal fluid collection protocols represents the most penetrable white-space opportunity, as cross-site harmonization now enables contractable volume previously fragmented by protocol variability. Target academic medical center partnerships that anchor high-complexity discovery contracts without requiring full GLP infrastructure. A go-to-market angle emphasizing machine learning-based annotation tools for untargeted metabolomics profiling differentiates against capital-intensive instrument ownership.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core analytical service divisions with embedded GLP certification and established pharmaceutical sponsor relationships. Long-term viability hinges on regulatory navigation capabilities that compound over multi-year companion diagnostic co-development cycles. The signal to watch is FDA draft guidance finalization on artificial intelligence-enabled biomarker algorithms, which would accelerate consolidation around providers with pre-validated machine learning workflows.
| Strategic Initiative | Industry Significance |
|---|---|
| Metabolomics Capability Acquisition | Captures emerging demand from immuno-oncology developers seeking pharmacodynamic markers without prior hypothesis constraints. |
| GLP Certification Expansion | Enables migration of single-cell RNA sequencing from academic contexts into regulated pharmaceutical trial workflows. |
| Real-Time Data Infrastructure Deployment | Differentiates providers as sponsor procurement prioritizes data delivery speed over raw instrument throughput. |
| Companion Diagnostic Co-Development Partnership | Aligns service capabilities with FDA expanded guidance accelerating biomarker-guided Phase I protocol embedding. |
| Decentralized Trial Logistics Integration | Redistributes sample collection infrastructure from central laboratories to regional clinical sites across North American CRO networks. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, CRO procurement managers, and biomarker scientists and secondary sources including FDA guidance documents, EMA qualification pathway submissions, ClinicalTrials.gov protocol registries, and ISO accreditation databases anchors the qualitative findings. Bottom-up service provider capacity modeling triangulates against top-down pharmaceutical R&D outsourcing expenditure patterns.
Calibration against historical biomarker adoption curves in oncology and neurology therapeutic areas shapes the analytical framework across the projection horizon. Segmentation dimensions include service type maturity, end-user procurement sophistication, technology infrastructure intensity, and disease-area regulatory pathway status. CAGRs derive from sponsor pipeline expansion rates and outsourcing penetration assumptions, with immuno-oncology program density and decentralized trial adoption serving as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native diagnostic platforms or instrument manufacturers into direct service provision would shift outcomes. Material shifts in FDA artificial intelligence guidance finalization or EMA novel methodology qualification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Cell Line Development Market