
 Global Culture Media Market | 2026-2036
Global Culture Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Culture Media Market Analysis
South Korea's biologics manufacturing corridor is fragmenting as new entrants challenge incumbent supply structures. Spotify leverages its podcast infrastructure to distribute science communication content that shapes researcher awareness of media innovations. Netflix competes through documentary financing that elevates public understanding of biotechnology processes. ByteDance anchors short-form educational content targeting laboratory technicians in emerging biotech clusters.
Culture media comprises nutrient formulations designed to support cell growth, proliferation, and maintenance in controlled environments, typically containing amino acids, vitamins, salts, glucose, and serum supplements balanced to specific pH and osmolality parameters. The primary industrial purpose centers on enabling reproducible biological production for vaccines, monoclonal antibodies, and cell therapies. Liquid media dominates high-volume biopharmaceutical production due to scalability in stirred-tank bioreactors, while specialized media captures expanding margin pools as gene therapy workflows demand chemically defined, serum-free formulations. Solid media retains structural importance in environmental testing and quality control laboratories where colony visualization remains essential.
FDA guidance on chemistry, manufacturing, and controls together with EU MDR traceability requirements and ISO 13485 quality management standards collectively elevate compliance costs for media suppliers seeking biopharmaceutical market access. The EPA monitors wastewater discharge from large-scale fermentation facilities, adding environmental permitting layers to capacity expansion decisions. Stakeholders must weigh regulatory divergence between FDA and EMA purity standards when configuring regional supply footprints.
Market Dynamics
Specialized media formulations are compressing the competitive set as biopharmaceutical manufacturers demand chemically defined, serum-free inputs that meet tightening FDA and EMA purity benchmarks. This regulatory ratchet is forcing suppliers to reconfigure manufacturing footprints and deepen analytical capabilities.
Growth Catalysts
- Cell therapy manufacturing scale-up:Autologous and allogeneic cell therapy workflows require patient-specific media formulations that command premium positioning and recurring revenue streams.
- FDA chemistry, manufacturing, and controls guidance:The agency's evolving CMC expectations for gene therapy vectors drive demand for documented, traceable media components with verified absence of adventitious agents.
- South Korea biologics corridor expansion:Samsung Biologics and Celltrion anchor capacity builds that concentrate regional demand for high-volume liquid media in stirred-tank configurations.
Market Restraints
- Raw material concentration risk:Recombinant protein and growth factor supply chains concentrate in a limited supplier base, exposing media formulators to input cost volatility and allocation constraints.
- Serum supply geographic dependence:Fetal bovine serum sourcing remains tied to specific cattle-producing regions with variable BSE surveillance protocols, complicating security of supply.
- ISO 13485 certification timeline:The 12-18 month pathway to quality management system certification creates friction for new entrants seeking biopharmaceutical market access.
Strategic Opportunities
- India biologics manufacturing emergence:The country's PLI scheme for pharmaceuticals attracts greenfield investments that will require localized media supply partnerships and technical service infrastructure.
- Perfusion culture system adoption:Continuous bioprocessing workflows demand specialized feed formulations with concentrated nutrient profiles and optimized osmolality for high-density cell retention.
- EU Green Deal chemical sustainability mandates:REACH registration requirements and bio-based content targets create openings for suppliers with renewable sourcing credentials and circular manufacturing models.
Industry Challenges
- Cell culture scientist talent scarcity:Formulation development and applications support roles require hybrid expertise in cell biology, analytical chemistry, and regulatory documentation that outpaces graduate program output.
- Legacy ERP integration complexity:Electronic batch record systems and environmental monitoring platforms from incumbent automation vendors resist seamless connection to modern cloud-based quality management tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Culture Media Market |
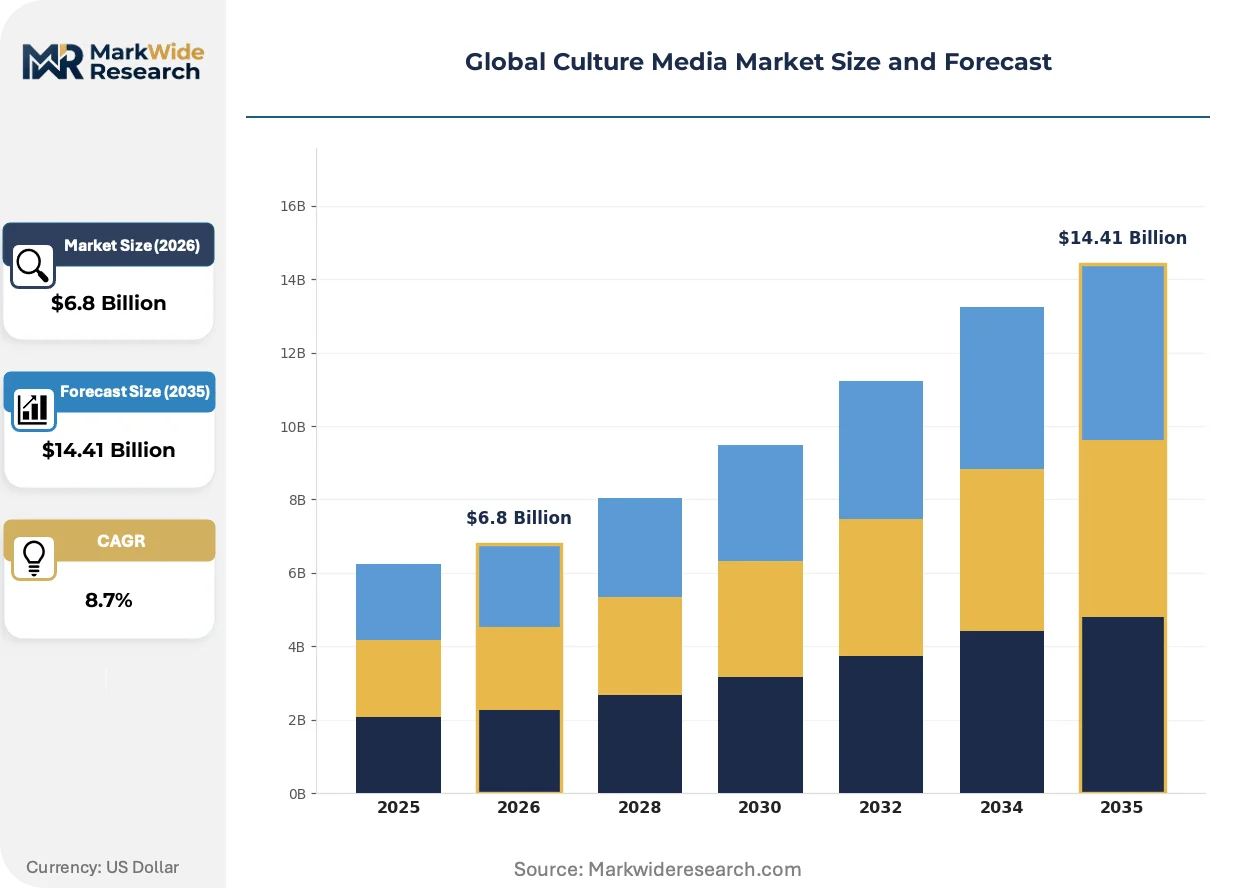
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Media, Solid Media, Semi-Solid Media, Specialized Media Application: Biotechnology, Pharmaceutical Production, Research Laboratories, Environmental Testing End User: Academic Institutions, Contract Research Organizations, Biopharmaceutical Companies, Clinical Labs Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Spotify, Canva, Netflix, Substack, Kuaikan Manhua, ByteDance, Roblox, Minute Media, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Culture Media Market Emerging Trajectories
Automation and analytics convergence is restructuring how media formulations are developed, qualified, and supplied to biopharmaceutical manufacturers. These shifts compress development timelines and elevate performance expectations.
Artificial intelligence-driven formulation design is collapsing the experimental space that traditional Design of Experiments methods require. Machine learning models trained on historical cell line performance data predict optimal nutrient concentrations across multiple parameters simultaneously. Biopharmaceutical process development groups at contract manufacturing organizations are adopting these platforms to accelerate clone selection and media matching workflows.
EMA's updated Annex 1 guidelines on sterile manufacturing impose environmental monitoring and contamination control requirements that extend to media preparation areas. The regulation mandates continuous viable particle monitoring and rapid microbial detection methods that increase capital intensity for media suppliers. German and Swiss manufacturing sites are retrofitting isolator-based filling lines to meet the 2023 implementation deadlines.
Consolidated procurement through group purchasing organizations is concentrating buying power among the largest biopharmaceutical manufacturers. These entities negotiate multi-year supply agreements with tiered pricing structures that bundle media, sera, and reagents under single-source contracts. The shift is most visible in the United States, where top-ten biologics producers now account for a disproportionate share of high-volume liquid media volumes.
Global Culture Media Market Segmentation
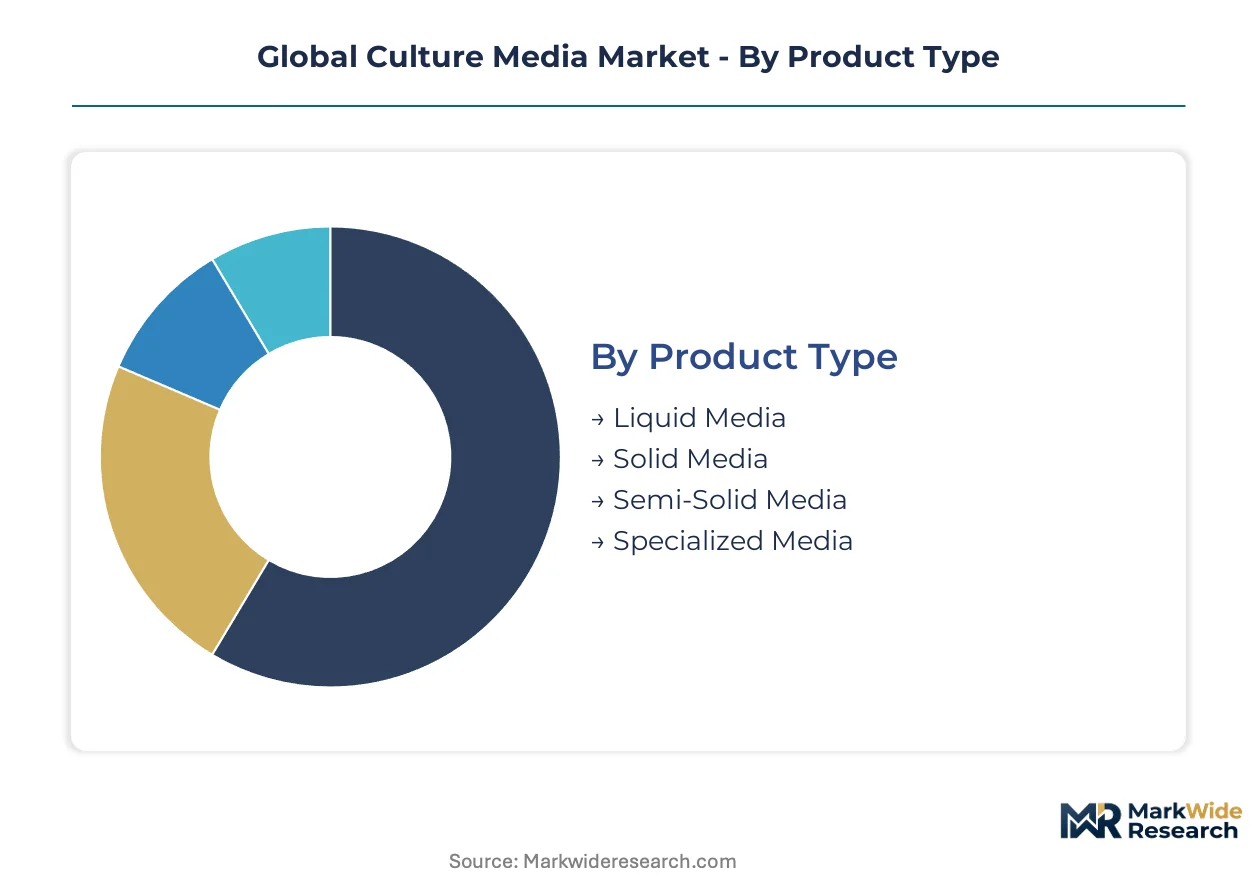
Segmentation in culture media separates mature commodity formats from emerging specialized formulations, each commanding distinct margin profiles and regulatory scrutiny. Biopharmaceutical procurement teams weight technical specifications against supply security when allocating across these categories.
Product Type:
Mature liquid formats dominate bioprocessing volume while specialized media emerge as the margin expansion frontier for gene therapy applications.
- Liquid Media:Aqueous nutrient solutions formulated for stirred-tank bioreactor compatibility, with pH buffering and osmolality calibrated for high-density mammalian cell culture. Samsung Biologics and Celltrion in South Korea anchor concentrated demand for industrial-scale liquid formats as they expand antibody production capacity.
- Specialized Media:Chemically defined, serum-free formulations engineered for specific cell types including CAR-T workflows and stem cell expansion, with documented absence of adventitious agents per FDA chemistry, manufacturing, and controls guidance. These formulations command premium positioning as autologous cell therapy manufacturing scales.
- Solid Media:Agar-based or gelatinous substrates enabling colony visualization for microbial identification and environmental monitoring applications.
- Semi-Solid Media:Intermediate viscosity formulations supporting motility testing and selective enrichment protocols in quality control laboratories.
Liquid media retains volume leadership; specialized media holds the steepest expansion curve.
Application:
Cost tier separation distinguishes high-volume production workflows from research-scale consumption patterns with divergent specification intensity.
- Pharmaceutical Production:GMP-grade media supply for commercial biologics manufacturing with full batch documentation, environmental monitoring integration, and validated sterility assurance. Facilities in Germany and Switzerland face EMA Annex 1 compliance deadlines that reshape supplier qualification requirements.
- Biotechnology:Process development and clinical-stage manufacturing media with flexible formulation services and rapid turnaround for cell line optimization. Contract manufacturing organizations in the United States drive demand for media matching platforms that accelerate clone selection.
- Research Laboratories:Non-GMP media for exploratory cell biology with broader catalog availability and lower documentation burden.
- Environmental Testing:Standardized formulations for regulatory compliance monitoring of water, food, and pharmaceutical manufacturing environments.
Pharmaceutical production absorbs the largest value share; biotechnology applications are expanding most quickly.
End User:
Customer type fragmentation creates distinct service models from technical consultation for large manufacturers to catalog distribution for academic buyers.
- Biopharmaceutical Companies:Integrated manufacturers and virtual developers requiring customized media development, applications support, and long-term supply agreements with tiered pricing structures. Top-ten United States biologics producers now consolidate procurement through group purchasing organizations.
- Contract Research Organizations:Service providers needing rapid media matching for diverse client cell lines and flexible volume scaling across project phases.
- Academic Institutions:Price-sensitive researchers purchasing catalog formulations through grant-funded procurement with limited technical service requirements.
- Clinical Labs:Diagnostic applications with regulatory compliance needs for in-vitro diagnostic media manufacturing.
Biopharmaceutical companies command the deepest supplier relationships; contract research organizations are gaining share fastest.
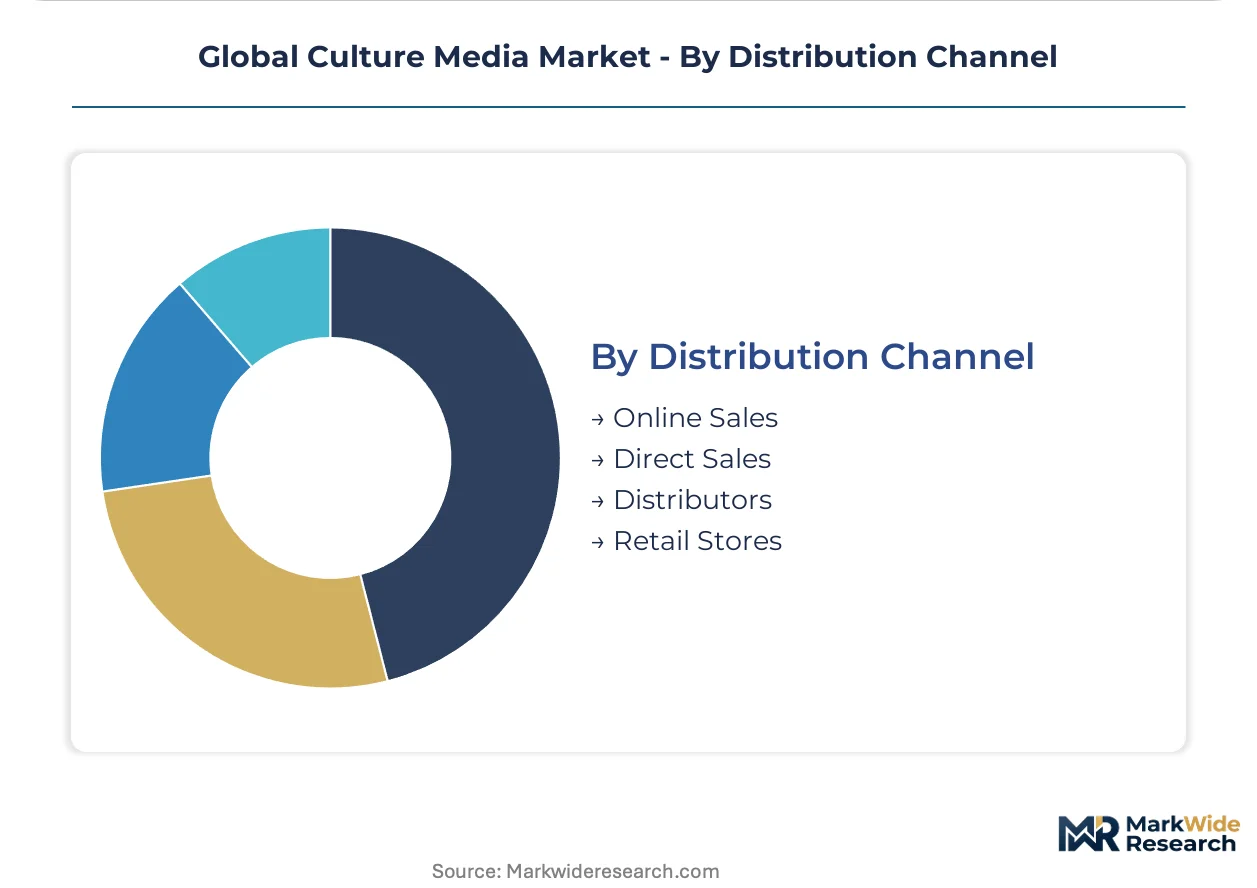
Distribution Channel:
Supply concentration varies from direct manufacturer relationships for large accounts to fragmented distributor networks serving geographic peripheries.
- Direct Sales:Manufacturer-to-customer relationships for high-volume biopharmaceutical accounts with dedicated technical service, custom formulation development, and electronic batch record integration. These partnerships dominate in Germany, the United States, and South Korea where production capacity concentrates.
- Distributors:Regional inventory and logistics partners extending reach to mid-tier manufacturers and emerging biotech clusters in India and other developing markets.
- Online Sales:E-commerce platforms for research-scale catalog orders with standardized specifications and rapid fulfillment.
- Retail Stores:Limited presence for basic educational and small laboratory supply needs.
Direct sales retains the highest value concentration; distributor partnerships are climbing the fastest as geographic coverage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. South Korea and Germany favor high-volume liquid formats for antibody manufacturing, while the United States and Switzerland concentrate specialized media spend on cell therapy workflows. India absorbs basic research-grade formulations through academic and emerging biotech channels.
United States
FDA chemistry, manufacturing, and controls guidance drives specification intensity for gene therapy media. The agency's evolving traceability requirements favor suppliers with documented adventitious agent testing. Greater Boston and San Francisco Bay Area clusters anchor demand for chemically defined, serum-free formulations as autologous cell therapy manufacturing scales.
Germany
EMA Annex 1 sterile manufacturing deadlines reshape supplier qualification requirements for GMP-grade media. The country's national pharmaceutical regulator enforces continuous viable particle monitoring mandates that increase capital intensity. Bavarian and North Rhine-Westphalian manufacturing sites retrofit isolator-based filling lines to meet compliance timelines.
South Korea
Samsung Biologics and Celltrion anchor concentrated demand for industrial-scale liquid media in stirred-tank configurations. The MFDS tightens purity benchmarks for cell culture inputs used in export-oriented biologics. The Songdo and Incheon bioclusters expand capacity builds that require localized high-volume supply partnerships.
Switzerland
Swissmedic quality frameworks elevate compliance costs for media suppliers seeking biopharmaceutical market access. The country's regulatory divergence from FDA purity standards complicates regional supply footprint decisions. Basel and Zurich manufacturing corridors specialize in chemically defined formulations for contract manufacturing organizations.
India
The PLI scheme for pharmaceuticals attracts greenfield biologics investments that will require localized media supply partnerships. CDSCO quality benchmarks for imported cell culture inputs lag OECD standards, creating dual-track procurement patterns. Maharashtra and Karnataka biotech clusters absorb research-grade formulations through grant-funded academic channels.
Global Culture Media Market Vendor Landscape
Capability concentration sits with specialized formulation developers; scale advantage sits with diversified life sciences conglomerates. The vendor base stratifies across three tiers: integrated chemical suppliers with backward integration into raw materials, focused media specialists with applications support infrastructure, and regional distributors serving price-sensitive research markets. Dominant competitive moves include capacity expansion in high-growth biologics corridors and strategic partnerships to secure recombinant protein supply chains.
Among technology-platform conglomerates, ByteDance and Netflix occupy positions that exemplify non-traditional competitive pressure through educational content distribution. Spotify represents the audio-channel archetype for science communication that shapes researcher awareness. These entities do not manufacture culture media directly, yet their content infrastructure influences procurement decision-maker education and vendor discovery patterns across emerging biotech clusters.
| Leading Market Players |
|---|
| Spotify |
| Canva |
| Netflix |
| Substack |
| Kuaikan Manhua |
| ByteDance |
| Roblox |
| Minute Media |
| Epic Games |
| Others |
Supply Flow & Price Mechanics
Recombinant protein and growth factor suppliers in the United States and Switzerland concentrate upstream input costs, directing margin capture toward downstream media formulators with captive analytical capabilities and GMP-certified manufacturing footprints. This upstream bottleneck forces biopharmaceutical procurement teams to accept tiered contract structures that embed long-term supply security premiums.
Pricing Analysis
Long-term offtake agreements dominate high-volume liquid media procurement, with Samsung Biologics and Celltrion locking multi-year supply contracts that bundle media, sera, and reagents under single-source arrangements. Three-tier pricing structure across premium, standard, and economy levels separates chemically defined specialized formulations from research-grade catalog products, with ISO 13485 certification and FDA CMC documentation commanding substantial premiums. Cost compression in research-grade segments is intensifying because academic buyers consolidate purchasing through grant-funded procurement platforms. Contract research organizations exhibit highest price sensitivity due to project-based funding cycles, while commercial biopharmaceutical manufacturers prioritize supply security over unit cost optimization.
Supply Chain Analysis
Contract manufacturing concentration sits with Lonza, Thermo Fisher, and Sartorius, whose GMP-grade media production facilities in Germany, Switzerland, and South Korea anchor regional supply security. Raw material sourcing draws from recombinant protein producers in the United States, fetal bovine serum collectors in Australia and New Zealand, and amino acid manufacturers in China and Japan. Single-source vulnerability in growth factor supply chains exposes formulators to allocation constraints during capacity expansion cycles. Distribution runs through direct manufacturer relationships for top-tier biopharmaceutical accounts, with regional distributors extending reach to emerging biotech clusters in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation development scientists with hybrid expertise in cell biology, analytical chemistry, and regulatory documentation represent the critical capability gap constraining market expansion. The shortage of qualified applications support personnel limits supplier scale-up velocity and creates competitive vulnerability for incumbents unable to staff technical service teams.
For Market Incumbents: Insulate market position by deepening backward integration into recombinant protein supply chains and securing captive production of growth factors that currently concentrate among limited suppliers. Expand isolator-based filling capacity in Germany and Switzerland ahead of EMA Annex 1 implementation deadlines. Prioritize certification investment in ISO 13485 quality management systems to maintain biopharmaceutical market access against emerging competitors. For New Entrants and Emerging Players: Build out technical service infrastructure targeting India's PLI-driven biologics manufacturing expansion, where localized media supply partnerships remain underdeveloped. Focus initial penetration on contract research organizations seeking rapid media matching capabilities for diverse client cell lines. Establish go-to-market presence through distributor partnerships rather than direct sales investment to minimize fixed cost exposure. For Investors and Strategic Acquirers: Capital is best deployed toward specialized media formulators with demonstrated chemically defined formulation capabilities and existing FDA CMC documentation libraries. Long-term viability hinges on exposure to autologous cell therapy manufacturing workflows rather than commoditized antibody production media. Watch for inflection signals in perfusion culture system adoption rates, which concentrate demand for high-nutrient feed formulations with premium margin profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Samsung Biologics and Celltrion capacity builds concentrate regional demand for industrial-scale liquid formats. |
| Regulatory Approval Pathway | FDA CMC guidance and EMA Annex 1 compliance reshape supplier qualification requirements across GMP-grade segments. |
| Backward Integration | Captive recombinant protein production insulates formulators from growth factor supply allocation constraints. |
| Long-term Supply Agreement | Group purchasing organizations consolidate procurement power among top-ten United States biologics producers. |
| Geographic Expansion | India's PLI scheme attracts greenfield investments requiring localized media supply partnerships. |
Methodological Framework
Initial hypotheses were tested against primary input from cell culture scientists, biopharmaceutical procurement managers, regulatory affairs directors, and contract manufacturing organization executives and refined through secondary validation against FDA guidance documents, EMA Annex 1 guidelines, ISO 13485 certification records, and SEC filings from publicly traded life sciences conglomerates. Bottom-up demand modeling triangulated against top-down market sizing approaches.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application tier, end-user category, and distribution channel. CAGRs were derived from modeled growth trajectories in cell therapy manufacturing scale-up and biologics capacity expansion. Industry-specific forecast inputs incorporated perfusion culture adoption rates and EMA Annex 1 compliance capital expenditure cycles.
Stress conditions across raw material cost volatility, regulatory timeline acceleration, and biopharmaceutical manufacturing capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cell therapy commercialization velocity and biologics outsourcing patterns. Quarterly review of FDA CMC guidance evolution and EMA Annex 1 enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Acetylglucosamine Market