
 Bioprocessing Analytics Equipment Market | 2026-2036
Bioprocessing Analytics Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprocessing Analytics Equipment Market Analysis
Contract Manufacturing Organizations are gaining procurement share as biopharma demand for outsourced analytics is bifurcating away from captive pharmaceutical laboratories. Thermo Fisher Scientific leverages its chromatography portfolio to dominate high-throughput process development workflows. Sartorius anchors European demand through integrated bioreactor sensor systems that reduce offline sampling requirements. Danaher Corporation competes across mass spectrometry and microbial analysis platforms through its operating company structure.
Bioprocessing analytics equipment encompasses sensors, analyzers, and software platforms designed to measure critical process parameters in real time, typically operating at measurement ranges from dissolved oxygen probes to multi-angle light scattering detectors for aggregate quantification. These systems enable closed-loop control of cell culture and purification operations, reducing batch failure rates while supporting continuous manufacturing transitions. Sensors and analyzers command the largest installed base, though software for multivariate data analysis is expanding fastest as facilities adopt digital twin architectures. Chromatography systems retain the deepest margin pools due to consumables lock-in, while mass spectrometry is displacing offline HPLC methods for at-line protein characterization.
FDA process analytical technology guidance and EMA's quality by design framework mandate real-time monitoring for commercial biologics approval, directly shaping equipment validation requirements and supplier qualification timelines. ISO 13485 and GAMP 5 software validation standards further constrain vendor entry by demanding documented software lifecycle controls for analytics platforms. Stakeholders must monitor how AI-enabled predictive algorithms will redefine regulatory expectations for automated batch release decisions.
Market Dynamics
Real-time release testing mandates from FDA process analytical technology guidance are compressing validation timelines and forcing equipment suppliers to pre-integrate software qualification packages with hardware shipments.
Growth Catalysts
- Continuous manufacturing transitions:Biologics facilities in Massachusetts and North Carolina are retrofitting stainless steel trains with at-line mass spectrometry to eliminate hold steps between unit operations.
- EMA quality by design framework:European commercial approval pathways now require multivariate statistical process control documentation, driving demand for integrated data analytics platforms.
- Cell and gene therapy expansion:Viral vector manufacturers require specialized in-process analytics for empty-to-full capsid ratios, creating dedicated equipment procurement streams.
Market Restraints
- Consumables lock-in costs:Chromatography column replacement cycles and proprietary buffer formulations from dominant suppliers create switching friction for mid-scale manufacturers.
- Single-source sensor dependencies:Dissolved oxygen and pH probe supply concentrates among three German and Swiss component houses, exposing buyers to allocation risk.
- GAMP 5 validation burden:Software lifecycle documentation requirements extend vendor qualification timelines by 8-14 months for new analytics platform introductions.
Strategic Opportunities
- India biologics manufacturing buildout:CDMO investments in Hyderabad and Bengaluru lack mature process analytical technology infrastructure, creating first-mover equipment installation windows.
- AI-enabled predictive release:Machine learning algorithms trained on batch history are converging with spectroscopic sensors to enable parametric release without end-point testing.
- Modular skid architectures:Pre-validated analytics modules reduce facility-specific engineering, opening sales channels to emerging biotechs without internal automation expertise.
Industry Challenges
- Multivariate statistics expertise gap:Facilities struggle to hire data scientists capable of interpreting principal component analysis outputs for batch deviation investigations.
- Legacy DCS integration complexity:Brownfield sites running 1990s-era distributed control systems face protocol mismatches when connecting modern OPC-UA analytics devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprocessing Analytics Equipment Market |
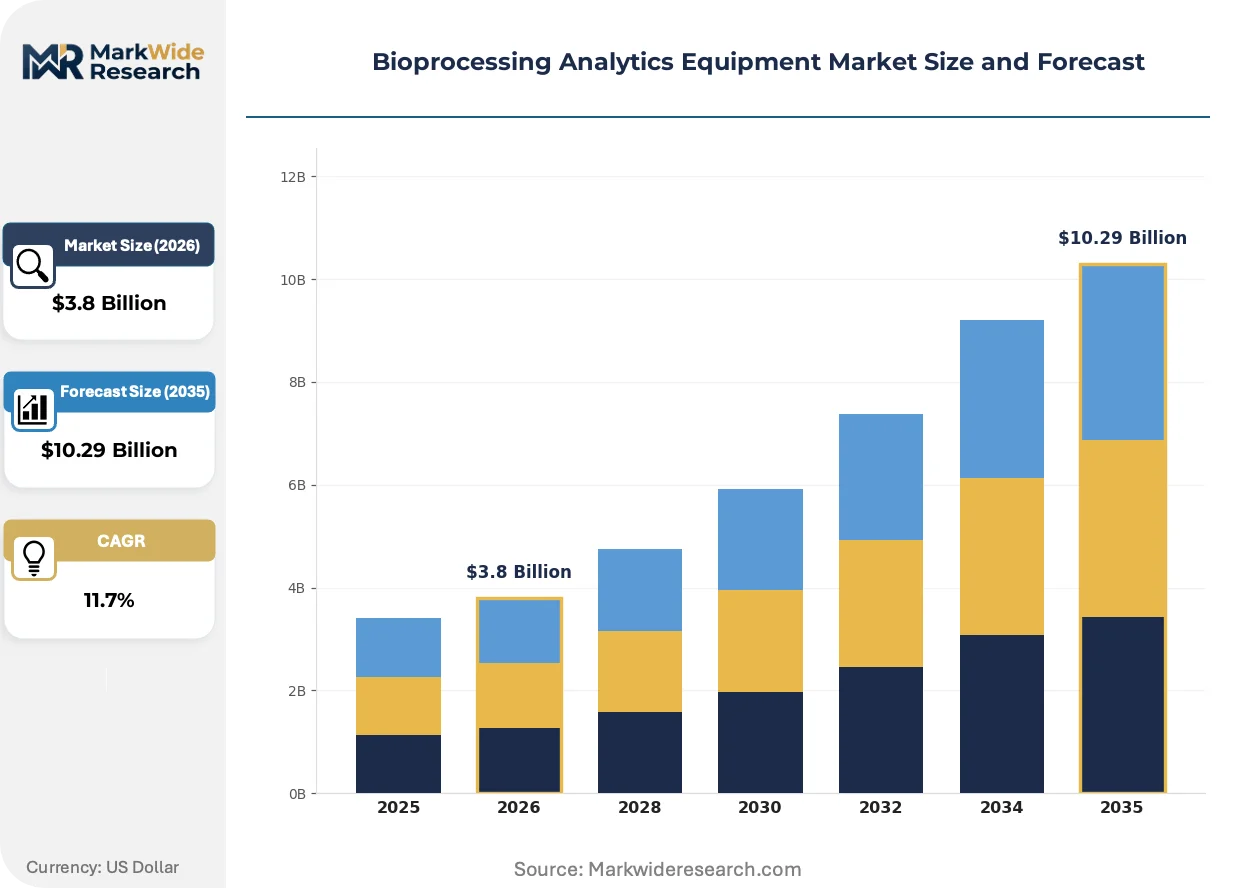
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Software, Flow Meters, Analyzers End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Technology: Chromatography, Mass Spectrometry, Spectroscopy, Microbial Analysis Application: Quality Control, Process Development, Process Optimization, Bioreactor Monitoring |
| Companies Covered | Thermo Fisher Scientific, Sartorius, Agilent Technologies, Cytiva, Bio-Rad Laboratories, Danaher Corporation, Merck KGaA, Waters Corporation, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprocessing Analytics Equipment Market Emerging Trajectories
Bioprocessing analytics is pivoting from offline quality control to embedded process control, with sensor miniaturization and cloud-native data architectures enabling distributed manufacturing networks.
Raman spectroscopy is fragmenting the protein titer measurement landscape. Single-use bioreactor manufacturers in California and Massachusetts are embedding 785nm probes directly into bag films for glucose and lactate monitoring. This bypasses sterile sampling interfaces and compresses feedback loop latency from hours to minutes.
FDA process analytical technology guidance is tightening software validation expectations. The 2023 revision emphasizes continuous verification for algorithm-driven control loops, forcing vendors to submit updated master files for AI-enabled analytics. European manufacturers are responding by pre-validating multivariate models against EMA's quality by design submission templates.
Equipment-as-a-service contracting is displacing capital purchase models for high-end mass spectrometry. CDMOs in Germany and Switzerland now lease quadrupole time-of-flight systems with bundled method development and regulatory support. This shifts balance sheet treatment and aligns vendor incentives with uptime performance rather than hardware shipment margins.
Bioprocessing Analytics Equipment Market Segmentation
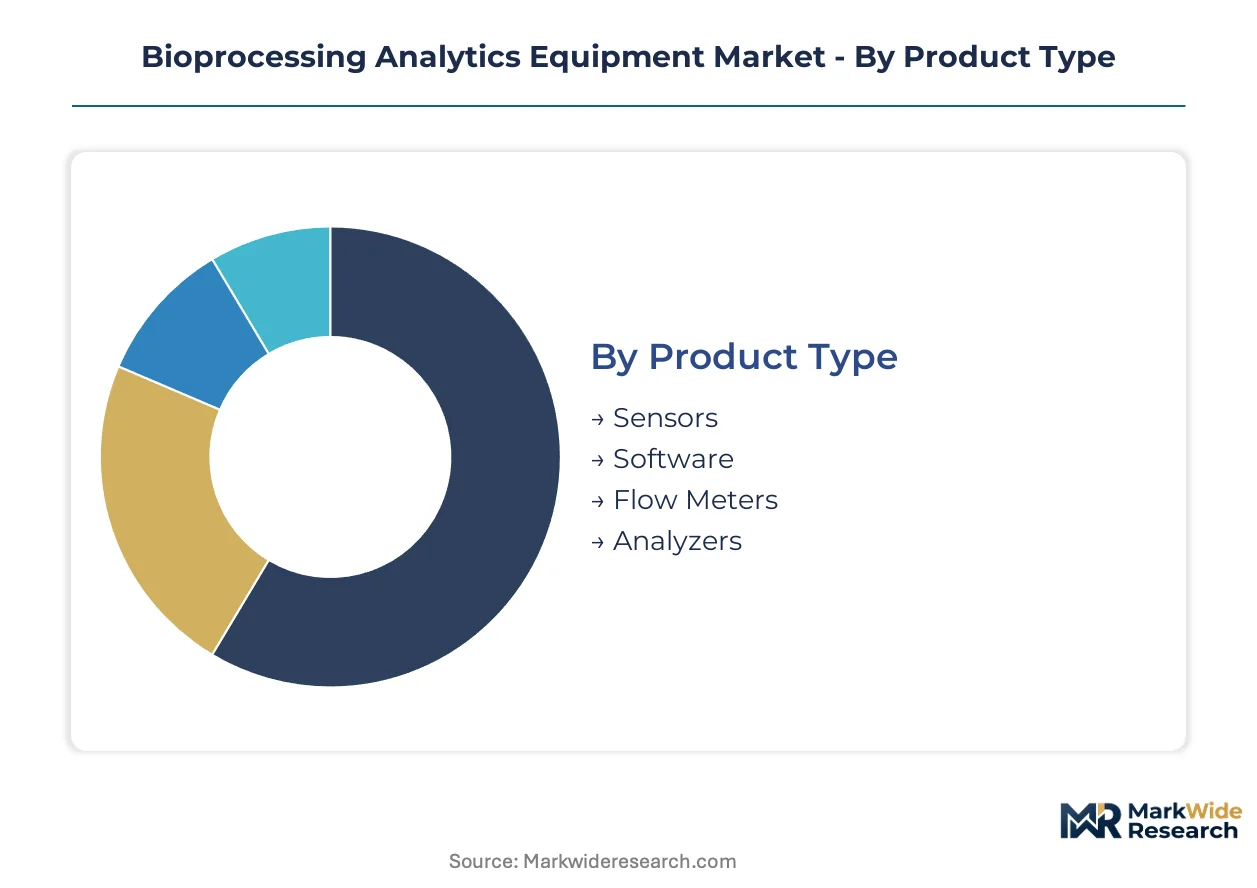
Equipment segmentation in bioprocessing analytics reflects divergent procurement patterns between mass-market sensor deployments and specialized analytical platforms. Vendors must align R&D pipelines with distinct validation requirements across product categories while navigating varying customer technical sophistication.
Product Type:
Sensors dominate domestic manufacturing footprints in the United States and Germany, while software platforms increasingly serve export-led distributed production networks in India and Southeast Asia.
- Sensors:Dissolved oxygen, pH, and conductivity probes constitute the foundational measurement layer for bioreactor control. Pharmaceutical facilities in Massachusetts and North Carolina deploy these at scale for monoclonal antibody production, though single-source dependencies on German and Swiss component houses create procurement vulnerability.
- Analyzers:At-line mass spectrometry and chromatography systems enable real-time titer and impurity quantification. Biotechnology firms in California and Switzerland drive demand for these capital-intensive platforms as they transition from batch to continuous manufacturing paradigms.
- Software:Multivariate data analysis platforms integrate sensor streams for predictive process control.
- Flow Meters:Single-use and stainless steel variants monitor perfusion rates and harvest operations.
Sensors command the established base. The steepest expansion runs through software platforms.
End User:
Cost tier stratification separates high-volume pharmaceutical buyers from mid-scale biotechnology firms and research institutions with constrained capital budgets.
- Contract Manufacturing Organizations:CDMOs in Germany, Switzerland, and India are expanding dedicated analytics capabilities to capture biopharma outsourcing demand. These organizations prioritize equipment-as-a-service contracting models to preserve balance sheet flexibility while accessing high-end mass spectrometry.
- Pharmaceutical Companies:Large-cap biologics manufacturers in the United States deploy integrated process analytical technology infrastructure across multi-product facilities. Their captive laboratories drive standardization requirements that shape vendor qualification protocols industry-wide.
- Biotechnology Firms:Emerging developers in California and Massachusetts favor modular skid architectures with pre-validated analytics modules.
- Research Institutions:Academic and government laboratories focus on early-stage method development rather than GMP-compliant production analytics.
Pharmaceutical companies anchor the revenue base. The steepest volume gains are concentrating in contract manufacturing organizations.
Technology:
Application maturity separates established chromatography methods from emerging spectroscopic techniques gaining share in at-line deployment scenarios.
- Chromatography:HPLC and UPLC systems retain the deepest margin pools through consumables lock-in, with proprietary column chemistries and buffer formulations creating substantial switching costs. These systems dominate quality control workflows in FDA-regulated commercial facilities.
- Mass Spectrometry:Quadrupole time-of-flight and Orbitrap platforms are displacing offline HPLC for protein characterization. European CDMOs in Germany and Switzerland increasingly lease these systems with bundled regulatory support rather than capital purchase.
- Spectroscopy:Raman and near-infrared probes enable non-invasive glucose and lactate monitoring in single-use bioreactors.
- Microbial Analysis:Rapid microbial detection systems address sterility testing requirements for cell and gene therapy vectors.
Chromatography commands the installed revenue base. Mass spectrometry is climbing the fastest as continuous manufacturing adoption accelerates.
Application:
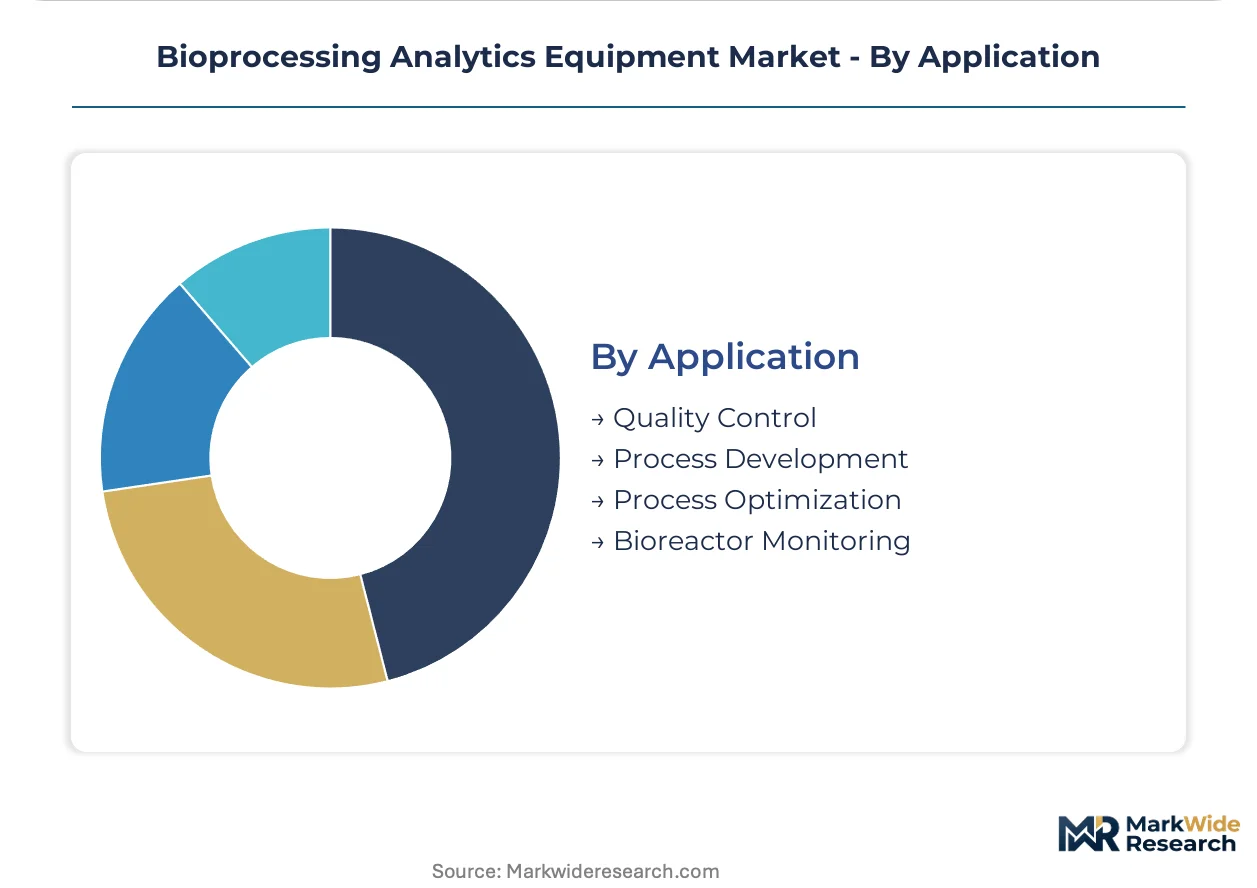
Customer type differentiation separates validated commercial production workflows from exploratory process development activities with distinct regulatory and technical requirements.
- Bioreactor Monitoring:Real-time dissolved oxygen, pH, and viable cell density measurement enables closed-loop control of fed-batch and perfusion cultures. Facilities in North Carolina and Massachusetts embed sensor arrays directly into single-use bag films to eliminate sterile sampling interfaces.
- Quality Control:Release testing for identity, purity, and potency mandates validated analytical methods with documented software lifecycle controls per GAMP 5 standards. This application concentrates procurement among established vendors with regulatory master files on record.
- Process Development:High-throughput screening of cell culture conditions and purification schemes drives demand for automated sampling and analysis platforms.
- Process Optimization:Multivariate statistical process control identifies design space boundaries for quality by design submissions to EMA and FDA.
Quality control commands the established base. The steepest expansion trajectory runs through bioreactor monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss component houses export dissolved oxygen and pH probes to biologics facilities in Massachusetts and North Carolina, establishing a transatlantic trade corridor that shapes equipment availability timelines for North American manufacturers.
United States
FDA process analytical technology guidance mandates real-time monitoring for commercial biologics approval, compressing validation timelines for equipment suppliers. Massachusetts and North Carolina host concentrated monoclonal antibody production clusters where facilities retrofit stainless steel trains with at-line mass spectrometry. CDMOs in these states increasingly favor equipment-as-a-service contracting to preserve balance sheet flexibility.
Germany
EMA quality by design framework requires multivariate statistical process control documentation for European commercial approval pathways. Bavaria and Baden-Württemberg anchor the continent's deepest biologics manufacturing footprints, with Sartorius leveraging integrated bioreactor sensor systems to reduce offline sampling requirements. German CDMOs drive standardization requirements that shape vendor qualification protocols across the European market.
China
NMPA regulatory alignment with international process analytical technology standards accelerates domestic equipment adoption for biologics export compliance. Yangtze River Delta and Pearl River Delta manufacturing zones expand viral vector production capacity for cell and gene therapy applications. Domestic suppliers face qualification barriers as multinational pharmaceutical companies enforce global equipment standardization.
Switzerland
Swissmedic oversight of commercial biologics manufacturing reinforces stringent software validation expectations per GAMP 5 standards. Basel and Zurich host precision sensor manufacturing clusters supplying global bioreactor control systems. Swiss CDMOs lease quadrupole time-of-flight mass spectrometry with bundled regulatory support rather than capital purchase.
India
CDSCO biologics manufacturing guidelines create regulatory pathways for process analytical technology infrastructure deployment. Hyderabad and Bengaluru CDMO investments lack mature real-time monitoring capabilities, opening first-mover equipment installation windows. Domestic manufacturers confront single-source sensor dependencies that expose procurement to allocation risk.
Bioprocessing Analytics Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and software validation capabilities, creating a tiered structure where scale-driven public companies anchor high-throughput segments while private firms occupy specialized niches. The market consolidates around chromatography and mass spectrometry platforms with consumables lock-in, though sensor component supply concentrates among a handful of European component houses. Three archetypes dominate: integrated life science conglomerates with broad analytical portfolios, precision instrumentation specialists with deep regulatory master files, and modular platform vendors targeting emerging biotechnology firms. Competitive dynamics center on pre-integrated software qualification packages and equipment-as-a-service contracting models that shift customer relationships from transactional hardware sales to ongoing performance partnerships.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven positioning across complementary analytical modalities. Sartorius occupies a distinct position as a European-anchored specialist with integrated bioreactor sensor capabilities. These three entities represent divergent strategic postures: Thermo Fisher leverages chromatography dominance for consumables recurring revenue, Danaher competes through operating company structure across mass spectrometry and microbial analysis, and Sartorius reduces offline sampling requirements through embedded sensor systems. Their collective presence shapes vendor qualification timelines and regulatory master file availability industry-wide.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius |
| Agilent Technologies |
| Cytiva |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Merck KGaA |
| Waters Corporation |
| Shimadzu Corporation |
| Others |
Supply Flow & Price Mechanics
FDA process analytical technology guidance and EMA quality by design framework simultaneously gate supplier qualification and stratify price tiers, as GAMP 5 validation documentation requirements extend vendor onboarding timelines and concentrate procurement among established players with regulatory master files on record. This regulatory entrenchment allows incumbent equipment manufacturers to command premium positioning for chromatography and mass spectrometry platforms while mid-scale biotechnology firms face switching friction from consumables lock-in.
Pricing Analysis
Next-generation Raman spectroscopy probes for single-use bioreactors command 40-60% premiums over prior-generation dissolved oxygen and pH sensor arrays, while legacy HPLC systems face depreciation pressure from at-line mass spectrometry displacement. Three-tier pricing structure across premium, standard, and economy levels separates fully validated GMP-compliant platforms from research-grade configurations, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in chromatography consumables is intensifying because CDMOs in Germany and Switzerland increasingly favor equipment-as-a-service contracting over capital purchase. Biotechnology firms in California and Massachusetts exhibit highest price sensitivity, while pharmaceutical companies in Massachusetts and North Carolina prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Swiss and German precision sensor manufacturing clusters constitute a critical chokepoint for dissolved oxygen and pH probe supply to global bioreactor control systems. Component sourcing draws from specialized optical foundries in Switzerland, electrochemical sensor houses in Germany, and single-use film extrusion facilities in the United States. Single-source vulnerability concentrates among three European component suppliers, exposing buyers to allocation risk during demand surges. Distribution runs through authorized distributor networks serving CDMO qualification protocols, with direct OEM relationships dominating large-cap pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment and consumables lock-in create substantial switching costs that protect incumbent positioning across validation-intensive segments.
For Market Incumbents: Fortify chromatography consumables recurring revenue through proprietary column chemistry investments, while expanding equipment-as-a-service contracting to capture CDMO balance sheet flexibility demands. Capacity addition in India addresses emerging biologics manufacturing buildout in Hyderabad and Bengaluru. Threat from modular skid vendors targeting emerging biotechnology firms without internal automation expertise necessitates pre-validated analytics module development. For New Entrants and Emerging Players: CDSCO fast-track regulatory pathways for process analytical technology infrastructure in Indian CDMOs offer penetrable entry points absent entrenched incumbent relationships. Target viral vector analytics for cell and gene therapy applications, where empty-to-full capsid ratio measurement demands specialized equipment procurement streams. Go-to-market angle centers on AI-enabled predictive release algorithms bundled with spectroscopic sensors for parametric batch release without end-point testing. For Investors and Strategic Acquirers: FDA process analytical technology guidance revision reshapes the acquisition landscape by elevating software validation capabilities as primary due diligence criteria. Long-term viability favors precision instrumentation specialists with deep regulatory master files and embedded sensor integration expertise. Signal to watch is AI-enabled control loop verification requirements in updated FDA submissions, which will redefine automated batch release competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Master File Expansion | FDA and EMA submission depth accelerates vendor qualification timelines for commercial biologics manufacturers. |
| Equipment-as-a-Service Contracting | CDMOs in Germany and Switzerland preserve balance sheet flexibility while accessing high-end mass spectrometry platforms. |
| AI-Enabled Predictive Release Development | Machine learning algorithms trained on batch history converge with spectroscopic sensors for parametric release. |
| Modular Skid Architecture Pre-Validation | Pre-validated analytics modules reduce facility-specific engineering for emerging biotechnology firms. |
| India Manufacturing Footprint Establishment | Hyderabad and Bengaluru CDMO investments lack mature process analytical technology infrastructure. |
Methodological Framework
Cross-validation between primary interviews with bioprocess engineers, regulatory affairs specialists, CDMO procurement directors, and equipment vendor sales executives anchors the qualitative findings against secondary validation from FDA guidance documents, EMA quality by design submissions, ISO 13485 certification records, and GAMP 5 software validation standards. Bottom-up equipment shipment tracking triangulates with top-down biologics manufacturing capacity expansion announcements across Massachusetts, North Carolina, Germany, and India.
Sensitivity analysis across the projection horizon tests demand elasticity for chromatography versus mass spectrometry platforms, with segmentation dimensions spanning product type, end user archetype, technology maturity, and application workflow. CAGRs derive from installed base replacement cycles, continuous manufacturing transition velocity, and cell and gene therapy viral vector production scaling. Industry-specific forecast inputs incorporate CDMO equipment-as-a-service adoption rates and AI-enabled predictive release algorithm regulatory acceptance timelines.
Underlying assumptions cover FDA and EMA process analytical technology guidance stability, with deviation risk concentrated in software validation requirement revisions and single-source sensor supply disruptions. Practitioners should keep alternative scenarios live as AI-enabled batch release regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market