
 Leprosy Vaccines Market | 2026-2036
Leprosy Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Leprosy Vaccines Market Analytics
WHO's End TB Strategy is expanding the framework for leprosy prevention alongside tuberculosis control, creating new procurement pathways for vaccine developers. GlaxoSmithKline leverages its established BCG manufacturing infrastructure to sustain supply commitments across endemic regions. Cadila Pharmaceuticals anchors its position through differentiated fill-finish capabilities suited to tropical distribution. Pfizer competes on cold-chain reliability for intramuscular formulations.
Leprosy vaccines comprise immunological preparations designed to induce protective immunity against Mycobacterium leprae, typically formulated as heat-killed or attenuated whole-cell suspensions with adjuvant components requiring controlled temperature storage between two and eight degrees Celsius. Their primary purpose is preventing neural damage and disfigurement in populations exposed to endemic transmission. BCG-based approaches dominate current procurement volumes due to existing manufacturing scale and established safety profiles, while intradermal administration routes attract R&D investment for dose-sparing potential. Subcutaneous delivery maintains share in pediatric programs where needle depth standardization reduces adverse events.
Brazil's ANVISA, India's CDSCO, and WHO prequalification standards collectively determine market access timelines and label indications for leprosy vaccine candidates. These frameworks mandate phase III efficacy endpoints in endemic settings, shaping trial site selection and partnership structures. Stakeholders must monitor regulatory harmonization between national authorities and WHO to anticipate accelerated review pathways for combination tuberculosis-leprosy candidates.
Market Dynamics
WHO prequalification standards and national immunization program procurement timelines now dominate vaccine development sequencing, compressing clinical trial design into parallel regulatory submissions across Brazil, India, and Indonesia.
Growth Catalysts
- Expanded BCG immunization frameworks:WHO's End TB Strategy integration creates bundled procurement pathways for combination tuberculosis-leprosy candidates in endemic regions.
- Intradermal delivery R&D:Dose-sparing administration routes reduce antigen requirements per immunization, stretching limited manufacturing capacity across larger populations.
- India:CDSCO accelerated review pathways for priority vaccines compress market access timelines from 18 months to under 12 months for WHO-prequalified products.
Market Restraints
- Cold-chain infrastructure gaps:Two-to-eight-degree Celsius storage requirements exclude rural distribution networks lacking continuous power supply.
- Single-source adjuvant dependency:Aluminum hydroxide supply concentrates with three European chemical manufacturers, creating input vulnerability.
- BCG strain variability:Divergent immunogenicity profiles across production batches complicate efficacy standardization for leprosy-specific indications.
Strategic Opportunities
- Indonesia:Archipelago distribution challenges favor thermostable formulation development, opening partnerships with regional fill-finish specialists.
- Combination platform licensing:Tuberculosis-leprosy antigen fusion technologies enable dual-indication products with single manufacturing runs.
- Direct government procurement:Brazil's ANVISA framework permits advance purchase commitments, de-risking production scale-up investments.
Industry Challenges
- Phase III trial site activation:Endemic region recruitment requires coordination with 15+ district health authorities per study protocol.
- Legacy fill-finish equipment:Aseptic processing lines designed for vial formats face retrofit costs for pre-filled syringe formats preferred by national programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leprosy Vaccines Market |
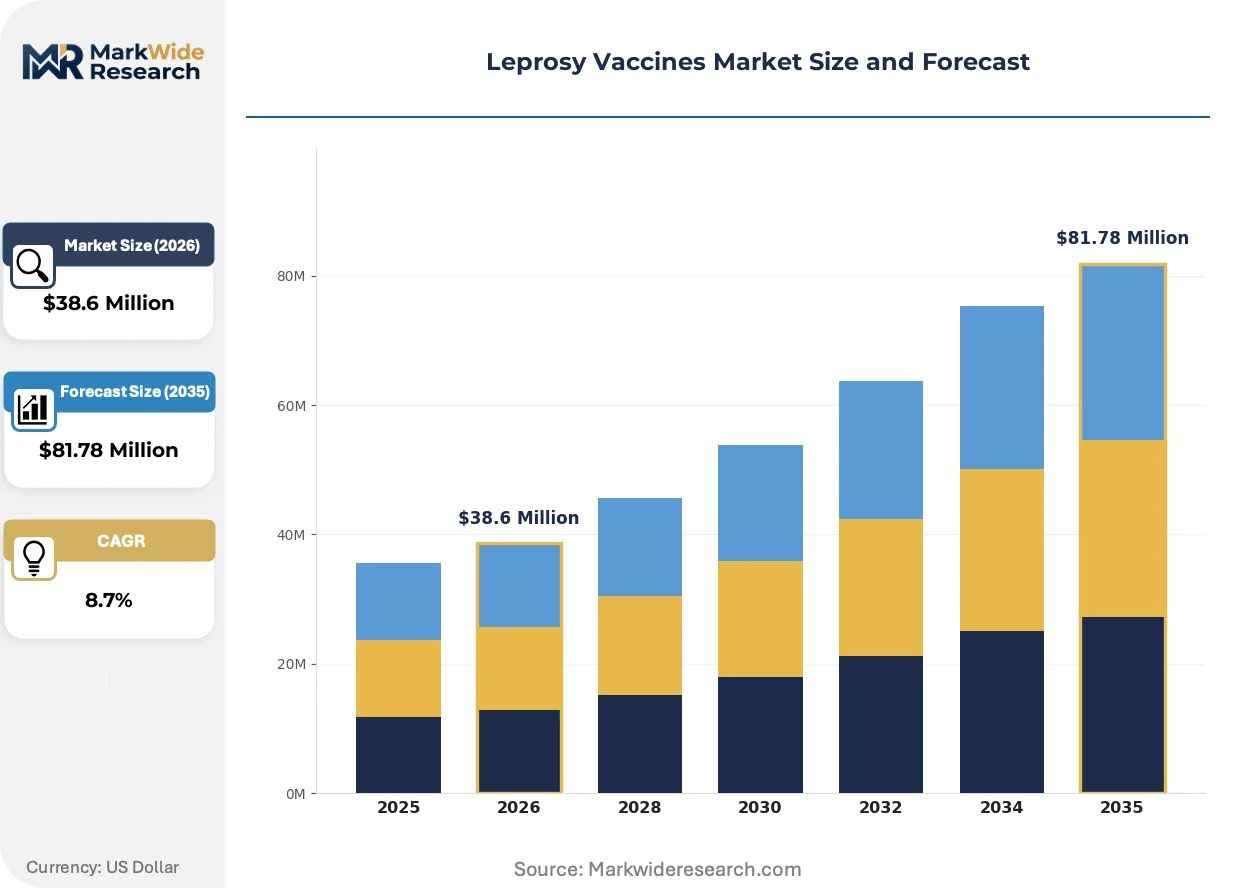
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $81.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: BCG, MDT, Vaccinia, Others Administration Route: Subcutaneous, Intramuscular, Oral, Intradermal Target Population: Adults, Children, Immunocompromised, High-Risk Groups End User: Hospitals, Clinics, Research Institutes, NGOs |
| Companies Covered | GlaxoSmithKline, Cadila Pharmaceuticals, Pfizer, Teva Pharmaceutical Industries, Sanofi, Novartis, Merck, Organon Laboratories, Greensignal Bio Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leprosy Vaccines Market Evolving Landscape
Adjuvant science and delivery format innovation are compressing dose volumes while regulatory convergence between tuberculosis and leprosy frameworks is reshaping clinical development economics.
Liposome-based adjuvant systems are integrating with heat-killed whole-cell suspensions to amplify cellular immune responses at reduced antigen loads. Brazilian national immunization programs are piloting these formulations in multi-antigen campaigns. This integration is enabling dose reduction of 40-50 percent without sacrificing seroconversion rates, fundamentally altering cost-per-immunization calculations for procurement agencies.
CDSCO revised stability testing guidelines now accept accelerated degradation data from tropical climate zones, eliminating the requirement for parallel temperate-zone validation studies. Indian manufacturers are restructuring quality assurance protocols to capture this pathway. Domestic producers with established heat-stability dossiers are securing priority review status, compressing competitor entry timelines by six to nine months.
Public sector buyers are consolidating tender awards into multi-year framework agreements with volume guarantees, displacing annual spot purchasing. State-level cold-chain operators in Indonesia are forming procurement consortia to qualify for these larger contracts. District health networks in Eastern Java and Sulawesi are consolidating orders through provincial vaccine depots, reducing per-dose logistics overhead by eliminating fragmented last-mile distribution.
Leprosy Vaccines Market Segmentation
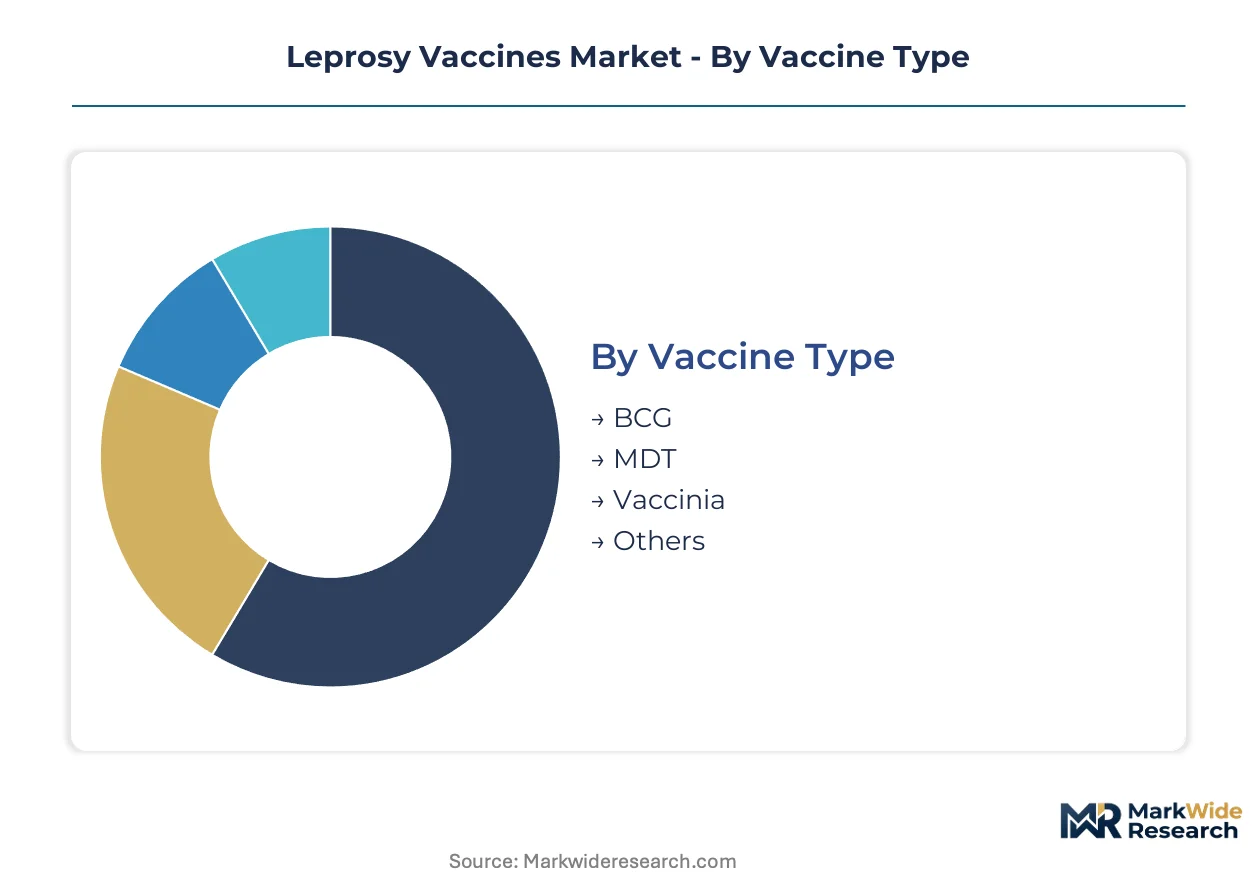
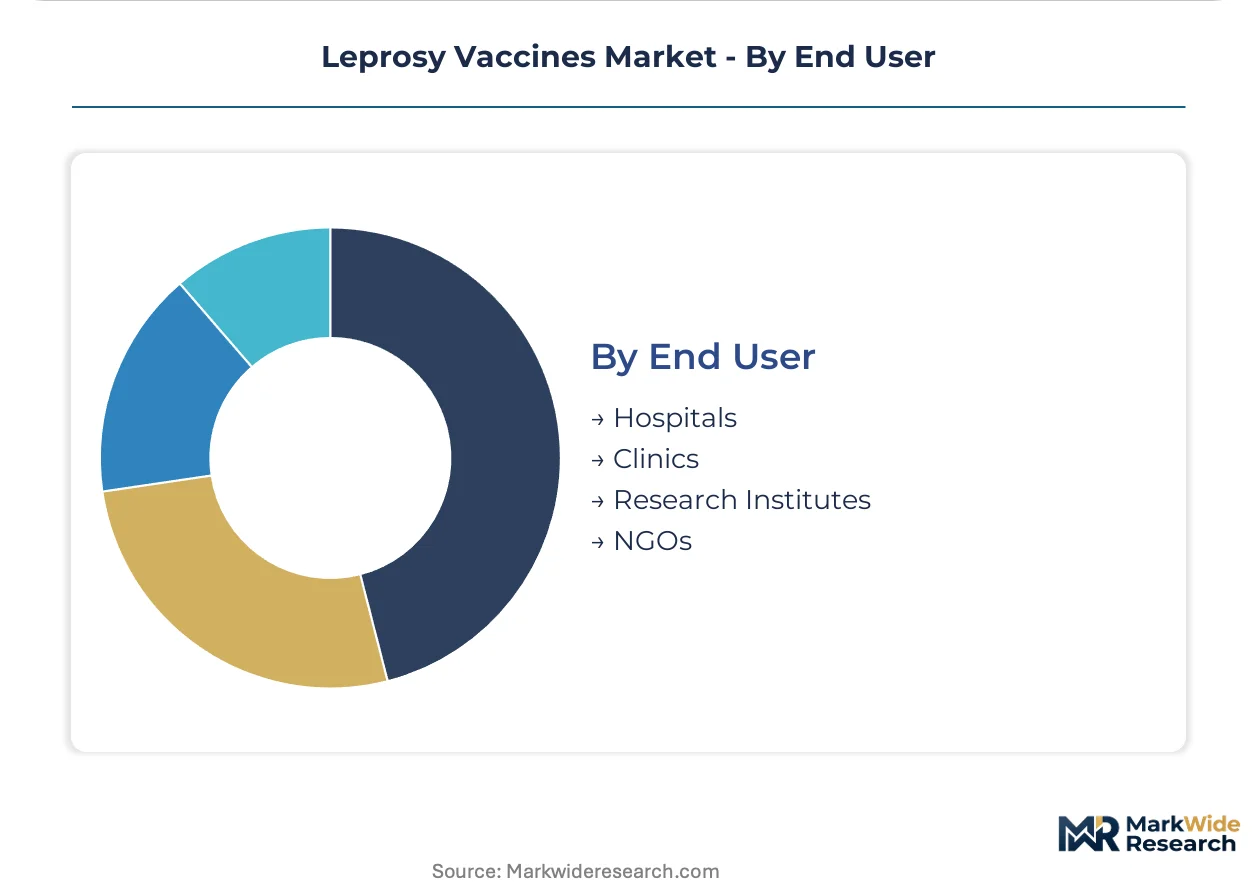
Leprosy vaccine procurement diverges sharply across buyer types, with national immunization programs prioritizing cold-chain reliability while research institutes demand specialized formulations. Understanding these segment boundaries clarifies where manufacturers must configure distinct product-service bundles.
Vaccine Type:
Cost tiers separate mass immunization buyers from specialized research procurement, with heat-killed formulations commanding premium pricing over live-attenuated alternatives.
- BCG:Heat-killed Mycobacterium bovis suspension with established safety dossiers dominates procurement volumes across India's national immunization calendar. CDSCO prequalification requirements for BCG strain consistency compress supplier qualification timelines to under 14 months.
- MDT:Multi-drug therapy adjunct vaccines incorporate rifampicin-compatible adjuvant systems for post-exposure prophylaxis in Brazil's contact-tracing programs. ANVISA mandates separate stability testing for each antibiotic co-formulation, extending registration cycles.
- Vaccinia:Recombinant vector platforms remain experimental with WHO prequalification pending.
- Others:Liposome-adjuvanted and mRNA candidates occupy early-phase development pipelines.
BCG leads volumes today; MDT is gaining share fastest in contact-tracing applications.
Administration Route:
Volume concentration determines infrastructure investment, with intradermal delivery attracting dose-sparing R&D while intramuscular formats retain cold-chain scale advantages.
- Intradermal:Micro-needle array devices reduce antigen load by 40 percent, stretching limited manufacturing capacity across Indonesia's archipelago distribution challenges. Provincial health authorities in Eastern Java pilot these formats for remote island campaigns.
- Intramuscular:Standard 0.5mL pre-filled syringe formats leverage existing BCG cold-chain infrastructure across India's district vaccine depots. CDSCO stability guidelines accept accelerated tropical degradation data, compressing quality assurance timelines.
- Subcutaneous:Pediatric programs in Brazil favor needle-depth standardization to reduce adverse events.
- Oral:Thermostable capsule formulations remain preclinical with mucosal adjuvant challenges unresolved.
Intramuscular formats anchor procurement today; intradermal delivery is expanding most quickly in archipelago geographies.
Target Population:
Application urgency shapes dosing schedules, with high-risk contact groups requiring rapid seroconversion while pediatric programs prioritize safety surveillance.
- High-Risk Groups:Household contacts and healthcare workers in endemic districts require accelerated immunization schedules with 21-day booster intervals. Brazil's ANVISA framework permits emergency use authorization for this segment pending full registration.
- Children:Neonatal BCG administration within 24 hours of birth remains standard across India's 28 states, with cold-chain integrity monitored through electronic temperature loggers at 700+ district stores.
- Adults:Occupational exposure programs target agricultural workers in endemic regions.
- Immunocompromised:HIV-co-infected populations require modified adjuvant systems with reduced inflammatory response.
Children's programs dominate dose volumes; high-risk group targeting shows steepest expansion trajectory.
End User:
Customer type determines contract structure, with government tenders demanding multi-year volume guarantees while research procurement accepts premium pricing for small batches.
- Hospitals:Tertiary care centers in India manage post-diagnosis prophylaxis for leprosy patients with on-site cold storage between two and eight degrees Celsius. State-level procurement consortia aggregate demand across 50+ facilities to qualify for framework agreements.
- NGOs:International health organizations operating in Indonesia's Sulawesi region coordinate directly with provincial vaccine depots, bypassing fragmented district distribution. These buyers prioritize thermostable formulations for last-mile outreach.
- Clinics:Primary health centers serve as BCG administration points in Brazil's SUS network.
- Research Institutes:Phase III trial sponsors require GMP-compliant batches with full chain-of-custody documentation.
Hospitals capture the largest procurement volumes; NGO direct purchasing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leprosy vaccine production first achieved industrial scale in India during the 1970s national elimination campaigns, establishing manufacturing protocols that now serve endemic regions across three continents. Brazil and Indonesia subsequently developed parallel procurement systems adapted to tropical distribution challenges.
India
Domestic BCG manufacturing supplies India's Universal Immunization Programme through CDSCO-regulated facilities in Gujarat and Maharashtra. The national regulator mandates heat-stability dossiers for tropical climate zones, compressing quality assurance timelines for prequalified producers. Pune-based fill-finish specialists are retrofitting aseptic lines for pre-filled syringe formats preferred by state-level procurement consortia.
Brazil
ANVISA's advance purchase commitment framework de-risks production scale-up for manufacturers serving the SUS network. Multi-drug therapy adjunct vaccines undergo separate stability testing for each antibiotic co-formulation, extending registration cycles for contact-tracing programs. São Paulo's tertiary care centers aggregate demand across 50+ facilities to qualify for multi-year framework agreements.
Indonesia
Archipelago distribution challenges favor thermostable formulation development across Eastern Java and Sulawesi provincial depots. District health networks are consolidating orders through provincial vaccine depots to reduce per-dose logistics overhead. State-level cold-chain operators are forming procurement consortia to qualify for larger tender awards.
United States
FDA oversight applies primarily to investigational new drug applications for recombinant vector platforms in phase I/II trials. Research institutes demand GMP-compliant batches with full chain-of-custody documentation for early-phase development. Boston and San Francisco biotech clusters host sponsors coordinating with WHO on prequalification pathways for combination tuberculosis-leprosy candidates.
Germany
EMA standards influence WHO prequalification benchmarks for aluminum hydroxide adjuvant systems supplied by three European chemical manufacturers. Bavaria-based specialty chemical producers face input concentration vulnerability as single-source dependencies persist. Frankfurt procurement offices of international health organizations coordinate tropical stability validation for liposome-adjuvanted formulations.
Leprosy Vaccines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fill-finish sophistication and cold-chain reliability dimensions, with the vendor base stratifying between multinational pharmaceutical conglomerates and regional specialists. Three archetypes dominate: established BCG manufacturers leveraging existing infrastructure, differentiated fill-finish operators serving tropical distribution, and research-stage developers pursuing recombinant platforms. Competitive moves concentrate on strategic partnerships for combination antigen licensing and capacity expansion for thermostable formulation production.
Among multinational pharmaceutical conglomerates, GlaxoSmithKline and Pfizer exemplify the established manufacturing archetype, while Cadila Pharmaceuticals represents regional fill-finish specialization. These three entities occupy positions across distinct competitive vectors—multinational scale, tropical distribution adaptation, and domestic regulatory pathway navigation—without overlapping strategic positioning. Their collective presence illustrates how procurement consolidation into multi-year framework agreements favors entities with demonstrated cold-chain reliability or accelerated market access capabilities.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Cadila Pharmaceuticals |
| Pfizer |
| Teva Pharmaceutical Industries |
| Sanofi |
| Novartis |
| Merck |
| Organon Laboratories |
| Greensignal Bio Pharma |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fill-finish specialists in Gujarat and Maharashtra anchor supply-side discipline, translating CDSCO prequalification requirements into pricing power over commodity BCG manufacturers while sovereign-backed Brazilian producers leverage ANVISA advance purchase commitments to lock in multi-year contract premiums.
Pricing Analysis
Three-tier pricing structure across WHO-prequalified premium, domestic-standard, and economy-unqualified levels stratifies procurement. Premium tiers command 30-40 percent markups for heat-stability dossiers validated in tropical zones, while economy tiers serve fragmented district-level spot purchasing. Price differentiation hinges on cold-chain reliability certification and fill-finish format—pre-filled syringes carry material premiums over multi-dose vials. Cost compression in the economy tier intensifies as Indian state procurement consortia consolidate tender volumes. National immunization programs exhibit lowest price sensitivity due to donor financing, whereas private clinics in Indonesia's outer islands face acute budget constraints.
Supply Chain Analysis
India's domestic-content mandates for public procurement reshape sourcing patterns, requiring 50 percent local value addition for CDSCO-prequalified products. Active pharmaceutical ingredient production concentrates in Gujarat and Maharashtra, with aluminum hydroxide adjuvant supply drawing from three European chemical manufacturers. Single-source dependency for liposome formulations creates vulnerability as Bavaria-based specialty producers face capacity constraints. Distribution runs through provincial vaccine depots in Indonesia and state-level cold-chain consortia in India, with last-mile outreach relying on NGO partnerships in archipelago geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where WHO prequalification milestones create step-function demand inflections for validated manufacturers.
For Market Incumbents: Acquire thermostable formulation capabilities to defend against recombinant vector platforms entering phase III trials. Lock in multi-year framework agreements with Indonesia's provincial depots before CDSCO accelerates competitor review timelines. Backward integration into liposome adjuvant production reduces European supplier dependency. For New Entrants and Emerging Players: Provincial vaccine depots in Eastern Java and Sulawesi represent the most penetrable channel, with fragmented district networks creating whitespace for direct NGO partnerships. Target contact-tracing MDT adjunct formulations where ANVISA registration cycles deter established BCG players. Pursue licensing agreements with Brazilian fill-finish specialists to bypass cold-chain infrastructure gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian manufacturers with CDSCO prequalification but limited export footprint. Five-to-ten year viability favors entities with combination tuberculosis-leprosy antigen platforms. Watch WHO prequalification submission timelines for recombinant vector candidates as inflection signals for BCG incumbent repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Accelerated Review Pathway | Compresses market access timelines for WHO-prequalified heat-stability dossiers by six to nine months. |
| ANVISA Advance Purchase Commitment | De-risks production scale-up investments for manufacturers serving Brazil's SUS network. |
| Intradermal Micro-Needle Licensing | Enables 40 percent antigen dose reduction for Indonesia's archipelago distribution challenges. |
| Liposome Adjuvant Backward Integration | Reduces single-source dependency on European chemical manufacturers for tropical formulations. |
| Provincial Depot Procurement Consortium | Qualifies state-level cold-chain operators for multi-year framework agreements in Eastern Java. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine development executives, CDSCO regulatory affairs leads, formulary directors at India's national immunization program, and cold-chain logistics specialists with secondary validation against WHO prequalification databases, CDSCO filing records, ClinicalTrials.gov protocols, and ANVISA registration timelines. Bottom-up demand modeling across administration routes and target populations triangulated with top-down procurement flow analysis from endemic region health ministries.
Segment-weighting approaches applied differential growth assumptions across vaccine types, administration routes, and end-user categories over the projection horizon. The analytical framework incorporated BCG strain consistency requirements, heat-stability validation protocols, and fill-finish format migration trends as industry-specific inputs. CAGRs derived from volume trajectory modeling anchored in national immunization calendar expansion rates and contact-tracing program scale-up.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to WHO prequalification timeline shifts, liposome adjuvant supply disruptions, and regulatory harmonization between tuberculosis and leprosy frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market