
 Human Placental Protein Market | 2026-2036
Human Placental Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Human Placental Protein Market Analysis
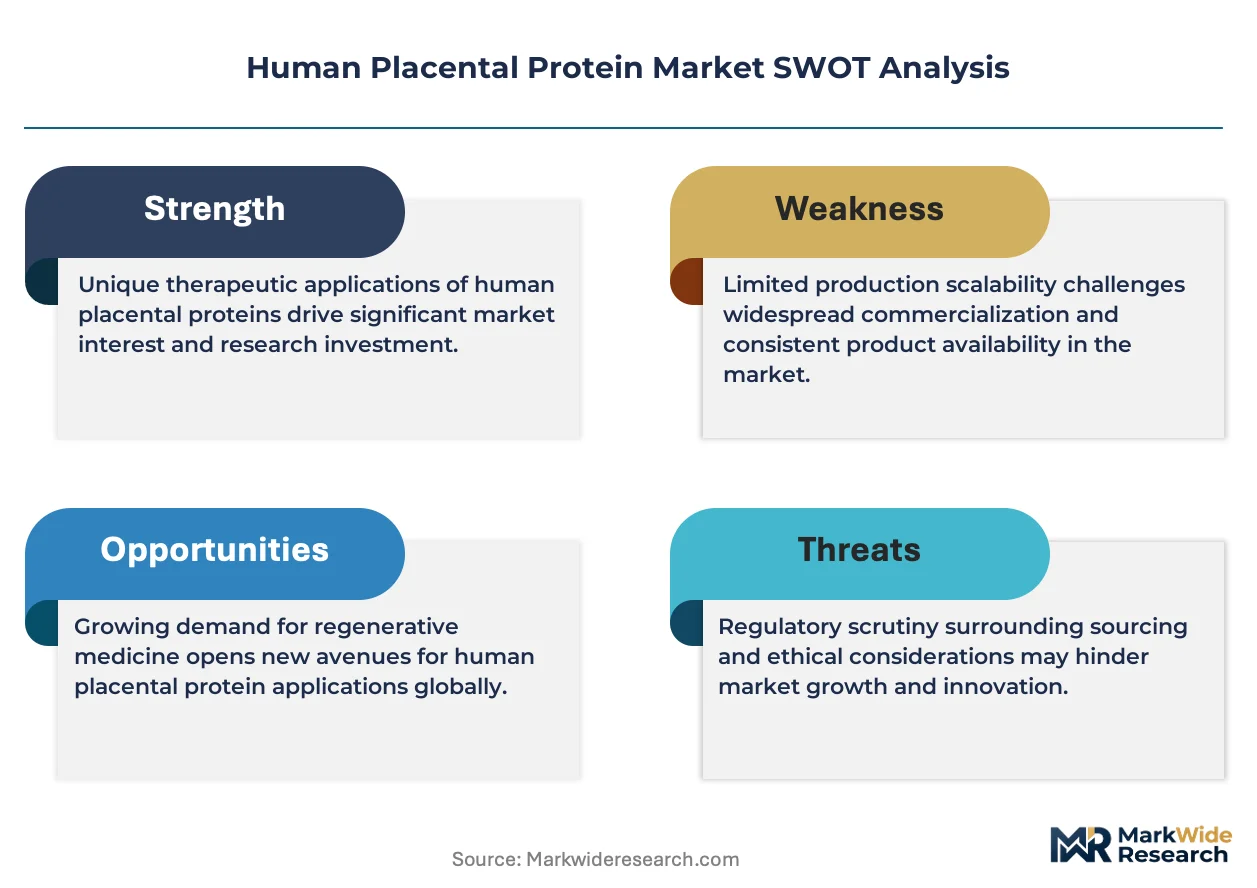
Cosmeceutical and regenerative medicine demand is hardening as the fastest-expanding vertical pull for human placental protein suppliers. JAPAN BIO PRODUCTS Co., Ltd. anchors its position through geographic dominance in Asian tissue sourcing networks. Takara Bio Inc specializes in cytokine purification technologies that sustain premium positioning in research-grade segments. Abcam plc competes globally by extending its antibody-conjugated placental protein portfolio across diagnostics channels.
Human placental protein comprises bioactive fractions—hormones, enzymes, cytokines, and vitamin K complexes—extracted from placental tissue via cold-processing or chromatographic methods, serving therapeutic, diagnostic, and cell-culture applications. The cytokines segment leads in value contribution due to its irreplaceable role in stem-cell expansion media and immunotherapy protocols. Diagnostics applications are growing fastest as multiplex assay platforms integrate placental-derived reference standards. Pharmaceutical companies represent the most concentrated end-user margin pool, though research institutes drive volume throughput for catalog-grade materials.
The FDA governs human tissue sourcing under 21 CFR Part 1271, while the EMA enforces donor-traceability standards through the EU Tissues and Cells Directive, tightening market access for non-compliant processors. Japan's PMDA and MHLW impose additional ethico-legal constraints on placental material importation, favoring domestic processors like JAPAN BIO PRODUCTS. Stakeholders must monitor evolving donor-consent frameworks and dual-use export controls that could restructure supply geography without warning.
Market Dynamics
Divergent donor-traceability mandates between FDA and EMA jurisdictions are fragmenting procurement workflows, forcing suppliers to maintain parallel compliance infrastructures and regional inventory pools.
Growth Catalysts
- Regenerative medicine infrastructure:Cell therapy manufacturers in Japan and the United States are scaling GMP-grade cytokine procurement for stem-cell expansion protocols.
- 21 CFR Part 1271 alignment:US-based tissue processors investing in donor screening automation are capturing contract research organization volume previously lost to documentation gaps.
- Chromatographic purification:Advances in affinity column technology are reducing endotoxin burden in research-grade placental extracts, opening diagnostic assay integration.
Market Restraints
- Donor material scarcity:Hospital collection network concentration in Tokyo and Osaka metropolitan areas limits raw tissue throughput for Japanese processors.
- EMA tissue directive friction:EU import documentation requirements for third-country placental material create 90-120 day customs holds at Rotterdam and Hamburg ports.
- Synthetic cytokine substitution:Recombinant interferon-gamma and interleukin-2 from Chinese contract manufacturers are displacing native placental sources in cost-sensitive cell culture applications.
Strategic Opportunities
- Brazilian tissue network development:ANVISA's 2023 biologics import simplification creates first-mover advantage for placental protein distributors establishing São Paulo cold-chain facilities.
- Multiplex diagnostic platforms:Placental-derived reference standards are penetrating cytokine profiling panels for autoimmune disease monitoring in European hospital laboratories.
- Single-use bioreactor convergence:Integration of perfusion culture systems with defined media formulations is expanding addressable market for serum-free placental extract alternatives.
Industry Challenges
- GMP certification timelines:FDA pre-approval inspections for human tissue drug master files average 14-18 months, freezing working capital in qualification batches.
- Donor consent chain integrity:Retrospective audit requirements for maternal health records are exposing documentation gaps in legacy hospital collection agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Placental Protein Market |
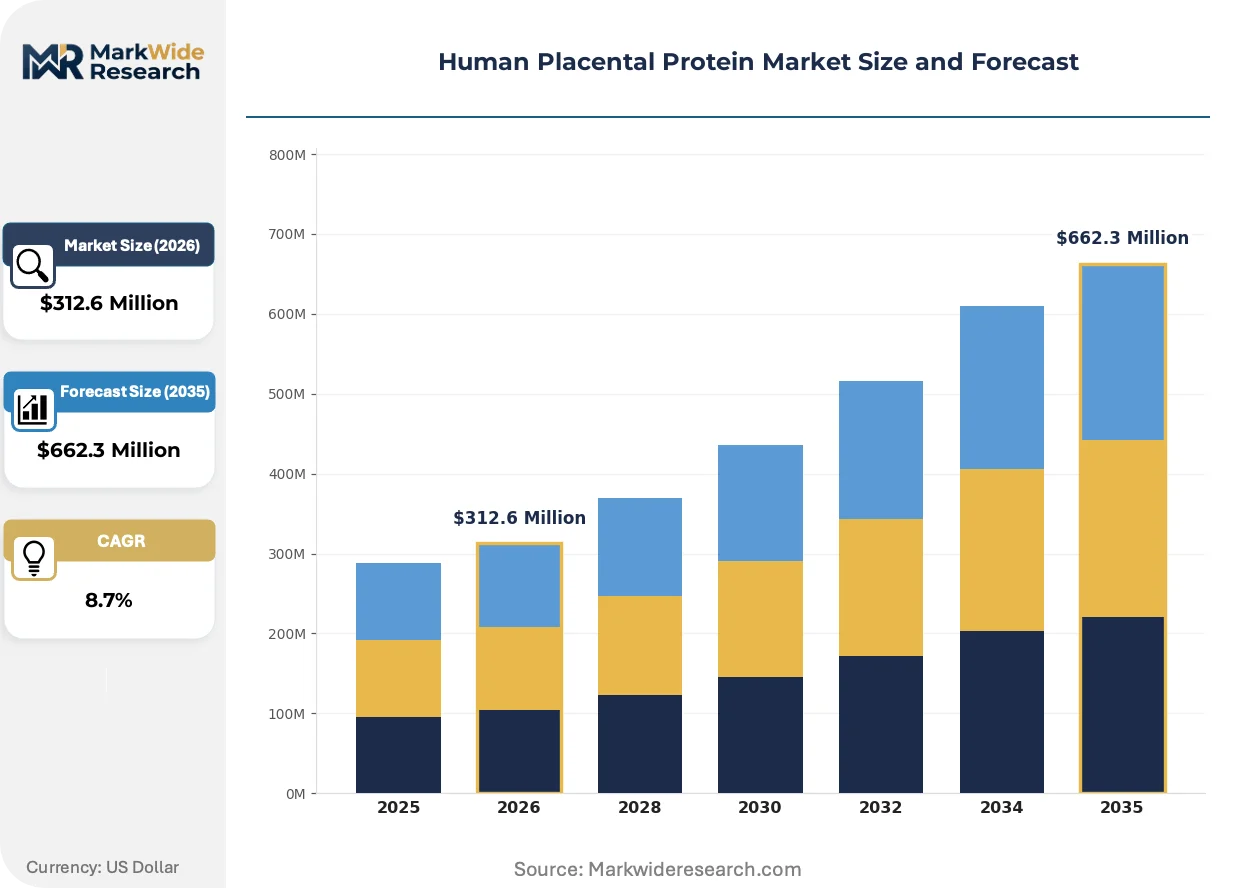
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin K, Hormones, Cytokines, Enzymes Application: Therapeutics, Diagnostics, Research, Supplementation End User: Pharmaceutical Companies, Hospitals, Research Institutes, Biotech Firms Form: Liquid, Powder, Injectable, Tablet |
| Companies Covered | JAPAN BIO PRODUCTS Co., Ltd., VWR International, Takara Bio Inc, Abcam plc, Kamiya Biomedical Co., Scripps Laboratories, Lee BioSolutions, Elabscience Biotechnology Co.,Ltd, R&D Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Placental Protein Market Emerging Trajectories
Cold-chain logistics digitization and serum-free media formulation advances are compressing the boundary between research-grade and clinical-grade placental protein supply tiers.
Perfusion-based tissue digestion systems are expanding into cytokine recovery workflows previously dominated by static cold-processing methods. Contract manufacturers in Singapore and Massachusetts are adopting these platforms to reduce batch-to-batch variability in growth factor yields. The technology is expanding into mid-scale cell therapy suppliers who previously outsourced purification to established Japanese processors.
EMA's 2024 revision to the EU Tissues and Cells Directive introduces real-time donor registry interoperability requirements. Tissue establishments must now demonstrate automated cross-border traceability query response within 48 hours. Small-scale US exporters serving German and French research institutes face disproportionate compliance burden relative to integrated European tissue banks.
Academic medical centers are consolidating placental protein procurement through centralized biorepository contracts rather than catalog-based spot purchasing. Stanford, Johns Hopkins, and Karolinska Institutet have shifted to multi-year supply agreements with specified donor demographic criteria. This concentration is most visible in the United States, where NIH funding mechanisms now require documented tissue provenance for grant compliance.
Human Placental Protein Market Segmentation
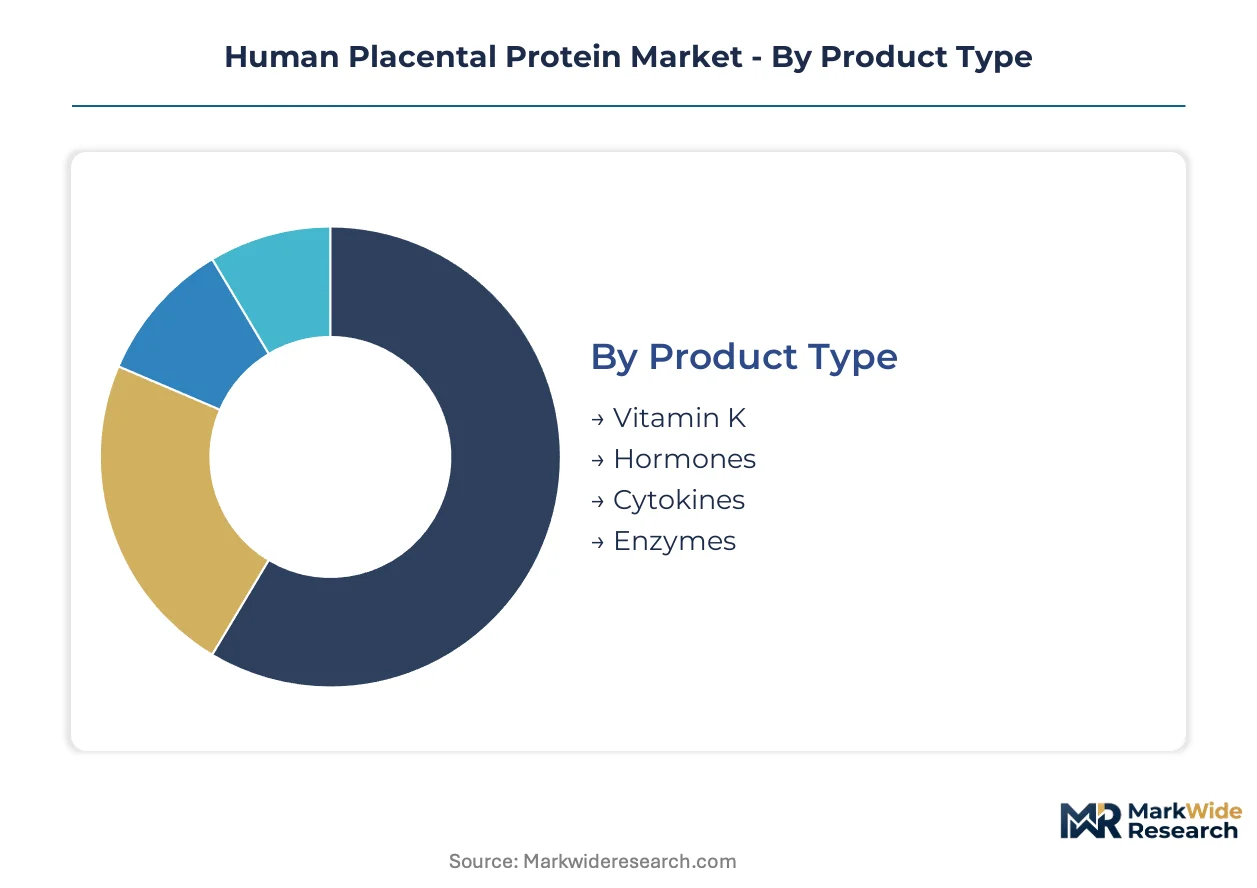
Procurement workflows for human placental protein diverge sharply across product grades and end-use specifications. Segment-specific compliance requirements and purity thresholds dictate supplier selection criteria and pricing tiers.
Product Type:
Upgrade cycles in cell therapy manufacturing are pushing demand toward higher-purity cytokine fractions that displace legacy hormone-based formulations.
- Cytokines:These signaling proteins—interleukins, interferons, and growth factors—command premium positioning in stem-cell expansion media. Cell therapy manufacturers in Japan and the United States source GMP-grade batches for CAR-T and iPSC workflows, with endotoxin specifications below 0.1 EU/mL driving supplier qualification costs upward.
- Hormones:Human chorionic gonadotropin and placental lactogen fractions serve fertility treatment protocols and endocrine research. European hospital pharmacies maintain standing orders for diagnostic-grade hormone reference materials, though recombinant alternatives are eroding native-source volumes in cost-sensitive applications.
- Enzymes:Placental alkaline phosphatase and other catalytic fractions support molecular biology reagent manufacturing.
- Vitamin K:Phylloquinone complexes from placental lipid extracts find niche use in neonatal supplementation and coagulation research.
Cytokines sit at the top of the volume ranking, with enzymes climbing the fastest as protease inhibitor cocktails penetrate cell lysis workflows.
Application:
Cost tier separation between therapeutic and research grades is widening as FDA 21 CFR Part 1271 compliance investments accumulate.
- Diagnostics:Placental-derived reference standards calibrate multiplex cytokine assays for autoimmune and infectious disease panels. European hospital laboratories in Germany and France are integrating these materials into routine IL-6 and TNF-alpha monitoring protocols.
- Therapeutics:GMP-grade cytokine lots support active pharmaceutical ingredient production for cell therapy products. Japanese PMDA master file requirements and extended stability testing protocols extend qualification timelines to 18-24 months.
- Research:Catalog-grade extracts supply academic institutions and contract research organizations for exploratory cell culture work.
- Supplementation:Cosmetic and wellness applications utilize hydrolyzed placental protein fractions in topical and oral formulations.
Therapeutics commands the highest margin tier, with diagnostics gaining share fastest through automated immunoassay platform expansion.
End User:
Customer concentration patterns favor integrated buyers with captive tissue processing capabilities over fragmented spot purchasers.
- Pharmaceutical Companies:These organizations negotiate multi-year supply agreements with specified donor demographics and batch release criteria. Their procurement teams prioritize suppliers with FDA drug master file precedents and documented viral inactivation protocols.
- Biotech Firms:Mid-scale cell therapy developers in Singapore and Massachusetts are building internal purification capabilities to reduce dependency on Japanese processors. Their sourcing decisions weigh serum-free media compatibility against total cost of ownership.
- Research Institutes:Stanford, Johns Hopkins, and Karolinska Institutet have consolidated purchasing through centralized biorepository contracts with provenance documentation requirements.
- Hospitals:Clinical laboratories in Tokyo and Osaka metropolitan areas represent concentrated demand for diagnostic-grade materials.
Pharmaceutical companies anchor procurement volume, with biotech firms expanding most quickly through venture-funded cell therapy pipelines.
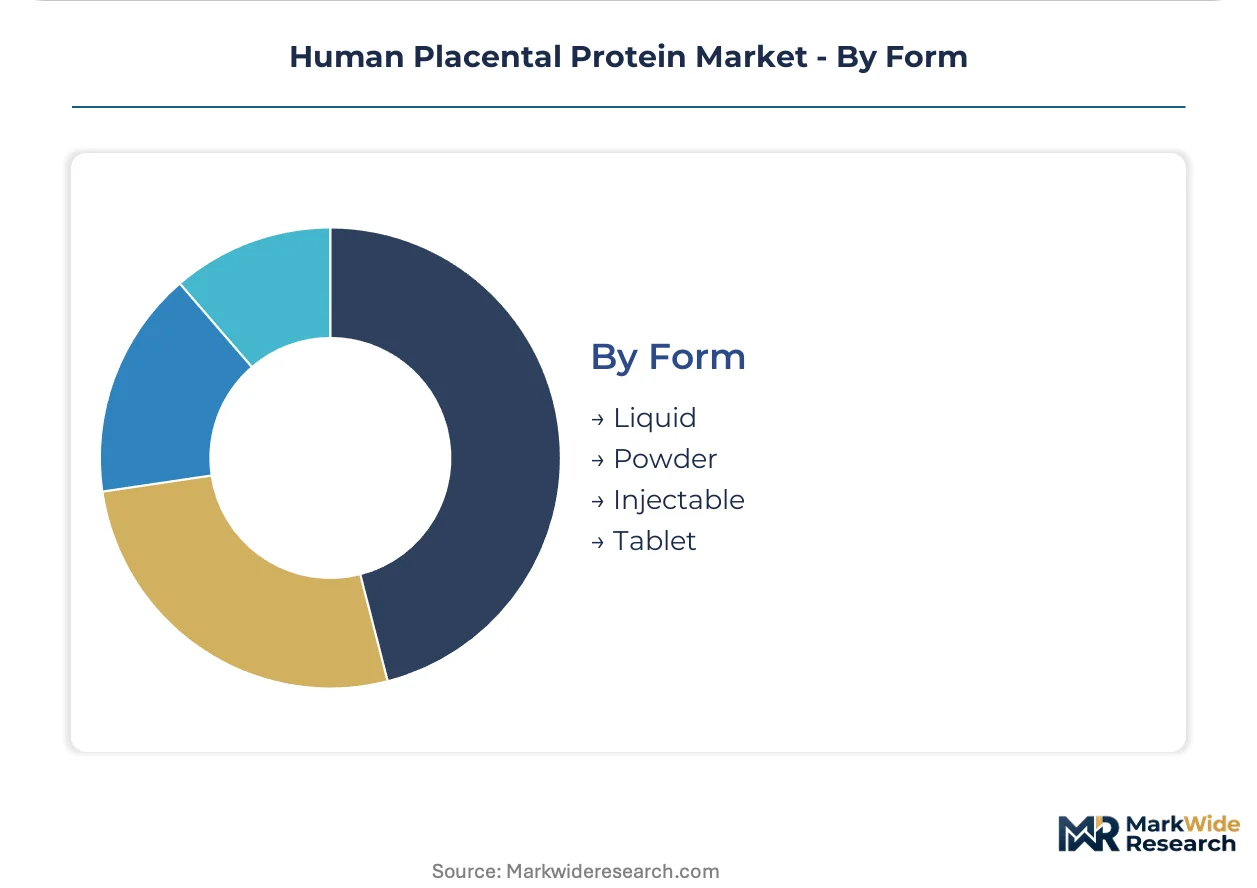
Form:
Supply concentration in lyophilized powder processing is creating bottlenecks for injectable-grade liquid formulations.
- Liquid:Frozen or refrigerated cytokine suspensions suit immediate-use cell culture applications. Cold-chain integrity requirements limit distribution radius for small-batch producers without regional cryogenic storage infrastructure.
- Powder:Lyophilized extracts offer extended shelf stability and reduced shipping costs. Japanese processors dominate this format through proprietary freeze-drying protocols that preserve bioactivity in growth factor preparations.
- Injectable:Sterile-filled vials for clinical trial supply face GMP certification barriers that freeze out research-grade suppliers.
- Tablet:Compressed placental protein formulations serve cosmetic and wellness supplement channels with minimal regulatory oversight.
Powder leads in shipment volume, with liquid formats gaining traction fastest through perfusion bioreactor integration in cell therapy manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting procurement flows as compliance cost differentials between FDA and EMA jurisdictions widen. Processors in Japan and the United States capture premium-tier contracts while European tissue banks absorb documentation-intensive import friction.
United States
Cell therapy manufacturers in Massachusetts and California drive GMP-grade cytokine procurement for CAR-T and iPSC workflows. FDA 21 CFR Part 1271 donor-screening automation investments are capturing contract research organization volume. Stanford and Johns Hopkins anchor academic demand through centralized biorepository contracts with specified donor demographics.
Japan
Tokyo and Osaka metropolitan hospitals concentrate diagnostic-grade material demand while domestic processors dominate Asian tissue sourcing networks. PMDA and MHLW ethico-legal constraints on placental importation favor JAPAN BIO PRODUCTS and established local processors. Perfusion-based tissue digestion adoption is expanding among mid-scale cell therapy developers in Kanto and Kansai regions.
Germany
EMA's EU Tissues and Cells Directive real-time donor registry requirements are restructuring procurement toward integrated European tissue banks. Frankfurt and Hamburg clinical laboratories integrate placental-derived reference standards into multiplex cytokine panels for autoimmune monitoring. Customs documentation friction at Rotterdam and Hamburg ports is extending lead times for third-country material.
United Kingdom
London and Cambridge research institutes are consolidating catalog-grade purchasing through multi-year supply agreements with provenance documentation. MHRA alignment with EMA traceability standards is compressing market access for non-compliant exporters. Oxford and Imperial College medical centers are driving diagnostic assay integration of placental protein reference materials.
Brazil
ANVISA's 2023 biologics import simplification is attracting first-mover distributors establishing São Paulo cold-chain facilities. São Paulo state university hospitals represent emerging demand for research-grade cytokine fractions. Regional tissue processing infrastructure gaps are creating procurement dependency on imported lyophilized powder formulations.
Human Placental Protein Market Vendor Landscape
Capacity expansion dominates the current landscape as established processors invest in perfusion-based tissue digestion platforms to reduce batch-to-batch variability. The vendor base stratifies across three tiers: integrated Japanese processors with captive tissue networks, US-based specialty cytokine purifiers, and European diagnostic reagent distributors. Technology licensing and geographic expansion represent the dominant competitive vectors as mid-scale suppliers seek serum-free media compatibility credentials.
Among Japanese processors, JAPAN BIO PRODUCTS Co., Ltd. anchors the integrated tier through geographic dominance in Asian tissue sourcing networks. Takara Bio Inc occupies a position exemplifying specialty cytokine purification technology. Abcam plc represents the diagnostic channel vector through antibody-conjugated portfolio extension. These three entities collectively illustrate the competitive archetypes shaping procurement decisions: tissue-network control, purification technology premium positioning, and global diagnostics distribution reach.
| Leading Market Players |
|---|
| JAPAN BIO PRODUCTS Co., Ltd. |
| VWR International |
| Takara Bio Inc |
| Abcam plc |
| Kamiya Biomedical Co. |
| Scripps Laboratories |
| Lee BioSolutions |
| Elabscience Biotechnology Co.,Ltd |
| R&D Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Donor screening labor costs cascade through three certification tiers, with FDA 21 CFR Part 1271 compliance investments separating GMP-grade cytokine batches from research-grade extracts. Japanese processors command premium positioning through captive tissue networks in Tokyo and Osaka metropolitan hospitals, while US distributors absorb margin compression from extended qualification timelines.
Pricing Analysis
Distributor markup layers separate Japanese processors from end-user pharmaceutical buyers, with logistics and cold-chain handling adding substantial cost before materials reach cell therapy manufacturers. Pricing stratifies across GMP-certified therapeutic, diagnostic-grade reference standard, and catalog research tiers, with endotoxin specification thresholds driving 40-60 point spreads between adjacent tiers. Cost compression in research-grade segments intensifies as Chinese recombinant cytokine substitutes displace native placental sources. Academic institutions and small biotech firms exhibit highest price sensitivity, while pharmaceutical companies with CAR-T and iPSC pipelines prioritize batch consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical procurement teams mandate parallel qualification of Japanese and US-based processors to mitigate single-origin disruption risk. Raw tissue supply concentrates in Japan, the United States, and select European hospital networks, with chromatographic resin and affinity column consumables drawing from German and US specialty chemical manufacturers. Single-source vulnerability in Tokyo-Osaka collection corridors threatens throughput for Asian-sourced materials. Distribution runs through regional cryogenic storage hubs before final-mile delivery to cell therapy manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The human placental protein market compounds steadily as regenerative medicine infrastructure hardens across Japan and the United States, with cell therapy manufacturing expansion creating durable demand for GMP-grade cytokine inputs.
For Market Incumbents: To counter synthetic cytokine substitution from Chinese recombinant manufacturers, JAPAN BIO PRODUCTS and established Japanese processors should deepen backward integration into hospital collection network contracts while accelerating perfusion-based purification technology deployment. FDA drug master file precedent holders must automate donor-traceability documentation to capture contract research organization volume fleeing documentation-deficient competitors. For New Entrants and Emerging Players: Contract research organizations in Singapore and Massachusetts represent the most penetrable buyer segment, as mid-scale cell therapy developers seek serum-free media compatibility credentials without legacy supplier dependency. ANVISA-simplified Brazilian import channels offer geographic white-space for distributors establishing São Paulo cold-chain infrastructure. A specialized cytokine purification technology licensing play bypasses tissue network barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA pre-approval inspection timelines freeze working capital and documentation gaps expose legacy hospital collection agreements to retrospective audit failure. Five-to-ten year viability favors processors with integrated tissue networks and demonstrated PMDA master file precedents. The signal to watch is EMA real-time donor registry interoperability compliance, which will strand non-automated exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion-Based Purification Scale-Up | Reduces batch-to-batch variability for CAR-T expansion media suppliers. |
| FDA Drug Master File Submission | Unlocks pharmaceutical procurement contracts requiring viral inactivation documentation. |
| Brazilian Cold-Chain Facility Establishment | Captures ANVISA-simplified import advantage before competitor infrastructure hardens. |
| Automated Donor-Traceability Platform | Meets EMA 48-hour cross-border query requirements without manual audit exposure. |
| Serum-Free Media Formulation Partnership | Aligns cytokine extracts with single-use bioreactor convergence in cell therapy workflows. |
Methodological Framework
Bottom-up cell therapy manufacturer demand modeling reconciled against top-down tissue processor capacity tracking forms the analytical core of this study. Primary interviews with cell therapy development executives, regulatory affairs leads at Japanese and US processors, hospital procurement managers in Tokyo and Osaka, and GMP quality assurance directors combined with secondary validation against FDA 21 CFR Part 1271 guidance documents, EMA EU Tissues and Cells Directive revisions, PMDA master file databases, and clinical trial registry entries. Supply-side triangulation against customs import records and cold-chain logistics provider disclosures verified demand estimates.
Input-output matrices mapped cytokine fraction demand across therapeutic, diagnostic, and research applications through the projection horizon, with segmentation dimensions spanning product purity grade, endotoxin specification tier, and regional regulatory cluster. CAGRs derived from installed base growth in stem-cell expansion workflows and multiplex diagnostic platform penetration. Forecast inputs incorporated perfusion bioreactor adoption curves and synthetic cytokine substitution elasticity in cost-sensitive research segments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to donor consent framework revisions and dual-use export control expansions that could restructure supply geography. Deviation in EMA-FDA regulatory alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Apoptosis Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market