
 North America Bacteriophages Therapy Market | 2026-2036
North America Bacteriophages Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bacteriophages Therapy Market Analytics
Canada is fragmenting as a production hub for phage manufacturing infrastructure, with new bioreactor capacity coming online in Toronto and Montreal clusters. Intralytix, Inc. leverages its FDA-registered food safety phage platform to anchor commercial revenue in the agricultural sector. Armata Pharmaceuticals, Inc. sustains a clinical-stage pipeline focused on multidrug-resistant Pseudomonas infections. Locus Biosciences competes through CRISPR-engineered phage technology aimed at precision antibacterial applications.
Bacteriophages therapy deploys viruses that infect and lyse specific bacterial hosts, with formulations typically requiring titers exceeding 10^9 plaque-forming units per milliliter and stability testing across pH 3-11 ranges to ensure therapeutic viability. Engineered phages command premium positioning due to programmable host specificity and reduced immunogenicity profiles, while natural phage combinations retain cost advantages in food safety and agricultural prophylaxis. Intravenous delivery mode carries the highest regulatory burden but also the largest margin pool in hospital settings, whereas topical administration dominates volume in dermatological and wound care applications.
FDA oversight through the Center for Biologics Evaluation and Research shapes investigational new drug pathways for phage therapeutics, while Health Canada's Biologic and Radiopharmaceutical Drugs Directorate establishes parallel review frameworks for cross-border product development. The USDA regulates agricultural phage applications under the Plant Protection Act, creating a tripartite compliance landscape that vendors must navigate simultaneously. Stakeholders should monitor FDA guidance document revisions on phage cocktail standardization, as these will determine whether centralized manufacturing or distributed compounding models prevail for hospital access.
Market Dynamics
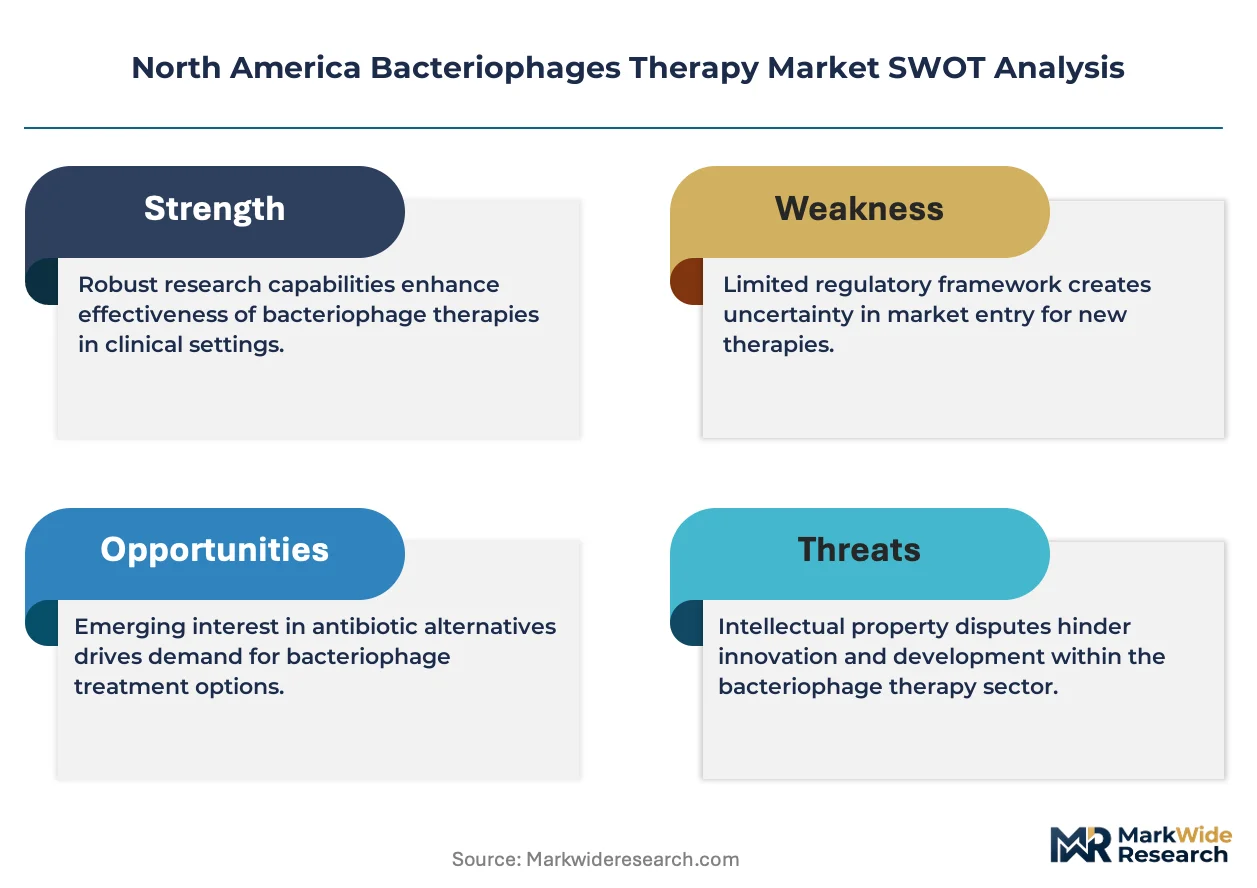
The FDA's expanded access program for phage therapy is compressing clinical trial timelines and forcing manufacturers to choose between centralized bioreactor production and distributed hospital compounding models.
Growth Catalysts
- Hospital-based infectious disease protocols:Multidrug-resistant Pseudomonas infections in burn and cystic fibrosis wards are creating protocol-level demand for phage cocktails as salvage therapy when conventional antibiotics fail.
- CRISPR-engineered phage platforms:Programmable host specificity is reducing off-target bacterial lysis and enabling precision antibacterial applications that natural phage combinations cannot achieve.
- USDA Plant Protection Act pathways:Agricultural phage prophylaxis for foodborne pathogens is generating commercial revenue streams with lower regulatory barriers than human therapeutic applications.
Market Restraints
- Bioreactor capacity concentration:Toronto and Montreal clusters control the majority of North American phage manufacturing infrastructure, creating single-source vulnerability for US hospital networks.
- FDA Center for Biologics Evaluation and Research friction:Investigational new drug pathways lack standardized phage cocktail composition rules, forcing sponsors to negotiate batch-to-batch variability on a per-protocol basis.
- Stability testing cost structure:pH 3-11 range validation and titer maintenance above 10^9 plaque-forming units per milliliter require cold chain infrastructure that rural hospital systems cannot sustain.
Strategic Opportunities
- Topical dermatological applications:Wound care protocols in Veterans Affairs health networks represent an underpenetrated channel with lower intravenous regulatory burdens and faster formulary adoption cycles.
- Health Canada cross-border harmonization:Parallel review frameworks between FDA and Biologic and Radiopharmaceutical Drugs Directorate could accelerate dual-approval timelines for sponsors with existing US clinical data.
- CRISPR-natural phage convergence:Hybrid engineered-natural cocktails combining programmable specificity with cost-optimized agricultural manufacturing economics could bridge premium and prophylaxis market tiers.
Industry Challenges
- Phage cocktail standardization delays:FDA guidance document revisions on host range testing and potency assays remain unpublished, freezing sponsor investment in commercial-scale manufacturing.
- Compounding pharmacy integration complexity:Hospital pharmacy information systems lack modules for lot tracking of live biological products with variable shelf lives, forcing manual workflow overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bacteriophages Therapy Market |
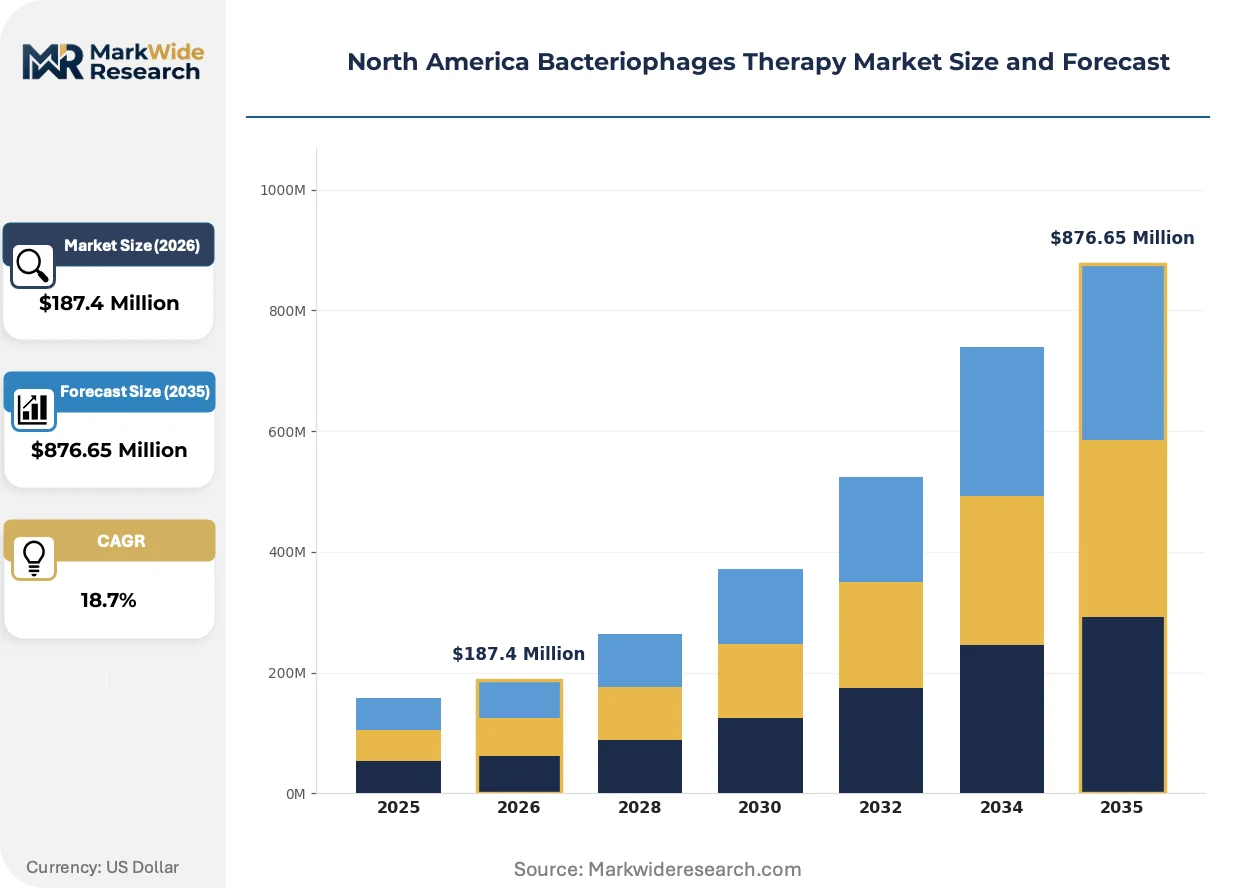
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Phages, Engineered Phages, Phage Combinations, Phage-Encoded Enzymes Application: Infectious Diseases, Food Safety, Agriculture, Veterinary Care Delivery Mode: Topical, Oral, Intravenous, Inhalation End User: Hospitals, Clinics, Research Laboratories, Agricultural Producers |
| Companies Covered | Intralytix, Inc., Armata Pharmaceuticals, Inc., Locus Biosciences, Adaptive Phage Therapeutics, BiomX, Cytophage Technologies Inc., Taconic Biosciences Inc., Zeptometrix, Phage International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bacteriophages Therapy Market Evolving Landscape
Engineering precision is displacing empirical phage selection across therapeutic applications, while regulatory frameworks race to catch up with manufacturing scale requirements.
CRISPR-Cas systems integrated into phage genomes are migrating from research-stage proof-of-concept to clinical manufacturing workflows. Academic medical centers in Boston and New York research corridors are piloting engineered phage banks with programmable resistance gene targeting. This migration from natural isolation to directed evolution is compressing development timelines and enabling personalized phage matching against patient-specific bacterial isolates.
Health Canada's Biologic and Radiopharmaceutical Drugs Directorate is revisiting stability testing requirements for live biological products, creating regulatory space for room-temperature phage formulations that would unlock rural hospital access. The industrial consequence is a manufacturing investment shift toward lyophilization and excipient development. Topical wound care applications are responding first, with sponsors submitting protocols that leverage the lower thermal stability thresholds already accepted for agricultural phage products.
Hospital procurement committees are unbundling phage therapy from bundled infection control contracts and establishing standalone therapeutic category budgets. This shift is disrupting traditional group purchasing organization channels that aggregated antibiotic and antiseptic purchasing. The Northeastern United States, particularly Massachusetts and New York state hospital networks, is most visible in this transition due to concentration of academic medical centers with existing phage research programs.
North America Bacteriophages Therapy Market Segmentation
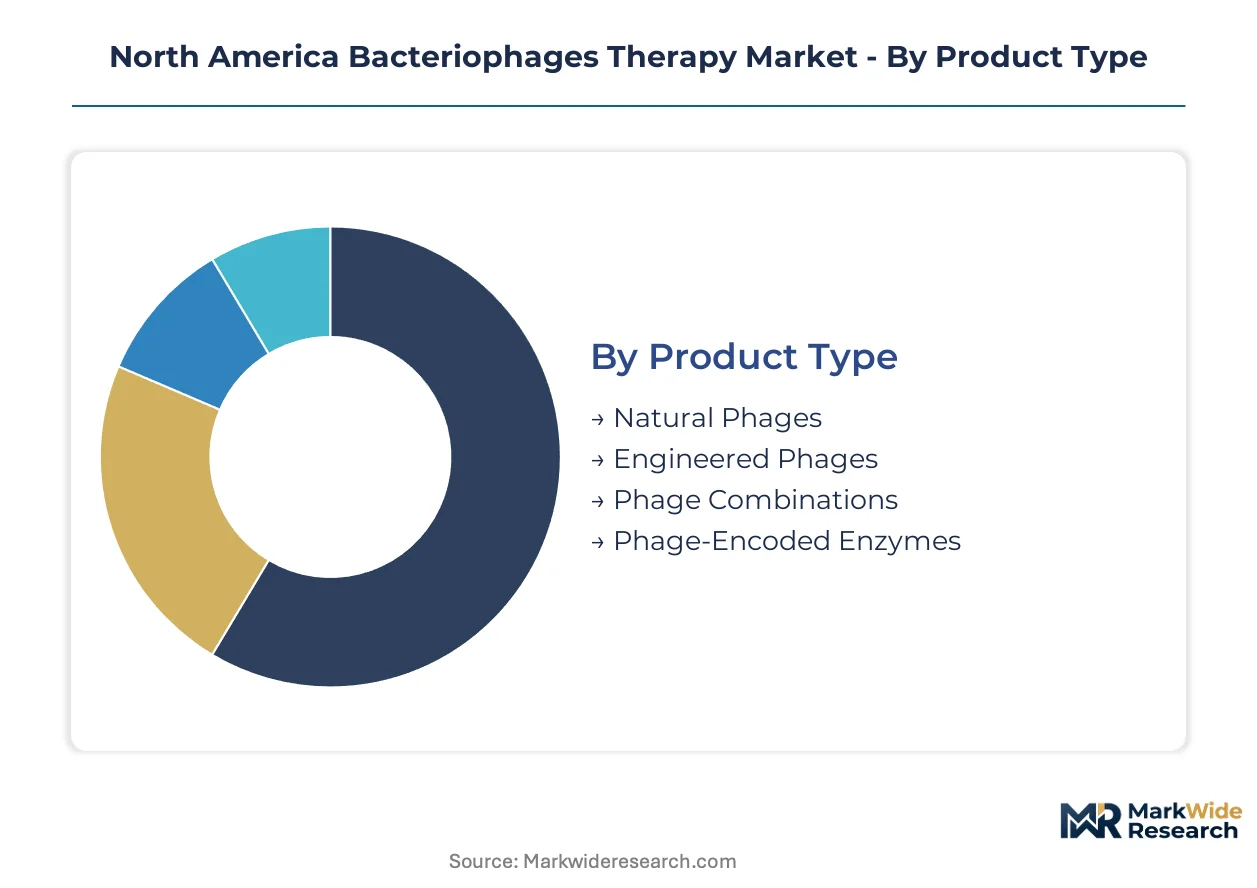
Phage therapy segmentation reveals divergent technical and commercial requirements across therapeutic versus prophylactic applications. Product architecture, delivery infrastructure, and end-user purchasing authority vary sharply between hospital infectious disease protocols and agricultural food safety deployments.
Product Type:
Cost tier stratification separates premium-positioned engineered platforms from commodity-scale natural phage production.
- Natural Phages:Wild-type viral isolates selected through empirical host-range screening against target bacterial strains. Demand concentrates in agricultural prophylaxis across the US Midwest and Canadian prairie provinces, where USDA Plant Protection Act compliance costs favor established isolation workflows over synthetic biology investment.
- Engineered Phages:CRISPR-Cas modified genomes with programmable resistance gene targeting and reduced immunogenicity profiles. Massachusetts and New York hospital networks are driving protocol adoption for multidrug-resistant Pseudomonas in burn wards, where precision lysis justifies premium reimbursement.
- Phage Combinations:Cocktail formulations combining multiple host-range specificities to delay resistance emergence.
- Phage-Encoded Enzymes:Purified lysins and depolymerases derived from phage genomes for direct antibacterial application.
Engineered Phages holds installed capacity. Natural Phages is rotating up the share rankings.
Application:
Application scope determines regulatory pathway complexity and margin structure across human therapeutic versus non-therapeutic sectors.
- Infectious Diseases:Hospital-based salvage therapy for antibiotic-refractory infections requiring FDA Center for Biologics Evaluation and Research investigational new drug oversight. Northeastern US academic medical centers in Boston and New York corridors are establishing protocol-level demand for cystic fibrosis and burn ward applications.
- Food Safety:Pre-harvest and post-harvest pathogen control on produce and meat products. Locus Biosciences and Intralytix anchor revenue in this segment through USDA-registered agricultural phage platforms with lower regulatory barriers than human therapeutics.
- Agriculture:Livestock and crop disease prophylaxis using environmental phage application.
- Veterinary Care:Companion animal and production animal therapeutic administration.
Infectious Diseases commands premium positioning. Food Safety is expanding most quickly through agricultural channel penetration.
Delivery Mode:
Delivery infrastructure requirements segment the market by cold chain dependence and administration setting.
- Intravenous:Direct bloodstream administration for systemic infections requiring sterile formulation and intensive monitoring. This mode carries the highest FDA regulatory burden but also the largest margin pool in US hospital settings, particularly for sepsis and endocarditis protocols.
- Topical:Wound care and dermatological application with lower stability thresholds. Veterans Affairs health networks across the US are piloting topical phage protocols for chronic wound infections, leveraging faster formulary adoption cycles than intravenous categories.
- Oral:Gastrointestinal targeting through encapsulated formulations resistant to gastric acid degradation.
- Inhalation:Nebulized delivery for respiratory tract infections including cystic fibrosis pulmonary colonization.
Topical holds installed capacity. Intravenous is climbing the fastest through hospital protocol expansion.
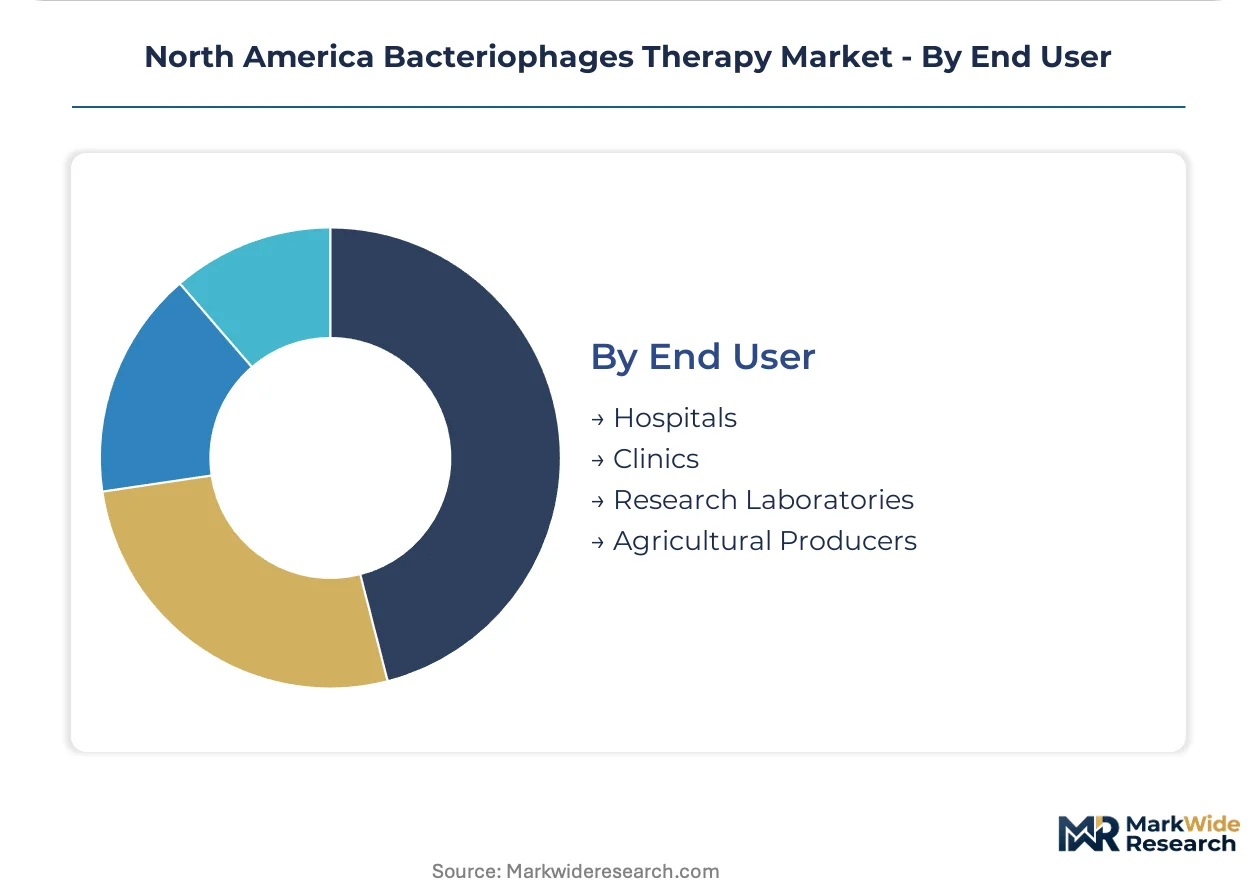
End User:
Customer purchasing authority shapes contract structure and technical support requirements.
- Hospitals:Academic medical centers and tertiary care facilities with infectious disease specialist capacity. Procurement committees in Massachusetts and New York state networks are unbundling phage therapy from bundled infection control contracts, creating standalone therapeutic category budgets.
- Research Laboratories:Academic and commercial R&D operations requiring characterized phage banks for directed evolution and host-range expansion studies. Toronto and Montreal clusters concentrate bioreactor capacity serving this segment.
- Clinics:Outpatient settings with limited cold chain infrastructure.
- Agricultural Producers:Farm and processing operations purchasing USDA-regulated phage products for food safety compliance.
Hospitals anchor revenue concentration. Research Laboratories is gaining share fastest through CRISPR-engineered phage platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioreactor capacity clusters in Toronto and Montreal anchor North American phage manufacturing, while FDA expanded access protocols concentrate clinical demand in Boston and New York research corridors.
United States
Boston and New York academic medical centers drive hospital-based infectious disease protocols for multidrug-resistant Pseudomonas in burn and cystic fibrosis wards. FDA Center for Biologics Evaluation and Research oversight shapes investigational new drug pathways for phage cocktails. Massachusetts and New York state hospital networks are unbundling phage therapy from bundled infection control contracts.
Canada
Toronto and Montreal bioreactor clusters control the majority of North American phage manufacturing infrastructure, creating cross-border supply dependencies for US hospital networks. Health Canada's Biologic and Radiopharmaceutical Drugs Directorate establishes parallel review frameworks for cross-border product development. Ontario and Quebec production facilities are expanding capacity to serve both research laboratory and clinical manufacturing demand.
Mexico
Veterinary care applications and agricultural food safety prophylaxis represent the primary demand channels as human therapeutic regulatory pathways remain under development. The country's national pharmaceutical regulator maintains alignment with FDA biologics standards for future market access. Northern border states concentrate pilot programs for livestock phage applications serving US-Mexico integrated supply chains.
North America Bacteriophages Therapy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in phage isolation and characterization services. The vendor base separates between CRISPR-engineered phage developers with precision antibacterial platforms and natural phage suppliers serving agricultural prophylaxis markets. Three archetypes dominate: engineered platform developers, agricultural food safety registrants, and clinical-stage infectious disease specialists. Capacity expansion in Canadian bioreactor clusters and strategic partnerships between academic medical centers and platform developers represent the dominant competitive moves.
Among US-based clinical-stage developers, Armata Pharmaceuticals, Inc. and Adaptive Phage Therapeutics occupy positions within the infectious disease salvage therapy archetype, while Intralytix, Inc. anchors the agricultural food safety segment through FDA-registered platforms. These three companies exemplify the market's bifurcation between premium therapeutic applications and lower-regulatory-barrier prophylaxis markets.
| Leading Market Players |
|---|
| Intralytix, Inc. |
| Armata Pharmaceuticals, Inc. |
| Locus Biosciences |
| Adaptive Phage Therapeutics |
| BiomX |
| Cytophage Technologies Inc. |
| Taconic Biosciences Inc. |
| Zeptometrix |
| Phage International, Inc. |
| Others |
Value Network & Pricing Analysis
Bioreactor undercapacity in Toronto and Montreal clusters is forcing US hospital networks to accept premium pricing for phage cocktail formulations while driving investment into distributed compounding alternatives that bypass cross-border supply dependencies.
Pricing Analysis
FDA Center for Biologics Evaluation and Research oversight dictates the pricing tier structure across investigational new drug pathways. Three-tier pricing separates engineered CRISPR platforms from natural phage cocktails and agricultural prophylaxis formulations. Cost compression in natural phage tiers is intensifying because USDA Plant Protection Act pathways carry lower validation burdens than human therapeutic applications. Agricultural producers exhibit highest price sensitivity, while Massachusetts and New York hospital networks accept premium positioning for precision antibacterial salvage therapy.
Supply Chain Analysis
Extended payment terms from Canadian bioreactor operators are financing working capital for US hospital network procurement. Manufacturing capacity concentrates in Canada, with raw material dependencies on characterized phage banks, sterile fermentation media, and cold chain logistics infrastructure. Single-source vulnerability runs through Toronto-Montreal corridor concentration, as no alternative North American capacity exists at clinical-grade scale. Distribution feeds from Canadian production clusters through specialized biologics couriers to northeastern US academic medical centers and Veterans Affairs health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as hospital procurement committees unbundle phage therapy from bundled infection control contracts, creating standalone therapeutic category budgets that favor specialized vendors over diversified antibiotic suppliers.
For Market Incumbents: Pre-empt CRISPR-engineered phage platform commoditization by securing exclusive hospital formulary contracts in Boston and New York corridors before FDA guidance document revisions standardize cocktail composition rules. Backward integration into captive bioreactor capacity in Ontario or Quebec reduces cross-border supply vulnerability. Channel control through direct pharmacy information system integration addresses compounding workflow friction. For New Entrants and Emerging Players: Veterans Affairs health networks in the US Southeast and Midwest represent the most penetrable channel, with topical wound care protocols offering faster formulary adoption cycles than intravenous categories. Agricultural food safety applications in the US Midwest and Canadian prairie provinces provide lower-regulatory-barrier revenue anchoring while clinical capabilities mature. Partner with existing USDA-registered platforms for co-development rather than building de novo regulatory infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-stage infectious disease specialists with existing FDA expanded access program experience and multidrug-resistant Pseudomonas protocol data. Long-term viability hinges on regulatory clarity rather than manufacturing scale alone. The signal to watch is FDA publication of phage cocktail standardization guidance, which would unlock commercial-scale manufacturing investment and consolidate sponsor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expanded access program data from Boston and New York corridors accelerates FDA investigational new drug pathway validation. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Toronto and Montreal clusters reduces single-source vulnerability for US hospital networks. |
| Regulatory Approval Pathway | Health Canada parallel review frameworks enable cross-border harmonization that compresses dual-approval timelines for sponsors. |
| Strategic Partnership | Academic medical center alliances provide access to patient-specific bacterial isolate banks for personalized phage matching. |
| Platform Integration | CRISPR-engineered phage banks with programmable resistance gene targeting displace empirical selection in precision antibacterial applications. |
Research Methodology
A standing panel of infectious disease specialists, hospital formulary directors, regulatory affairs leads at phage therapy developers, and USDA agricultural product registrants provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA expanded access program records, Health Canada biologic submission databases, ClinicalTrials.gov phage therapy protocols, and hospital procurement database extracts. Bottom-up demand modeling from individual hospital protocol adoption and top-down capacity analysis from Canadian bioreactor operators were triangulated to produce volume and value estimates.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation dimensions including product architecture (engineered versus natural phage platforms), delivery mode (intravenous, topical, inhalation), application sector (infectious disease, food safety, agriculture), and end-user purchasing authority (hospital procurement committees, agricultural producers, research laboratories). CAGRs were derived from protocol-level demand build-ups and manufacturing capacity expansion schedules. Forecast inputs included FDA guidance document revision timelines and Health Canada stability testing requirement updates for live biological products.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CRISPR-platform specialists or agricultural phage registrants would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding regulatory clarity progression and hospital procurement committee unbundling velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
AI for Drug Discovery Market