
 Cell Isolation Market | 2026-2036
Cell Isolation Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Isolation Market Intelligence
The EU Green Deal is rebalancing procurement criteria for cell isolation consumables toward lower-plastic, recyclable formats. Thermo Fisher Scientific leverages its consumables scale to sustain contract positions across academic core facilities. Danaher Corporation anchors its position through integrated workflow automation spanning separation to analysis. Miltenyi Biotec dominates magnetic bead technology with proprietary column-based systems that command premium placement in stem cell laboratories.
Cell isolation encompasses the mechanical, enzymatic, or immunological separation of target cell populations from heterogeneous biological samples, typically achieving purity thresholds above 95% viability for downstream genomic or proteomic analysis. Magnetic separation systems lead the technology landscape due to protocol simplicity and reproducibility, while microfluidics represents the fastest-expanding segment as lab-on-chip devices reduce sample volume requirements and integrate with single-cell sequencing pipelines. Reagents and kits capture the largest product type share because recurring purchase cycles outpace instrument replacement timelines.
The FDA enforces Current Good Manufacturing Practice standards for cell therapy manufacturing that mandate documented isolation purity and traceability, while the EMA's Advanced Therapy Medicinal Products framework imposes comparable batch-release criteria across European manufacturing sites. ISO 13485 certification shapes supplier qualification for instrument vendors serving diagnostic and therapeutic end users. Stakeholders must weigh automation investment against manual protocol flexibility as regulatory divergence between regional pharmacopeias complicates global kit formulation strategies.
Market Dynamics
CAR-T manufacturing scale-up is compressing isolation protocol timelines while FDA and EMA purity mandates tighten simultaneously, forcing biopharmaceutical producers to choose between automation capital deployment and manual flexibility retention.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Batch-release criteria for cell therapies mandate documented isolation traceability, pulling investment into qualified separation systems across European manufacturing sites.
- Microfluidics convergence with single-cell sequencing:Lab-on-chip devices reduce sample volumes while preserving viability, accelerating adoption in academic core facilities and precision medicine programs.
- China biopharmaceutical manufacturing expansion:NMPA cell therapy guidance alignment with international standards drives demand for GMP-compliant magnetic separation infrastructure in Shanghai and Suzhou clusters.
Market Restraints
- Proprietary reagent lock-in:Column-based magnetic bead systems bind users to consumable ecosystems with limited interchangeability, inflating lifetime cost structures.
- Enzyme supply concentration:Collagenase and dispase production clusters in Denmark and Germany expose downstream users to input volatility and batch consistency risks.
- ISO 13485 certification timelines:Diagnostic instrument vendors face 12-18 month qualification periods that delay market entry and compress early revenue windows.
Strategic Opportunities
- India CDMO emergence:CDSCO cell therapy regulations maturing alongside PLI scheme biopharma incentives create greenfield demand for scalable isolation platforms in Hyderabad and Bengaluru.
- EU Green Deal procurement criteria:Recyclable consumable formats and reduced-plastic reagent packaging open contract repositioning at German and French academic core facilities.
- Automation-to-analysis integration:Workflow unification spanning cell separation through flow cytometry compresses labor costs and error rates for high-throughput screening operations.
Industry Challenges
- GMP compliance talent scarcity:Cell therapy manufacturing requires operators trained in both aseptic technique and isolation platform validation, with qualified personnel concentrated in Boston, Basel, and Singapore.
- Legacy instrument interoperability:Automated separation systems must integrate with existing LIMS and sample tracking infrastructure without disrupting validated workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Isolation Market |
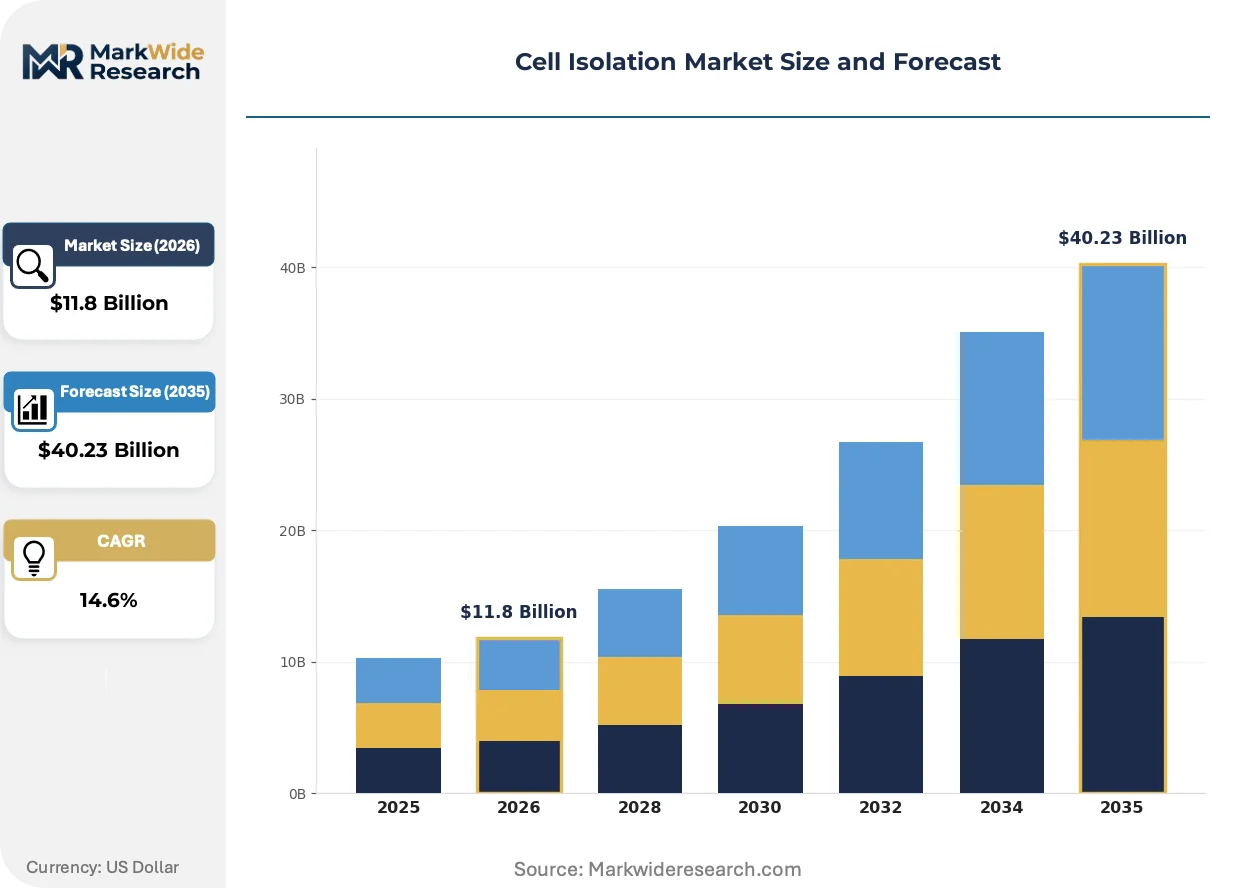
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Consumables Technology: Magnetic Separation, Density Gradient Centrifugation, Microfluidics, Flow Cytometry Application: Stem Cell Research, Cancer Research, Drug Discovery, Genetic Testing End User: Academic Institutions, Pharmaceutical Companies, Biotech Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Becton, Dickinson and Company, Merck KGaA, Bio-Rad Laboratories Inc., Terumo Corporation, STEMCELL Technologies Inc., Corning Incorporated, Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Isolation Market Strategic Shifts & Innovations
Acoustic and dielectrophoretic separation modalities are advancing from research curiosity to pilot-scale deployment, challenging magnetic bead dominance in applications demanding label-free cell recovery.
Acoustic cell separation is electrifying the field by enabling contact-free, label-free isolation based on physical properties rather than surface marker binding. CAR-T developers in the United States and Germany are piloting these systems for T-cell subsets where bead remnants complicate downstream processing. The technology is electrifying competitive positioning by eliminating consumable dependencies and reducing regulatory documentation burdens for residual bead testing.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing reagent reformulation across European supply chains. Magnetic bead coatings and surface chemistries face substance scrutiny that threatens existing product registrations. German and Swiss reagent suppliers are accelerating fluorine-free alternatives to defend contract positions ahead of anticipated 2026-2027 enforcement windows.
Service unbundling is fragmenting traditional instrument-reagent bundling models as biopharmaceutical procurement teams demand à la carte maintenance and flexible consumable sourcing. Large-scale CDMOs in the United States and China are negotiating separate pricing for hardware, software, and reagent tiers, compressing vendor margin structures. This pattern is most visible in multi-site CAR-T manufacturing networks where standardization across locations conflicts with vendor-exclusive supply agreements.
Cell Isolation Market Segmentation
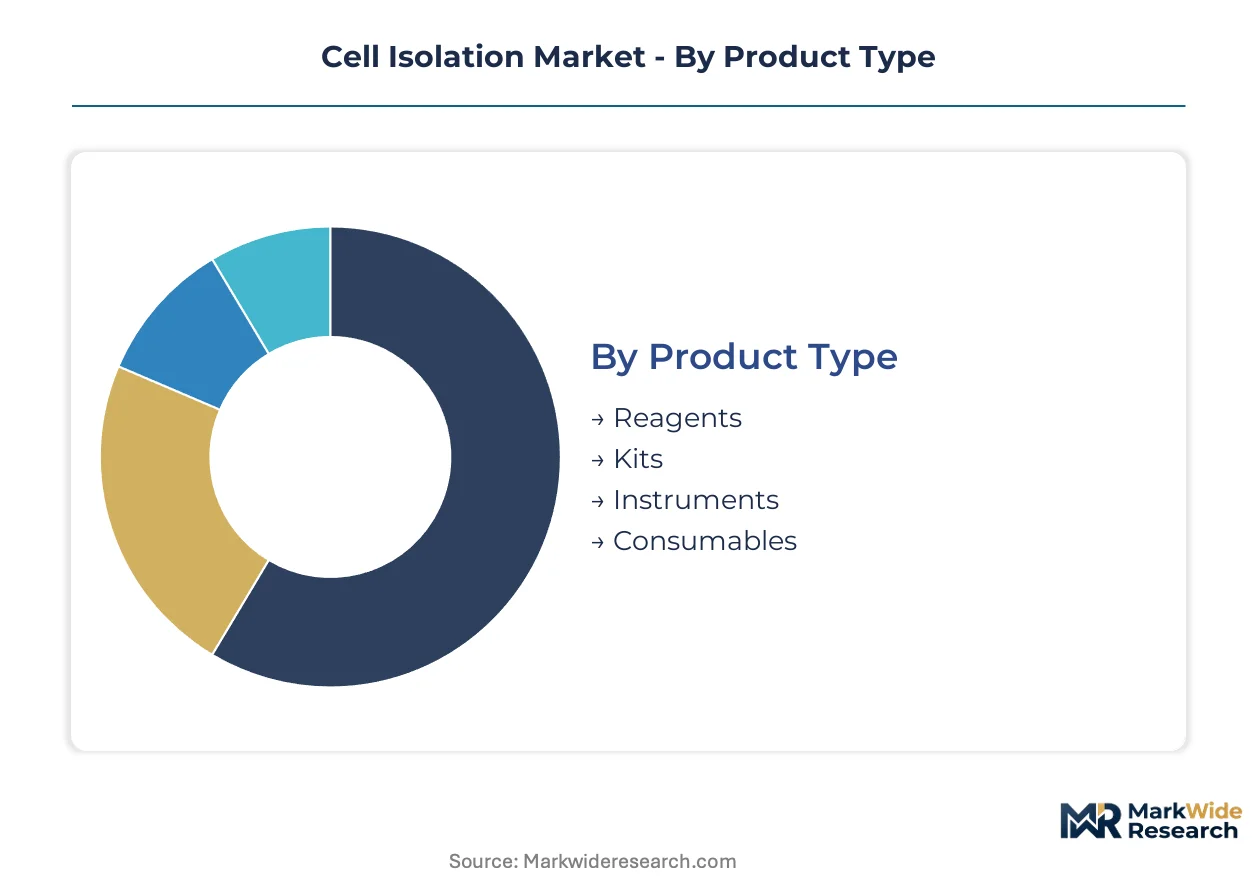
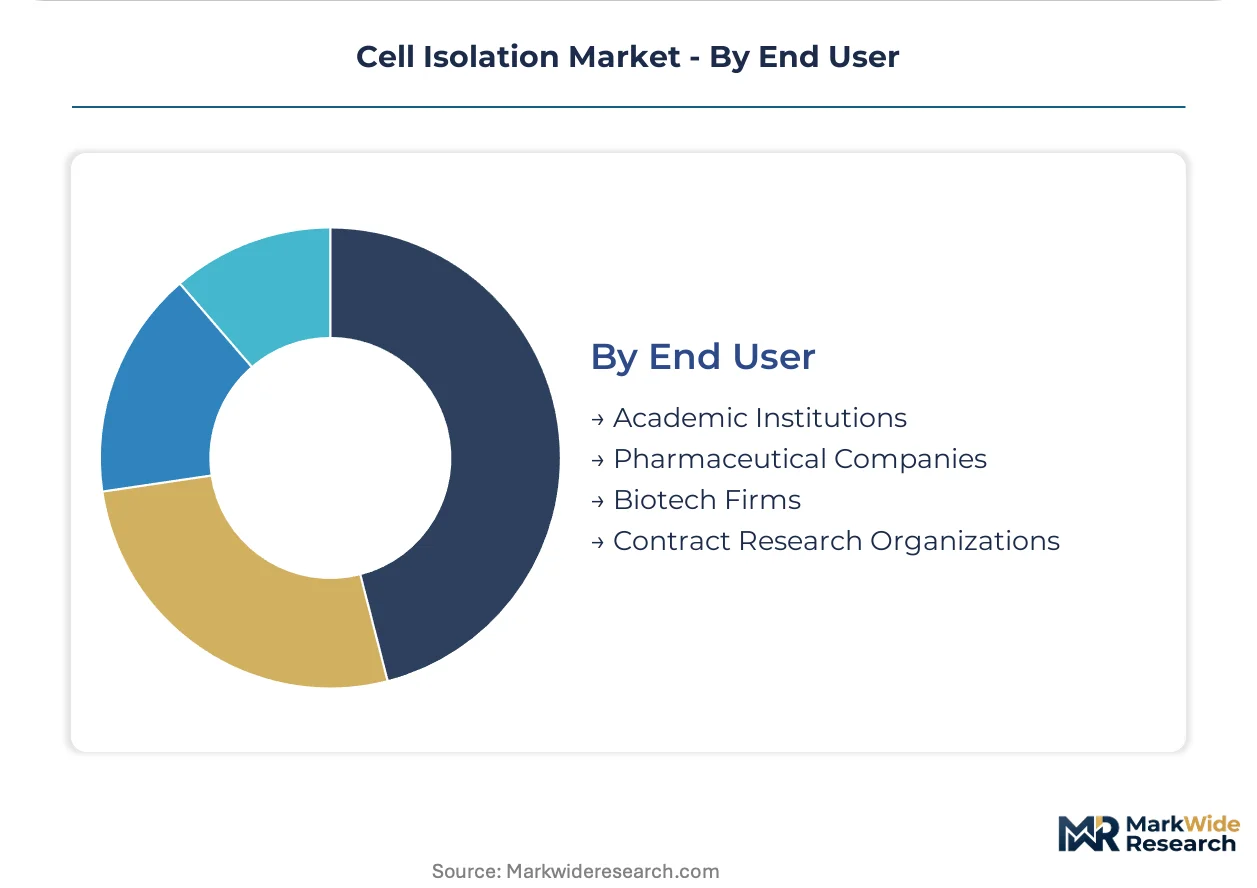
Cell isolation procurement decisions diverge sharply across user archetypes, with academic core facilities prioritizing protocol flexibility while pharmaceutical manufacturers optimize for batch reproducibility and regulatory documentation. Understanding these segment-specific purchasing logics clarifies where automation investments yield returns versus where manual workflows retain competitive advantage.
Product Type:
Reagent purchasing cycles dominate operational budgeting for high-throughput facilities, with contract structures reflecting volume commitments and shelf-life constraints.
- Reagents:Enzymatic dissociation cocktails and buffer formulations constitute recurring procurement with 6-12 month stability windows. CAR-T manufacturers in the United States and Germany negotiate multi-year supply agreements to secure collagenase batch consistency amid concentration of production in Denmark.
- Kits:Pre-formulated isolation systems bundle reagents, protocols, and quality documentation to reduce validation burden. Academic institutions in China favor kit formats to accelerate graduate training and minimize protocol optimization overhead.
- Instruments:Automated separation platforms require capital allocation cycles spanning 5-7 year depreciation schedules. Biopharmaceutical companies weigh FDA 21 CFR Part 11 compliance features against total cost of ownership.
- Consumables:Columns, tubes, and single-use separation chambers generate recurring revenue tied to instrument installed base. EU Green Deal procurement criteria are shifting demand toward recyclable formats in France and Germany.
Reagents lead on scale; microfluidics-ready consumables lead on momentum.
Technology:
Technology selection hinges on sample volume requirements and downstream analytical compatibility, with magnetic systems dominating clinical translation while microfluidics captures precision medicine applications.
- Magnetic Separation:Column-based and tube-based systems achieve 95%+ purity through antibody-coated bead binding. Stem cell laboratories in Basel and Singapore maintain premium placements for Miltenyi Biotec systems due to established SOP libraries.
- Microfluidics:Lab-on-chip devices integrate acoustic, dielectrophoretic, or hydrodynamic separation with sample volumes below 100 microliters. Single-cell sequencing pipelines in Boston and Suzhou drive adoption for rare cell recovery applications.
- Density Gradient Centrifugation:Ficoll and Percoll protocols remain cost-effective for bulk lymphocyte isolation. Blood processing centers in India leverage established infrastructure for diagnostic sample preparation.
- Flow Cytometry:Fluorescence-activated cell sorting delivers highest purity for complex immunophenotyping. Cancer research centers combine FACS with downstream genomic analysis for clonal evolution studies.
Magnetic separation commands installed base; microfluidics climbs fastest on precision medicine tailwinds.
Application:
Application-driven purchasing reflects divergent purity thresholds and throughput requirements, with therapeutic manufacturing imposing GMP documentation burdens absent from research use.
- Stem Cell Research:Pluripotent and adult stem cell isolation demands viability preservation above 90% for expansion protocols. Academic core facilities in Heidelberg and Kyoto prioritize gentle separation modalities for fragile populations.
- Cancer Research:Circulating tumor cell isolation from blood requires enrichment factors exceeding 10^6 for downstream mutation profiling. Liquid biopsy programs in the United States integrate microfluidic capture with NGS pipelines.
- Drug Discovery:Primary cell isolation for toxicity screening emphasizes batch consistency across multi-site campaigns. Pharmaceutical companies standardize on automated platforms to reduce inter-operator variability.
- Genetic Testing:Fetal cell and circulating DNA isolation from maternal blood drives non-invasive prenatal testing volume. Diagnostic laboratories in China scale magnetic bead protocols for population screening programs.
Cancer research leads on technology premium; genetic testing leads on volume scaling.
End User:
End-user procurement authority varies with organizational scale, with contract research organizations consolidating purchasing across sponsor programs while biotech firms retain flexibility for platform switching.
- Academic Institutions:Core facilities manage shared instrumentation with user fee structures and training certification requirements. German and French universities face EU Green Deal pressure to reduce plastic consumable footprints.
- Pharmaceutical Companies:CAR-T manufacturing sites demand GMP-qualified systems with batch record integration. FDA and EMA guidance compliance drives validation documentation investment.
- Biotech Firms:Emerging cell therapy developers balance automation capital constraints against manual protocol flexibility. Boston and San Diego clusters concentrate early-stage demand.
- Contract Research Organizations:CDMOs serving multiple sponsors require platform standardization across sites with sponsor-specific protocol adaptation. Indian CROs in Hyderabad and Bengaluru scale for international cell therapy contract manufacturing.
Pharmaceutical companies lead on contract value; CROs lead on platform standardization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified cell therapy manufacturing operators concentrate in Boston, Basel, and Singapore, anchoring regional demand clusters where GMP compliance expertise commands wage premiums and shapes facility investment decisions.
United States
FDA Current Good Manufacturing Practice standards for cell therapies mandate documented isolation purity and traceability, pulling investment into qualified separation systems. The 21 CFR Part 11 compliance requirements for electronic batch records drive automation procurement in CAR-T manufacturing. Boston and San Diego biotech clusters concentrate early-stage demand for flexible isolation platforms.
Germany
EMA Advanced Therapy Medicinal Products framework imposes batch-release criteria that require documented isolation traceability across European manufacturing sites. REACH restriction proposals on per- and polyfluoroalkyl substances force reagent reformulation across supply chains. Heidelberg and Munich academic core facilities face EU Green Deal pressure to reduce plastic consumable footprints.
China
NMPA cell therapy guidance alignment with international standards drives demand for GMP-compliant magnetic separation infrastructure. The country's biopharmaceutical manufacturing expansion concentrates in Shanghai and Suzhou clusters. Graduate training programs at Chinese academic institutions favor pre-formulated kit formats to minimize protocol optimization overhead.
India
CDSCO cell therapy regulations maturing alongside PLI scheme biopharma incentives create greenfield demand for scalable isolation platforms. Collagenase and dispase supply concentration in Europe exposes Indian downstream users to input volatility. Hyderabad and Bengaluru CDMOs scale for international cell therapy contract manufacturing.
Switzerland
Swissmedic maintains stringent batch-release criteria comparable to EMA standards for advanced therapy medicinal products. REACH-aligned substance scrutiny threatens existing magnetic bead coating registrations. Basel anchors stem cell laboratory demand where established SOP libraries sustain premium system placements.
Cell Isolation Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the cell isolation landscape, with integrated workflow vendors holding installed base advantages against specialized component suppliers. The market structure tilts toward consolidation at the premium tier where recurring consumable revenue locks in multi-year contracts. Three archetypes dominate: diversified life science conglomerates with consumables scale, integrated automation specialists spanning separation to analysis, and magnetic bead technology purists with proprietary column ecosystems. Competitive moves concentrate on automation-to-analysis integration and service unbundling to capture CDMO procurement flexibility.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions where consumables scale and integrated workflow automation anchor contract retention across academic and pharmaceutical segments. Miltenyi Biotec exemplifies the magnetic bead technology specialist archetype with proprietary column-based systems that command premium placement in stem cell laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Merck KGaA |
| Bio-Rad Laboratories Inc. |
| Terumo Corporation |
| STEMCELL Technologies Inc. |
| Corning Incorporated |
| Miltenyi Biotec |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between GMP-qualified and research-use-only systems splits the Cell Isolation Market into divergent cost structures. Premium placements in Basel and Boston command sustained margin premiums through FDA and EMA validation documentation, while academic procurement in India and China gravitates toward unbundled consumable sourcing that compresses vendor pricing power.
Pricing Analysis
Bundled instrument-reagent contracts versus unbundled à la carte service tiers now define competitive positioning across the Cell Isolation Market. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and automation integration depth. Pricing pressure stems from CDMO procurement teams demanding separate hardware, software, and reagent negotiations. Academic core facilities exhibit highest price sensitivity; CAR-T manufacturers show lowest sensitivity due to batch-release compliance mandates.
Supply Chain Analysis
Logistics and freight cost volatility for temperature-sensitive enzymatic reagents now shapes inventory positioning across the Cell Isolation Market. Collagenase and dispase production concentrates in Denmark and Germany, exposing downstream users to input volatility. Magnetic bead coatings draw from fluorine-based chemistries facing REACH restriction timelines. Single-source vulnerability runs through European enzyme suppliers. Distribution runs through authorized distributor networks with GMP qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cell Isolation Market offers margin expansion through consumable recurring revenue capture and premium automation tier migration. Cost compression in manual protocol segments creates acquisition opportunities for integrated workflow vendors.
For Market Incumbents: Anchor installed base retention through proprietary column consumable ecosystems that resist interchangeability. Defend against acoustic separation displacement by accelerating automation-to-analysis integration investments. Prioritize backward integration into fluorine-free bead coating chemistries ahead of REACH enforcement windows. For New Entrants and Emerging Players: Direct-to-CDMO digital procurement platforms offer the most penetrable route into fragmented Indian and Chinese contract manufacturing demand. Target service-unbundled pricing models at multi-site CAR-T networks where standardization conflicts with vendor-exclusive agreements. Lead with microfluidics-ready consumable formats for single-cell sequencing pipeline integration. For Investors and Strategic Acquirers: Consolidation pressure builds where GMP compliance talent scarcity concentrates qualified manufacturing operators in Boston, Basel, and Singapore. Five-to-ten-year viability favors integrated workflow automation specialists over pure-play reagent vendors. Watch NMPA cell therapy guidance harmonization with FDA standards as inflection signal for China infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA 21 CFR Part 11 compliance features differentiate automated platforms for CAR-T manufacturers. |
| Manufacturing Scale-Up | GMP-qualified magnetic separation infrastructure expansion captures NMPA-aligned demand in Shanghai clusters. |
| Backward Integration | In-house fluorine-free bead coating production defends European contract positions against REACH substance scrutiny. |
| Platform Integration | Acoustic separation modules integrated with single-cell sequencing pipelines challenge magnetic bead dominance. |
| Geographic Expansion | Hyderabad and Bengaluru CDMO scaling creates greenfield demand for scalable isolation platforms. |
Research Approach
Direct dialogue with cell therapy manufacturing executives, regulatory affairs leads at EMA and FDA, academic core facility directors, and CDMO procurement managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, EMA Advanced Therapy Medicinal Products assessments, ISO 13485 certification databases, and customs trade data for enzymatic reagent flows. Bottom-up instrument and consumable unit economics triangulated against top-down market sizing across technology and application segments.
Segment-level value outputs were derived through installed base modeling, replacement cycle analysis, and recurring revenue coefficient estimation across the projection horizon. Technology segmentation captured magnetic separation, microfluidics, density gradient centrifugation, and flow cytometry modalities. Application dimensions spanned stem cell research, cancer research, drug discovery, and genetic testing. End-user archetypes included academic institutions, pharmaceutical companies, biotech firms, and contract research organizations. CAGRs were computed from compound growth trajectory fitting against validated baseline data points.
EMA guidance revision, REACH enforcement timing on fluorine-based coatings, and NMPA regulatory harmonization pace are the dominant revision risks to forecast assumptions. Model refresh is warranted upon material change in cell therapy manufacturing automation capital deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
In Vitro Protein Expression Market