
 AI for Drug Discovery Market | 2026-2036
AI for Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
AI for Drug Discovery Market Analysis
Mid-sized biotechnology firms is rotating toward AI-native discovery platforms faster than legacy pharmaceutical conglomerates, reshaping procurement patterns across the sector. Recursion Pharmaceuticals leverages its phenomic data infrastructure to sustain high-throughput experimental loops. Insilico Medicine anchors its competitive position through generative chemistry engines that design novel molecular structures. Exscientia differentiates via autonomous laboratory systems that close the loop between computational prediction and physical validation.
AI for drug discovery denotes the application of computational algorithms, statistical models, and neural architectures to identify therapeutic targets, design molecular candidates, and predict clinical outcomes with reduced reliance on traditional wet-laboratory screening. These systems process multi-omic datasets, chemical structure libraries, and biomedical literature to generate testable hypotheses, compressing timelines that previously spanned years into months. Deep learning architectures now dominate the technology landscape, with convolutional and transformer-based models capturing complex biochemical relationships that simpler statistical methods miss. Target identification and compound screening applications absorb the majority of platform investment, though clinical trial optimization represents an emerging margin pool as sponsors seek to reduce patient recruitment failures and protocol amendments.
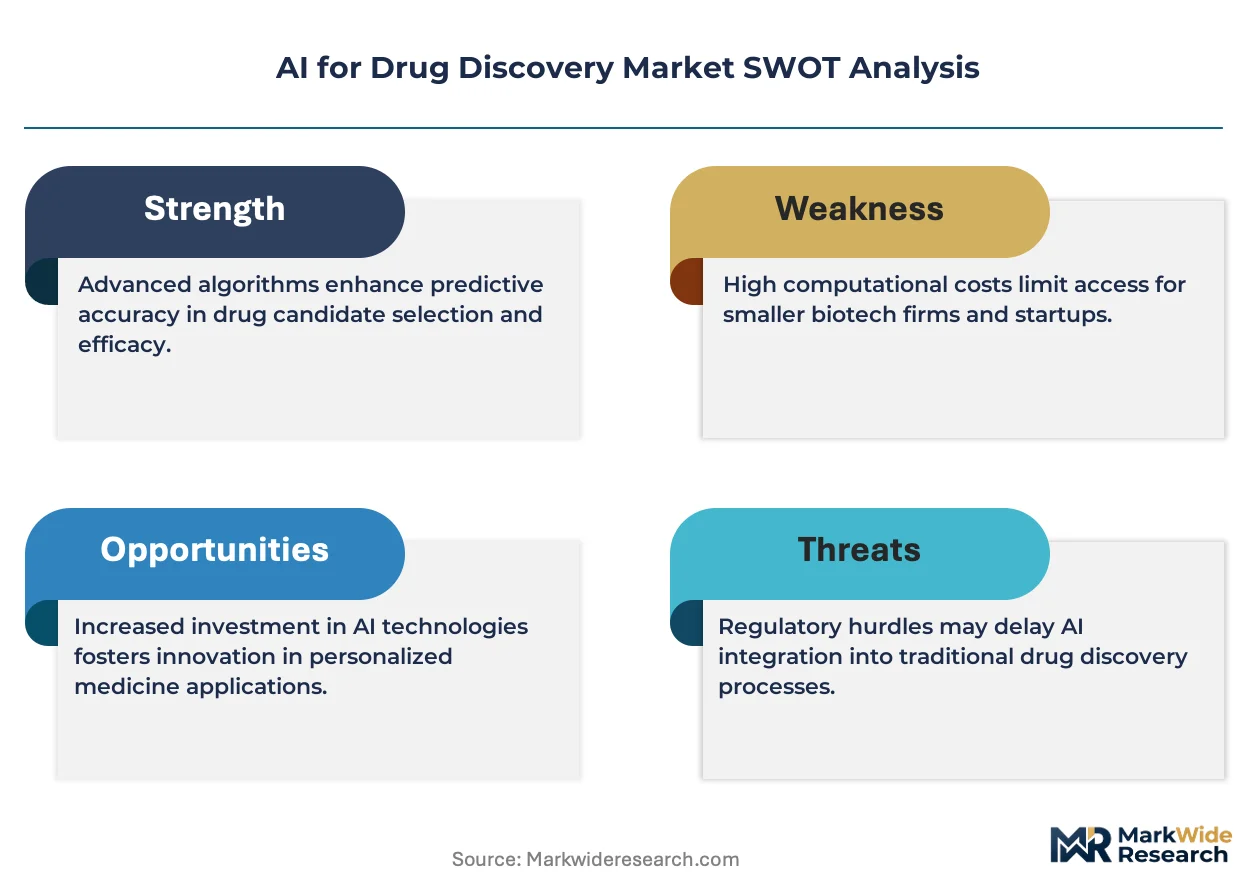
The FDA, EMA, and WHO collectively shape market access through divergent postures on algorithmic transparency, training data provenance, and validation standards for AI-derived biomarkers. The FDA's emerging framework for model-informed drug development tools demands documented performance across demographic subgroups, directly influencing platform design priorities. Stakeholders must monitor regulatory convergence trajectories, as misalignment between jurisdictions on evidentiary thresholds for algorithmic predictors could fragment commercialization pathways and force redundant validation investments.
Market Dynamics
Generative chemistry engines are compressing molecular design timelines from years to months, forcing biopharmaceutical buyers to restructure R&D procurement around platform-based partnerships rather than traditional fee-for-service contracts.
Growth Catalysts
- FDA Model-Informed Drug Development Framework:The FDA's emerging guidance on algorithmic predictors creates validation pathways that institutionalize AI-derived biomarkers in regulatory submissions.
- Transformer architectures:Deep learning models now capture biochemical relationships that statistical methods miss, expanding addressable target classes for previously intractable diseases.
- Venture capital deployment:Federal research funding in the United States concentrates computational biology investment, accelerating platform commercialization timelines.
Market Restraints
- Training data provenance requirements:The FDA's documentation demands for demographic subgroup performance inflate validation costs and extend platform qualification timelines.
- Algorithmic transparency mandates:Divergent EMA and FDA postures on explainability standards force redundant validation investments for multi-jurisdictional sponsors.
- Specialized talent scarcity:The intersection of computational biology and medicinal chemistry expertise remains concentrated in Boston and San Francisco clusters, constraining platform scaling.
Strategic Opportunities
- Clinical trial optimization:AI-enabled patient stratification and recruitment prediction represents an emerging margin pool as sponsors seek protocol amendment reductions.
- Japan's regulatory convergence:PMDA's evolving posture on algorithmic biomarkers creates first-mover advantages for platforms validating under harmonized FDA-PMDA frameworks.
- Phenomic data infrastructure:High-throughput experimental loops integrating imaging and transcriptomics open new target identification categories beyond traditional genomics.
Industry Challenges
- Wet-laboratory integration complexity:Closing the loop between computational prediction and physical validation requires capital-intensive autonomous laboratory systems that strain mid-sized firm balance sheets.
- Cross-jurisdictional compliance fragmentation:Misalignment between FDA, EMA, and WHO evidentiary thresholds forces platform architects to maintain parallel validation tracks.
- IP licensing friction:Training data access agreements and algorithmic output ownership disputes complicate partnership structures between AI platform vendors and biopharmaceutical sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI for Drug Discovery Market |
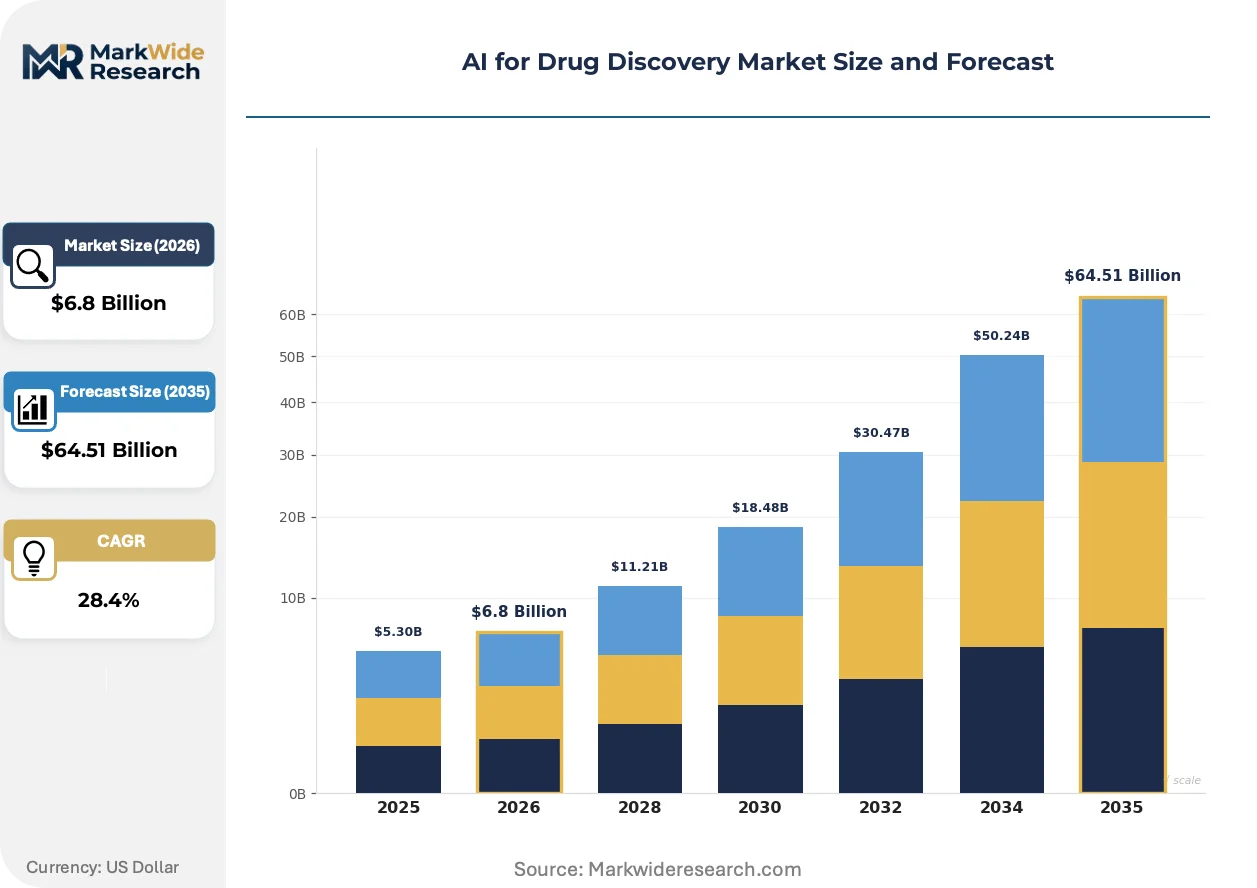
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Deep Learning, Reinforcement Learning Application: Target Identification, Compound Screening, Preclinical Testing, Clinical Trials End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Solution: Software Platforms, Data Analytics Tools, Cloud-Based Solutions, Consulting Services |
| Companies Covered | Recursion Pharmaceuticals, Insilico Medicine, Exscientia, Atomwise, BenevolentAI, Schrödinger, Isomorphic Labs, Insitro, Valo Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI for Drug Discovery Market Emerging Trajectories
Computational architectures are displacing traditional screening paradigms across the discovery value chain. Three developments are compressing timelines and restructuring competitive positioning.
Transformer-based molecular generators are displacing structure-based virtual screening in lead optimization workflows. Biopharmaceutical sponsors with internal AI capabilities now bypass traditional contract research organizations for hit-to-lead programs. This compression is eliminating fee-for-service chemistry providers from high-value discovery segments.
REACH and the EU AI Act are imposing algorithmic transparency requirements that diverge from FDA disclosure standards. Platform vendors must now engineer dual-track explainability modules to satisfy European chemical safety and AI liability frameworks. Mid-sized biotechnology firms prioritizing European market access are selecting vendors with pre-validated EU compliance architectures.
Biopharmaceutical procurement now favors platform subscriptions with milestone-linked pricing over traditional full-time-equivalent arrangements. Early-stage biotechnology companies in the United States are unbundling discovery services, purchasing target identification from specialized AI vendors while retaining medicinal chemistry in-house. This fragmentation is eroding integrated contract research organization margins in Boston and San Diego clusters.
AI for Drug Discovery Market Segmentation
Technology and application boundaries in AI drug discovery are dissolving as platform vendors bundle capabilities into unified workflows. Buyers now evaluate segments based on integration depth rather than isolated feature sets, compressing procurement cycles for modular solutions.
Technology:
Platform vendors route computational modules through distinct channel architectures depending on technical complexity and deployment maturity.
- Deep Learning:Convolutional and transformer architectures process multi-omic datasets to capture biochemical relationships beyond statistical reach. Biopharmaceutical sponsors in the United States concentrate procurement here, driven by FDA validation pathways for model-informed drug development tools.
- Machine Learning:Random forest and gradient boosting algorithms handle structured molecular property prediction with lower computational overhead. Mid-sized biotechnology firms favor these implementations for target identification pipelines where training data volume constrains neural approaches.
- Natural Language Processing:Extracts therapeutic hypotheses from biomedical literature and patent corpora. Research institutions deploy these tools to map disease mechanism networks.
- Reinforcement Learning:Optimizes molecular design through iterative reward feedback in simulated environments. Emerging adoption concentrates among sponsors with autonomous laboratory integration.
Deep Learning dominates installed base. Reinforcement Learning is where expansion concentrates.
Application:
Cost tier stratification separates high-investment preclinical modules from lower-margin clinical optimization tools.
- Target Identification:Multi-omic data integration pinpoints disease-modifying proteins and pathways. Venture capital deployment in Boston and San Francisco accelerates platform commercialization for this segment.
- Compound Screening:Virtual libraries of billions of molecules are evaluated against predicted binding affinity. Pharmaceutical companies redirect procurement from contract research organizations toward direct platform subscriptions.
- Preclinical Testing:Predictive toxicology and pharmacokinetic modeling reduce animal study requirements. EMA algorithmic transparency mandates under REACH and EU AI Act shape European vendor selection.
- Clinical Trials:Patient stratification and recruitment prediction compress protocol timelines. Biotechnology firms view this as an emerging margin pool for amendment reduction.
Target Identification commands the largest share of platform investment. Clinical Trials is gaining share fastest.
End User:
Customer type determines pricing architecture, with enterprise pharmaceutical contracts carrying 3-5x the annual value of academic site licenses.
- Pharmaceutical Companies:Internal AI capabilities now bypass traditional contract research organizations for hit-to-lead programs. Procurement restructuring around milestone-linked platform partnerships eliminates fee-for-service arrangements.
- Biotechnology Firms:Unbundled discovery services separate target identification from medicinal chemistry retention. These sponsors drive fastest adoption of generative chemistry engines.
- Research Institutions:Federal research funding in the United States sustains computational biology infrastructure. Phenomic data integration projects concentrate in Boston and San Diego clusters.
- Contract Research Organizations:Margin compression in traditional chemistry services forces pivot toward AI-enabled platform resale. Integrated discovery margins erode as sponsors fragment procurement.
Pharmaceutical Companies anchor enterprise contract volume. Biotechnology Firms is where steepest expansion trajectory materializes.
Solution:
Delivery mode maturity separates cloud-native architectures from legacy on-premise installations requiring specialized integration.
- Software Platforms:End-to-end discovery workflows integrate target identification through lead optimization. Biopharmaceutical buyers prioritize vendors with pre-validated FDA and EMA compliance architectures.
- Cloud-Based Solutions:Scalable compute access reduces capital expenditure for mid-sized firms. AWS and Azure partnerships dominate deployment in the United States.
- Data Analytics Tools:Specialized modules for pathway analysis or toxicity prediction. Research institutions license these for hypothesis generation prior to experimental validation.
- Consulting Services:Algorithmic implementation and regulatory navigation support. European sponsors utilize these for REACH and EU AI Act dual-track explainability engineering.
Software Platforms dominate committed spend. Cloud-Based Solutions is where vendor investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based AI drug discovery platforms export computational services to biopharmaceutical sponsors across Germany, Japan, and the United Kingdom. Federal research funding and venture capital deployment in Boston and San Francisco sustain this trade corridor.
United States
National Institutes of Health funding and FDA model-informed drug development frameworks accelerate platform commercialization. The FDA's emerging guidance on algorithmic predictors demands documented performance across demographic subgroups. Boston and San Diego clusters concentrate phenomic data infrastructure and generative chemistry engine development.
Germany
EMA algorithmic transparency mandates under REACH and the EU AI Act reshape vendor selection criteria. German pharmaceutical conglomerates prioritize platforms with pre-validated dual-track explainability modules. The Rhine-Main and Munich biotech corridors attract AI-native discovery partnerships from mid-sized biotechnology firms.
United Kingdom
Biomedical literature mining and patent corpus analysis drive natural language processing procurement. The Medicines and Healthcare products Regulatory Agency's evolving posture on AI-enabled biomarkers influences validation investment. London and Cambridge clusters concentrate contract research organization pivots toward platform resale models.
Japan
PMDA's regulatory convergence with FDA frameworks creates first-mover advantages for validated algorithmic predictors. METI funding for computational biology infrastructure accelerates platform adoption among domestic pharmaceutical sponsors. The Kanto and Kansai regions concentrate autonomous laboratory system integration projects.
Switzerland
Swissmedic's evolving standards for AI-derived clinical biomarkers attract platform validation investments. Roche and Novartis procurement restructuring around milestone-linked partnerships eliminates traditional fee-for-service arrangements. Basel and Zurich clusters anchor European headquarters for generative chemistry engine vendors.
AI for Drug Discovery Market Vendor Landscape
Player mix skews toward venture-backed AI-native platforms with phenomic data infrastructure and generative chemistry capabilities. The competitive terrain fragments across three strategic tiers: integrated platform operators, specialized algorithm vendors, and autonomous laboratory system providers. Dominant competitive moves include strategic partnerships with biopharmaceutical sponsors and technology licensing agreements for regulatory-validated modules.
Within the integrated platform tier, Recursion Pharmaceuticals and Insilico Medicine exemplify archetypes built on high-throughput experimental loops and generative molecular design. Exscientia occupies a position representing autonomous laboratory integration, closing computational-to-physical validation loops. These three entities anchor the competitive landscape through distinct technological positioning rather than scale advantages.
| Leading Market Players |
|---|
| Recursion Pharmaceuticals |
| Insilico Medicine |
| Exscientia |
| Atomwise |
| BenevolentAI |
| Schrödinger |
| Isomorphic Labs |
| Insitro |
| Valo Health |
| Others |
Supply Flow & Price Mechanics
FDA model-informed drug development frameworks gate both platform vendor qualification and subscription tier differentiation, compressing price spreads between validated and non-validated algorithmic modules while elevating compliance documentation costs across all tiers.
Pricing Analysis
Next-generation transformer-based molecular generators command 40-60% subscription premiums over legacy machine learning implementations, while prior-generation statistical screening tools face accelerating price erosion. Three-tier pricing structure across enterprise, mid-market, and academic site licenses dominates procurement, with FDA validation tier and phenomic data integration depth as primary differentiation drivers. Pricing pressure stems from venture-backed AI-native platforms subsidizing early deployments to capture biopharmaceutical sponsor relationships. Mid-sized biotechnology firms exhibit highest price sensitivity, while pharmaceutical conglomerates prioritize compliance architecture over cost.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes from Shanghai and Busan elevate cloud compute hardware delivery timelines for on-premise platform installations. The United States, United Kingdom, and Switzerland concentrate generative chemistry engine development, while Taiwan and South Korea anchor GPU and specialized accelerator chip fabrication. Supply chains draw from NVIDIA and AMD datacenter hardware, proprietary molecular databases, and federated clinical data networks. Single-source vulnerability concentrates in cloud infrastructure providers, with AWS and Azure partnerships dominating downstream distribution through direct enterprise licensing and channel partner resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform subscription renewals and regulatory validation support services expand faster than initial software licensing, creating durable recurring-revenue attach opportunities for vendors with FDA and EMA pre-qualified modules.
For Market Incumbents: Consolidate phenomic data infrastructure advantages through exclusive biobank partnerships and autonomous laboratory network expansion. Deepen vertical integration into high-throughput experimental validation to defend against generative chemistry engine commoditization. Prioritize dual-track FDA-EMA compliance engineering to capture European market access before regulatory divergence hardens. For New Entrants and Emerging Players: Regulatory navigation consulting for mid-sized biotechnology firms represents the most penetrable service-layer gap, with incumbents under-investing in hands-on FDA submission support. Target Japanese market entry through PMDA convergence pathways, leveraging harmonized validation frameworks as lower-cost regulatory beachhead. Pursue partnership-first go-to-market models embedding platforms within existing CRO relationships rather than direct sponsor sales. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates spinning out internal AI discovery units as standalone platform vendors. Long-term viability hinges on autonomous laboratory integration depth and recurring revenue mix exceeding 60% of total bookings. Watch FDA algorithmic biomarker approval velocity as inflection signal for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Pathway | FDA model-informed drug development qualification accelerates biopharmaceutical sponsor procurement cycles. |
| Phenomic Data Infrastructure Expansion | High-throughput imaging and transcriptomics integration opens target categories beyond traditional genomics. |
| Autonomous Laboratory Network | Closing computational-to-physical validation loops differentiates platforms from pure-software competitors. |
| Dual-Track Compliance Engineering | Pre-validated FDA-EMA architectures reduce redundant validation investments for multi-jurisdictional sponsors. |
| Platform Subscription Pivot | Milestone-linked pricing models displace fee-for-service arrangements and capture downstream value. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, computational biology platform engineers, and biopharmaceutical procurement directors; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and venture capital deployment databases. Bottom-up platform revenue triangulation against top-down biopharmaceutical R&D spending allocation provided cross-checks on market sizing.
Across the analysis window, forecasts employed multi-dimensional segmentation across technology generation, application workflow depth, end-user scale tier, and regional regulatory cluster. CAGRs derived from platform adoption curve modeling and sponsor R&D budget reallocation patterns, with inputs from federal research funding trajectories and FDA guidance evolution timelines.
Underlying assumptions cover sustained FDA validation pathway institutionalization and stable venture capital deployment into computational biology, with deviation risk concentrated in regulatory divergence between FDA and EMA evidentiary thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market