
 Alcohol Dehydrogenase Enzymes Market | 2026-2036
Alcohol Dehydrogenase Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Dehydrogenase Enzymes Market Outlook
Biopharmaceutical companies are redrawing procurement patterns for alcohol dehydrogenase enzymes, displacing academic laboratories as the dominant volume buyers. Novozymes leverages its industrial fermentation infrastructure to supply bulk ADH grades for commercial biocatalysis. Sigma-Aldrich anchors the high-purity research segment with catalog-distributed isoenzyme variants. Codexis competes through proprietary protein engineering platforms that enhance cofactor recycling efficiency.
Alcohol dehydrogenase enzymes constitute a class of oxidoreductases that catalyze the reversible conversion of alcohols to aldehydes or ketones using NAD+ or NADP+ cofactors, typically operating at pH 8.0-9.0 and temperatures of 25-37°C for native forms. These enzymes serve industrial and commercial purposes spanning chiral intermediate synthesis, ethanol detection in clinical diagnostics, and in vitro metabolism studies for drug safety assessment. The ADH1 isoenzyme family dominates current revenue owing to its established role in stereoselective ketone reductions for active pharmaceutical ingredient manufacturing. Enzymatic assays represent the fastest-expanding technology segment as automated platforms displace manual spectrophotometric methods in high-volume toxicology screening.
FDA enzyme quality guidelines and REACH registration requirements in Europe are elevating documentation burdens for suppliers seeking dual-market access. ISO 13485 certification shapes competitive positioning in the diagnostics application segment, where healthcare providers demand traceable manufacturing records. EMA's evolving stance on biocatalytic processes in drug master files is forcing enzyme vendors to expand regulatory affairs capabilities. Stakeholders must monitor how FDA's emerging framework for enzyme-based manufacturing controls interacts with EMA's quality guidance to anticipate compliance-driven sourcing consolidation.
Market Dynamics
Pharmaceutical biocatalysis is displacing traditional chemical synthesis routes, concentrating enzyme procurement decisions within contract manufacturing organizations that coordinate multi-site fermentation networks across biotechnology clusters.
Growth Catalysts
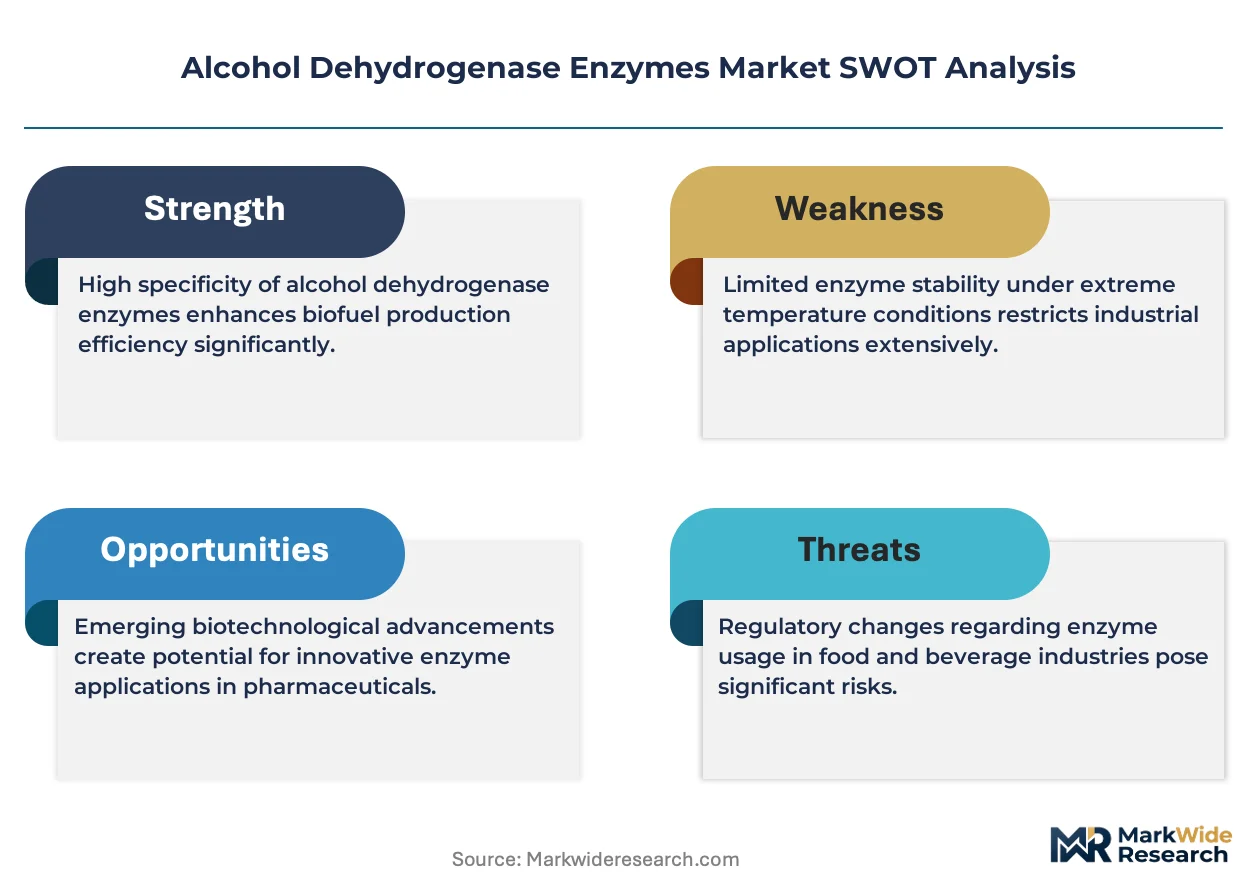
- EMA biocatalytic process guidance:Regulatory acceptance of enzyme-based manufacturing in drug master files accelerates vendor qualification for European pharmaceutical supply chains.
- Chiral intermediate synthesis:Stereoselective ketone reductions for active pharmaceutical ingredient manufacturing pull high-purity ADH grades into commercial-scale production.
- Germany's Rhine-Main biotechnology cluster:Contract research organizations coordinate distributed fermentation capacity, creating concentrated demand for bulk enzyme supply.
Market Restraints
- NAD+ cofactor cost volatility:Nicotinamide adenine dinucleotide supply fluctuations compress margins for continuous biocatalytic processes requiring cofactor recycling.
- Single-source fermentation capacity:Industrial-scale enzyme production concentrates among established microbial fermentation operators, limiting supply elasticity during demand spikes.
- Protein stability limitations:Native ADH variants require controlled temperature and pH ranges, restricting deployment in non-ideal industrial environments.
Strategic Opportunities
- Continuous flow biocatalysis:Immobilized enzyme reactor systems enable 24-hour operational cycles that batch processes cannot match, opening pharmaceutical manufacturing contracts.
- FDA enzyme quality guidelines:Emerging documentation frameworks create first-mover advantages for suppliers building regulatory affairs capabilities ahead of formal implementation.
- Diagnostics platform integration:Automated enzymatic assay systems for ethanol detection expand into workplace safety and forensic toxicology applications.
Industry Challenges
- Regulatory affairs talent scarcity:Dual-market access requires specialists fluent in both FDA enzyme guidelines and REACH registration protocols, creating recruitment bottlenecks.
- ISO 13485 certification timelines:Diagnostics-grade manufacturing demands 12-18 month quality system implementation periods that delay market entry.
- Protein engineering IP complexity:Cofactor recycling efficiency improvements sit within dense patent thickets, complicating freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Dehydrogenase Enzymes Market |
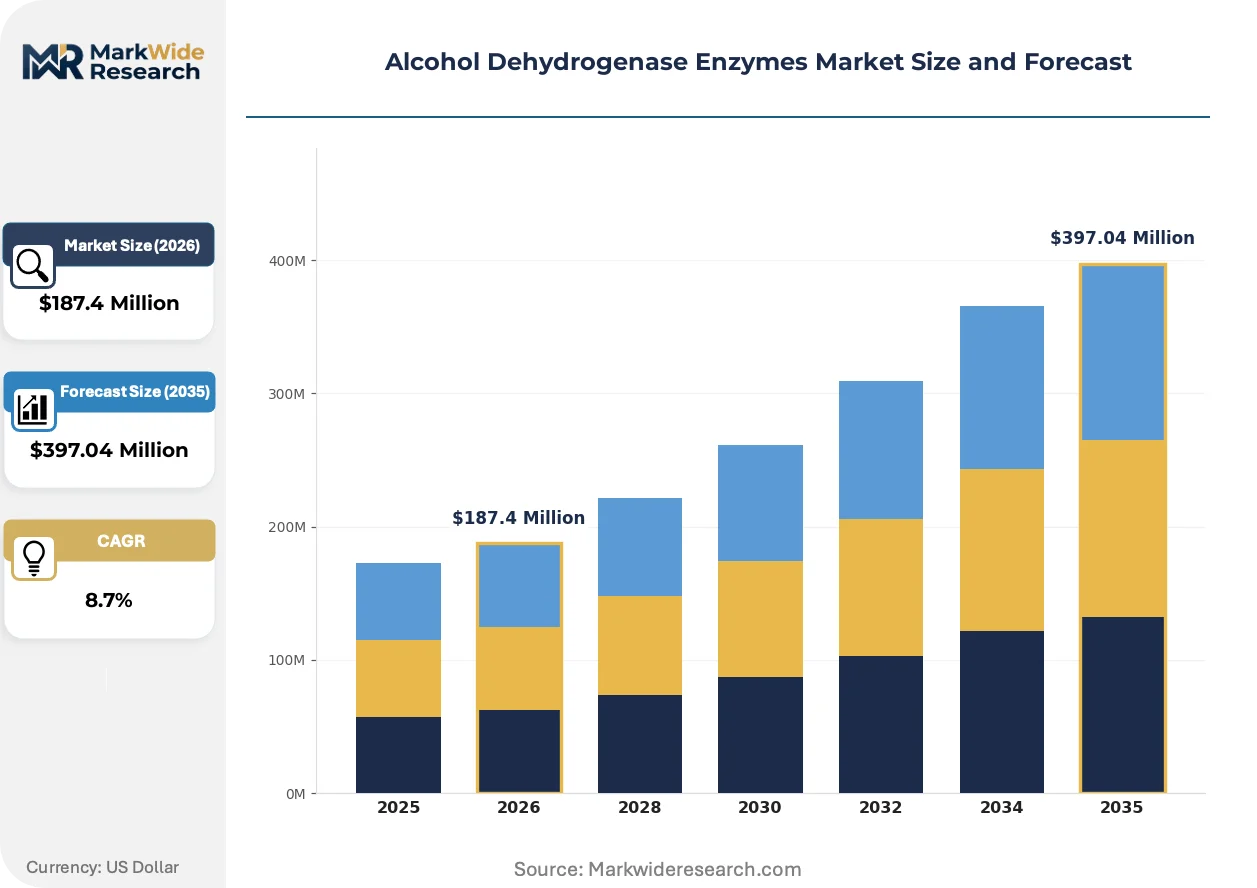
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ADH1, ADH2, ADH3, ADH4 Application: Biotechnology, Pharmaceuticals, Diagnostics, Research End User: Academic Institutions, Biopharmaceutical Companies, Contract Research Organizations, Healthcare Providers Technology: Enzymatic Assays, Genetic Engineering, Protein Engineering, High-Throughput Screening |
| Companies Covered | Worthington Biochemical, Codexis, Sigma-Aldrich, Sekisui Diagnostics, Amano Enzyme, Thermo Fisher Scientific, Novozymes, Merck KGaA, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Dehydrogenase Enzymes Market Strategic Shifts
Engineered enzyme variants and automated assay platforms are compressing traditional procurement cycles, while regulatory documentation requirements reshape supplier competitive positioning across pharmaceutical and diagnostics segments.
Directed evolution platforms are decomposing the performance gap between native and engineered ADH variants. Pharmaceutical manufacturers adopt Codexis-derived enzymes for commercial biocatalysis at accelerating pace. This protein engineering advance is decomposing cost barriers to continuous manufacturing adoption.
REACH registration requirements in Europe elevate purity documentation burdens for industrial enzyme suppliers. Dual-market access now demands comprehensive substance characterization data that batch-level testing cannot satisfy. German and Swiss suppliers are responding by building in-house analytical chemistry capabilities.
Contract research organizations now specify performance-guaranteed enzyme supply agreements rather than catalog purchases. This specification shift displaces spot-market buying in high-volume pharmaceutical applications. The Rhine-Main biotechnology cluster exhibits this behavioral change most prominently.
Alcohol Dehydrogenase Enzymes Market Segmentation
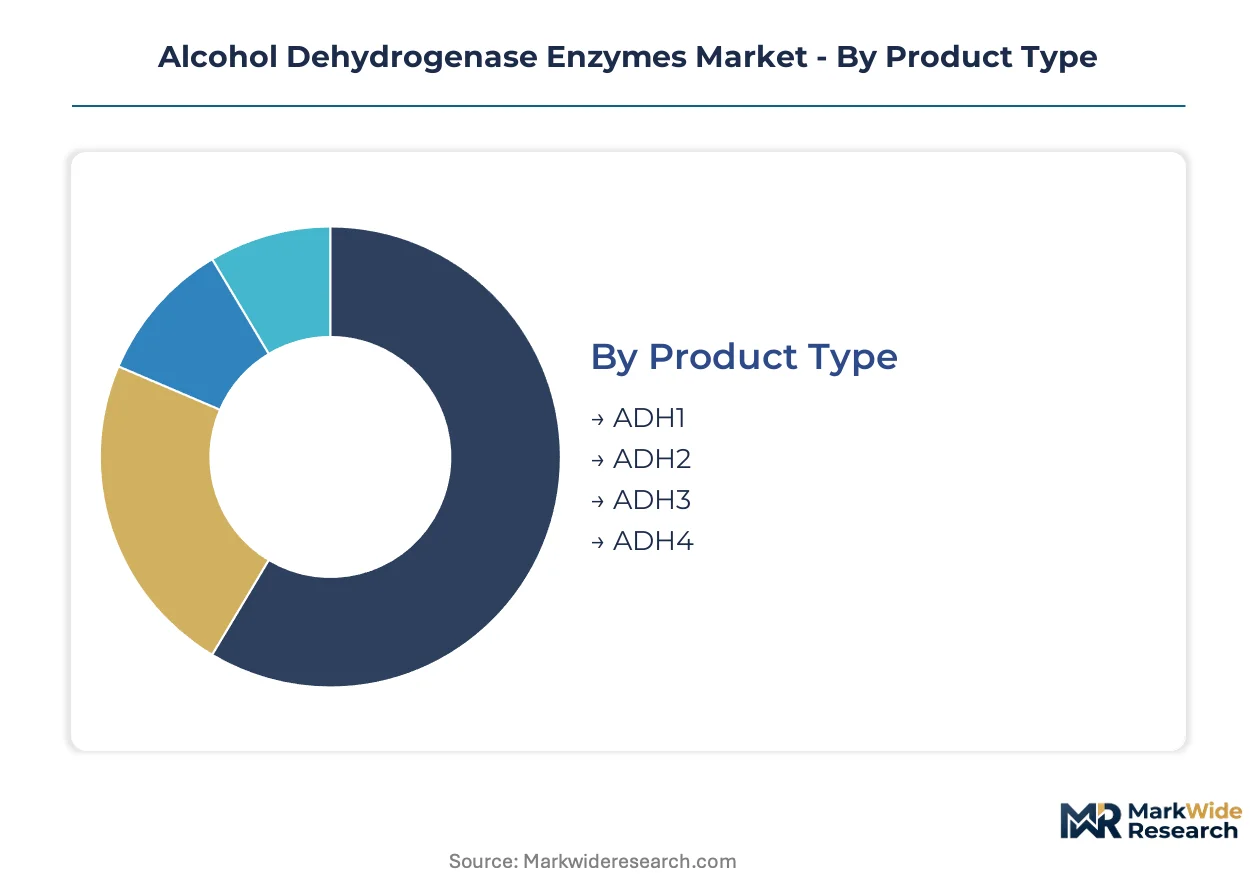
Segmentation in the alcohol dehydrogenase enzymes market exposes where substitution pressures from chemical catalysts and alternative biocatalysts concentrate most intensely. Procurement patterns diverge sharply across product variants and application contexts, with pharmaceutical-grade specifications commanding premium positioning against research-grade alternatives.
Product Type:
Substitution pressure from chemical reduction catalysts hits ADH4 and less-characterized isoenzymes hardest, while ADH1 maintains entrenched specification in commercial drug manufacturing.
- ADH1:The founding member of the human alcohol dehydrogenase family, ADH1 exhibits broad substrate specificity for ethanol and longer-chain alcohols with zinc-dependent catalytic sites. Pharmaceutical manufacturers in Germany's Rhine-Main cluster specify ADH1 for stereoselective ketone reductions in active pharmaceutical ingredient synthesis, where regulatory familiarity in FDA drug master files resists catalyst substitution.
- ADH2:Pi-class isoenzyme with distinct kinetic properties favoring medium-chain alcohol substrates and altered cofactor affinity. Research institutions in Switzerland and the Netherlands deploy ADH2 variants for mechanistic enzymology studies, though commercial scale-up remains constrained by lower expression yields in standard microbial hosts.
- ADH3:Chi-class enzyme with specialized roles in formaldehyde detoxification pathways and glutathione-dependent catalysis.
- ADH4:Sigma-class isoenzyme exhibiting narrow substrate range and limited commercial characterization data.
ADH1 anchors the volume base while protein engineering investments push ADH2 toward the steepest expansion trajectory among characterized isoenzymes.
Application:
Cost tier stratification separates diagnostics-grade manufacturing with ISO 13485 requirements from research-grade procurement with minimal documentation burdens.
- Biotechnology:Industrial enzyme deployment spans chiral intermediate synthesis, biofuel processing, and fine chemical manufacturing. Contract manufacturing organizations in Basel and Boston coordinate multi-site fermentation networks for bulk ADH supply, where continuous flow reactor integration is compressing batch process economics.
- Pharmaceuticals:Biocatalytic drug synthesis routes displace traditional chemical reductions in late-stage active pharmaceutical ingredient manufacturing. EMA's evolving guidance on enzyme-based processes in European drug master files is accelerating vendor qualification timelines for commercial supply.
- Diagnostics:Ethanol detection assays for clinical toxicology and workplace safety screening.
- Research:Academic procurement of catalog-distributed isoenzyme variants for in vitro metabolism studies.
Pharmaceuticals commands the steepest margin tier while diagnostics applications expand most quickly through automated platform integration.
End User:
Customer type determines whether procurement flows through spot-market catalog purchases or performance-guaranteed supply agreements with fermentation capacity commitments.
- Academic Institutions:Research laboratories purchase small-volume enzyme aliquots through distributor catalogs for mechanistic and kinetic studies. Budget constraints and publication-driven demand cycles create price sensitivity that favors standard-grade over custom-manufactured variants.
- Biopharmaceutical Companies:Integrated drug developers specify high-purity ADH grades with comprehensive regulatory documentation for internal biocatalysis programs. These organizations are displacing academic laboratories as dominant volume buyers through captive process development groups.
- Contract Research Organizations:Multi-site service providers coordinate distributed fermentation capacity across biotechnology clusters.
- Healthcare Providers:Hospital laboratories and reference diagnostics operators integrate ADH-based ethanol assays into automated toxicology platforms.
Biopharmaceutical companies anchor the volume base while contract research organizations gain share at the steepest rate through outsourced biocatalysis service expansion.
Technology:
Supply concentration in microbial fermentation operators and protein engineering platforms creates divergent capability requirements across technology segments.
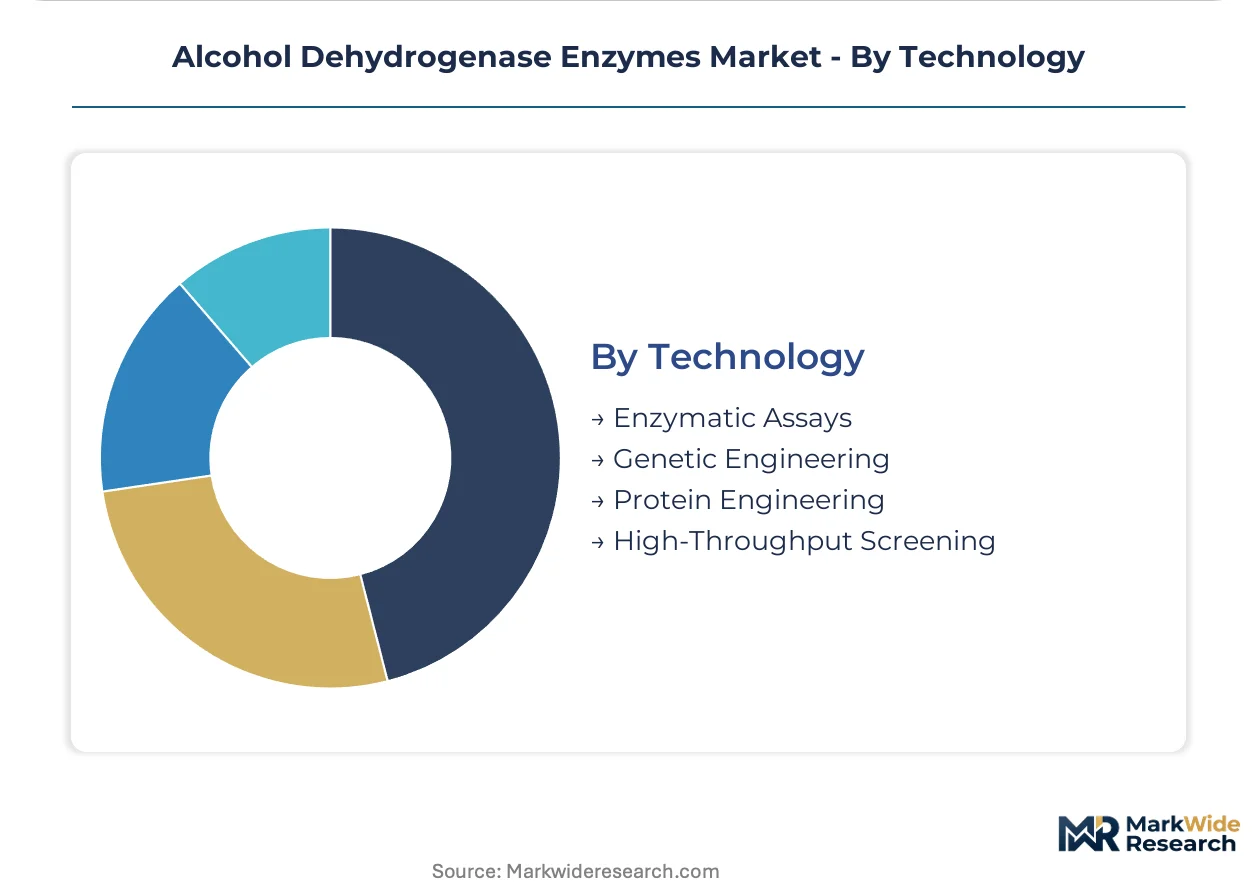
- Enzymatic Assays:Spectrophotometric and electrochemical detection systems for NADH formation kinetics in ethanol quantification. Automated platform manufacturers in California and Massachusetts are displacing manual methods in high-volume toxicology laboratories, where throughput requirements favor 96-well and 384-well microplate formats.
- Genetic Engineering:Recombinant DNA approaches for heterologous ADH expression in Escherichia coli and yeast systems. Codon optimization and promoter engineering in Danish and German biotechnology facilities are improving soluble protein yields for commercial manufacturing.
- Protein Engineering:Directed evolution and rational design for thermostability and cofactor recycling efficiency.
- High-Throughput Screening:Parallel biocatalytic reaction evaluation for substrate scope and stereoselectivity profiling.
Enzymatic assays anchors the installed base while protein engineering gains share at the steepest rate through engineered variant commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites Europe's dominance in industrial enzyme distribution, connecting Rhine-Main fermentation clusters to Atlantic shipping lanes.
Germany
EMA biocatalytic process guidance accelerates vendor qualification for commercial ADH supply. REACH registration protocols enforce comprehensive substance characterization for dual-market enzyme suppliers. The Rhine-Main biotechnology cluster concentrates contract research organizations coordinating multi-site fermentation networks.
United States
FDA enzyme quality guidelines tighten purity benchmarks for pharmaceutical-grade manufacturing. Biopharmaceutical companies displace academic laboratories as dominant volume buyers through captive process development groups. Greater Boston anchors automated enzymatic assay platform manufacturing for toxicology diagnostics.
Switzerland
Swissmedic's evolving stance on biocatalytic processes in drug master files shapes vendor regulatory affairs capabilities. Basel-based contract manufacturing organizations coordinate distributed fermentation capacity across biotechnology clusters. The country's pharmaceutical manufacturing heritage concentrates high-purity ADH procurement decisions.
Japan
METI industrial biotechnology programs support protein engineering infrastructure for engineered enzyme variant development. PMDA quality guidance intersects with EMA frameworks for dual-market access documentation. The Kansai region hosts fermentation operators supplying bulk ADH grades for Asian pharmaceutical manufacturing.
India
CDSCO's emerging enzyme quality frameworks create compliance preparation windows for export-oriented suppliers. PLI scheme incentives attract contract research organization investment in multi-site fermentation capacity. Maharashtra's biotechnology corridor concentrates enzymatic assay manufacturing for domestic diagnostics expansion.
Alcohol Dehydrogenase Enzymes Market Competitive Environment
Concentration sits with industrial fermentation specialists and protein engineering platforms. The vendor base spans three tiers: bulk-grade suppliers leveraging microbial fermentation infrastructure, high-purity catalog distributors serving research segments, and engineered variant developers enhancing cofactor recycling efficiency. Strategic moves center on regulatory affairs capability building for dual-market access and continuous flow reactor partnerships for pharmaceutical manufacturing contracts.
Among industrial biotechnology specialists, Novozymes anchors bulk ADH supply through fermentation infrastructure scale. Sigma-Aldrich exemplifies the high-purity research-grade tier with catalog-distributed isoenzyme variants. Codexis occupies a position within the engineered enzyme segment, representing protein engineering platforms that decompose cost barriers to continuous manufacturing adoption.
| Leading Market Players |
|---|
| Worthington Biochemical |
| Codexis |
| Sigma-Aldrich |
| Sekisui Diagnostics |
| Amano Enzyme |
| Thermo Fisher Scientific |
| Novozymes |
| Merck KGaA |
| Roche Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Ninety-day fermentation batch cycles and 45-60 day analytical certification timelines tether working capital requirements to pricing power across ADH supplier tiers. This lead-time compression concentrates procurement leverage with contract manufacturing organizations in Germany's Rhine-Main biotechnology cluster, while REACH documentation burdens elevate purity premiums for dual-market access.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade ADH1 isoenzymes with FDA drug master file documentation from research-grade catalog variants and bulk industrial fermentation outputs. Price differentiation hinges on ISO 13485 certification status and cofactor recycling efficiency guarantees, with diagnostics manufacturers absorbing the steepest premiums. Cost compression in research-grade tiers is intensifying because academic budget constraints favor standard-grade over custom-engineered variants. Contract research organizations exhibit the lowest price sensitivity due to performance-guaranteed supply agreements, while academic laboratories negotiate spot-market catalog purchases.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade procurement, with biopharmaceutical companies maintaining 60-90 day ADH inventories to buffer against single-source fermentation capacity constraints. Supply concentrates in Denmark, Germany, and Switzerland, where microbial fermentation infrastructure draws from yeast extract, nicotinamide adenine dinucleotide cofactors, and zinc-dependent catalytic site precursors. Single-source vulnerability in industrial-scale enzyme production creates exposure during demand spikes. Distribution runs through contract research organization networks coordinating multi-site fermentation projects across biotechnology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery anchored to EMA biocatalytic process guidance accelerating vendor qualification timelines for commercial pharmaceutical supply chains.
For Market Incumbents: Fortify regulatory affairs capabilities ahead of FDA enzyme quality guideline formalization, building dual-market documentation expertise that emerging entrants cannot replicate. Deepen backward integration into nicotinamide adenine dinucleotide cofactor supply to buffer margin pressure from raw material cost volatility. Capture continuous flow reactor partnerships with Rhine-Main contract manufacturing organizations to lock in performance-guaranteed supply agreements. For New Entrants and Emerging Players: Regulatory documentation services for mid-tier biopharmaceutical companies represent the most penetrable white-space target, as established suppliers prioritize top-tier pharmaceutical accounts. Automated enzymatic assay platform integration for workplace safety diagnostics offers lower certification barriers than pharmaceutical-grade manufacturing. Pursue go-to-market angles through ISO 13485 certification partnerships with existing diagnostics manufacturers rather than greenfield fermentation capacity buildout. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capability consolidation play because REACH and FDA documentation requirements are concentrating procurement decisions among suppliers with proven dual-market track records. Target acquisition profiles center on engineered enzyme variant developers with proprietary protein engineering platforms enhancing cofactor recycling efficiency. Watch EMA drug master file acceptance rates for biocatalytic processes as the inflection indicator signaling accelerated commercial adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Buildout | Dual-market access documentation expertise accelerates vendor qualification for EMA and FDA pharmaceutical supply chains. |
| Continuous Flow Reactor Partnership | Immobilized enzyme systems enable 24-hour operational cycles that batch processes cannot match for pharmaceutical manufacturing contracts. |
| Protein Engineering Platform Investment | Directed evolution capabilities decompose cost barriers to continuous manufacturing adoption through enhanced cofactor recycling efficiency. |
| ISO 13485 Certification Pathway | Diagnostics-grade manufacturing quality systems unlock automated enzymatic assay platform integration for toxicology screening expansion. |
| Backward Integration into Cofactor Supply | In-house nicotinamide adenine dinucleotide production buffers margin compression from supply fluctuations in continuous biocatalytic processes. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with biopharmaceutical process development executives, regulatory affairs specialists at enzyme suppliers, contract research organization procurement leads, and diagnostics platform manufacturers; and secondary validation through FDA enzyme quality guideline drafts, EMA biocatalytic process guidance documents, REACH registration protocols, and SEC filings from publicly traded industrial biotechnology firms. Bottom-up triangulation across fermentation capacity estimates and top-down validation against pharmaceutical biocatalysis adoption rates anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning ADH isoenzyme variants, application tiers from research-grade to pharmaceutical-grade, end-user archetypes from academic laboratories to contract manufacturing organizations, and technology segments from native enzymes to engineered variants. CAGRs were derived from trend extrapolation of biocatalytic process adoption in active pharmaceutical ingredient manufacturing, cross-referenced with regulatory timeline assumptions for EMA and FDA documentation requirements. Industry-specific forecast inputs included protein engineering platform commercialization rates and automated enzymatic assay platform displacement of manual spectrophotometric methods.
Underlying assumptions cover EMA biocatalytic process guidance finalization timelines and FDA enzyme quality guideline implementation trajectories, with deviation risk concentrated in regulatory affairs talent scarcity delaying vendor qualification programs. Forecasts reflect these documented conditions. Revision becomes warranted when REACH registration requirement stringency crosses thresholds that eliminate marginal suppliers from dual-market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Antibody Fragments Market