
 Global Microbial Protein Market | 2026-2036
Global Microbial Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbial Protein Market Foresight
Modular ingredient bundling is recalibrating how feed manufacturers evaluate microbial protein suppliers. Cargill, Incorporated leverages its global grain trading infrastructure to secure offtake agreements with fermentation startups. DSM-Firmenich anchors European supply through its nutrition bioscience division, while Calysta specializes in methane-to-protein platforms using natural gas feedstock.
Microbial protein denotes biomass cultivated from bacteria, yeast, fungi, or algae through controlled fermentation, typically containing 50-80% crude protein on a dry weight basis with amino acid profiles comparable to fishmeal or soybean meal. Its primary purpose is to replace conventional protein sources in animal nutrition, human foods, and industrial bioprocesses. Single cell protein dominates current commercial volumes due to established supply chains for feed applications, while mycoprotein captures premium positioning in human nutrition where texture and fiber content command higher margins. Fermentation technology leads production scale-up, though bioreactor-based systems are displacing batch culture in new facilities seeking continuous output.
The FDA regulates microbial protein intended for human consumption under GRAS notification pathways, while the EPA oversees fermentation effluent discharge under the Clean Water Act. EFSA novel food authorizations in Europe create a two-year market access timeline that shapes investment pacing for entrants. REACH compliance for process chemicals adds cost layers that favor larger producers with dedicated regulatory teams. Stakeholders must monitor how carbon border adjustment mechanisms restructure the cost competitiveness of regional fermentation hubs against imported conventional proteins.
Market Dynamics
Fermentation capacity concentration in the Netherlands, Denmark, and Singapore is restructuring supplier-buyer power dynamics as animal feed manufacturers negotiate multi-year offtake contracts ahead of bioreactor commissioning timelines.
Growth Catalysts
- EU Green Deal:The EU Green Deal mandates 55% emissions reduction by 2030, compelling livestock producers to source low-carbon protein alternatives and accelerating fermentation facility investments across member states.
- Precision fermentation scale-up:Continuous bioreactor systems are replacing batch culture in new facilities, cutting unit production costs and enabling supply contracts with industrial aquafeed operations.
- Singapore biotech clusters:Singapore's 30 by 30 food security initiative funds microbial protein infrastructure, attracting venture deployment and creating regional export hubs for Southeast Asian markets.
Market Restraints
- Natural gas feedstock volatility:Methane-to-protein platforms face input cost exposure as European natural gas prices fluctuate, compressing margins for gas-dependent fermentation operators.
- EFSA novel food timelines:European Food Safety Authority authorizations require 18-24 month review cycles, delaying human-grade product launches and freezing capital deployment until clearance certainty emerges.
- Soybean meal substitution economics:Conventional soy protein maintains price advantages in bulk feed applications, limiting microbial protein penetration to premium-certified livestock segments.
Strategic Opportunities
- India aquaculture expansion:India's shrimp and fish farming sector seeks certified sustainable feed inputs, creating first-mover advantage for fermentation suppliers establishing local production partnerships.
- Carbon border adjustment mechanisms:The EU's CBAM penalizes imported high-carbon proteins, tilting cost competitiveness toward domestic and near-shore fermentation capacity.
- Human nutrition texture innovation:Mycoprotein fiber structures command premium positioning in meat analog applications, opening margin expansion beyond commodity feed markets.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial fermentation facilities compete for limited pools of metabolic engineering and bioreactor scale-up specialists, inflating compensation costs.
- REACH chemical compliance:Process chemical registration under EU REACH adds fixed cost layers that disproportionately burden mid-scale producers without dedicated regulatory teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbial Protein Market |
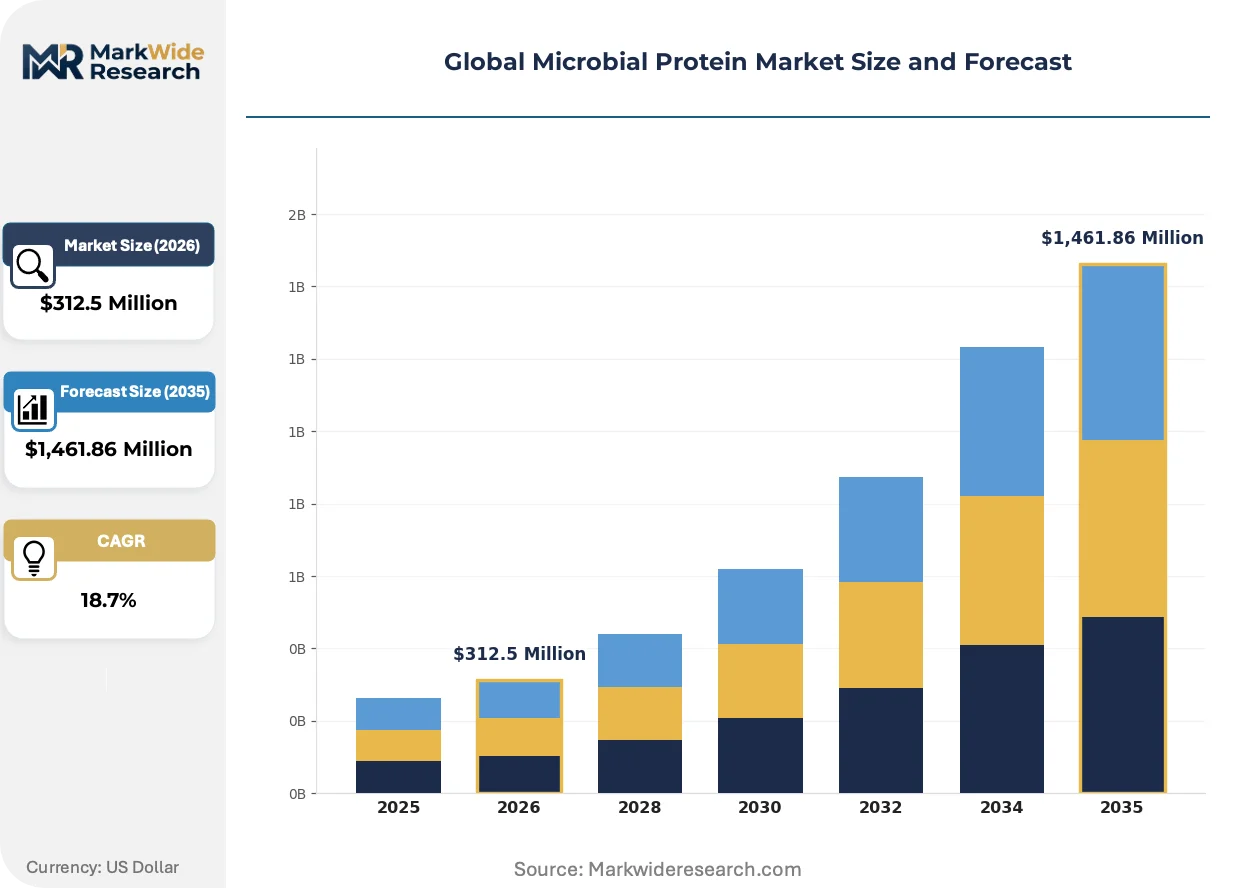
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cell Protein, Mycoprotein, Algal Protein, Bacterial Protein, Fungal Protein, Yeast Protein Application: Animal Feed, Aquaculture Feed, Fertilizers, Bioplastics, Human Nutrition, Dietary Supplements Production Technology: Fermentation, Submerged Culture, Solid State Fermentation, Bioreactor-Based, Continuous Culture, Batch Culture End User Industry: Feed Manufacturers, Agriculture, Pharmaceuticals, Food & Beverages, Biotechnology Firms, Nutraceutical Companies |
| Companies Covered | Cargill, Incorporated, DSM-Firmenich, Corbion N.V., Kerry Group plc, Sensient Technologies Corporation, Unibio, Calysta, Novozymes, MycoTechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbial Protein Market Shifts & Advancements
Continuous fermentation systems are displacing batch operations as the dominant production architecture, while regulatory carbon accounting and procurement certification requirements reshape competitive positioning across supply tiers.
Continuous bioreactor technology is rewriting protein manufacturing economics by enabling steady-state output with reduced downtime and lower labor intensity per kilogram of biomass. Industrial aquafeed manufacturers in Northern Europe are adopting this architecture fastest, locking in supply agreements before competitors complete facility retrofits. The shift compresses viable scale thresholds, favoring capital-rich entrants who can commission integrated continuous lines from project inception.
The EU F-Gas Regulation is tightening emissions standards for cooling systems in fermentation facilities, forcing equipment retrofits or replacement of synthetic refrigerants with natural alternatives. This mandate elevates facility engineering costs by 8-12% for new builds but creates compliance differentiation for early adopters. Dutch and Danish producers are responding fastest, securing preferred supplier status with carbon-conscious livestock integrators.
Feed manufacturers are consolidating supplier relationships around bundled ingredient contracts that combine microbial protein with amino acid premixes and feed additives. This procurement model concentrates purchasing power with integrated nutrition companies while marginalizing standalone fermentation startups lacking formulation capabilities. The Netherlands exhibits this pattern most acutely, where DSM-Firmenich and Cargill leverage existing distribution networks to capture microbial protein volumes.
Global Microbial Protein Market Segmentation
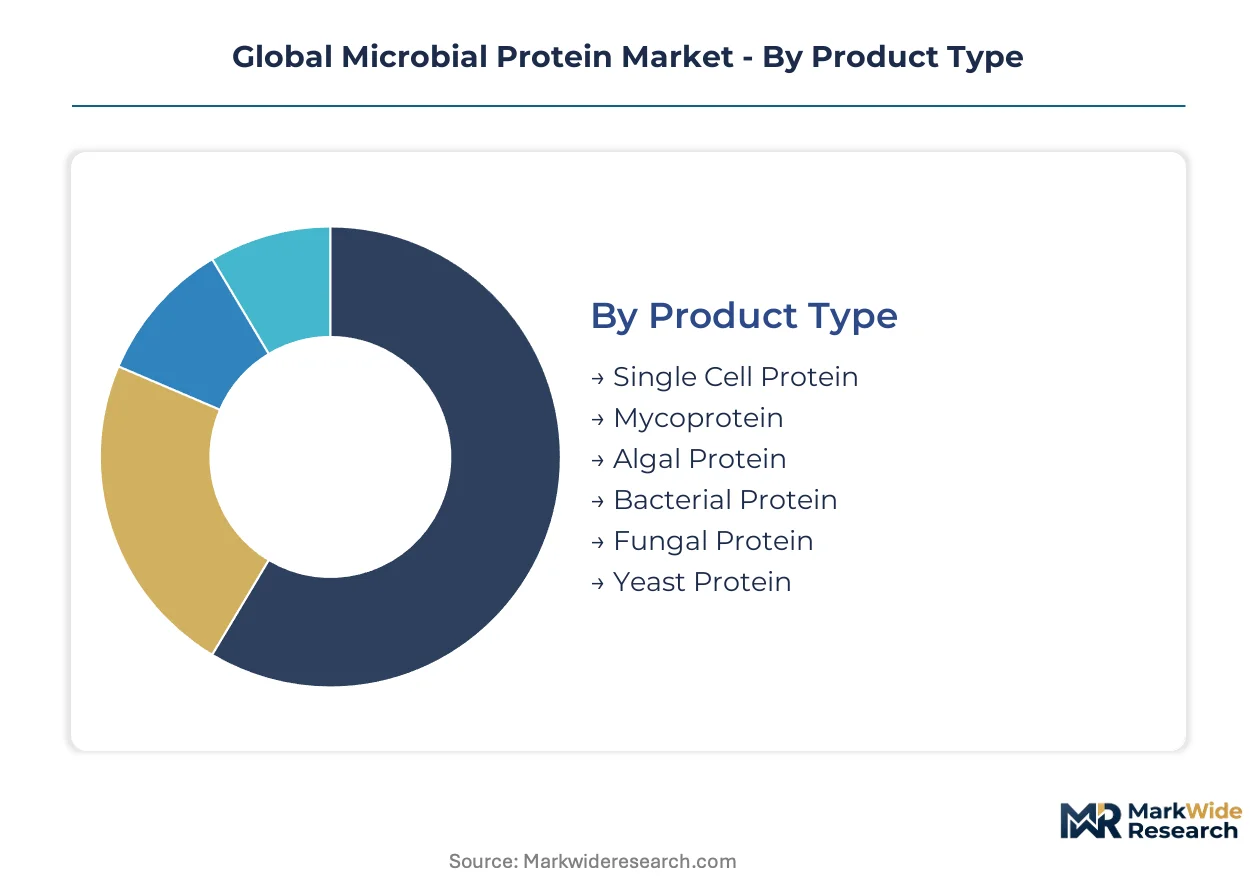
Microbial protein suppliers configure production assets around distinct technical specifications and customer requirements. Each segmentation dimension reveals different margin structures, regulatory pathways, and capacity investment patterns that determine competitive positioning.
Product Type:
Standardization dominates commodity-grade biomass while customization unlocks premium pricing in specialized nutrition applications.
- Single Cell Protein:Biomass derived from bacteria or yeast fermentation containing 50-80% crude protein with amino acid profiles matching fishmeal specifications. Feed manufacturers in the Netherlands and Denmark concentrate procurement here, driven by EU Green Deal emissions reduction mandates for livestock operations.
- Mycoprotein:Filamentous fungal biomass valued for meat-like texture and fiber content in human nutrition applications. Human food manufacturers prioritize mycoprotein where EFSA novel food authorizations create two-year regulatory timelines that shape investment pacing.
- Algal Protein:Photosynthetic microalgae cultivation yielding protein with omega-3 fatty acid co-products.
- Bacterial Protein:Methane-oxidizing bacteria platforms converting natural gas feedstock directly into edible biomass.
- Fungal Protein:Non-filamentous fungi optimized for rapid biomass accumulation in submerged culture systems.
- Yeast Protein:Saccharomyces and non-conventional yeast strains with established GRAS status for food applications.
Most installed capacity flows through Single Cell Protein. Expansion is steepest in Mycoprotein.
Application:
Volume scale separates commodity feed markets from premium-certified segments where sustainability credentials command price premiums.
- Animal Feed:Poultry and swine rations incorporating microbial protein as soy meal replacement at inclusion rates of 5-15%. Cargill procurement teams negotiate multi-year offtake agreements ahead of bioreactor commissioning in Singapore and Denmark.
- Aquaculture Feed:Salmon and shrimp diets requiring consistent amino acid profiles and low contaminant levels. Indian shrimp farming operations seek certified sustainable inputs, creating first-mover positioning for fermentation suppliers establishing local partnerships.
- Fertilizers:Microbial biomass as nitrogen-rich soil amendments in organic agriculture systems.
- Bioplastics:Protein-based feedstock for biodegradable polymer production in industrial biotechnology.
- Human Nutrition:Direct consumption formats including meat analogs and protein-enriched foods.
- Dietary Supplements:Powder and capsule formulations targeting sports nutrition and wellness segments.
Aquaculture Feed absorbs the greatest share of new commissioning capacity. Human Nutrition generates the highest margin per kilogram.
Production Technology:
Continuous processing architectures displace batch systems as capital efficiency becomes the decisive scale-up variable.
- Fermentation:Broad category encompassing all controlled microbial cultivation systems with standardized vessel configurations. Dutch and Danish facilities lead retrofit investments to meet EU F-Gas Regulation cooling system standards.
- Continuous Culture:Steady-state bioreactor operation eliminating downtime between batches and reducing labor intensity. Northern European aquafeed manufacturers adopt this architecture fastest, locking supply agreements before competitors complete facility upgrades.
- Submerged Culture:Liquid-phase cultivation of fungi and bacteria in aerated vessels.
- Solid State Fermentation:Moist solid substrate cultivation for specialized fungal protein applications.
- Bioreactor-Based:Engineered vessel systems with precise environmental control for high-value products.
- Batch Culture:Traditional sequential operation with distinct growth phases and harvest cycles.
Most installed capacity flows through Fermentation. Continuous Culture is gaining share fastest.
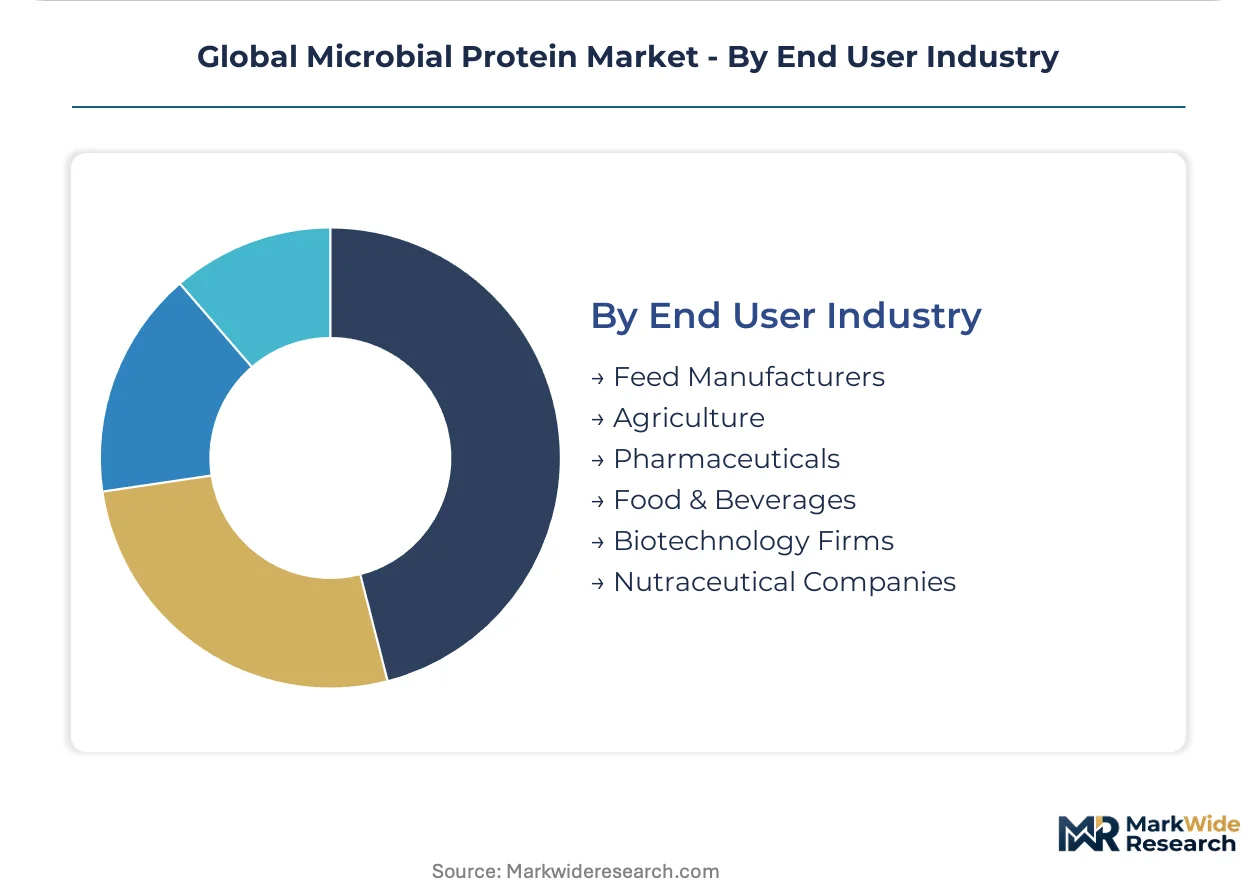
End User Industry:
Procurement sophistication varies sharply between formulation-integrated buyers and standalone processors.
- Feed Manufacturers:Compound feed producers bundling microbial protein with amino acid premixes and additives. DSM-Firmenich leverages European distribution networks to capture volumes through integrated nutrition contracts in the Netherlands.
- Food & Beverages:CPG companies developing meat analog and protein-fortified product lines. Singapore's 30 by 30 food security initiative funds infrastructure attracting venture deployment for regional export hub development.
- Agriculture:Direct farm procurement for specialty livestock and organic operations.
- Pharmaceuticals:Cell culture media and therapeutic protein production applications.
- Biotechnology Firms:Industrial enzyme and biochemical production using microbial biomass.
- Nutraceutical Companies:Branded supplement formulators seeking differentiated protein sources.
Feed Manufacturers command the largest volume commitments. Food & Beverages is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision fermentation originated in Northern European food biotechnology labs during the 1960s, with Denmark and the Netherlands establishing the first industrial-scale facilities for single cell protein production. These heritage clusters now anchor global capacity expansion as commercial deployment accelerates.
Netherlands
DSM-Firmenich operates integrated nutrition bioscience facilities near Delft, supplying compound feed manufacturers with bundled amino acid premixes. The EU F-Gas Regulation mandates synthetic refrigerant phase-out in cooling systems, forcing bioreactor retrofits across Randstad fermentation hubs. Wageningen University anchors research partnerships that transfer continuous culture technology to commercial operators.
Denmark
Novozymes maintains industrial enzyme production infrastructure that supports microbial protein scale-up for aquafeed applications. The national government channels green transition funds into bioreactor capacity expansion near Copenhagen. Kalundborg's industrial symbiosis park hosts fermentation facilities sharing utilities and waste streams between operators.
Singapore
The 30 by 30 food security initiative directs public investment toward precision fermentation infrastructure for regional protein supply. Enterprise Singapore coordinates venture deployment into biotech clusters near Tuas Biomedical Park. Local operators secure export positioning for Southeast Asian aquaculture feed markets.
United States
Calysta deploys methane-to-protein platforms using natural gas feedstock in California and Texas facilities. FDA GRAS notification pathways govern human-grade product authorization timelines. Greater Boston biotech corridors attract metabolic engineering talent for continuous fermentation system development.
India
Shrimp farming operations in Andhra Pradesh and Gujarat seek certified sustainable feed inputs from fermentation suppliers. FSSAI novel food regulations create compliance frameworks for human nutrition applications. Maharashtra-based feed manufacturers evaluate microbial protein inclusion rates for poultry and swine rations.
Global Microbial Protein Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and application certification tiers. The supplier base organizes around integrated nutrition conglomerates, specialized fermentation technology firms, and regional feed ingredient distributors. Three archetypes dominate: grain-trading houses leveraging procurement infrastructure, bioscience divisions with formulation capabilities, and pure-play methane-to-protein operators. Competitive moves concentrate on multi-year offtake contracting ahead of bioreactor commissioning and modular ingredient bundling that combines protein biomass with amino acid premixes.
Among integrated nutrition conglomerates, Cargill, Incorporated and DSM-Firmenich represent the procurement-integration archetype, anchoring supplier-buyer relationships through existing distribution networks. Within specialized fermentation technology, Calysta occupies a position exemplifying feedstock-specific platform development. These three entities illustrate how competitive positioning stratifies between commodity feed volume and premium-certified human nutrition segments.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DSM-Firmenich |
| Corbion N.V. |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Unibio |
| Calysta |
| Novozymes |
| MycoTechnology |
| Others |
Supply & Pricing Matrix
Natural gas feedstock costs propagate through methane-to-protein platforms into contract pricing tiers, compressing margins for Calysta-style operators while continuous fermentation adopters in the Netherlands and Denmark capture premium positioning through carbon-certified output.
Pricing Analysis
Long-term offtake contracting dominates commercial relationships, with pricing stratifies across premium-certified, standard-grade, and economy-bulk tiers. EFSA novel food authorizations and EU Green Deal compliance credentials command 15-25% premiums over commodity feed-grade biomass. Pricing pressure stems from soybean meal substitution economics in bulk poultry and swine applications. Aquafeed manufacturers in Northern Europe exhibit lowest price sensitivity due to sustainability procurement mandates, while Asian compound feed producers drive hardest volume negotiations.
Supply Chain Analysis
Methane feedstock supply rests on Dutch, Danish, and Norwegian natural gas infrastructure, with hydrogen and CO2 inputs sourced from industrial symbiosis parks at Kalundborg and Rotterdam. Bioreactor vessel fabrication draws from German and Swiss precision engineering suppliers. Single-source vulnerability concentrates in cooling system refrigerants facing EU F-Gas Regulation phase-out deadlines. Distribution runs through DSM-Firmenich and Cargill integrated nutrition networks bundling microbial protein with amino acid premixes and feed additives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial protein offers margin expansion through continuous fermentation scale-down economics and premium-tier certification positioning in human nutrition. Cost compression in bioreactor-based systems accelerates payback periods for capital-rich first movers.
For Market Incumbents: Extend formulation bundling advantages by integrating microbial protein into existing amino acid premix contracts before standalone fermentation startups achieve GRAS notification completion. Anchor capacity additions in Singapore and Denmark where biotech clusters concentrate engineering talent and regulatory familiarity. Defend against pure-play methane-to-protein entrants by locking multi-year offtake agreements with carbon-conscious aquafeed integrators ahead of competitor commissioning timelines. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for natural refrigerant cooling system specialists to retrofit existing fermentation facilities at 8-12% capital premiums. Target India's shrimp farming sector in Andhra Pradesh and Gujarat where certified sustainable feed inputs remain underpenetrated and first-mover partnerships command pricing power. Pursue go-to-market angles through direct bioreactor supply agreements rather than competing against established distribution networks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers lack dedicated REACH compliance teams and face fixed cost disadvantages against integrated nutrition conglomerates. Five-to-ten year viability favors technology licensors with continuous culture intellectual property and captive feedstock arrangements. Acquisition target archetype: fermentation operators with EFSA novel food pipeline progress and regional production partnerships in Southeast Asia. Watch Singapore 30 by 30 funding disbursement velocity as inflection indicator for regional capacity buildout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Commissioning | Steady-state operation cuts labor intensity per kilogram for Northern European aquafeed suppliers. |
| EFSA Novel Food Authorization Investment | Two-year regulatory timelines in Europe shape human-grade product launch sequencing and capital pacing. |
| Modular Ingredient Bundling | DSM-Firmenich leverages European distribution networks to capture volumes through integrated nutrition contracts. |
| Natural Refrigerant Retrofit Compliance | EU F-Gas Regulation mandates create 8-12% facility engineering cost premiums for early Dutch adopters. |
| Methane Feedstock Partnership | Calysta-style platforms secure long-term natural gas supply agreements to stabilize input cost volatility. |
Research Methodology
Coverage spans Northern Europe, Southeast Asia, and North America, with primary inputs from each region combined with secondary validation. Fermentation facility operators, compound feed procurement directors, aquafeed nutritionists, and regulatory affairs specialists at EFSA and FDA provided operational data. Secondary sources included EU F-Gas Regulation implementation filings, REACH chemical registration databases, Singapore Enterprise Singapore investment disclosures, and SEC filings from integrated nutrition conglomerates. Bottom-up capacity installation tracking and top-down protein substitution demand modeling were triangulated against trade flow data.
Granularity-level modeling disaggregated volume and value across product type, application, production technology, and end-user industry dimensions throughout the projection horizon. CAGRs were derived from bioreactor commissioning timelines, offtake contract pricing trajectories, and feedstock cost scenario analysis. Industry-specific forecast inputs incorporated EU Green Deal livestock emissions reduction enforcement schedules and FSSAI novel food regulatory pathway developments in India.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price volatility and EFSA authorization timeline extensions. Forecasts reflect assumptions about continuous fermentation technology adoption rates and carbon border adjustment mechanism implementation scope. Regulatory enforcement intensity, feedstock supply disruption, and bioprocess engineering talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market