
 Asia-Pacific G-CSF/ PEG-G-CSF Market | 2026-2036
Asia-Pacific G-CSF/ PEG-G-CSF Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific G-CSF/ PEG-G-CSF Market Outlook
A shift from single-source originator contracts toward multi-source biosimilar procurement is restructuring hospital pharmaceutical committees across the Asia-Pacific G-CSF/ PEG-G-CSF Market. Amgen sustains brand loyalty among oncology departments through its established pegfilgrastim formulations. CSPC leverages domestic manufacturing scale to undercut imported originator pricing in China's provincial tenders. Jiangsu Hengrui Medicine anchors its position through vertical control over recombinant protein production from cell line to finished vial.
G-CSF (granulocyte colony-stimulating factor) and its polyethylene glycol-conjugated variant PEG-G-CSF are recombinant glycoproteins produced in E. coli or mammalian cell cultures, formulated at specific protein concentrations to stimulate neutrophil proliferation and maturation in bone marrow. These agents serve as prophylactic and therapeutic support in myelosuppressive cancer regimens. Pegfilgrastim commands premium positioning in hospital formularies due to its once-per-cycle dosing convenience versus filgrastim's daily administration burden. Biosimilars are capturing volume fastest as China's centralized procurement and India's hospital chains prioritize cost containment. Cancer therapy applications generate the dominant revenue pool, though chronic neutropenia represents a stable maintenance segment with longer treatment durations.
Japan's PMDA maintains stringent comparability exercise requirements for biosimilar G-CSF entrants, while China's NMPA has streamlined review timelines for domestically manufactured filgrastim copies through its abbreviated pathway. Australia's TGA alignment with EU biosimilar guidance reduces redundant clinical trial burdens for sponsors targeting both markets. Stakeholders must monitor how South Korea's MFDS reimbursement price-capping mechanism and India's CDSCO accelerated approval track for oncology supportive care reshape competitive dynamics in the region.
Market Dynamics
Centralized hospital procurement networks across China, South Korea, and Australia are consolidating purchasing power, forcing filgrastim and pegfilgrastim suppliers to compete on unit economics rather than clinical differentiation alone.
Growth Catalysts
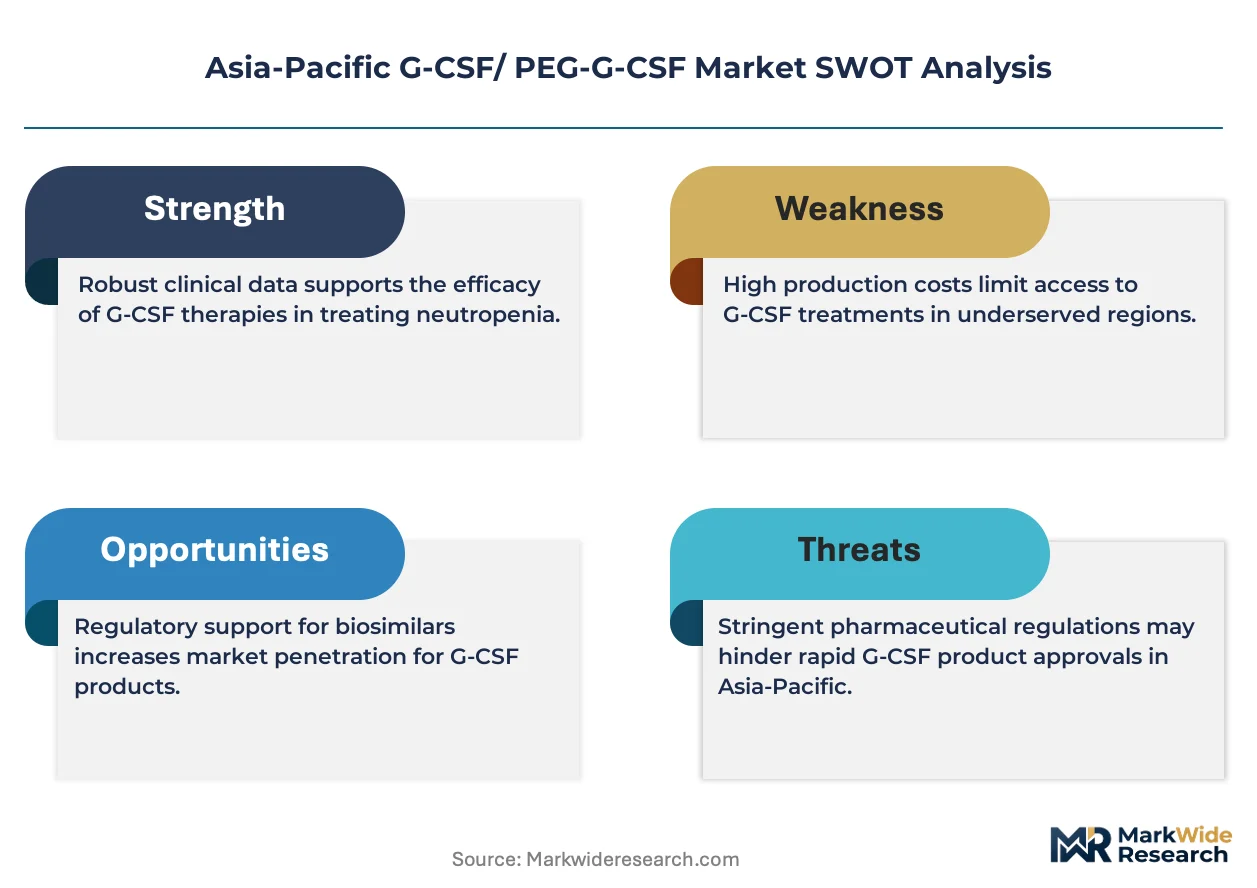
- NMPA's abbreviated biosimilar pathway:China's streamlined review timelines compress regulatory approval durations for domestic filgrastim manufacturers, accelerating market entry.
- Chemotherapy volume expansion:Oncology centers in South Korea are scaling myelosuppressive regimen administration, expanding prophylactic G-CSF demand.
- Recombinant protein production scale-up:Mammalian cell culture capacity investments across the region reduce per-unit manufacturing costs for glycoprotein therapeutics.
Market Restraints
- PMDA comparability stringency:Japan's exhaustive analytical exercise requirements for biosimilar G-CSF entrants impose prolonged development timelines and elevated clinical trial costs.
- Originator brand entrenchment:Established pegfilgrastim formulations retain formulary preference in premium hospital tiers despite biosimilar price undercutting.
- Plasmid DNA supply concentration:Regional dependence on limited qualified suppliers for expression vector materials creates input bottleneck vulnerability.
Strategic Opportunities
- Chronic neutropenia maintenance:Extended-duration treatment protocols in stable patient populations offer recurring revenue streams distinct from acute cancer cycle dependency.
- India's CDSCO accelerated oncology track:Expedited approval pathways for supportive care agents reduce time-to-revenue for filgrastim biosimilar sponsors.
- Prefilled syringe auto-injector convergence:Integration of single-dose delivery devices with pegylated formulations addresses home-administration demand in outpatient settings.
Industry Challenges
- Cell line development expertise scarcity:Qualified molecular biologists capable of optimizing high-titer CHO expression systems command premium compensation, constraining workforce scalability.
- Post-approval immunogenicity surveillance:Pharmacovigilance infrastructure requirements for biosimilar G-CSF sponsors demand sustained investment in adverse event monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific G-CSF/ PEG-G-CSF Market |
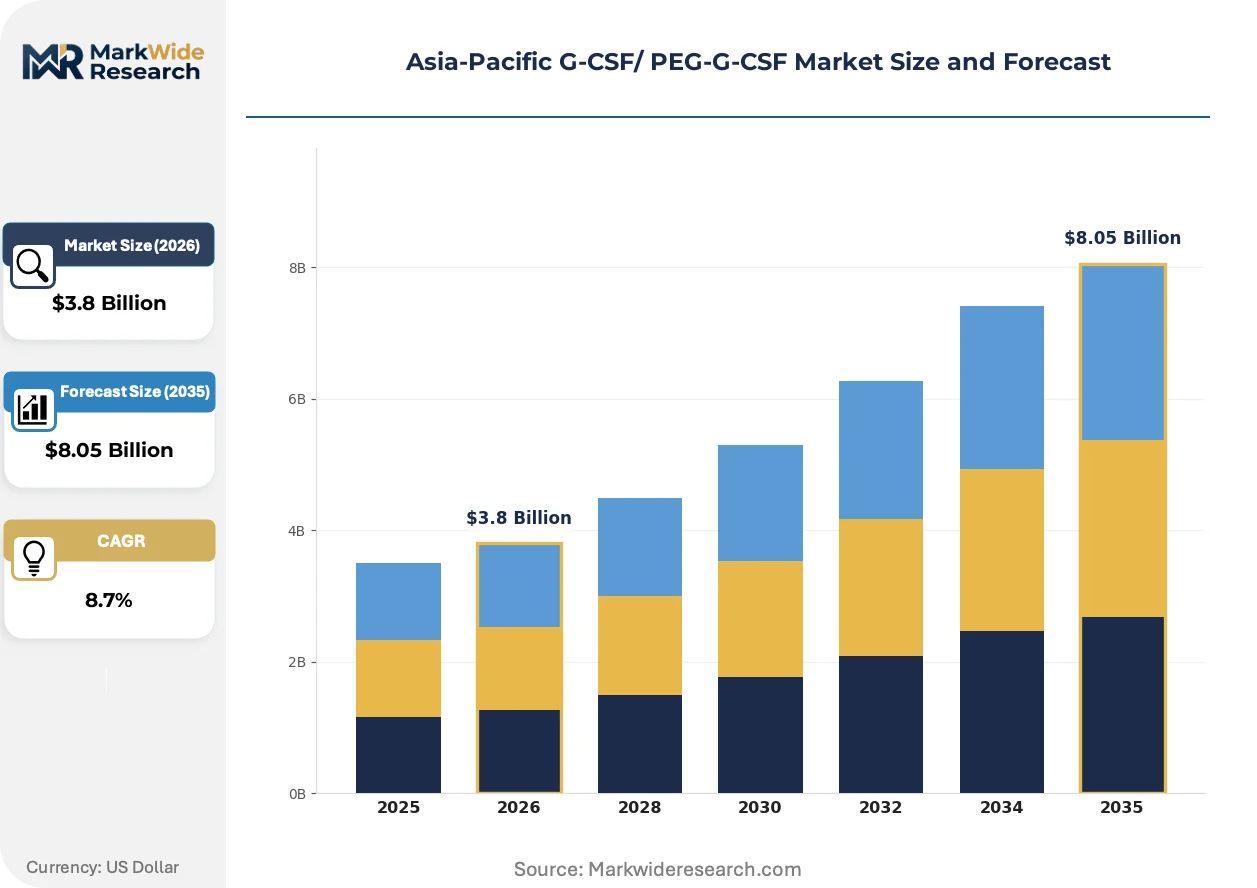
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filgrastim, Pegfilgrastim, Biosimilars, Others Application: Cancer Therapy, Bone Marrow Transplantation, Chronic Neutropenia, Others End User: Hospitals, Clinics, Pharmaceutical Companies, Contract Research Organizations Delivery Mode: Subcutaneous Injection, Intravenous Injection, Oral, Others |
| Companies Covered | Amgen, CSPC, Qilu Pharmaceutical, Jiangsu Hengrui Medicine, Sandoz, Fresenius Kabi, Teva Pharmaceutical Industries, Roche, Eisai, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific G-CSF/ PEG-G-CSF Market Strategic Shifts
Formulation science and delivery mechanism advances are compressing dosing frequency while regulatory pathway evolution is compressing development timelines across the Asia-Pacific G-CSF landscape.
Long-acting pegfilgrastim formulations incorporating novel PEGylation chemistries are electrifying prophylactic neutropenia management by enabling single-injection-per-chemotherapy-cycle protocols. Oncology departments in China's tier-one hospitals are adopting these agents at accelerating rates. This technology is electrifying market share capture away from daily filgrastim regimens by reducing nursing burden and patient clinic visits.
MFDS reimbursement price-capping mechanisms in South Korea are restructuring hospital pharmaceutical committee evaluation criteria for G-CSF procurement. Domestic biosimilar sponsors gain preferential formulary placement when demonstrating cost parity with regional reference products. Cancer therapy centers are responding by diversifying supplier portfolios beyond single-originator dependence.
Centralized tendering platforms in China's provincial procurement networks are consolidating buyer power across multiple hospital systems. Cost-competitive pegfilgrastim suppliers displace fragmented distributor relationships through direct contract execution. This concentration is most visible in Jiangsu and Guangdong provinces, where volume-based procurement mandates favor manufacturers with captive fermentation capacity.
Asia-Pacific G-CSF/ PEG-G-CSF Market Segmentation
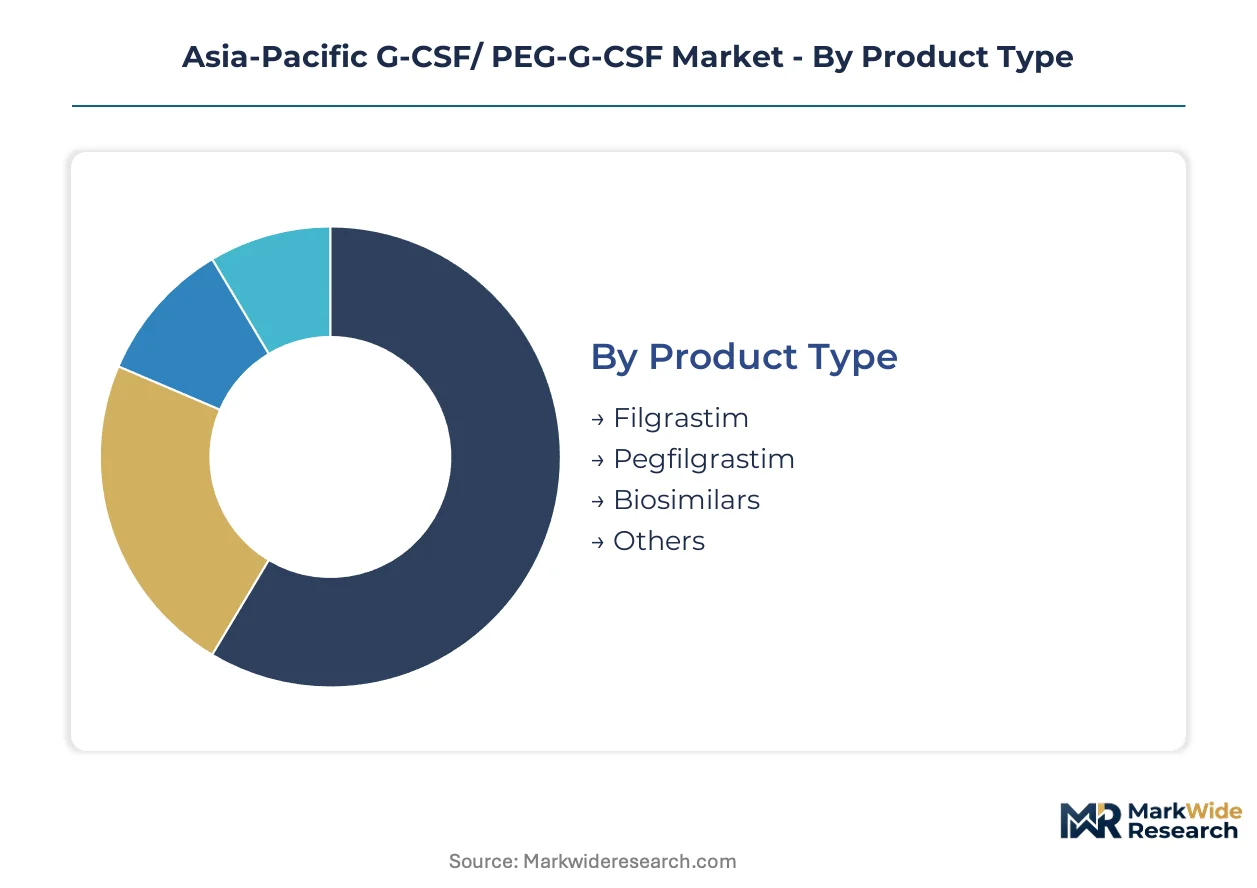
Segmentation in the Asia-Pacific G-CSF/PEG-G-CSF market reveals how procurement networks, clinical protocols, and manufacturing scale interact across distinct product tiers and delivery modes. Understanding these divisions exposes where pricing power concentrates and where biosimilar competition disrupts established revenue pools.
Product Type:
Standardization dominates filgrastim and biosimilar categories, while pegfilgrastim retains customization premiums through formulation complexity and dosing convenience.
- Filgrastim:Daily-administered recombinant G-CSF produced in E. coli or mammalian systems, requiring multi-dose regimens per chemotherapy cycle. Demand concentrates in China's provincial hospital networks where NMPA-abbreviated pathways have accelerated domestic manufacturing scale. Cost containment pressures from centralized tendering compress margins despite volume expansion.
- Pegfilgrastim:PEGylated long-acting variant enabling single-injection-per-cycle protocols through extended pharmacokinetic half-life. Oncology departments in South Korea's cancer therapy centers prioritize this format for reduced nursing burden and outpatient clinic efficiency. Premium positioning persists in tier-one Chinese hospitals despite biosimilar undercutting.
- Biosimilars:NMPA and CDSCO pathway approvals are compressing development timelines for domestic filgrastim and pegfilgrastim copies across China and India.
- Others:Investigational long-acting formulations and novel PEGylation chemistries occupy pre-commercial development pipelines.
Leading the category by volume: Filgrastim. Growing fastest: Biosimilars.
Application:
Volume scales with chemotherapy administration intensity, while margin durability varies sharply between acute prophylaxis and chronic maintenance protocols.
- Cancer Therapy:Prophylactic neutropenia prevention during myelosuppressive regimens generates dominant revenue concentration. China's hospital procurement networks and South Korea's expanding cancer centers drive demand scaling with chemotherapy volume expansion. Biosimilar capture accelerates fastest in this segment due to cost-containment procurement mandates.
- Bone Marrow Transplantation:High-intensity conditioning regimens require intensive G-CSF support for engraftment acceleration and neutrophil recovery. Australia's TGA-aligned transplant centers and Japan's PMDA-regulated academic hospitals concentrate demand for originator-grade products where immunogenicity risk tolerance is lowest.
- Chronic Neutropenia:Extended-duration maintenance protocols in stable patient populations create recurring revenue streams with lower cycle-to-cycle volatility than acute cancer applications.
- Others:Severe congenital neutropenia and cyclic neutropenia represent niche indications with orphan-drug pricing potential.
Cancer Therapy commands absolute volume share. Bone Marrow Transplantation sustains the steepest premium pricing.
End User:
Procurement sophistication stratifies sharply between consolidated hospital networks and fragmented outpatient settings.
- Hospitals:Centralized tendering platforms in China's provincial systems and South Korea's MFDS price-capped reimbursement pools consolidate purchasing power. Multi-source biosimilar procurement is displacing single-originator contracts across tier-one and tier-two facilities.
- Clinics:Outpatient oncology clinics in Australia and Japan's urban centers are adopting prefilled auto-injector formats for home administration convenience.
- Pharmaceutical Companies:Contract manufacturing demand from regional biosimilar sponsors seeking recombinant protein production capacity.
- Contract Research Organizations:Clinical trial supply for biosimilar comparability studies and post-approval immunogenicity surveillance protocols.
Hospitals absorb the dominant procurement volume. Pharmaceutical companies are expanding fastest as biosimilar development accelerates.
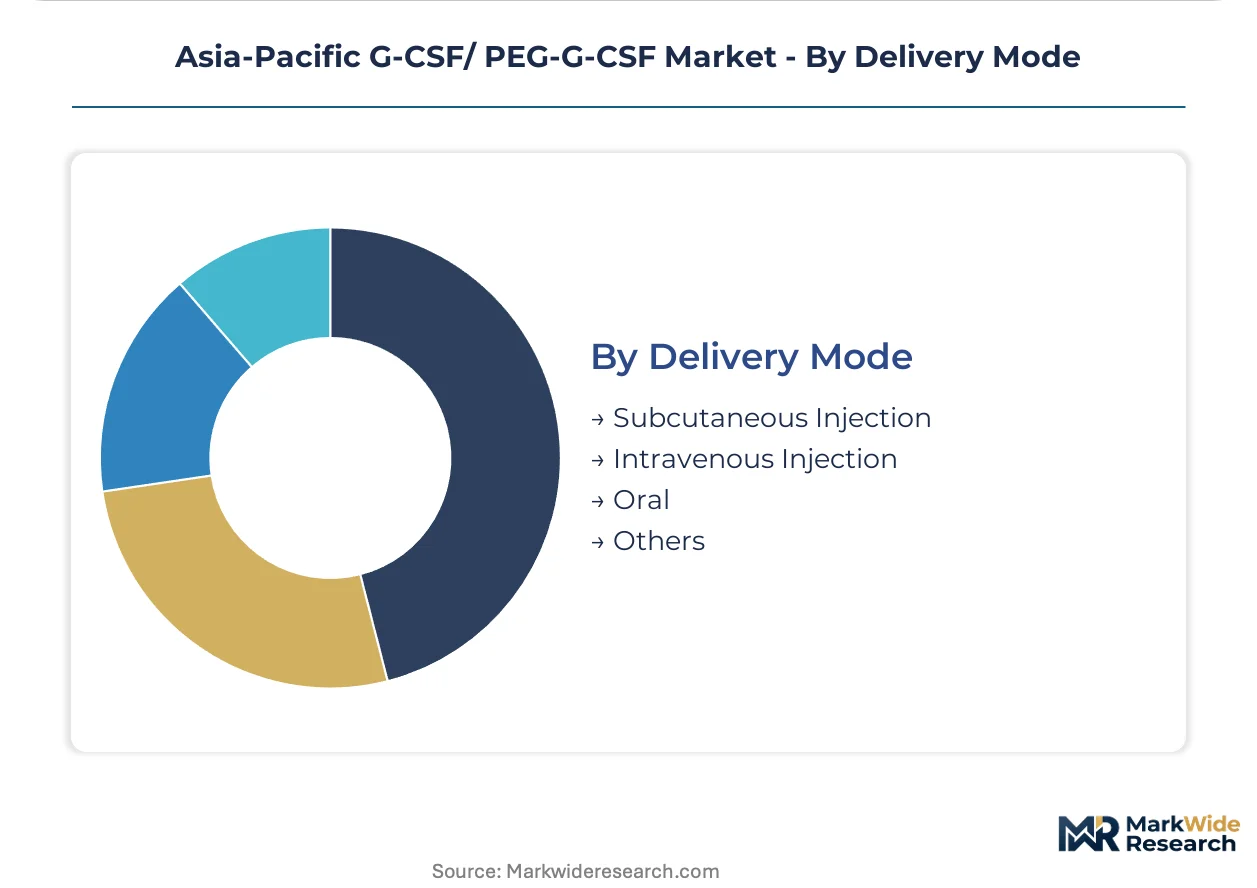
Delivery Mode:
Patient convenience and healthcare resource efficiency are displacing traditional administration formats across the region.
- Subcutaneous Injection:Primary delivery route for pegfilgrastim and filgrastim formulations, enabling outpatient self-administration. Prefilled syringe and auto-injector convergence is reshaping product differentiation in China's home-care expansion segments.
- Intravenous Injection:Reserved for inpatient settings and specific clinical protocols requiring direct vascular delivery.
- Oral:No commercially viable oral G-CSF formulations exist; this category captures investigational small-molecule approaches in early development.
- Others:Implanted depot formulations and transdermal delivery systems remain preclinical.
Subcutaneous Injection dominates administration volume. Auto-injector integration represents the fastest-advancing format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant protein fermentation capacity in China anchors Asia-Pacific G-CSF supply chains. Mammalian cell culture investments across South Korea and India are redrawing regional manufacturing maps.
China
Provincial hospital procurement networks in Jiangsu and Guangdong concentrate pegfilgrastim demand through volume-based tendering mandates. NMPA's abbreviated biosimilar pathway compresses regulatory timelines for domestic filgrastim manufacturers. Beijing-Tianjin-Hebi corridor hosts expanding CHO cell line development facilities serving regional biosimilar sponsors.
South Korea
Cancer therapy centers in Seoul and Busan scale myelosuppressive chemotherapy administration, expanding prophylactic G-CSF procurement volumes. MFDS reimbursement price-capping mechanisms restructure hospital pharmaceutical committee evaluation criteria for supplier selection. Daegu-Gyeongbuk biocluster anchors recombinant protein production investments from domestic and multinational sponsors.
Japan
PMDA comparability exercise requirements impose exhaustive analytical standards on biosimilar G-CSF entrants, prolonging development timelines. Tokyo and Osaka academic medical centers maintain formulary preference for originator-grade pegfilgrastim in transplant protocols. Kansai region concentrates mammalian cell culture expertise serving immunogenicity-sensitive applications.
India
CDSCO's accelerated approval track for oncology supportive care reduces time-to-market for filgrastim biosimilar developers. Hospital chains in Maharashtra and Gujarat prioritize cost containment through multi-source procurement strategies. Hyderabad-Chennai corridor hosts contract manufacturing demand from regional biosimilar sponsors seeking recombinant protein capacity.
Australia
TGA alignment with EU biosimilar guidance reduces redundant clinical trial burdens for sponsors targeting dual-market registration. Melbourne and Sydney transplant centers concentrate demand for originator-grade G-CSF in bone marrow engraftment protocols. Victoria's biotechnology precinct supports analytical method development for comparability studies.
Asia-Pacific G-CSF/ PEG-G-CSF Market Competitive Environment
Global majors compete with regional champions across regulatory pathway access and manufacturing scale. The vendor base stratifies between originator brand incumbents, domestic biosimilar scale players, and contract manufacturing specialists. Three archetypes dominate: multinational originators defending premium positioning, Chinese manufacturers exploiting NMPA pathway advantages, and Indian biosimilar developers leveraging CDSCO acceleration. Competitive moves concentrate on capacity expansion in mammalian cell culture and strategic partnerships for plasmid DNA supply security.
Among originator-tier anchors, Amgen exemplifies brand-loyalty defense through established pegfilgrastim formulations. CSPC and Jiangsu Hengrui Medicine occupy positions within the domestic Chinese manufacturer archetype, representing vertical control from cell line development through finished vial production. These three entities illustrate the competitive tension between global clinical differentiation and regional cost-competitive manufacturing scale.
| Leading Market Players |
|---|
| Amgen |
| CSPC |
| Qilu Pharmaceutical |
| Jiangsu Hengrui Medicine |
| Sandoz |
| Fresenius Kabi |
| Teva Pharmaceutical Industries |
| Roche |
| Eisai |
| Others |
Value Chain & Pricing Dynamics
Qualified molecular biologists capable of optimizing high-titer CHO expression systems in the Beijing-Tianjin-Hebei corridor command premium compensation, widening spreads between originator-grade and biosimilar pricing tiers across the Asia-Pacific G-CSF landscape. Labor-cost differentials between China's coastal bioclusters and inland fermentation facilities feed directly into procurement negotiations for hospital pharmaceutical committees weighing daily filgrastim against single-dose pegfilgrastim formats.
Pricing Analysis
Warranty and cold-chain assurance bundling separates originator pegfilgrastim contracts from unbundled biosimilar tenders in China's provincial procurement networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by immunogenicity surveillance depth and batch-release documentation rigor. Cost compression in the biosimilar tier is intensifying because NMPA-abbreviated pathway approvals compress development recovery timelines. Hospital procurement managers in South Korea's MFDS-capped reimbursement pools exhibit highest price sensitivity, while Japan's transplant centers maintain lowest sensitivity due to PMDA-mandated comparability thresholds.
Supply Chain Analysis
Regional distribution centers in Shanghai, Singapore, and Mumbai operate hub-and-spoke patterns for temperature-sensitive glycoprotein finished goods. Manufacturing concentrates in China, South Korea, and India, with plasmid DNA expression vectors drawing from qualified suppliers in the United States and Germany. Single-source vulnerability in mammalian cell culture media creates exposure to raw material qualification delays. Distribution runs through hospital procurement networks in China and pharmaceutical distributor consignment models in Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with captive fermentation capacity, as centralized tendering and NMPA pathway acceleration squeeze contract-dependent players without upstream control.
For Market Incumbents: Lock in cell line development expertise through dedicated training pipelines in the Beijing-Tianjin-Hebei corridor, insulating against workforce scarcity that threatens biosimilar scale-up timelines. Secure plasmid DNA supply through dual-qualified vendor relationships, mitigating single-source concentration risk that could disrupt batch release schedules. Expand mammalian cell culture capacity in South Korea's Daegu-Gyeongbuk biocluster to capture MFDS price-capped volume without sacrificing margin on logistics. For New Entrants and Emerging Players: Begin with chronic neutropenia maintenance protocols in India's Maharashtra hospital chains, where CDSCO accelerated approval tracks compress time-to-revenue and prescriber loyalty remains underdeveloped. Target prefilled auto-injector convergence for home administration in Australia's outpatient oncology clinics, where TGA-EU alignment reduces redundant clinical investment. Lead with cost-parity positioning against regional reference products rather than clinical differentiation claims. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated domestic Chinese manufacturers given NMPA pathway acceleration and provincial tendering consolidation. Long-term viability over the coming decade hinges on backward integration into recombinant protein production from cell line through finished vial. Watch for MFDS reimbursement price-cap expansion beyond Seoul and Busan as the inflection signal for regional procurement harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Mammalian Cell Culture Scale-Up | Captive fermentation capacity in China's Jiangsu and Guangdong provinces secures volume-based procurement eligibility. |
| NMPA Biosimilar Pathway Navigation | Abbreviated review timelines compress regulatory approval durations for domestic filgrastim sponsors. |
| Plasmid DNA Supply Security | Dual-qualified expression vector vendors mitigate single-source bottleneck vulnerability in glycoprotein production. |
| Prefilled Auto-Injector Integration | Single-dose delivery device convergence addresses home-administration demand in Australia's outpatient settings. |
| Post-Approval Immunogenicity Surveillance | Sustained pharmacovigilance investment satisfies PMDA comparability requirements for Japan market entry. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced against NMPA and PMDA regulatory databases for pathway timeline validation. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors in China, South Korea, and India supplied forward-looking procurement intention data. Bottom-up and top-down triangulation reconciled manufacturer capacity disclosures with hospital tendering volume aggregates.
Bottom-up modeling anchored forecasts to individual country chemotherapy administration growth trajectories and biosimilar penetration assumptions, while top-down validation checked aggregate regional spend against macro healthcare budget allocations. Treatment line, dosage form, administration route, and regional regulatory cluster segmentation dimensions shaped volume projections across the analysis window. CAGRs derived from fitted growth curves applied to historic procurement data, with input from mammalian cell culture capacity expansion announcements and CDSCO approval pipeline tracking.
Underlying measurement precision varies by segment; cancer therapy applications carry tighter precision than chronic neutropenia maintenance due to chemotherapy volume reporting standardization. Forecasts reflect documented assumptions regarding NMPA pathway efficiency and MFDS reimbursement stability, with revision risk from PMDA comparability stringency changes or plasmid DNA supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
CMO and CDMO Biotechnology Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Alpha Mannosidosis Market