
 Hormone Sensitive Prostate Cancer Market | 2026-2036
Hormone Sensitive Prostate Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Hormone Sensitive Prostate Cancer Market Foresight
FDA accelerated approval pathway redesign is broadening the cost-of-entry calculus for hormone sensitive prostate cancer drug developers, demanding larger confirmatory trial commitments before full approval. Pfizer leverages its established oncology manufacturing scale to sustain supply security across North American hospital networks. Johnson & Johnson anchors its position through deep urology channel relationships and integrated patient support infrastructure. Astellas Pharma differentiates via concentrated R&D intensity in next-generation androgen receptor signaling inhibitors.
Hormone sensitive prostate cancer denotes malignancies that initially respond to androgen deprivation, requiring therapeutic suppression of testosterone or androgen receptor activity through surgical or pharmacological castration, typically measured by PSA response criteria and radiographic progression-free survival endpoints. Androgen Deprivation Therapy occupies the dominant revenue position as the foundational backbone across all disease stages, while Anti-Androgens represent the fastest-expanding margin pool driven by next-generation agent uptake in metastatic settings. Oral administration routes command the largest volume share due to patient convenience and outpatient cost structures, though subcutaneous formulations are gaining traction in home care transitions.
FDA, EMA, and WHO guideline frameworks collectively shape hormone sensitive prostate cancer product standards, trial design, and market access timelines, with each body tightening evidentiary requirements for overall survival benefits in hormonal therapy approvals. The FDA's Project Optimus initiative is forcing dose-optimization studies earlier in development, extending regulatory timelines but potentially improving long-term safety profiles. Stakeholders must monitor emerging biomarker-driven patient stratification approaches that could fragment addressable populations and reshape commercial targeting priorities.
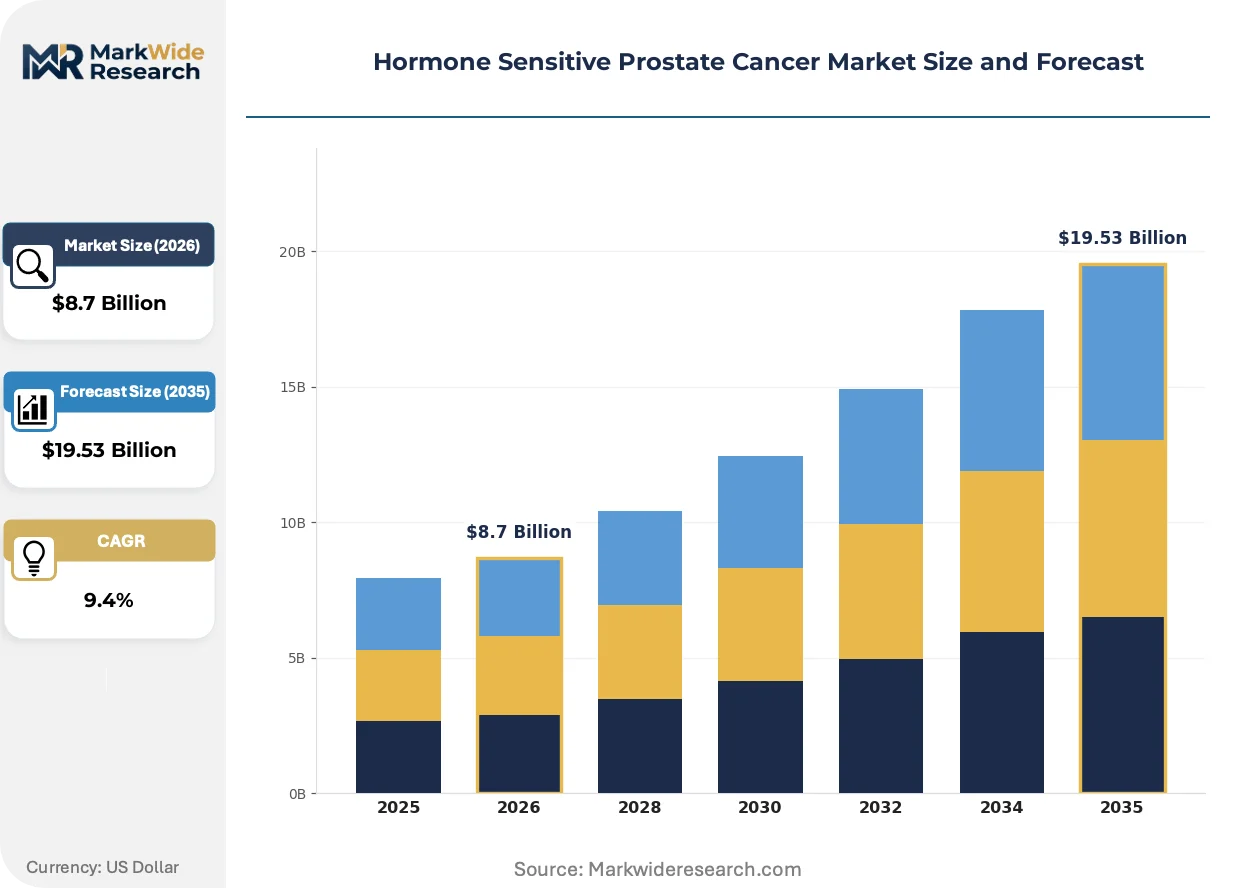
Market Dynamics
FDA's Project Optimus initiative is forcing dose-optimization studies earlier in hormone sensitive prostate cancer drug development, extending regulatory timelines while reshaping clinical trial design requirements for androgen receptor signaling inhibitors.
Growth Catalysts
- Hospital-based oncology expansion:Major academic medical centers in the United States are scaling combination androgen deprivation protocols, creating pull-through demand for next-generation hormonal agents.
- EMA's adaptive pathway frameworks:European regulators are streamlining conditional marketing authorization for novel hormonal therapies, compressing time-to-market for metastatic hormone sensitive prostate cancer treatments.
- PSA response biomarker integration:Liquid biopsy technologies are enabling earlier patient stratification, accelerating enrollment into targeted hormonal therapy trials.
Market Restraints
- Confirmatory trial cost inflation:FDA's post-confirmatory mortality endpoint requirements are doubling late-phase development expenditure for androgen receptor pathway inhibitors.
- Active pharmaceutical ingredient concentration:Steroid hormone synthesis capabilities cluster in China and India, creating supply vulnerability for castration-resistant progression therapies.
- Cross-resistance mechanisms:Prior abiraterone or enzalutamide exposure limits efficacy of sequential hormonal agents, narrowing eligible populations for later-line therapies.
Strategic Opportunities
- Home care administration transition:Subcutaneous depot formulations are opening ambulatory and home infusion channels, bypassing hospital-based oncology infusion center bottlenecks.
- Biomarker-driven trial design:AR-V7 splice variant detection is enabling enrichment strategies that could accelerate regulatory pathways for AR-targeted combinations.
- Japan's Sakigake designation:Japan's PMDA priority review system offers compressed approval timelines for first-in-class hormonal agents addressing unmet castration-resistant needs.
Industry Challenges
- Overall survival endpoint execution:Prolonged survival in metastatic hormone sensitive prostate cancer extends trial duration, compressing patent exclusivity windows for developers.
- Integrated patient support infrastructure:Co-pay assistance and adherence program deployment requires specialized hub services that strain mid-cap pharmaceutical operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hormone Sensitive Prostate Cancer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Androgen Deprivation Therapy, Anti-Androgens, Chemotherapy, Radiotherapy Patient Stage: Localized, Locally Advanced, Metastatic, Recurrence Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Home Care, Research Institutions |
| Companies Covered | Pfizer, Johnson & Johnson, Astellas Pharma, Bayer AG, AstraZeneca, Novartis, Merck & Co., AbbVie, Ferring Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hormone Sensitive Prostate Cancer Market Shifts & Advancements
Next-generation androgen receptor signaling inhibitors are compressing development cycles while biomarker stratification fragments addressable patient populations into molecularly defined subgroups.
Radioligand therapy conjugation is electrifying the hormone sensitive prostate cancer landscape by merging targeted hormonal suppression with cytotoxic payload delivery. Major oncology centers in Germany and the United States are establishing theranostic infrastructure to support lutetium-based prostate-specific membrane antigen targeting. This convergence is compressing the traditional boundary between hormonal and cytotoxic therapy paradigms, forcing developers to reposition androgen receptor inhibitors within combination radioligand protocols.
REACH regulatory pressure in Europe is tightening environmental discharge standards for steroid hormone manufacturing, forcing API producers to invest in closed-loop synthesis systems. Contract manufacturers serving European hormonal drug developers face accelerated compliance deadlines for persistent organic pollutant reduction. Small-molecule androgen receptor antagonist producers with German and Swiss manufacturing footprints are absorbing capital expenditure increases to maintain EMA-approved site status.
Hospital procurement consolidation is concentrating purchasing authority within integrated delivery networks, compressing price negotiation leverage for standalone hormonal agents. Oncology therapeutics committees at major US academic medical centers are demanding head-to-head overall survival data before formulary inclusion of next-generation anti-androgens. This behavioral shift is most visible in the Northeastern and Midwestern United States, where health system mergers have created super-regional pharmacy and therapeutics governance structures.
Hormone Sensitive Prostate Cancer Market Segmentation
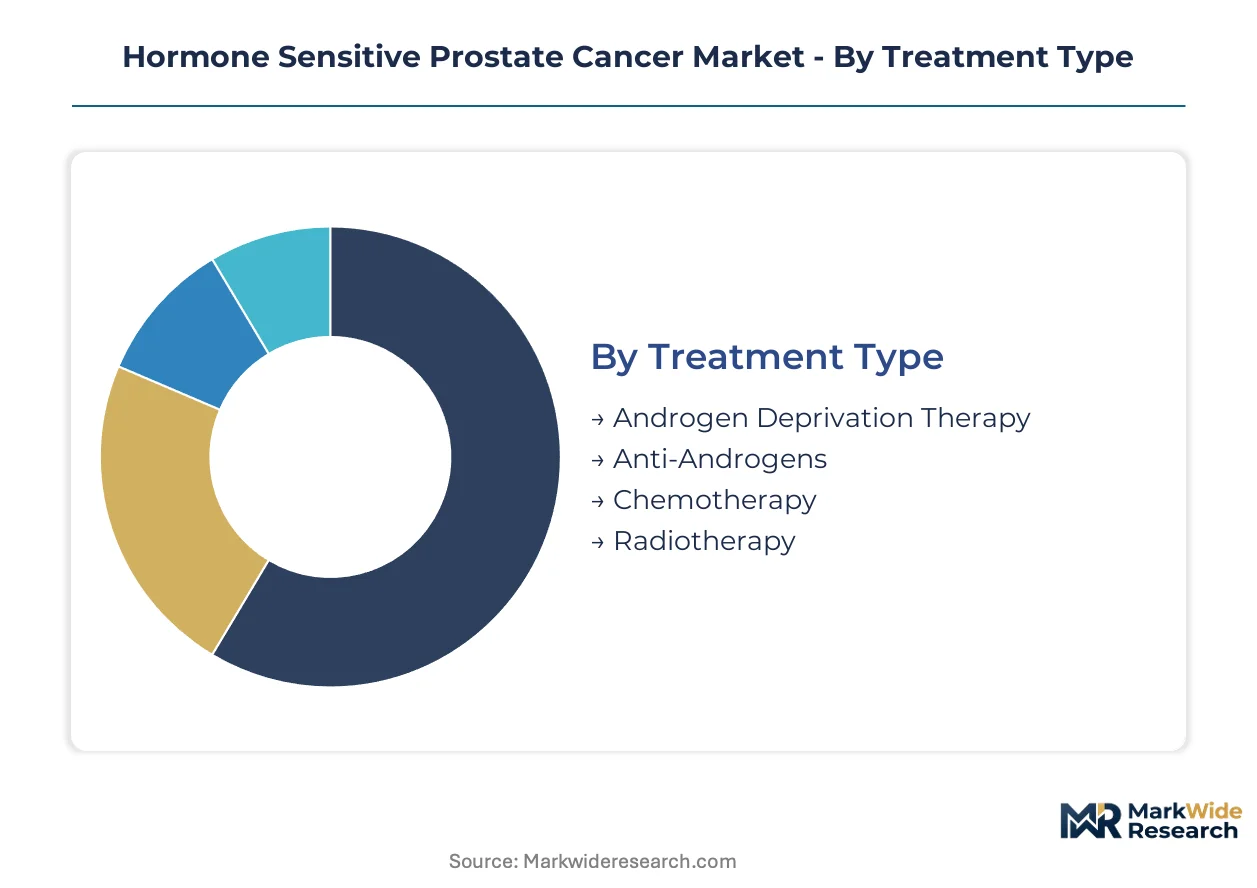
Patient stratification by disease stage and molecular characteristics is fragmenting addressable populations into smaller, biomarker-defined subgroups. Pharmaceutical developers must align formulation strategies with specific administration settings and reimbursement pathways.
Treatment Type:
Upgrade cycles from first-generation castration agents to next-generation androgen receptor inhibitors are compressing revenue lifecycles for legacy molecules.
- Androgen Deprivation Therapy:Surgical or pharmacological castration remains the foundational backbone across all disease stages. Hospital-based oncology departments in the United States sustain the largest volume commitments for luteinizing hormone-releasing hormone agonists and antagonists.
- Anti-Androgens:Next-generation agents including enzalutamide and apalutamide demonstrate superior radiographic progression-free survival. Demand concentrates in metastatic settings where oral bioavailability drives outpatient prescribing.
- Chemotherapy:Docetaxel regimens retain utility in high-volume metastatic disease despite hormonal therapy advances. Academic medical centers deploy combination protocols before castration resistance emerges.
- Radiotherapy:External beam and brachytherapy approaches address localized disease with curative intent. German university hospitals are integrating radioligand theranostics into hormone-sensitive treatment sequences.
Volume placements concentrate in Androgen Deprivation Therapy; the faster expansion belongs to Anti-Androgens.
Patient Stage:
Cost tier differentiation separates curative-intent localized protocols from chronic management approaches in metastatic populations.
- Localized:Disease confined to the prostate gland permits radical prostatectomy or definitive radiotherapy. Active surveillance protocols in Swedish urology centers are delaying hormonal intervention.
- Locally Advanced:Extraprostatic extension without distant metastasis drives neoadjuvant and adjuvant hormonal combinations. French oncology networks emphasize multimodal treatment intensification.
- Metastatic:Distant spread to bone or viscera mandates systemic hormonal suppression with life-long therapy. The FDA's overall survival endpoint requirements dominate trial design for this population.
- Recurrence:Biochemical relapse after primary therapy triggers salvage hormonal protocols. PSA doubling time calculations guide treatment initiation in United Kingdom tertiary centers.
Commercial investment concentrates in Metastatic disease; the steepest expansion trajectory is appearing in Recurrence management.
Administration Route:
Patient convenience preferences are displacing hospital-dependent infusion models toward self-administered oral and subcutaneous alternatives.
- Oral:Small-molecule androgen receptor inhibitors enable outpatient management without infusion center dependency. United States pharmacy benefit designs favor oral agents with streamlined prior authorization.
- Intravenous:Cytotoxic chemotherapy and some hormonal agents require supervised administration. Hospital capacity constraints in Italy are limiting intravenous treatment access.
- Subcutaneous:Depot formulations of luteinizing hormone-releasing hormone antagonists permit home administration. Japanese home care infrastructure is accelerating subcutaneous adoption.
- Intramuscular:Long-acting injectable testosterone suppressants sustain castration with monthly or quarterly dosing. Rural Australian clinics rely on intramuscular options where infusion access is limited.
Prescription volume concentrates in Oral administration; the fastest share gain is occurring in Subcutaneous delivery.
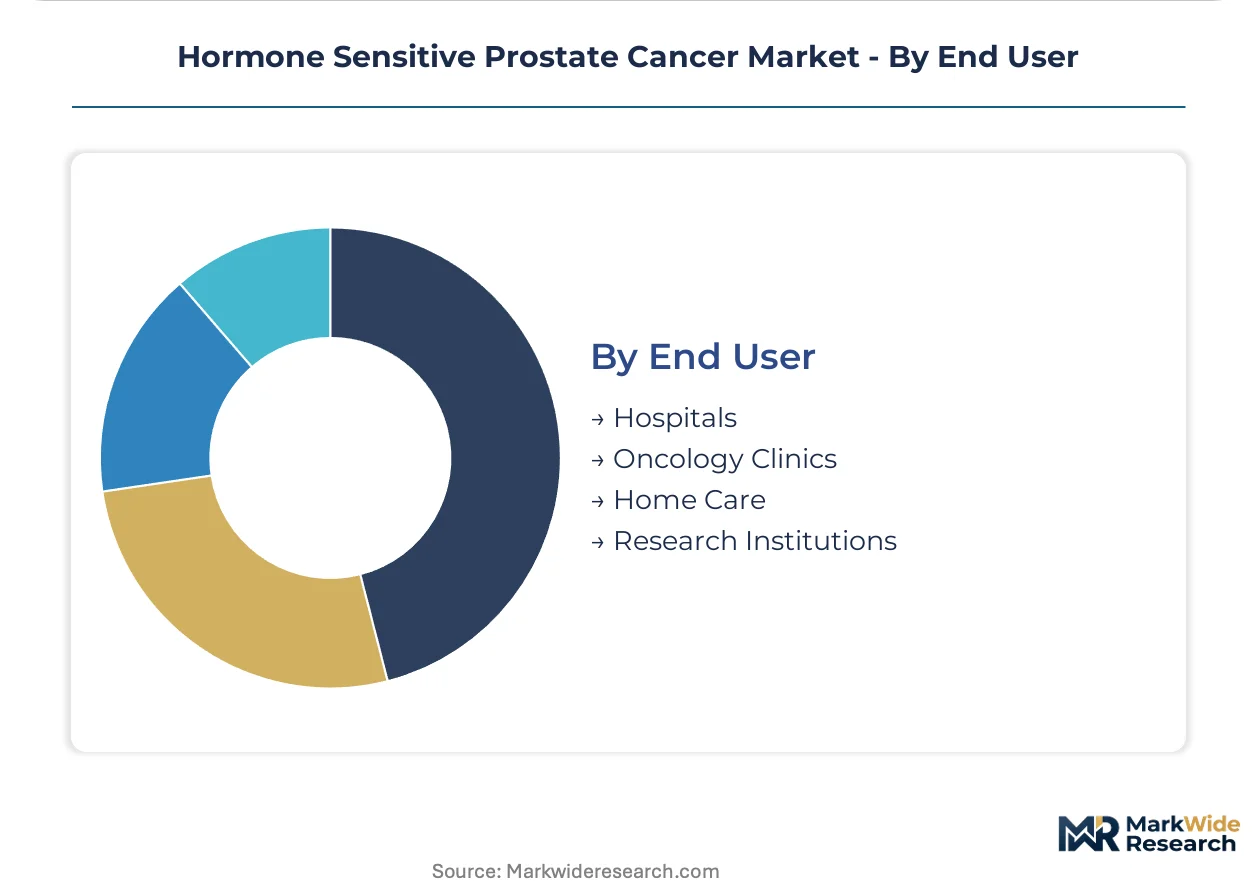
End User:
Procurement authority is concentrating within integrated delivery networks that span hospital and ambulatory settings.
- Hospitals:Academic medical centers command the largest hormonal therapy procurement volumes through oncology therapeutics committees. Northeastern United States health system mergers are creating super-regional formulary governance.
- Oncology Clinics:Community-based infusion centers handle stable patients on established hormonal regimens. German office-based oncologists manage substantial metastatic hormone-sensitive populations.
- Home Care:Subcutaneous depot administration is shifting treatment delivery from facilities to residential settings. Home infusion vendors in the Netherlands are building specialized urology nursing capabilities.
- Research Institutions:Phase I-III trial sites drive early adoption of investigational hormonal agents. National Cancer Institute-designated centers in the United States enroll the majority of registrational studies.
Patient volume concentrates in Hospitals; the most rapid channel expansion is appearing in Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Opportunity Zones and German BioRegions concentrate pharmaceutical R&D tax incentives, pulling hormone sensitive prostate cancer clinical trial infrastructure toward Boston-Cambridge, Research Triangle Park, and Munich-Martinsried clusters.
United States
Academic medical centers in Massachusetts and North Carolina enroll the majority of registrational hormonal therapy trials. FDA's Project Optimus initiative mandates dose-optimization studies earlier, extending development timelines for androgen receptor inhibitors. The Boston-Cambridge corridor houses concentrated Phase I-III site networks serving metastatic hormone sensitive populations.
Germany
University hospitals in Munich and Heidelberg integrate radioligand theranostics into hormone-sensitive treatment sequences. REACH regulatory pressure tightens environmental discharge standards for steroid hormone manufacturing, forcing API producers toward closed-loop synthesis. The Martinsried biotechnology cluster anchors EMA-aligned clinical development for next-generation anti-androgens.
Japan
PMDA's Sakigake designation offers compressed approval timelines for first-in-class hormonal agents. Home care infrastructure accelerates subcutaneous depot administration transitions from hospital to residential settings. The Kanto region's tertiary centers lead enrollment for castration-resistant combination studies.
United Kingdom
NHS England's Cancer Drugs Fund creates accelerated access pathways for novel hormonal therapies meeting cost-effectiveness thresholds. PSA doubling time calculations at London and Manchester tertiary centers guide biochemical relapse treatment initiation. The Oxford-Cambridge arc concentrates early-phase androgen receptor signaling inhibitor development.
Switzerland
Swissmedic's alignment with EMA standards streamlines concurrent European market authorization for hormonal agents. Basel and Zurich house specialized urology nursing capabilities supporting home infusion transitions. Contract manufacturers absorb capital expenditure increases to maintain EMA-approved site status for steroid hormone synthesis.
Hormone Sensitive Prostate Cancer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the hormone sensitive prostate cancer landscape, producing a tiered structure where scale-driven pharmaceutical majors anchor hospital procurement while mid-cap developers concentrate on next-generation androgen receptor signaling inhibitors. The vendor base organizes around three strategic archetypes: integrated oncology majors with established manufacturing scale, urology-focused specialists with deep channel relationships, and emerging biopharma developers pursuing biomarker-driven trial designs. Dominant competitive moves include M&A activity targeting androgen receptor pathway assets and strategic partnerships securing radioligand therapy conjugation capabilities.
Within the integrated oncology tier, Pfizer leverages manufacturing scale to sustain supply security across North American hospital networks, while Johnson & Johnson anchors position through urology channel infrastructure. Astellas Pharma exemplifies the R&D-intensive specialist archetype, occupying a concentrated position in next-generation androgen receptor signaling inhibitor development.
| Leading Market Players |
|---|
| Pfizer |
| Johnson & Johnson |
| Astellas Pharma |
| Bayer AG |
| AstraZeneca |
| Novartis |
| Merck & Co. |
| AbbVie |
| Ferring Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidation across the United States is concentrating purchasing authority within integrated delivery networks, forcing API manufacturers to absorb compliance costs for EMA-aligned steroid hormone synthesis while passing margin pressure downstream into next-generation anti-androgen pricing.
Pricing Analysis
Short lead-time premiums for next-generation androgen receptor inhibitors command substantial markups over standard procurement cycles in metastatic hormone-sensitive prostate cancer settings. Three-tier pricing structure across premium, standard, and economy levels separates patented oral anti-androgens from generic LHRH agonists and commodity surgical castration alternatives. Cost compression in the oral small-molecule tier is intensifying because of formulary exclusion demands from super-regional pharmacy and therapeutics committees. Community oncology clinics exhibit the highest price sensitivity due to thin reimbursement margins, while academic medical centers prioritize overall survival data over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA cGMP standards and EMA quality guidelines compel finished dose manufacturers to qualify API suppliers across multiple geographies. Steroid hormone synthesis capabilities cluster in China, India, and Switzerland, with contract manufacturers in Basel and Zurich absorbing capital expenditure increases for REACH-compliant closed-loop systems. Raw material dependencies span pregnenolone intermediates, rare metal catalysts for asymmetric synthesis, and specialized chromatography resins. Single-source vulnerability concentrates in advanced androgen receptor antagonist active pharmaceutical ingredients. Distribution runs through hospital-centric procurement networks with direct-to-pharmacy channels for oral agents and specialty distributor cold chains for subcutaneous depot formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's Project Optimus initiative and EMA's tightening evidentiary requirements for overall survival benefits have erected substantial cost-of-compliance barriers that protect incumbent developers with established regulatory affairs infrastructure and late-phase trial execution capabilities.
For Market Incumbents: Extend manufacturing scale advantages into subcutaneous depot formulation capacity to capture home care transition demand, while deepening urology channel relationships through integrated patient support infrastructure that mid-cap competitors cannot replicate. Cross-resistance mechanisms in sequential hormonal therapy threaten long-term revenue durability for androgen receptor pathway inhibitors, necessitating biomarker-driven combination trial investment to defend formulary position. For New Entrants and Emerging Players: Digital therapeutics platforms and remote patient monitoring systems offer lower regulatory entry costs than small-molecule development, enabling partnership-based penetration of adherence program and co-pay assistance services that strain mid-cap operational capacity. Japan's Sakigake designation pathway presents the most penetrable regulatory environment for first-in-class hormonal agents, with compressed approval timelines supporting accelerated commercialization through Kanto region tertiary center networks. For Investors and Strategic Acquirers: The window for entry favors developers with radioligand therapy conjugation capabilities and theranostic infrastructure integration, as this convergence compresses traditional boundaries between hormonal and cytotoxic paradigms. Acquisition target archetypes include mid-cap specialists with AR-V7 splice variant detection platforms and European API manufacturers with REACH-compliant steroid synthesis footprints. The signal to watch is radioligand therapy formulary adoption velocity at German university hospitals and United States National Cancer Institute-designated centers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA conditional marketing authorization compresses time-to-market for metastatic hormone-sensitive therapies in European markets. |
| Manufacturing Scale-Up | Pfizer's established oncology production networks sustain supply security across North American hospital networks during demand surges. |
| Pipeline Diversification | Astellas Pharma's concentrated R&D intensity in next-generation androgen receptor signaling inhibitors reduces single-asset dependency risk. |
| Licensing Agreement | Strategic partnerships securing radioligand therapy conjugation capabilities enable repositioning within combination theranostic protocols. |
| Reimbursement Strategy | NHS England's Cancer Drugs Fund creates accelerated access pathways for novel hormonal therapies meeting cost-effectiveness thresholds. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers across the United States, Germany, Japan, and the United Kingdom. FDA submission documents, EMA assessment reports, ClinicalTrials.gov entries, and hospital procurement databases provided validation points for market sizing. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across prescription audit feeds, distribution channel sell-in data, and payer claims databases enabled cross-validation of volume assumptions across the analysis window. Segmentation dimensions encompassed treatment type, patient stage, administration route, and end-user channel, with regional regulatory clusters capturing FDA, EMA, PMDA, and Swissmedic framework variations. CAGRs were derived from log-linear trend fitting to adjusted baseline estimates, incorporating PSA response biomarker adoption curves and radioligand therapy penetration assumptions as industry-specific forecast inputs.
Inputs from clinical trial registries and formulary databases were available through the study window; gaps in real-world evidence for home care administration transitions introduce uncertainty bands around subcutaneous delivery share projections. Deviation in FDA confirmatory trial mortality endpoint requirements or EMA REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Human Placental Protein Market