
 Global Preimplantation Genetic Diagnosis (PGD) Market | 2026-2036
Global Preimplantation Genetic Diagnosis (PGD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Preimplantation Genetic Diagnosis (PGD) Market Intelligence
The bundling of proprietary test kits with dedicated software tools is decoupling assay choice from the core sequencing hardware. Illumina leverages its dominant position in sequencing platforms to offer integrated PGD solutions. Natera specializes in cell-free DNA testing, creating a distinct niche in non-invasive screening. Thermo Fisher Scientific competes by offering a broad portfolio of reagents and instruments for genetic analysis.
Preimplantation Genetic Diagnosis involves the genetic profiling of embryos prior to implantation in an in-vitro fertilization cycle. The procedure analyzes DNA from one or more biopsied cells to identify specific genetic conditions or chromosomal defects. Next-Generation Sequencing technology is rapidly becoming the standard, displacing older methods like Fluorescence In Situ Hybridization. Applications for aneuploidy screening and identifying monogenic disorders represent the largest and most established use cases for PGD.
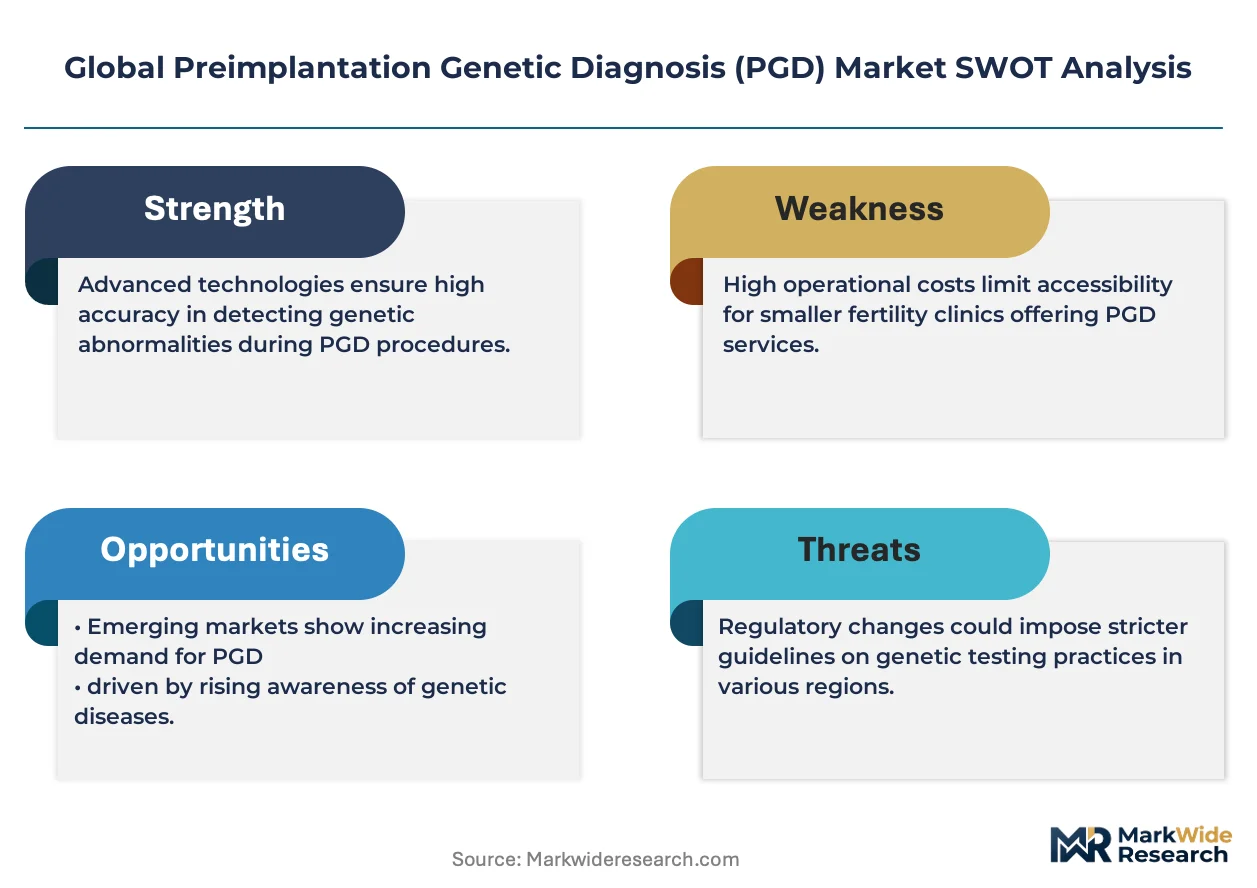
Regulatory frameworks, including oversight from the US FDA and the European Union's MDR, govern the approval and marketing of PGD test kits. In China, the NMPA sets stringent standards for clinical validation and laboratory certification. The key decision for providers now centers on balancing the adoption of advanced, high-cost sequencing technologies with evolving ethical guidelines and patient accessibility.
Market Dynamics
The maturation of Next-Generation Sequencing (NGS) is the central force redefining the PGD market. This shift expands diagnostic capabilities while creating new complexities in clinical implementation, data interpretation, and regulatory compliance.
Growth Catalysts
- NGS Maturation:Advancements in Next-Generation Sequencing offer higher throughput and accuracy for detecting aneuploidy and monogenic diseases, making PGD more reliable.
- Expanding Clinical Use:Demand from fertility centers is broadening to include comprehensive chromosomal screening as a standard part of many IVF protocols.
- Supportive Frameworks:Increased patient awareness and evolving ethical acceptance in the United States and China are encouraging wider clinical adoption.
Market Restraints
- Cost Barriers:The high cost of PGD, combined with the underlying IVF cycle, remains a significant financial barrier for patients, especially in regions lacking insurance reimbursement.
- Regulatory Fragmentation:Stringent oversight from bodies like the US FDA and China's NMPA creates a complex compliance landscape, increasing validation costs and time-to-market.
- Diagnostic Ambiguity:Embryonic mosaicism complicates diagnosis, as a biopsy may not represent the entire embryo, leading to difficult clinical decisions about implantation.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Latin America and Southeast Asia, where IVF services are growing, present expansion opportunities for established PGD providers.
- Non-Invasive Testing:Developing non-invasive PGT (niPGT) using cell-free DNA from blastocyst culture media offers a less invasive alternative to embryo biopsy.
- AI-Powered Analytics:Integrating artificial intelligence with NGS data can enhance the accuracy of embryo viability assessment and automate identification of chromosomal abnormalities.
Industry Challenges
- Specialized Talent Scarcity:A shortage of embryologists skilled in trophectoderm biopsy and geneticists proficient in NGS data interpretation limits the scalability of PGD services.
- Standardization Deficits:The absence of universal protocols for clinical validation and data reporting across labs hinders result comparability and quality assurance.
- Bioinformatics Burden:Managing massive datasets from NGS requires substantial investment in secure IT infrastructure, a challenge for smaller fertility clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Preimplantation Genetic Diagnosis (PGD) Market |
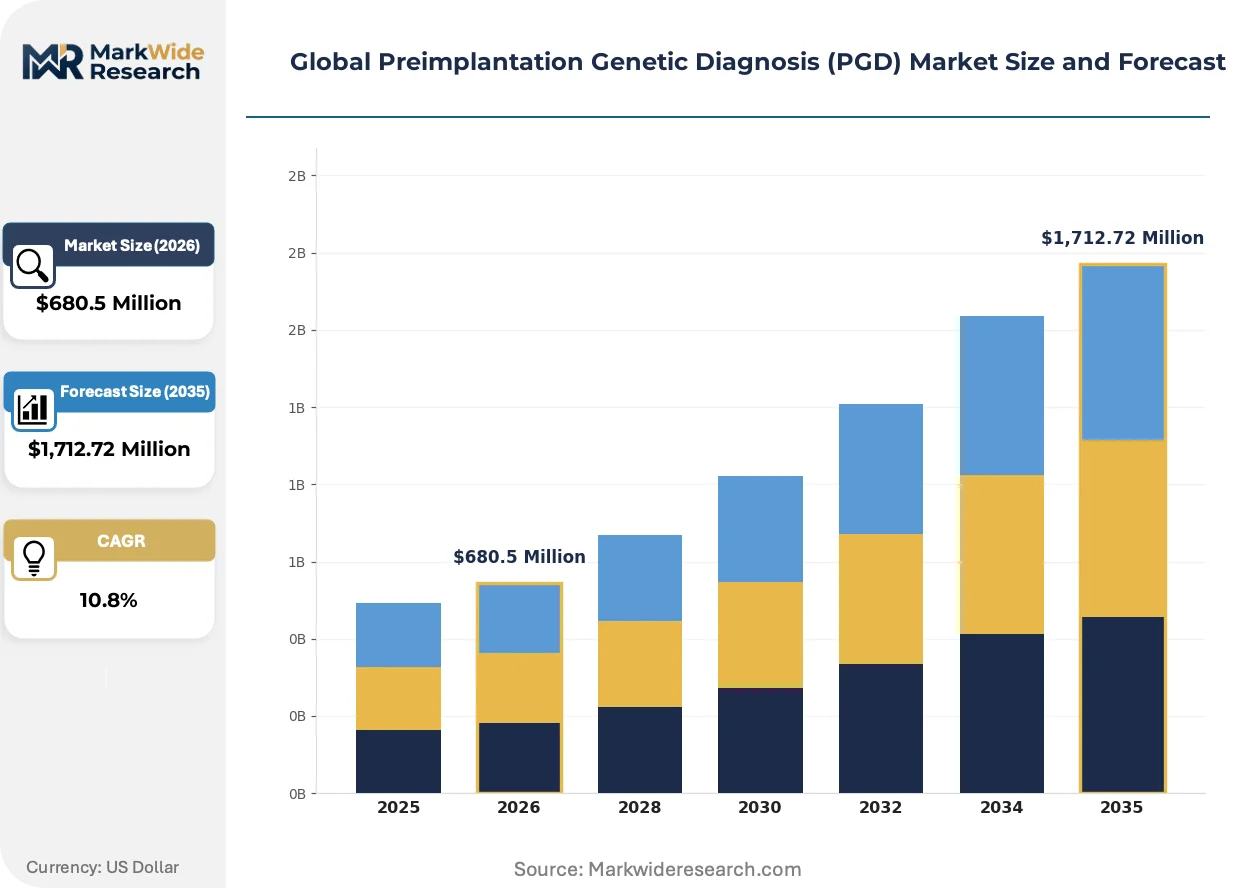
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,712.72 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Diagnostic Reagents, Scanning Devices, Imaging Systems, Software Tools Technology: Next-Generation Sequencing, Fluorescence In Situ Hybridization, Polymerase Chain Reaction, Comparative Genomic Hybridization, Microarray Analysis Application: Monogenic Disorders, Chromosomal Abnormalities, Sex Selection, Aneuploidy Screening, Balanced Translocations End User: Fertility Clinics, Genetic Counseling Centers, Research Laboratories, Specialty Hospitals, Assisted Reproduction Centers |
| Companies Covered | Natera, PerkinElmer, Illumina, Roche, Quest Diagnostics, Thermo Fisher Scientific, Agilent Technologies, BGI Genomics, The Cooper Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Preimplantation Genetic Diagnosis (PGD) Market Strategic Shifts & Innovations
Technological evolution is shifting preimplantation genetic diagnosis from a specialized, manual procedure toward a more integrated and data-centric component of standard fertility care. This transition prioritizes workflow efficiency and diagnostic consistency across clinical settings.
Integrated benchtop NGS systems combine sample prep, sequencing, and initial data analysis into one compact platform. Fertility clinics increasingly adopt these systems to perform PGD testing in-house rather than outsourcing. This trend is decentralizing diagnostic capabilities, bringing advanced genetic screening closer to the point of care.
The European Union's In Vitro Diagnostic Regulation (IVDR) is creating a more rigorous compliance environment. The regulation mandates that PGD test makers provide more extensive clinical evidence and performance data for CE marking. This shift impacts test kit developers, who face higher validation costs and longer approval timelines for market access in Europe.
A notable shift in clinic behavior involves moving from a la carte test ordering to adopting bundled solution contracts. These bundles include proprietary test kits, reagents, and analysis software tied to a specific hardware platform. This procurement model is most visible in high-volume markets like the United States, where large clinic networks prioritize workflow standardization.
Global Preimplantation Genetic Diagnosis (PGD) Market Segmentation
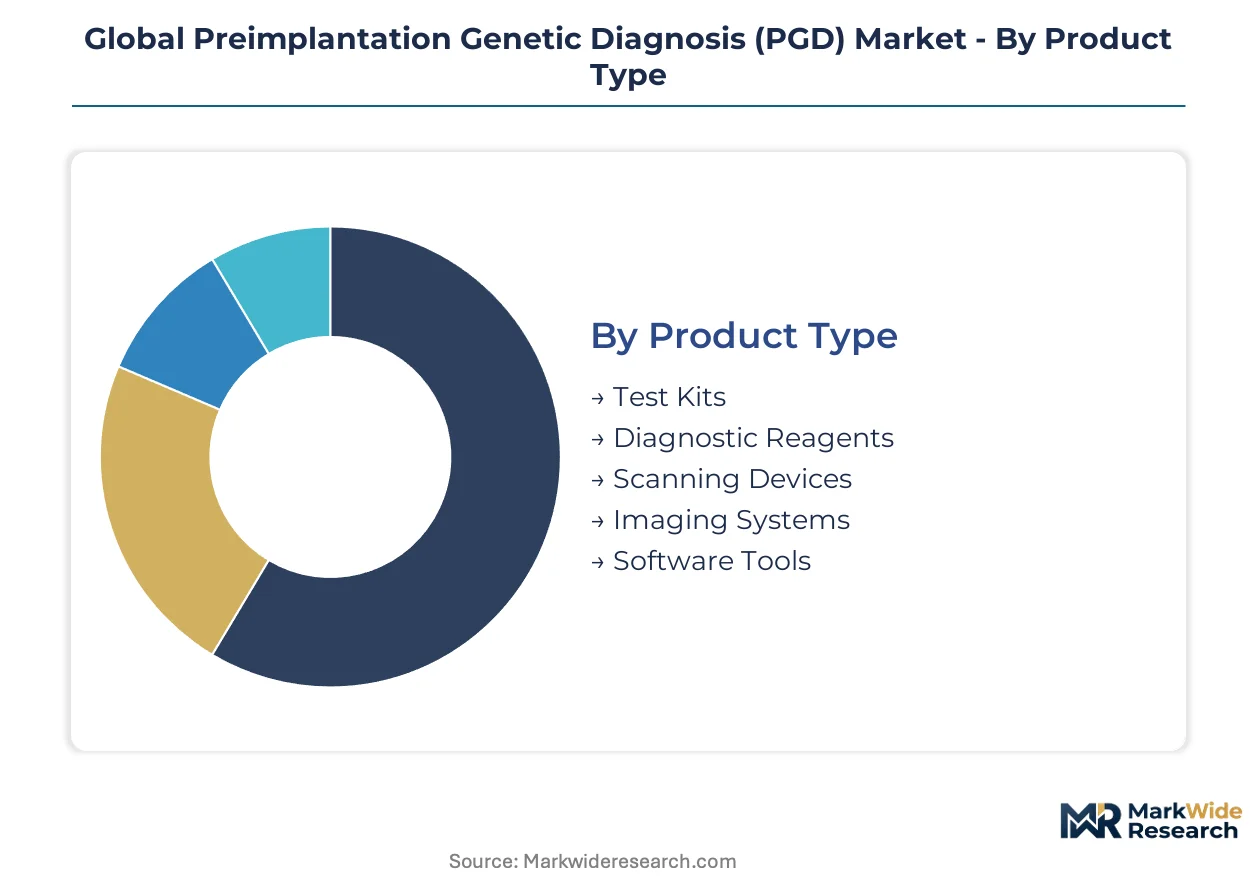
The Global Preimplantation Genetic Diagnosis market is segmented across key dimensions, reflecting diverse technological approaches, clinical applications, and end-user requirements. This granular analysis clarifies demand patterns and strategic positioning of solutions within fertility medicine. It illuminates where innovation and investment are most concentrated.
Product Type:
Buyer selection in the PGD market is significantly differentiated by the integration level and functionality offered by various product types, ranging from consumable kits to comprehensive software platforms.
- Test Kits:These contain reagents and consumables necessary for genetic analysis, often proprietary and bundled with specific instruments. Demand concentrates in high-volume fertility clinics in the United States, driven by the need for standardized, repeatable assays.
- Software Tools:Dedicated bioinformatics platforms manage and interpret complex sequencing data, often integrating with laboratory information systems. Growth is accelerating in specialized medical centers in China, as AI-powered analytics enhance embryo viability assessment.
- Diagnostic Reagents:Essential chemical components facilitate DNA extraction, amplification, and labeling processes during PGD testing.
- Scanning Devices:Specialized instruments are used for high-resolution imaging and analysis of embryonic cells or genetic material.
- Imaging Systems:These systems capture and process visual data from genetic samples, aiding in morphological assessment and quality control.
Volume sits with Test Kits; growth tilts toward Software Tools.
Technology:
The choice of PGD technology is primarily driven by the specific genetic anomaly targeted and the required diagnostic resolution, influencing clinical workflow and data interpretation.
- Next-Generation Sequencing:This high-throughput method sequences millions of DNA fragments simultaneously, offering superior accuracy for aneuploidy and monogenic disorder detection. Adoption is expanding within fertility clinics globally, driven by improved diagnostic capabilities and efficiency.
- Polymerase Chain Reaction:PCR amplifies specific DNA sequences, making it highly sensitive for detecting single-gene disorders and enabling rapid analysis. It remains a foundational technique in research laboratories for targeted genetic analysis.
- Fluorescence In Situ Hybridization:FISH uses fluorescent probes to detect specific chromosomal abnormalities, though it is being displaced by sequencing technologies.
- Comparative Genomic Hybridization:CGH identifies chromosomal gains or losses across the entire genome by comparing patient DNA to a reference.
- Microarray Analysis:This technique screens for genetic variations, including copy number variations, across many loci simultaneously.
Next-Generation Sequencing dominates new installations, while Polymerase Chain Reaction maintains utility for specific, rapid diagnoses.
Application:
PGD applications are defined by the specific patient needs and clinical objectives, ranging from preventing severe genetic diseases to improving IVF success rates.
- Aneuploidy Screening:This application identifies abnormal chromosome numbers in embryos, significantly improving implantation rates and reducing miscarriage risk in IVF cycles. It represents a primary use case in fertility clinics, especially for older maternal age patients.
- Monogenic Disorders:PGD for monogenic disorders detects specific single-gene mutations responsible for inherited conditions like cystic fibrosis or Huntington's disease. Demand is consistent in regions with high genetic disease prevalence, driven by family planning decisions.
- Sex Selection:This application allows for embryo selection based on sex, primarily for family balancing or preventing X-linked genetic disorders.
- Chromosomal Abnormalities:PGD identifies structural rearrangements in chromosomes, such as translocations or inversions, impacting embryo viability.
- Balanced Translocations:This specific application screens for embryos carrying balanced chromosomal translocations, which can lead to recurrent miscarriages.
Demand for Aneuploidy Screening remains robust, with Monogenic Disorders exhibiting significant expansion.
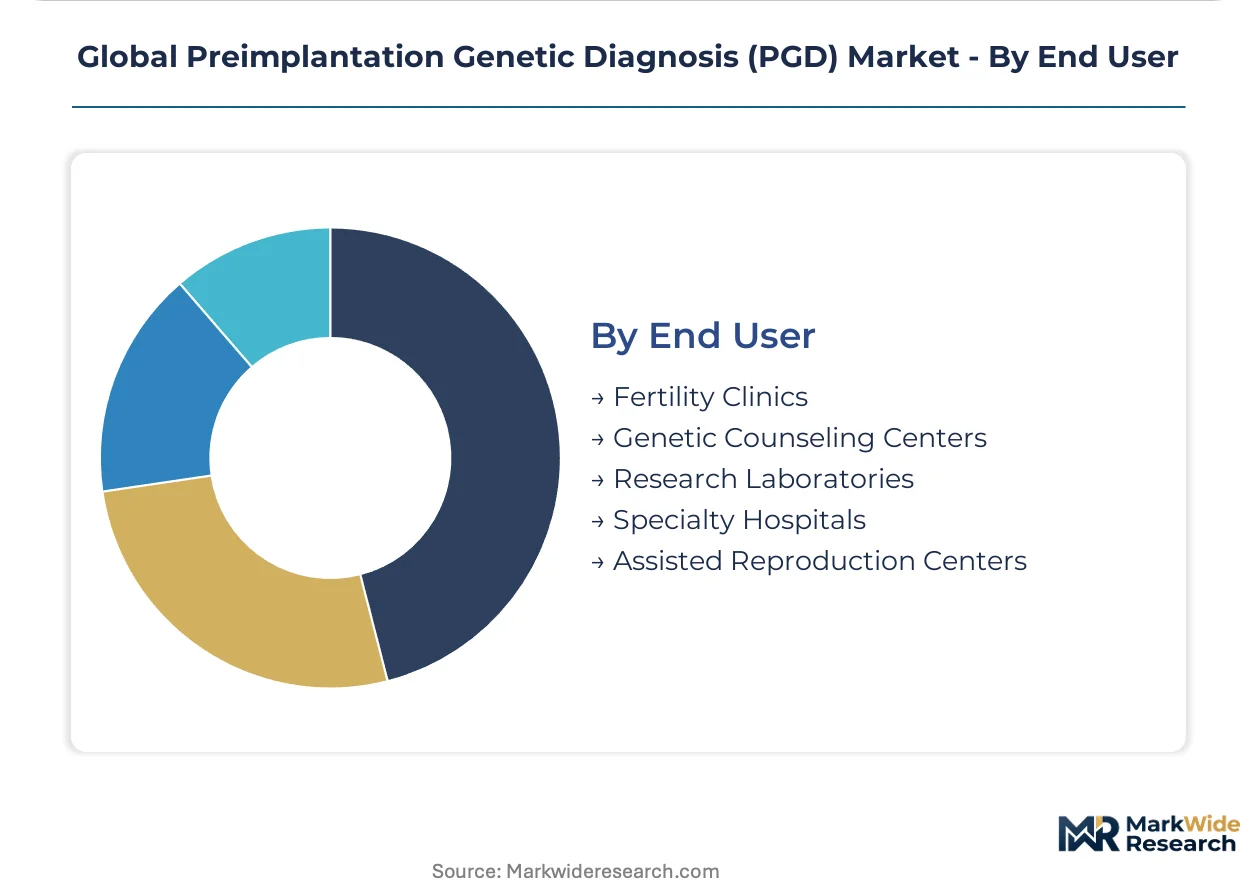
End User:
End-user segments are differentiated by their operational scale, patient volume, and the scope of genetic services they provide, from routine IVF to complex research.
- Fertility Clinics:These centers perform in-vitro fertilization and directly offer PGD services to patients seeking to prevent genetic conditions or improve IVF outcomes. They represent the largest customer base, particularly in the United States, due to expanding clinical use.
- Research Laboratories:These facilities focus on developing new PGD techniques, validating novel biomarkers, and understanding embryonic development. Investment in these labs is critical for advancing non-invasive testing and AI integration.
- Genetic Counseling Centers:These centers provide pre- and post-test consultation, helping patients understand PGD implications and results.
- Specialty Hospitals:Hospitals with advanced reproductive medicine departments integrate PGD into broader maternal-fetal health programs.
- Assisted Reproduction Centers:These centers offer a range of reproductive technologies, often including PGD as part of comprehensive care packages.
The largest patient volumes flow through Fertility Clinics, while Research Laboratories drive specialized development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of advanced medical research and clinical services in specific biotech hubs drives significant demand for Preimplantation Genetic Diagnosis globally. These regions benefit from established healthcare infrastructure and supportive regulatory environments for reproductive technologies. Such strategic concentrations accelerate both innovation and clinical adoption.
United States
Demand for aneuploidy screening and monogenic disorder detection remains robust across the United States. Regulatory oversight from the US FDA ensures product safety and efficacy for PGD test kits. Major biotech clusters in Boston and the San Francisco Bay Area continue to drive innovation in genetic diagnostics.
China
China's PGD market experiences substantial growth due to expanding fertility center services and rising patient awareness. The NMPA sets stringent standards for clinical validation and laboratory certification, impacting market access. Large medical centers in Shanghai and Beijing are rapidly adopting advanced NGS technologies for PGD.
Germany
German fertility clinics are increasingly integrating PGD into their IVF protocols, particularly for comprehensive chromosomal screening. The European Union's MDR governs the approval and marketing of PGD test kits, ensuring high safety standards. Research and development hubs in Munich and Heidelberg contribute to technological advancements in genetic analysis.
Japan
Japan exhibits consistent demand for PGD, especially for identifying monogenic disorders and chromosomal abnormalities. The PMDA oversees the approval of diagnostic devices and reagents, ensuring clinical reliability. Advanced fertility clinics in Tokyo and Osaka are at the forefront of implementing sophisticated PGD techniques.
Global Preimplantation Genetic Diagnosis (PGD) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the Global Preimplantation Genetic Diagnosis market. This market structure features a mix of large healthcare technology providers and niche diagnostic firms. Strategic archetypes include integrated platform providers and specialized service laboratories. Companies primarily engage in strategic partnerships and portfolio diversification to enhance their market presence.
Specialists in non-invasive screening, such as Natera, exemplify the innovation-driven segment focusing on cell-free DNA technologies. Integrated platform providers like Illumina occupy a significant position, leveraging their sequencing hardware dominance to offer comprehensive PGD solutions. Thermo Fisher Scientific, a broad portfolio provider, sits within the larger diagnostic instruments and reagents archetype. These players often differentiate through technological advancements and the breadth of their diagnostic offerings.
| Leading Market Players |
|---|
| Natera |
| PerkinElmer |
| Illumina |
| Roche |
| Quest Diagnostics |
| Thermo Fisher Scientific |
| Agilent Technologies |
| BGI Genomics |
| The Cooper Companies |
| Others |
Cost & Logistics Intelligence
Reagent synthesis costs directly influence the pricing of proprietary PGD test kits, impacting the final service fees charged by fertility clinics. This upstream cost component flows through to patient expenses, especially in regions without comprehensive insurance coverage for reproductive technologies.
Pricing Analysis
The high cost of PGD services presents a significant financial barrier for patients, particularly where insurance reimbursement is absent. Pricing models often combine per-unit transactional fees for test kits with bundled solution contracts for integrated platforms. Differentiation arises from NGS technology accuracy, brand reputation, and comprehensive software support. Fertility clinics prioritize workflow standardization, while individual patients exhibit high price sensitivity for out-of-pocket expenses.
Supply Chain Analysis
Direct-to-clinic distribution channels deliver integrated NGS systems and proprietary test kits to fertility centers globally. Supply concentration for advanced sequencing platforms and specialized reagents largely centers in the United States, with significant contributions from China and Germany for research and manufacturing. Key dependencies include custom sequencing chips and complex bioinformatics algorithms. A primary supply chain risk involves single-source vulnerability for highly specialized components and proprietary technologies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PGD market is evolving into a consolidation play, as stringent regulatory compliance and the high cost of advanced NGS technologies pressure smaller or less integrated providers. This environment favors established players with robust R&D and market access capabilities.
For Market Incumbents: Anchor existing market share by integrating AI-powered analytics into NGS platforms, enhancing embryo viability assessment accuracy. Expand into underpenetrated markets like Latin America and Southeast Asia, leveraging established IVF service growth. Address the scarcity of specialized talent through training programs for embryologists and geneticists. This strategy mitigates threats from emerging non-invasive testing solutions and strengthens regulatory compliance.
For New Entrants and Emerging Players: Enter via developing non-invasive PGT (niPGT) solutions using cell-free DNA from blastocyst culture media, offering a less invasive alternative. Target research laboratories and early-adopter fertility clinics seeking advanced, less burdensome diagnostic methods. Focus on specialized bioinformatics tools for complex NGS data interpretation, addressing the bioinformatics burden. This approach allows differentiation from established platform providers.
For Investors and Strategic Acquirers: Widespread insurance reimbursement for PGD services is the leading indicator that patient accessibility challenges are significantly reducing. The market demonstrates long-term viability over the next decade due to expanding IVF utilization and genetic health awareness. Target acquisition archetypes include companies specializing in AI-powered analytics for NGS data or developers of novel non-invasive PGT technologies. Monitor regulatory shifts in emerging markets for early expansion opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-Powered Analytics | Enhances embryo viability assessment and accelerates chromosomal abnormality identification. |
| Develop Non-Invasive PGT (niPGT) | Offers a less invasive alternative, reducing risks associated with embryo biopsy. |
| Expand into Underpenetrated Markets | Captures new patient populations in regions with growing IVF services. |
| Invest in Regulatory Compliance | Ensures market access and builds trust in regions with stringent oversight. |
| Strategic Partnerships with Fertility Clinics | Facilitates workflow standardization and broadens direct patient reach for PGD services. |
Research Approach
Independent corroboration across fertility clinic directors, genetic counselors, and NGS platform engineers underwrites the qualitative findings. Primary interviews with regulatory affairs specialists provided critical market insights. Secondary validation involved extensive review of US FDA filings, EU MDR guidance documents, and NMPA clinical validation reports. This approach combined top-down market sizing with bottom-up segment analysis.
Historical market performance across comparable periods anchors the forecast framework for the PGD market. The analytical model integrates segmentation across product type, technology, application, end-user, and regional regulatory variations. Compound annual growth rates derive from historical market trends, technological adoption rates, and evolving clinical practice. Key inputs include IVF cycle volumes and genetic disorder prevalence rates over the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or rapid technological advancements. The projections reflect current market dynamics and assumptions regarding patient accessibility and clinical adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market