
 Apoptosis Market | 2026-2036
Apoptosis Market Size, Share, and Industry Trends Forecast 2026-2036
Apoptosis Market Outlook
Buyer concentration among pharmaceutical companies is repositioning procurement leverage toward large oncology developers with integrated discovery platforms. Thermo Fisher Scientific leverages its reagent-to-instrument portfolio to anchor workflow bundling across top-twenty drug developers. Bio-Techne Corporation specializes in high-affinity antibody supply chains that sustain margin pools in the monoclonal antibodies segment. Danaher Corporation dominates analytical instrumentation placement in contract research organizations serving apoptosis-focused drug programs.
Apoptosis denotes programmed cell death executed through caspase cascades, mitochondrial outer membrane permeabilization, and receptor-mediated signaling pathways, with Bcl-2 family proteins and cytochrome c release serving as quantifiable functional parameters. The process enables targeted elimination of malignant or damaged cells, forming the mechanistic basis for both cancer therapeutics and tissue homeostasis research. Monoclonal antibodies command the largest revenue share among product types due to validated clinical pathways in oncology, while gene therapies attract the fastest development velocity as CRISPR-directed apoptosis modulation enters Phase I portfolios. The therapy area dimension shows oncology as the mature revenue base and immunology as the emerging expansion vector, with checkpoint inhibitor combination trials redirecting apoptosis assay demand toward multiplexed biomarker readouts.
The FDA and EMA enforce divergent evidentiary thresholds for cell-death mechanism validation in oncology submissions, with the FDA emphasizing patient survival endpoints and the EMA requiring deeper pharmacodynamic biomarker justification. ISO 15189 accreditation standards for clinical diagnostic laboratories further constrain assay reproducibility claims in hospital-based apoptosis testing. Stakeholders must monitor how regulatory divergence between Washington and Brussels reshapes trial location strategy and companion diagnostic co-development timelines.
Market Dynamics
Pharmaceutical procurement consolidation is compressing vendor margins and forcing reagent suppliers to bundle instrumentation, consumables, and bioinformatics into multi-year platform contracts.
Growth Catalysts
- CRISPR-directed apoptosis modulation:Gene-editing platforms enable precise caspase pathway targeting, accelerating preclinical validation timelines for oncology developers.
- FDA survival endpoint requirements:The agency's emphasis on overall survival data in oncology submissions drives demand for longitudinal apoptosis biomarker monitoring in Phase III trials.
- Boston-San Francisco corridor concentration:Academic-industry partnerships in these clusters generate sustained preclinical throughput for assay reagent procurement.
Market Restraints
- High-affinity antibody input costs:Recombinant protein production and hybridoma maintenance create persistent margin pressure for diagnostic manufacturers.
- ISO 15189 accreditation timelines:Clinical diagnostic laboratories face 12-18 month certification cycles that delay commercial assay deployment.
- Small-molecule substitution threat:Bcl-2 inhibitor chemistry advances in medicinal chemistry programs divert R&D budgets from biologic apoptosis modulators.
Strategic Opportunities
- Immunology expansion vector:Checkpoint inhibitor combination trials redirect assay demand toward multiplexed biomarker readouts in immuno-oncology.
- EMA pharmacodynamic biomarker mandates:The agency's deeper mechanistic justification requirements create service revenue pools for CROs with specialized cell-death analytics.
- Gene therapy manufacturing convergence:Viral vector production and apoptosis assay workflows are integrating into unified GMP facility designs.
Industry Challenges
- Caspase assay standardization gaps:Inter-laboratory variability in fluorometric readouts complicates cross-trial data pooling for regulatory submissions.
- Multiplex platform integration complexity:Legacy flow cytometry infrastructure requires costly retrofitting to accommodate high-content imaging systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apoptosis Market |
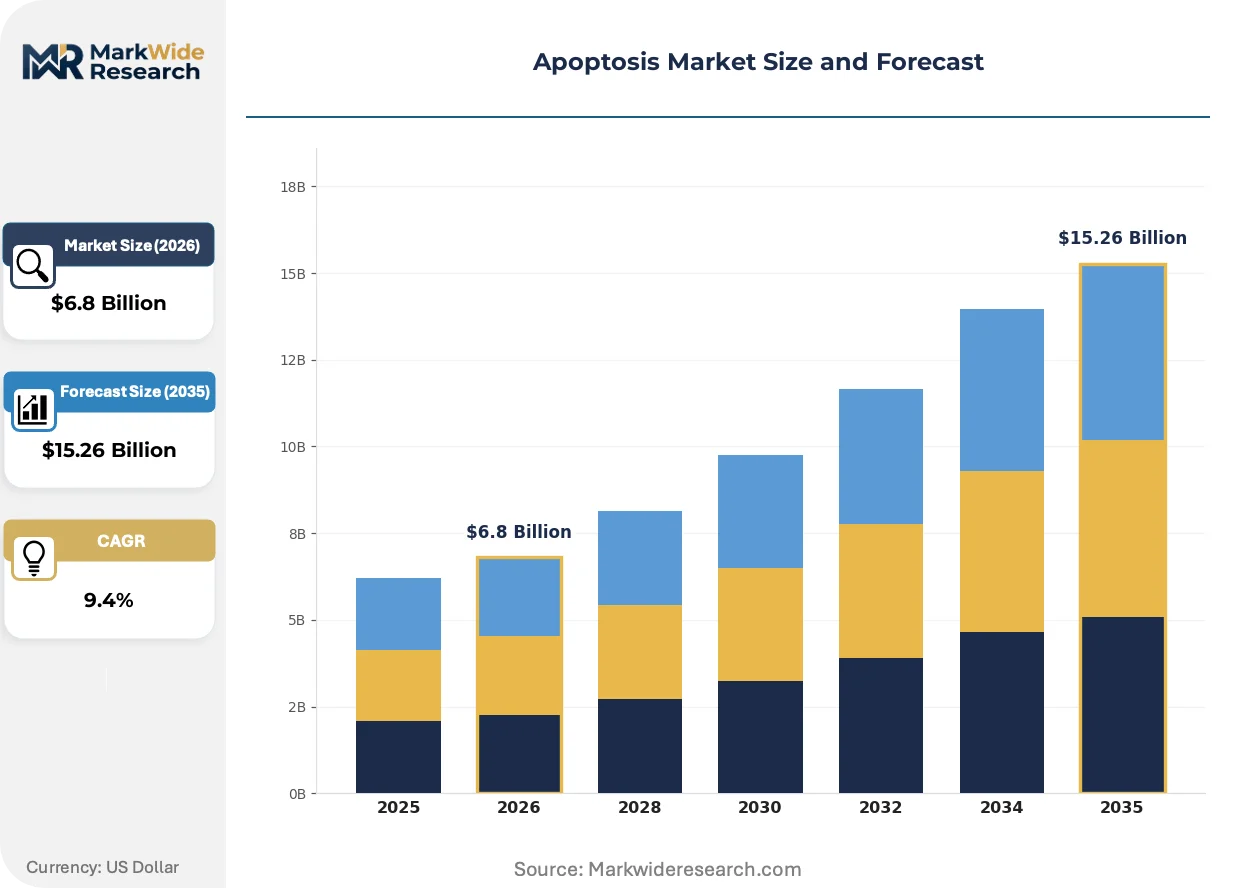
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Biologicals, Gene Therapies Therapy Area: Oncology, Neurology, Immunology, Cardiovascular End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Hospitals Application: Drug Development, Diagnostics, Therapeutic Intervention, Clinical Trials |
| Companies Covered | Bio-Rad Laboratories, Abcam plc, Thermo Fisher Scientific Inc., Danaher Corporation, Sartorius AG, Merck KGaA, Promega Corporation, Bio-Techne Corporation, Becton, Dickinson and Company (BD), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apoptosis Market Strategic Shifts
Workflow automation and AI-assisted image analysis are compressing assay turnaround times while regulatory divergence between Washington and Brussels reshapes trial location strategy.
High-content imaging systems with machine learning classification are overtaking traditional flow cytometry for apoptosis quantification in drug screening. Large oncology developers with integrated discovery platforms are adopting these platforms at 18-month replacement cycles. The technology is overtaking manual gating protocols and reducing per-sample analysis time from hours to minutes.
EMA's pharmacodynamic biomarker justification requirements are tightening evidence standards for cell-death mechanism validation in oncology submissions. The regulation forces sponsors to invest in longitudinal biomarker strategy earlier in development. Combination therapy trials in Europe are responding by embedding multiplexed apoptosis readouts into adaptive trial designs.
Academic medical centers are consolidating reagent procurement through shared-service organizations that negotiate multi-year supply agreements. The distributor channel faces disintermediation as these centers establish direct relationships with manufacturers. This pattern is most visible in the United States, where hospital system mergers have created regional purchasing consortia with substantial volume leverage.
Apoptosis Market Segmentation
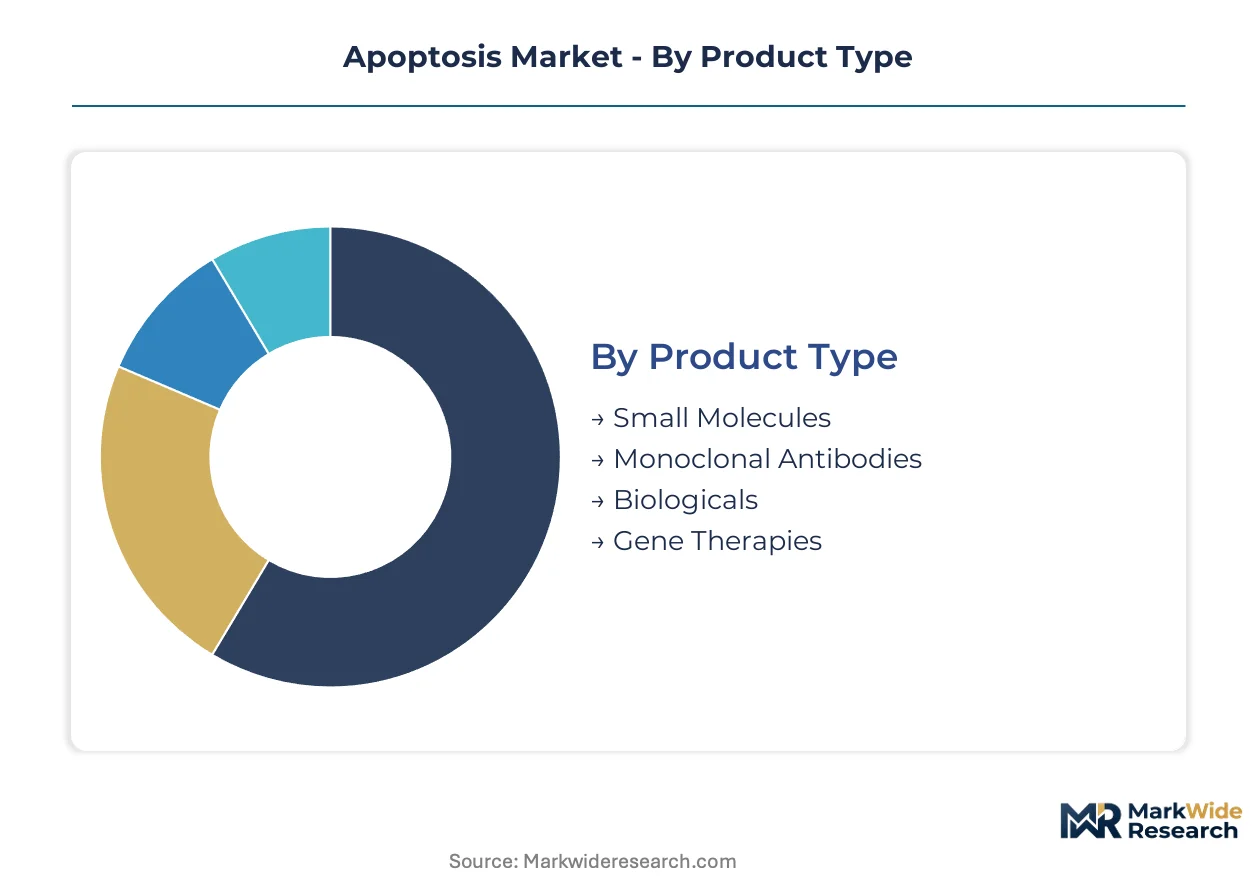
Apoptosis market segmentation reveals divergent procurement patterns across therapeutic modalities and end-use settings. Pharmaceutical buyers prioritize validated clinical pathways in oncology while research institutions drive preclinical assay demand through specialized reagent procurement.
Product Type:
Procurement leverage concentrates around clinical validation status and manufacturing scalability rather than molecular class alone.
- Monoclonal Antibodies:High-affinity binding domains targeting Bcl-2 family proteins and death receptors enable quantifiable pharmacodynamic readouts. Large oncology developers with integrated discovery platforms in Boston and San Francisco anchor sustained procurement volumes for checkpoint inhibitor combination trials.
- Gene Therapies:CRISPR-directed caspase pathway modulation delivers precise apoptotic control through viral vector delivery systems. Preclinical validation timelines compress as Phase I portfolios expand, redirecting R&D budgets toward viral vector manufacturing convergence with assay workflows.
- Small Molecules:Bcl-2 inhibitor chemistry advances in medicinal chemistry programs sustain established revenue pools.
- Biologicals:Recombinant protein production and hybridoma maintenance create persistent margin pressure for diagnostic manufacturers.
Volume sits with Monoclonal Antibodies; growth tilts toward Gene Therapies.
Therapy Area:
Maturity gradients across disease categories determine assay specification requirements and regulatory pathway complexity.
- Oncology:Programmed cell death execution through caspase cascades and mitochondrial outer membrane permeabilization forms the mechanistic foundation for cancer therapeutics. FDA survival endpoint requirements drive longitudinal biomarker monitoring in Phase III trials, sustaining demand for multiplexed readouts.
- Immunology:Checkpoint inhibitor combination trials redirect apoptosis assay demand toward multiplexed biomarker panels. EMA pharmacodynamic biomarker mandates create service revenue pools for CROs with specialized cell-death analytics in adaptive trial designs.
- Neurology:Neuronal apoptosis mechanisms in neurodegenerative conditions attract preclinical research investment.
- Cardiovascular:Ischemia-reperfusion injury applications drive specialized assay development for cardiac tissue models.
Oncology commands installed base; Immunology shows steepest expansion trajectory.
End User:
Customer scale and integration depth separate platform contract opportunities from transactional reagent sales.
- Pharmaceutical Companies:Procurement consolidation among large oncology developers compresses vendor margins and forces multi-year platform contracts bundling instrumentation, consumables, and bioinformatics. Thermo Fisher Scientific and Danaher Corporation anchor workflow placement through reagent-to-instrument portfolios.
- Research Institutions:Academic-industry partnerships in Boston and San Francisco generate sustained preclinical throughput for assay reagent procurement. Shared-service organizations negotiate multi-year supply agreements, disintermediating traditional distributor channels.
- Biotechnology Firms:Specialized discovery platforms prioritize high-affinity antibody supply chains for monoclonal antibody development.
- Hospitals:ISO 15189 accreditation timelines constrain clinical diagnostic laboratory deployment of apoptosis testing protocols.
Pharmaceutical Companies dominate contract value; Research Institutions drive volume fragmentation.
Application:
Development stage and evidentiary requirements determine analytical platform specifications and regulatory submission strategies.
- Drug Development:High-content imaging systems with machine learning classification overtake traditional flow cytometry for apoptosis quantification in screening workflows. Large oncology developers adopt these platforms at accelerated replacement cycles, reducing per-sample analysis time substantially.
- Clinical Trials:FDA and EMA divergent evidentiary thresholds for cell-death mechanism validation reshape trial location strategy and companion diagnostic co-development timelines. Longitudinal biomarker strategy investment shifts earlier in development cycles.
- Diagnostics:Caspase assay standardization gaps complicate cross-trial data pooling for regulatory submissions.
- Therapeutic Intervention:GMP facility designs increasingly integrate viral vector production with apoptosis assay workflows.
Drug Development absorbs capital expenditure; Clinical Trials capture service revenue expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant protein production facilities in Massachusetts and California anchor North American supply chains for apoptosis-modulating reagents. Academic medical centers in these clusters generate concentrated preclinical demand for high-affinity antibodies and caspase assay platforms.
United States
FDA survival endpoint requirements drive longitudinal biomarker monitoring in Phase III oncology trials across Boston and San Francisco academic-industry partnerships. The agency's emphasis on overall survival data compresses assay validation timelines for drug developers. Shared-service organizations in these metropolitan clusters negotiate multi-year reagent supply agreements, disintermediating traditional distributor channels.
Germany
EMA pharmacodynamic biomarker mandates create service revenue pools for contract research organizations with specialized cell-death analytics. REACH compliance obligations for research-grade chemicals constrain reagent import workflows from non-EU suppliers. The Heidelberg-Munich corridor concentrates preclinical apoptosis research infrastructure, with Max Planck Institute spin-offs driving assay innovation.
United Kingdom
MHRA post-Brexit divergence from EMA evidentiary standards complicates pan-European trial design for apoptosis-targeted therapies. The UK Biobank's longitudinal tissue collections enable retrospective apoptosis biomarker validation in oncology cohorts. Cambridge-London life science clusters attract CRISPR-directed apoptosis modulation startups seeking proximity to Wellcome Trust funding mechanisms.
Japan
PMDA's emphasis on pharmacokinetic bridging studies for Western-developed apoptosis modulators extends regulatory timelines for multinational sponsors. METI's healthcare innovation subsidies support domestic development of high-content imaging systems for drug screening. The Kansai region's Osaka-Kobe biomedical corridor hosts specialized CROs serving Asia-Pacific apoptosis assay demand.
Switzerland
Swissmedic's accelerated assessment pathway for orphan oncology indications attracts apoptosis-targeted gene therapy developers to Basel-Zurich. The country's bilateral mutual recognition agreements with FDA and EMA streamline multi-jurisdictional submission strategies. Roche and Novartis legacy infrastructure sustains specialized supplier ecosystems for Bcl-2 inhibitor chemistry programs.
Apoptosis Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue CRISPR-directed gene therapy platforms and AI-assisted image analysis workflows. The vendor base stratifies across three tiers: diversified life science conglomerates with reagent-to-instrument portfolios, specialized antibody manufacturers with hybridoma capabilities, and niche analytical instrumentation providers. Consolidation pressure from pharmaceutical procurement bundling favors players with integrated workflow offerings. Dominant competitive moves include multi-year platform contract negotiations and backward integration into recombinant protein production.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation anchor workflow placement through captive supply of consumables and instrumentation. Bio-Techne Corporation exemplifies the specialized antibody manufacturer archetype, occupying a position sustained by high-affinity binding domain expertise. These three entities represent the competitive structure: scale-driven bundling, precision reagent specialization, and analytical platform dominance.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Abcam plc |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Sartorius AG |
| Merck KGaA |
| Promega Corporation |
| Bio-Techne Corporation |
| Becton, Dickinson and Company (BD) |
| Others |
Value Chain & Pricing Dynamics
Large oncology developers with integrated discovery platforms command procurement leverage that compresses vendor margins and forces reagent suppliers toward multi-year platform contracts bundling instrumentation, consumables, and bioinformatics. This buyer concentration shapes a contract-based pricing structure where volume commitments determine access to premium service tiers.
Pricing Analysis
Volume concentrates in monoclonal antibodies while margins pool in gene therapy reagents. Pricing stratifies across premium, standard, and economy tiers based on clinical validation status and ISO 15189 certification level. Cost compression in the biologicals segment is intensifying because recombinant protein production and hybridoma maintenance create persistent input cost pressure. Research institutions exhibit highest price sensitivity due to shared-service organization negotiations, whereas pharmaceutical companies prioritize workflow integration over unit cost.
Supply Chain Analysis
Regional distribution centers in Massachusetts and California anchor North American hub-and-spoke patterns for apoptosis-modulating reagents. Manufacturing concentration rests on the United States, Germany, and Switzerland for high-affinity antibodies and analytical instrumentation. Supply chains draw from recombinant protein production facilities, viral vector manufacturing sites, and hybridoma maintenance operations. Single-source vulnerability around CRISPR-directed caspase pathway reagents creates exposure to academic spin-off supplier consolidation. Distribution runs through direct manufacturer relationships with hospital purchasing consortia and pharmaceutical procurement departments, disintermediating traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The apoptosis market sits in a technology-transition phase as high-content imaging systems with machine learning classification displace legacy flow cytometry for quantification workflows. This displacement is compressing assay turnaround times and reshaping platform replacement cycles.
For Market Incumbents: Extend reagent-to-instrument portfolio bundling to capture multi-year platform contracts before CRISPR-directed gene therapy platforms mature. Deepen backward integration into recombinant protein production to defend margin pools against hybridoma cost pressure. Prioritize ISO 15189 certification investment to maintain clinical diagnostic laboratory access against emerging entrants lacking accreditation infrastructure.
For New Entrants and Emerging Players: Begin with immuno-oncology multiplexed biomarker panels where checkpoint inhibitor combination trials redirect assay demand toward specialized readouts. Target academic-industry partnerships in the Boston-San Francisco corridor for preclinical throughput validation. Pursue a service-revenue-first go-to-market angle embedding cell-death analytics into adaptive trial designs for European sponsors facing EMA pharmacodynamic biomarker mandates.
For Investors and Strategic Acquirers: The window for entry favors specialized antibody manufacturers with hybridoma capabilities and established high-affinity binding domain expertise. Long-term viability hinges on gene therapy manufacturing convergence with apoptosis assay workflows over the next decade. Watch CRISPR-directed apoptosis modulation Phase I portfolio expansion as the inflection signal for platform technology displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA survival endpoint requirements compress assay validation timelines for Phase III oncology programs. |
| Regulatory Approval Pathway | EMA pharmacodynamic biomarker mandates create service revenue pools for CROs with specialized analytics. |
| Manufacturing Scale-Up | Viral vector production and apoptosis assay workflows integrate into unified GMP facility designs. |
| Backward Integration | Recombinant protein production and hybridoma maintenance anchor captive supply for margin defense. |
| Pipeline Diversification | Immunology expansion vectors redirect R&D budgets from oncology toward checkpoint inhibitor combinations. |
Study Parameters
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings. Primary interviews with these stakeholders combined secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up segment sizing and top-down market reconciliation anchored the analytical framework.
Comparable-period anchoring to historical reference periods established the forecast window trajectory. The projection horizon spans product type, therapy area, end user, and application dimensions alongside regional regulatory cluster segmentation. CAGRs derived from modeled adoption curves for high-content imaging systems and CRISPR-directed platforms. Forecast inputs incorporated longitudinal biomarker monitoring intensity and platform replacement cycle compression.
Underlying measurement precision varies by segment; monoclonal antibodies and oncology applications carry tighter precision than emerging gene therapy modalities. Forecasts reflect documented assumptions around regulatory divergence persistence and academic-industry partnership throughput. Apoptosis assay standardization gaps and inter-laboratory variability in fluorometric readouts could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market