
 Antibody Fragments Market | 2026-2036
Antibody Fragments Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Fragments Market Intelligence
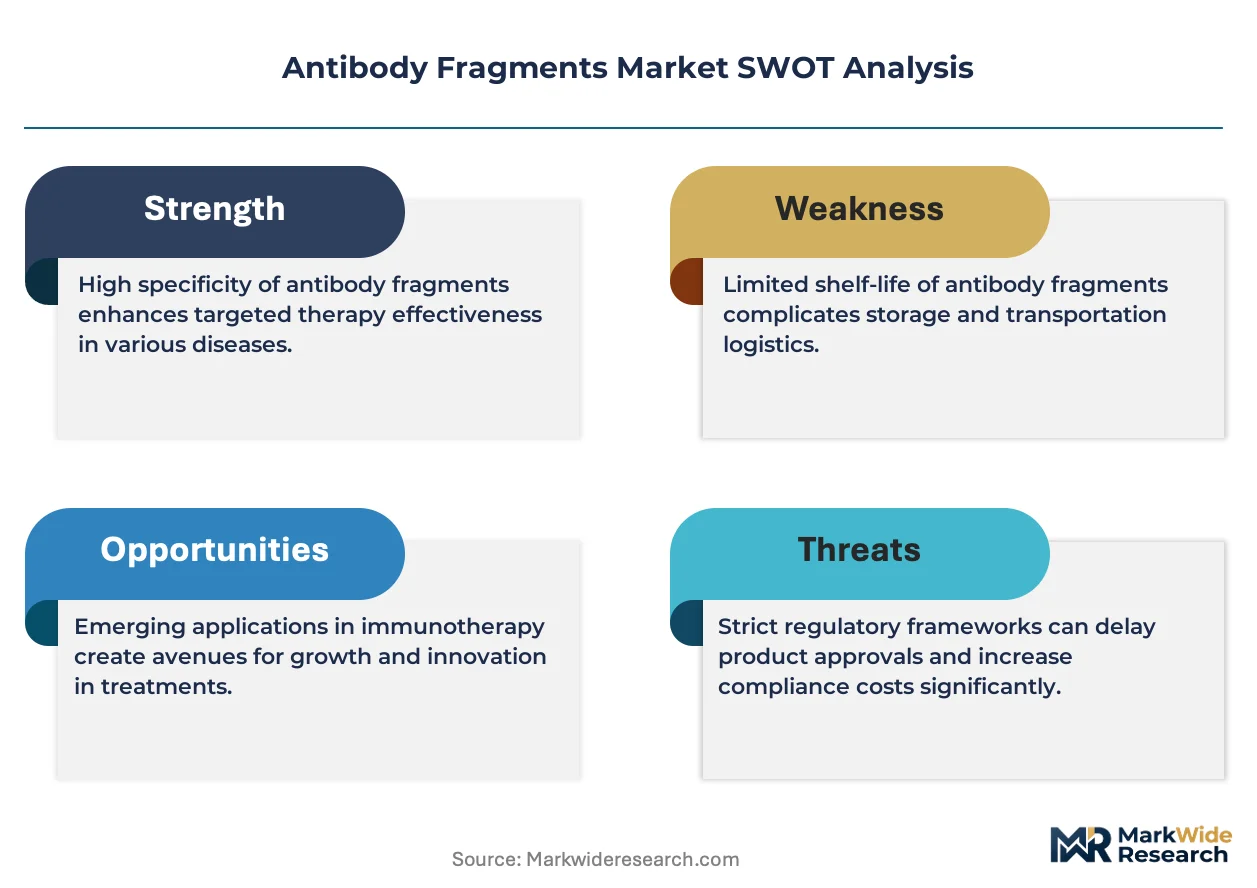
A capital-intensity divergence between fully integrated biopharmaceutical conglomerates and specialized fragment engineering boutiques is bifurcating competitive returns in antibody fragments. F. Hoffmann-La Roche AG leverages its Basel-based biologics manufacturing network to sustain captive supply chains for Fc-fusion programs. Ablynx competes through alpaca-derived single-domain antibody specialization, while Genentech, Inc. anchors its position via humanized fragment platforms developed in South San Francisco.
Antibody fragments are recombinant protein derivatives of immunoglobulins—typically Fab, ScFv, or sdAb constructs—that retain antigen-binding specificity without the full Fc-mediated effector functions of intact antibodies, enabling renal clearance tuning and solid tumor penetration. Their primary commercial purpose centers on targeted therapeutics where molecular weight constraints dictate dosing frequency or tissue accessibility. Fab segments currently lead revenue contribution due to established manufacturing templates and biosimilar compatibility, while sdAb formats represent the fastest-expanding margin pool as camelid-derived stability profiles open CNS and intraocular delivery modes previously inaccessible to conventional monoclonal architectures.
FDA biologics license application requirements and EMA's Committee for Medicinal Products for Human Use guidelines dictate immunogenicity testing thresholds that fragment developers must clear before Phase III entry, effectively filtering out undercapitalized entrants. ISO 10993 biocompatibility standards and ICH Q5D cell substrate qualifications further constrain which expression systems—mammalian versus microbial—gain traction for commercial-scale fragment production. Stakeholders must monitor how CRISPR-edited CHO cell lines and continuous bioprocessing technologies reshape cost structures before committing to platform investments.
Market Dynamics
Continuous bioprocessing technologies are compressing cost structures for fragment manufacturing while FDA and EMA accelerated approval pathways compress development timelines, creating a dual squeeze that favors capitalized incumbents with captive CHO cell line infrastructure over boutique engineering shops dependent on contract manufacturing organizations.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway compresses Phase II-to-approval timelines for fragment-based oncology therapeutics, pulling forward revenue recognition for developers with existing biologics license application experience.
- Camelid-derived single-domain antibodies:Their thermal stability and reduced molecular weight unlock intraocular and CNS delivery routes previously inaccessible to conventional monoclonal architectures, opening new therapeutic verticals.
- Japan's PMDA Sakigake designation:The priority review system accelerates market entry for first-in-class fragment therapeutics, concentrating early-adopter demand in Tokyo-Osaka clinical trial corridors.
Market Restraints
- Mammalian expression system concentration:CHO cell substrate dependence creates input cost volatility when serum supply tightens, squeezing gross margins for non-vertically integrated developers.
- ICH Q5D qualification barriers:The cell substrate documentation requirements filter out undercapitalized entrants before Phase III entry, structurally limiting the competitive pool.
- Peptide-drug conjugate substitution:Smaller synthetic alternatives threaten fragment positioning in solid tumor penetration applications where manufacturing simplicity outweighs binding affinity advantages.
Strategic Opportunities
- India's CDSCO fast-track pathway:The abbreviated approval route for biologics developed elsewhere creates a white space for post-approval manufacturing partnerships serving South Asian demand.
- CRISPR-edited CHO platforms:Convergence of gene editing with continuous perfusion bioprocessing promises 40-60% cost reduction in fragment production, enabling price competition with biosimilars.
- Direct-to-specialist distribution:Bypassing wholesale distributors to ship temperature-controlled fragment doses directly to academic medical center pharmacies reduces cold-chain failure risk and capture margin.
Industry Challenges
- Bioprocess engineering talent scarcity:The specialized skill set spanning perfusion cell culture and downstream purification bottlenecks capacity expansion at mid-scale facilities.
- ISO 10993 biocompatibility testing backlog:Certification timeline extension for novel fragment formats delays Phase I initiation, burning runway for cash-constrained developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Fragments Market |
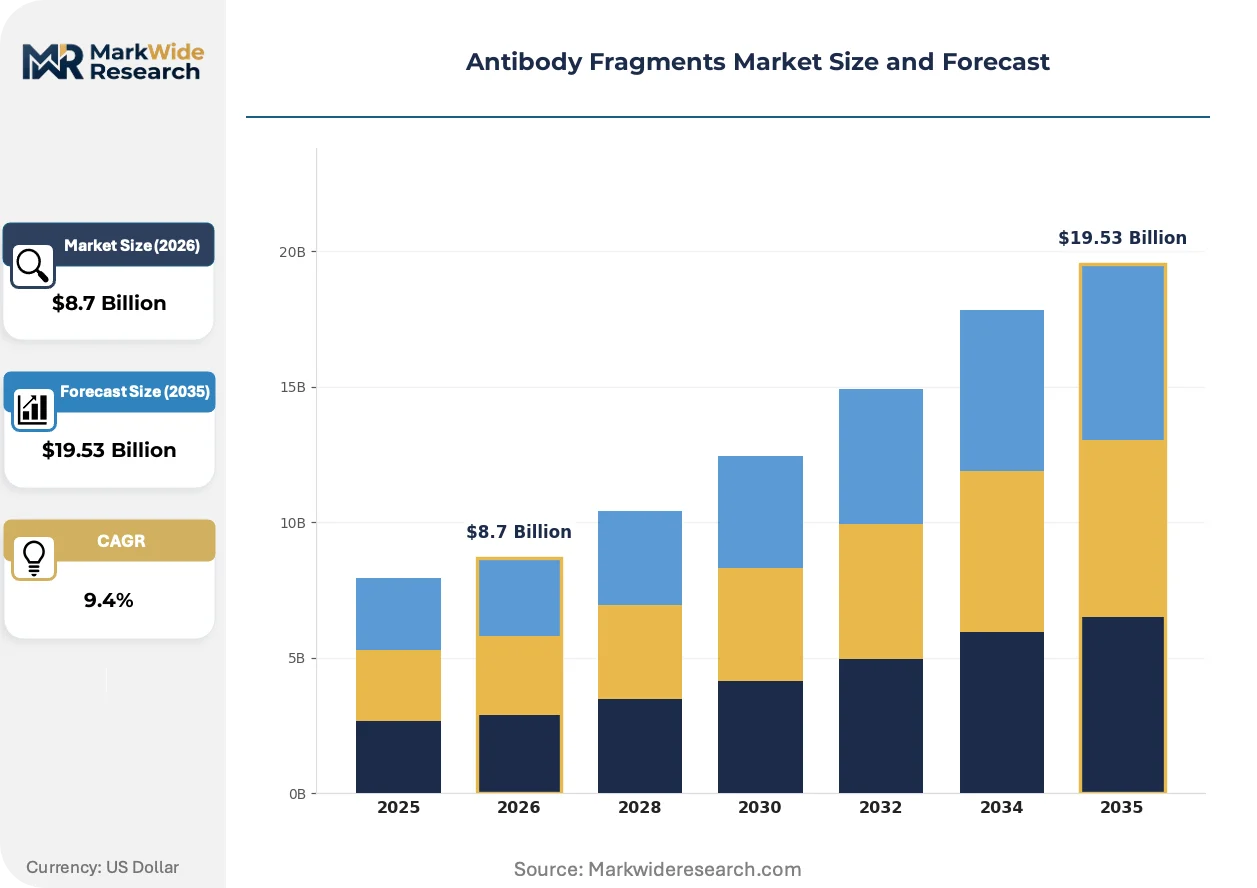
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fab, ScFv, sdAb, Fc Fragment Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Cardiovascular Diseases Delivery Mode: Injectable, Oral, Topical, Intranasal End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Contract Manufacturing Organizations |
| Companies Covered | Amgen Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche AG, Genentech, Inc., Johnson & Johnson, AbbVie Inc., Pfizer Inc., Ablynx, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Fragments Market Strategic Shifts & Innovations
Expression platform diversification is fragmenting established manufacturing paradigms. Microbial systems, yeast platforms, and plant-based production are eroding mammalian cell culture dominance as developers chase cost and speed advantages for non-glycosylated fragment formats.
Continuous perfusion bioprocessing is fragmenting batch manufacturing economics. Perfusion systems enable higher cell densities and real-time harvest, cutting facility footprint requirements by half. Genentech and Roche anchor their Basel-South San Francisco manufacturing networks around this technology, forcing contract manufacturers to retool or exit fragment production. The shift compresses capital intensity thresholds, privileging conglomerates with existing stainless-steel infrastructure over greenfield entrants.
EMA's revised biosimilar guidance for monoclonal fragments tightens immunogenicity comparability thresholds. The regulation forces originator developers to lock analytical methods earlier in development, raising documentation burdens but extending market exclusivity for reference products. Fab-format therapeutics face the steepest compliance adjustment in Germany, where the Paul-Ehrlich-Institut enforces the most stringent interpretation.
Academic medical centers are consolidating fragment procurement through centralized pharmacy committees. The buying-pattern shift displaces individual principal-investigator purchasing autonomy with formulary-driven standardization, compressing vendor count per institution. This concentration is most visible in the United States, where NCI-designated cancer centers negotiate multi-year supply agreements locking in manufacturing slots and pricing tiers.
Antibody Fragments Market Segmentation
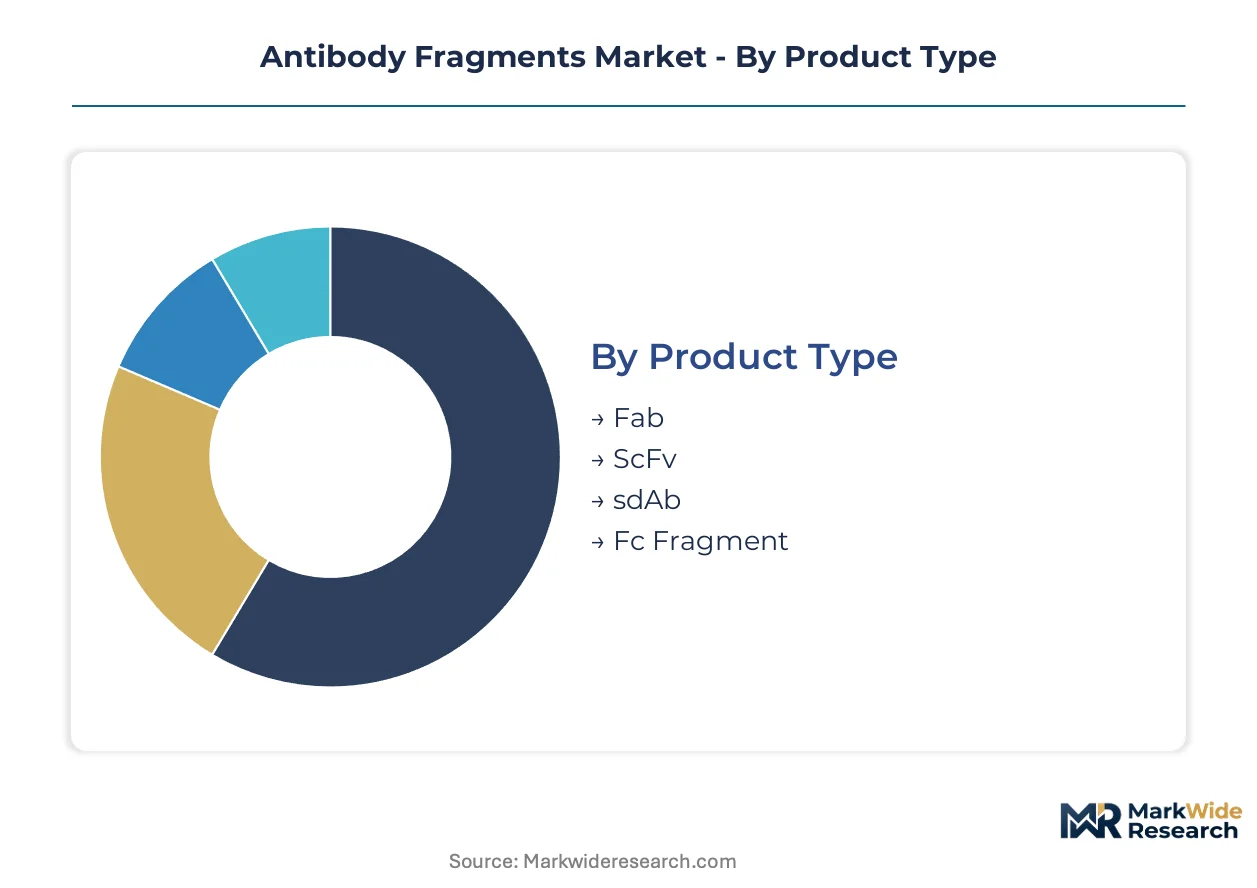
Fragment developers must align platform investments with where substitution pressure and regulatory scrutiny concentrate most intensely. Segmentation reveals which formats face peptide-drug conjugate displacement versus where manufacturing moats protect margin.
Product Type:
Substitution pressure from synthetic alternatives varies sharply by molecular weight and glycosylation requirements, with smaller formats most exposed to peptide-drug conjugate encroachment.
- Fab:These antigen-binding fragments retain the full variable and first constant domains of heavy and light chains, typically 50-55 kDa. Manufacturing templates are mature in Basel and South San Francisco, where Roche and Genentech leverage established CHO infrastructure. Demand concentrates in oncology infusion centers where effector function modulation matters less than tissue penetration. Fab segments face moderate substitution pressure from bispecific constructs in solid tumor applications.
- sdAb:Single-domain antibodies derived from camelid heavy-chain-only immunoglobulins, 12-15 kDa with superior thermal stability. Their reduced molecular weight unlocks intraocular and CNS delivery routes previously inaccessible to conventional monoclonal architectures. Demand is concentrating in Japan's PMDA Sakigake-designated programs for neurological indications.
- ScFv:Single-chain variable fragments linking VH and VL domains via flexible peptide linkers, approximately 25-30 kDa. These constructs enable bacterial expression systems that bypass mammalian cell substrate costs.
- Fc Fragment:Crystallizable fragment regions enabling half-life extension through neonatal Fc receptor recycling, typically fused to therapeutic peptides. These formats depend on glycosylation patterns that constrain expression platform choices.
Fab anchors the volume base while sdAb gains share at the steepest rate.
Therapy Area:
Cost tier stratification separates acute oncology indications requiring premium pricing from chronic autoimmune maintenance where biosimilar pressure compresses margins fastest.
- Oncology:Fragment therapeutics targeting solid tumors exploit enhanced penetration versus intact antibodies. Academic medical centers in the United States, Germany, and Japan host the deepest clinical trial infrastructures, concentrating early-adopter demand. FDA Breakthrough Therapy Designation compresses Phase II-to-approval timelines, pulling forward revenue recognition.
- Autoimmune Disorders:Chronic administration requirements favor formats with established subcutaneous delivery infrastructure. EMA's Committee for Medicinal Products for Human Use imposes stringent immunogenicity testing thresholds that filter undercapitalized developers before Phase III entry.
- Infectious Diseases:Rapid pathogen evolution demands platform flexibility that microbial expression systems can supply more quickly than mammalian cell culture.
- Cardiovascular Diseases:Large patient populations and established reimbursement pathways attract developers seeking volume-based returns over premium pricing.
Oncology commands premium pricing tiers while autoimmune applications face the steepest biosimilar compression.
Delivery Mode:
Supply concentration in temperature-controlled logistics networks privileges injectable formats with established cold-chain infrastructure over novel routes requiring distribution reinvention.
- Injectable:Intravenous and subcutaneous administration dominates commercialized fragment therapeutics. Temperature-controlled distribution networks in the United States, Germany, and Japan concentrate manufacturing partnerships near academic medical center pharmacies.
- Oral:Gastrointestinal stability challenges have limited fragment penetration, though enteric coating advances and protease inhibitor co-formulation are eroding technical barriers.
- Topical:Skin penetration limits restrict applications to superficial inflammatory conditions where molecular weight constraints matter less.
- Intranasal:Blood-brain barrier bypass potential attracts CNS-focused developers, though mucosal clearance kinetics complicate dosing consistency.
Injectable formats anchor manufacturing scale while intranasal routes climb fastest on CNS targeting potential.
End User:
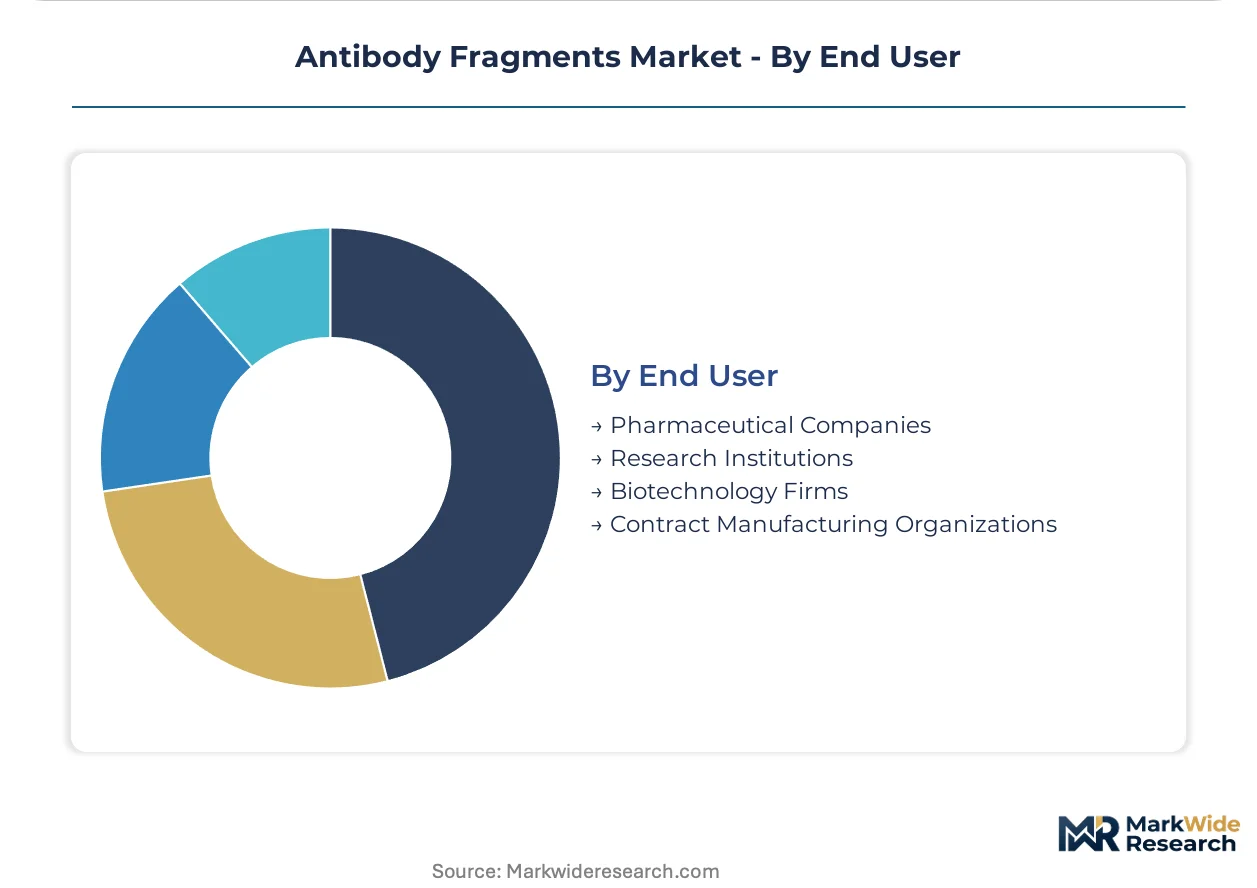
Customer type determines procurement autonomy versus centralized formulary control, with pharmaceutical companies retaining vendor selection flexibility that research institutions have ceded to pharmacy committees.
- Pharmaceutical Companies:Vertically integrated developers like Roche maintain captive CHO cell line infrastructure and continuous perfusion bioprocessing capabilities. These organizations lock in multi-year supply agreements with manufacturing slots and pricing tiers.
- Biotechnology Firms:Mid-scale developers dependent on contract manufacturing organizations face input cost volatility when serum supply tightens, squeezing gross margins.
- Contract Manufacturing Organizations:Perfusion system retooling requirements are forcing exit decisions among non-specialized providers, concentrating capacity among conglomerates with existing stainless-steel infrastructure.
- Research Institutions:Academic medical centers are consolidating procurement through centralized pharmacy committees, displacing individual principal-investigator purchasing autonomy with formulary-driven standardization.
Pharmaceutical companies anchor demand volume while contract manufacturing organizations face the steepest capability consolidation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in antibody fragments tilt heavily toward net imports in emerging markets while the United States, Germany, and Japan maintain biologics trade surpluses driven by captive manufacturing infrastructure. Regulatory divergence across FDA, EMA, and PMDA jurisdictions shapes where clinical-stage fragments concentrate in development pipelines.
United States
FDA Breakthrough Therapy Designation accelerates Phase II-to-approval timelines for oncology-focused fragments, pulling revenue recognition forward for developers with established biologics license application experience. The agency's Center for Drug Evaluation and Research maintains stringent immunogenicity testing thresholds that filter undercapitalized entrants before Phase III entry. South San Francisco and Boston-Cambridge clusters host the deepest fragment engineering talent pools, with Genentech anchoring manufacturing capabilities across the Bay Area.
Germany
EMA's Committee for Medicinal Products for Human Use enforces the most stringent interpretation of biosimilar comparability thresholds for Fab-format therapeutics, extending market exclusivity for reference products. The Paul-Ehrlich-Institut in Langen imposes documentation burdens that raise competitive barriers for non-vertically integrated developers. Basel-adjacent Baden-Württemberg and Bavaria concentrate continuous perfusion bioprocessing capabilities, with Roche leveraging cross-border manufacturing networks.
Japan
PMDA's Sakigake designation accelerates market entry for first-in-class fragment therapeutics, concentrating early-adopter demand in Tokyo-Osaka clinical trial corridors. The priority review system compresses regulatory timelines for single-domain antibody programs targeting CNS indications. Kanto and Kansai regions host specialized bioprocess engineering talent that bottlenecks capacity expansion at mid-scale facilities serving neurological therapeutic verticals.
Switzerland
Swissmedic aligns with EMA guidance while offering streamlined parallel consultation pathways for fragment developers seeking simultaneous EU and Swiss market entry. The regulatory convergence reduces documentation duplication for Basel-headquartered conglomerates with captive CHO cell line infrastructure. Northwestern Switzerland concentrates Fc-fusion program manufacturing, with Roche sustaining stainless-steel perfusion networks that force contract manufacturers to retool or exit fragment production.
India
CDSCO's fast-track pathway for biologics developed elsewhere creates white space for post-approval manufacturing partnerships serving South Asian demand. The abbreviated approval route attracts contract manufacturing organizations seeking to bypass originator market timelines. Maharashtra and Telangana clusters concentrate microbial expression system capabilities that erode mammalian cell culture dominance for non-glycosylated fragment formats.
Antibody Fragments Market Key Industry Players
Concentration sits with fully integrated biopharmaceutical conglomerates wielding captive CHO infrastructure, while specialized fragment engineering boutiques compete through format-specific expertise. The competitive field splits between mammalian-platform incumbents with continuous perfusion capabilities and microbial-expression specialists chasing cost advantages for smaller constructs. Strategic archetypes include Fc-fusion integrators, camelid-derived single-domain specialists, and bacterial-expression boutiques. Dominant competitive moves encompass backward integration into cell line development and geographic expansion through multi-year supply agreements with academic medical center pharmacies.
Within the fully integrated tier, F. Hoffmann-La Roche AG and Genentech, Inc. exemplify conglomerates with captive biologics manufacturing networks spanning Basel and South San Francisco. Ablynx occupies a position among specialized boutiques competing through alpaca-derived single-domain antibody platforms. These three anchors represent the structural divide between capital-intensive incumbents with stainless-steel infrastructure and format-focused specialists dependent on niche expression systems.
| Leading Market Players |
|---|
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche AG |
| Genentech, Inc. |
| Johnson & Johnson |
| AbbVie Inc. |
| Pfizer Inc. |
| Ablynx |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day CHO cell substrate lead times concentrate pricing power among Basel and South San Francisco manufacturers with captive perfusion infrastructure, while spot-market serum price spikes transmit directly to contract manufacturing organization quotes. This inventory-to-pricing linkage filters margin resilience through vertical integration depth.
Pricing Analysis
The customization-premium spread separates Fab-format standard catalog pricing from configured-to-order sdAb development programs. Three-tier pricing structure across premium, standard, and economy levels anchors on glycosylation complexity and expression platform choice. Pricing pressure stems from peptide-drug conjugate substitution in solid tumor applications where synthetic manufacturing simplicity outweighs binding affinity. Biotechnology firms dependent on contract manufacturing organizations exhibit acute price sensitivity, while Roche and Genentech's captive supply chains buffer margin compression.
Supply Chain Analysis
Just-in-time serum inventory strategies dominate among non-vertically integrated developers, exposing margins to fetal bovine serum spot-price volatility. Supply concentrates in the United States, Germany, and Switzerland, where stainless-steel perfusion networks anchor Fc-fusion and Fab-format production. Raw material dependencies center on CHO cell substrates, protein A chromatography resins, and single-use bioreactor bags. Single-source vulnerability concentrates in protein A resin suppliers. Distribution runs through temperature-controlled logistics networks directly to academic medical center pharmacies, bypassing wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Breakthrough Therapy Designation acceleration compresses development timelines, creating a high-growth disruption window where capitalized incumbents capture revenue recognition earlier than fragmented competitors. This regulatory inflection concentrates competitive advantage in developers with existing biologics license application experience.
For Market Incumbents: Shield Fab-format market position through backward integration into CRISPR-edited CHO cell line development, locking substrate cost advantages against serum price volatility. Consolidate manufacturing slots through multi-year supply agreements with NCI-designated cancer centers, displacing boutique competitors from formulary-driven procurement committees. For New Entrants and Emerging Players: CDSCO fast-track pathway certification accelerates post-approval manufacturing partnerships serving South Asian demand, bypassing originator market timelines that constrain established players. Target microbial expression system capabilities in Maharashtra and Telangana for non-glycosylated ScFv formats, exploiting cost advantages that mammalian-platform incumbents cannot match. Lead with direct-to-specialist distribution models that reduce cold-chain failure risk. For Investors and Strategic Acquirers: Long-term, this sits as a platform-technology play because camelid-derived single-domain antibody specialization opens CNS and intraocular delivery verticals previously inaccessible to conventional monoclonal architectures. Acquisition candidates with alpaca-derived platforms and PMDA Sakigake-designated pipelines offer the strongest positioning. Watch for continuous perfusion bioprocessing adoption rates as the inflection signal separating viable scale from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy Designation compresses Phase II-to-approval timelines for oncology fragments. |
| Manufacturing Scale-Up | Continuous perfusion bioprocessing adoption cuts facility footprint requirements by half for Basel-based networks. |
| Backward Integration | Captive CHO cell line development buffers margin compression from fetal bovine serum price volatility. |
| Pipeline Diversification | Camelid-derived sdAb programs unlock intraocular and CNS delivery routes in Japan's Sakigake-designated corridors. |
| Long-term Supply Agreement | Multi-year manufacturing slot contracts with academic medical centers lock in pricing tiers and displace competitors. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates across the analysis window.
Variance decomposition across product type, therapy area, delivery mode, and end user dimensions structured the analytical framework. CAGRs were derived from modeled revenue trajectories incorporating continuous bioprocessing adoption curves, regulatory pathway acceleration rates, and substitution pressure from peptide-drug conjugate alternatives.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA accelerated approval pathway availability; material deviation would warrant model refresh. Revision becomes warranted when CRISPR-edited CHO platform cost reduction crosses thresholds that restructure competitive economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Becker Muscular Dystrophy Market