
 Cancer Antigens Market | 2026-2036
Cancer Antigens Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Antigens Market Outlook
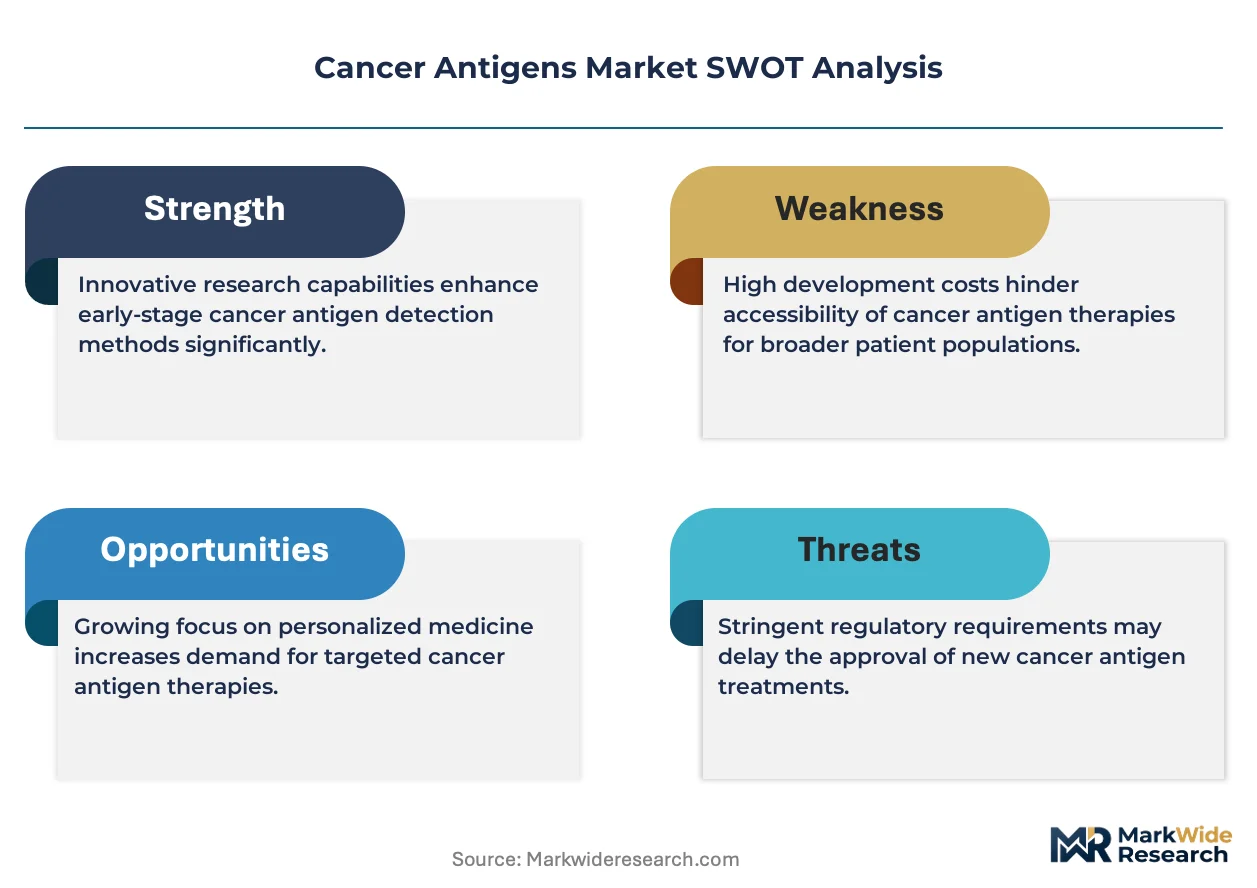
Multiplexed protein detection platforms are reshaping how cancer antigens are profiled in clinical and research settings. F. Hoffmann-La Roche leverages its embedded diagnostics division to sustain integrated assay-to-therapy workflows across oncology franchises. Thermo Fisher Scientific anchors its position through captive supply of recombinant antigen substrates and mass spectrometry readout systems. Bristol Myers Squibb differentiates by aligning biomarker discovery with checkpoint inhibitor development pipelines.
Cancer antigens comprise tumor-associated proteins, glycoproteins, and carbohydrate structures eliciting immune recognition or serving as serological markers, typically quantified through immunoassay formats with analytical sensitivity thresholds in the picogram-per-milliliter range for early-stage detection. Their primary purpose spans diagnostic surveillance, therapeutic target identification, and immune response monitoring in solid and hematological malignancies. Monoclonal antibodies represent the dominant product category, capturing substantial margin pools through long-standing clinical validation in colorectal, pancreatic, and ovarian cancer settings. Diagnostic kits are gaining structural momentum as point-of-care and decentralized laboratory models expand, while biomarkers remain the fastest-growing segment driven by liquid biopsy companion diagnostic mandates.
The FDA governs cancer antigen assays as Class II or III medical devices under 21 CFR, enforcing analytical and clinical validation standards that shape market entry timelines and development costs. EMA's In Vitro Diagnostic Regulation imposes notified body conformity assessments that restructure competitive access across European member states. ISO 13485 quality management requirements and WHO prequalification pathways for oncology diagnostics further condition procurement eligibility in emerging health systems. Stakeholders must monitor evolving payer evidence requirements for multiplex biomarker panels versus single-analyte reimbursement codes.
Market Dynamics
The FDA's accelerated approval pathway for companion diagnostics is compressing development timelines and forcing biomarker developers to front-load analytical validation investments before clinical trials complete. This regulatory velocity is reshaping how cancer antigen assays transition from research tools to reimbursable clinical products.
Growth Catalysts
- Liquid biopsy mandates:Oncology drug labels increasingly require circulating tumor DNA companion diagnostics, expanding addressable specimen volumes beyond tissue biopsies.
- EMA In Vitro Diagnostic Regulation:Notified body conformity assessments in Europe are consolidating market access around CE-IVD certified manufacturers, advantaging pre-positioned suppliers.
- Centralized pathology networks:Germany's regional laboratory consolidation is standardizing CA 19-9 and CEA testing protocols, creating volume concentration effects for assay providers.
Market Restraints
- Recombinant protein input costs:Purified antigen substrates for immunoassay manufacturing face supply volatility from Chinese bioreactor capacity constraints.
- Single-analyte reimbursement codes:US CMS payment structures favor standalone tests over multiplex panels, fragmenting revenue capture for integrated protein profiling platforms.
- Analytical sensitivity thresholds:Picogram-per-milliliter detection requirements for early-stage cancer surveillance demand specialized detection chemistry that extends R&D cycles.
Strategic Opportunities
- Point-of-care decentralization:Clinical laboratories in the United States are expanding immunohistochemistry workflows into satellite facilities, creating instrument placement opportunities.
- Multiplex biomarker panels:Payer evidence requirements are evolving toward composite scoring algorithms that combine multiple antigens for risk stratification.
- ISO 13485 prequalification:WHO oncology diagnostic pathways for emerging health systems reward quality-certified manufacturers with procurement eligibility advantages.
Industry Challenges
- Companion diagnostic co-development timelines:Checkpoint inhibitor developers require biomarker validation synchronized with Phase II trials, compressing assay design windows.
- Immunohistochemistry workflow integration:Automated staining platforms from incumbent vendors create switching friction for new antigen assay entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Antigens Market |
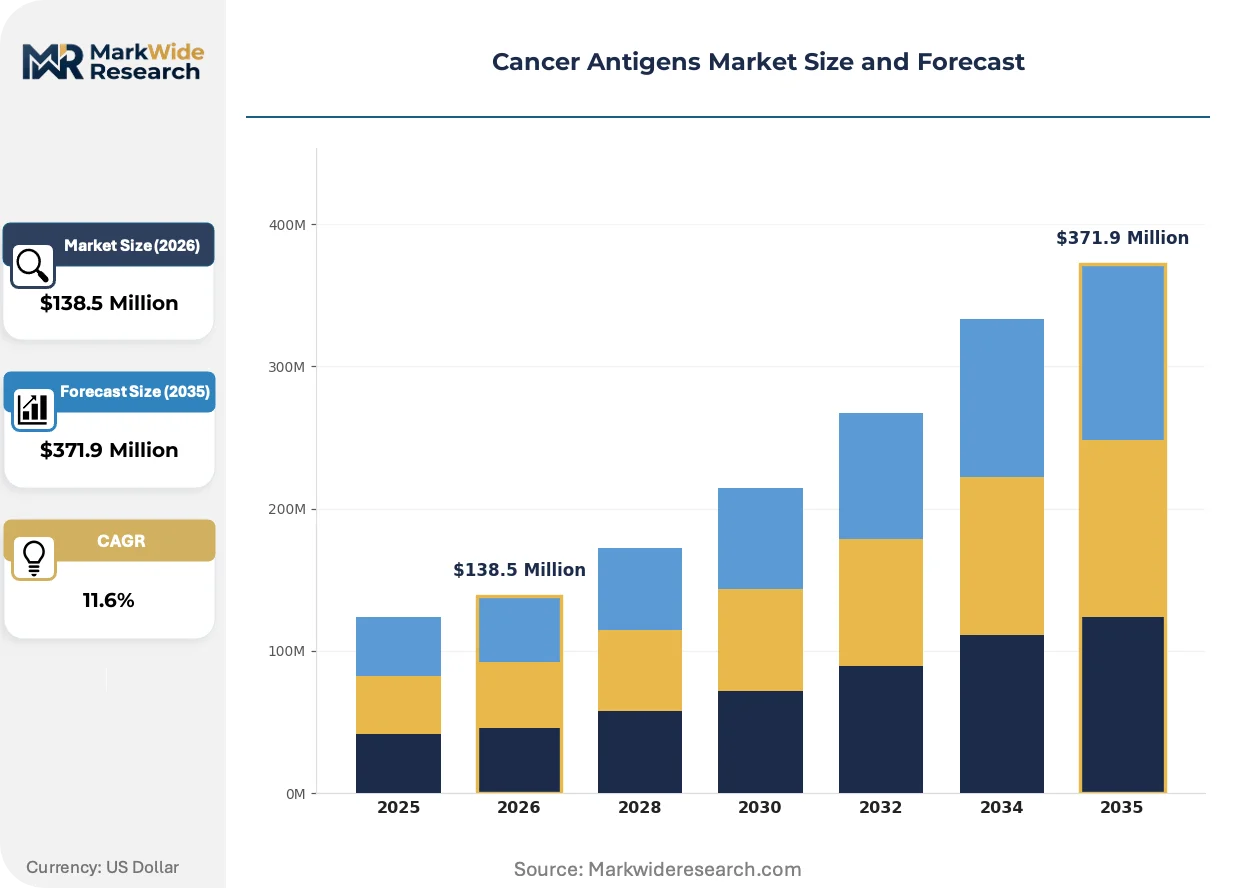
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $371.9 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Biomarkers, Diagnostic Kits Therapy Area: Immunotherapy, Targeted Therapy, Diagnostics, Supportive Care End User: Hospitals, Research Laboratories, Clinics, Biopharmaceutical Companies Application: Research, Diagnostic Testing, Clinical Trials, Therapeutic Development |
| Companies Covered | F. Hoffmann-La Roche, Thermo Fisher Scientific, Amgen, Novartis, Merck & Co., Bristol Myers Squibb, AstraZeneca, Johnson & Johnson, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Antigens Market Strategic Shifts
Multiplexed protein detection platforms are converging with mass spectrometry readout systems to enable simultaneous quantification of tumor-associated antigens, glycoproteins, and carbohydrate structures from minimal specimen volumes.
Mass spectrometry-based immunoassay workflows are digitizing antigen quantification by replacing optical detection with precise mass measurement, eliminating antibody cross-reactivity interference. Academic medical centers and reference laboratories in the United States are adopting these platforms for research-use profiling. The technology is digitizing serological marker validation pipelines, compressing the timeline from biomarker discovery to clinical assay transfer.
EMA's In Vitro Diagnostic Regulation imposes notified body conformity assessments that restructure competitive access across European member states. Manufacturers must now maintain technical documentation and post-market surveillance systems that previously applied only to higher-risk device categories. Germany's centralized pathology networks are responding by consolidating procurement around suppliers with established CE-IVD portfolios and notified body relationships.
Hospital systems are unbundling after-sales service contracts from instrument purchases, treating maintenance and reagent supply as separately negotiable spend categories. Integrated diagnostics divisions that previously captured captive consumable revenue now face third-party reagent competitors. This pattern is most visible in the United States, where health system purchasing coalitions are extracting price transparency commitments for per-test costs across monoclonal antibody and recombinant antigen substrate lines.
Cancer Antigens Market Segmentation
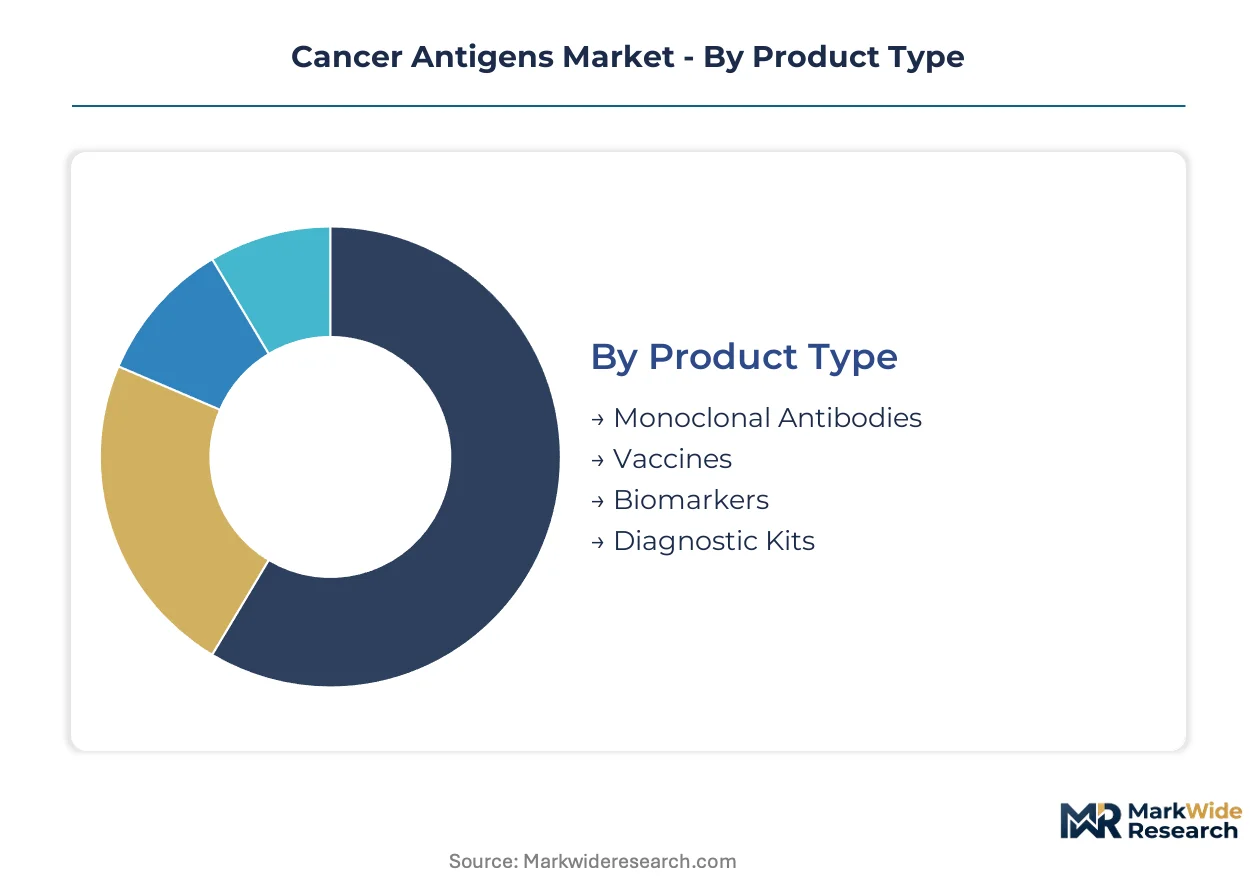
Cancer antigens serve distinct functions across detection, treatment, and monitoring workflows. Segment boundaries reflect how regulatory pathways, reimbursement structures, and technical specifications channel procurement decisions toward specialized product formats.
Product Type:
Cost tiers separate mature antibody franchises from emerging biomarker platforms requiring heavier validation investment.
- Monoclonal Antibodies:Purified immunoglobulins targeting specific tumor-associated epitopes with established pharmacokinetic profiles. Long-standing FDA approvals for CA 19-9, CEA, and PSA assays sustain recurring revenue in hospital laboratories across the United States and Germany. Reimbursement codes favor these validated formats over novel alternatives.
- Biomarkers:Circulating protein signatures and circulating tumor DNA fragments enabling non-invasive cancer surveillance. Liquid biopsy mandates in oncology drug labels are accelerating specimen volume growth beyond tissue-based workflows. Multiplex panel configurations face CMS reimbursement fragmentation.
- Vaccines:Therapeutic formulations designed to elicit antigen-specific T-cell responses against tumor neoantigens.
- Diagnostic Kits:Pre-configured reagent sets for immunoassay deployment in decentralized testing environments.
Monoclonal antibodies hold installed capacity. Biomarkers are rotating up the share rankings.
Therapy Area:
Application maturity determines whether segments compete on price or clinical evidence depth.
- Immunotherapy:Checkpoint inhibitor combinations and CAR-T protocols requiring predictive biomarker stratification. Companion diagnostic co-development with pembrolizumab, nivolumab, and atezolizumab labels concentrates demand in reference laboratories capable of PD-L1 and tumor mutational burden testing. FDA accelerated approval timelines compress assay validation windows.
- Diagnostics:Screening and surveillance applications for early-stage malignancy detection. Germany's centralized pathology networks standardize CA 19-9 and CEA protocols across regional laboratory consolidations, creating volume concentration for assay providers with CE-IVD certification.
- Targeted Therapy:Small-molecule inhibitors matched to specific antigen expression profiles.
- Supportive Care:Antigen monitoring for treatment response and recurrence surveillance.
Diagnostics holds installed capacity. Immunotherapy is rotating up the share rankings.
End User:
Customer type dictates purchasing authority, with health systems consolidating procurement around integrated suppliers.
- Hospitals:Acute care facilities with embedded clinical laboratories performing routine immunoassay testing. United States health system purchasing coalitions are unbundling instrument purchases from reagent supply contracts, extracting price transparency for per-test costs. ISO 13485 certification increasingly conditions contract eligibility.
- Biopharmaceutical Companies:Drug developers requiring biomarker validation synchronized with Phase II and III trial timelines. Checkpoint inhibitor pipelines demand antigen assay readiness before regulatory submission, front-loading investment in analytical validation.
- Research Laboratories:Academic and government institutions conducting discovery-stage antigen profiling.
- Clinics:Outpatient facilities pursuing point-of-care decentralization for rapid turnaround.
Hospitals hold installed capacity. Biopharmaceutical companies are rotating up the share rankings.
Application:
Volume concentration follows regulatory submission timelines, with clinical trial demand peaking in synchronization with drug development cycles.
- Diagnostic Testing:Clinical-grade antigen quantification for patient management decisions. EMA's In Vitro Diagnostic Regulation imposes notified body conformity assessments that restructure European procurement around CE-IVD certified suppliers. Germany's regional laboratory networks respond by consolidating vendor relationships.
- Clinical Trials:Biomarker endpoint validation for regulatory submissions and patient stratification. FDA companion diagnostic mandates for oncology drug approvals expand addressable specimen volumes beyond traditional tissue biopsy constraints into circulating tumor DNA workflows.
- Research:Discovery-stage antigen identification and mechanism investigation.
- Therapeutic Development:Target identification and validation for novel drug modalities.
Diagnostic testing holds installed capacity. Clinical trials are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision oncology diagnostics to consolidated hospital networks across the European Union. The United States imports recombinant antigen substrates from Asian bioreactor facilities for domestic immunoassay manufacturing. Trade corridors concentrate high-value cancer antigen reagents in markets with centralized pathology infrastructure and companion diagnostic mandates.
United States
FDA's accelerated approval pathway for companion diagnostics compresses biomarker assay validation timelines. Health system purchasing coalitions in Texas and California unbundle instrument purchases from reagent supply contracts. Reference laboratories in Greater Boston adopt mass spectrometry-based immunoassay workflows for research-use antigen profiling.
Germany
Centralized pathology networks in Bavaria and North Rhine-Westphalia standardize CA 19-9 and CEA testing protocols across regional laboratory consolidations. EMA's In Vitro Diagnostic Regulation imposes notified body conformity assessments that restructure procurement around CE-IVD certified manufacturers. The Rhine-Main cluster concentrates automated immunohistochemistry platform deployment.
China
NMPA oncology diagnostic approvals expand domestic manufacturing capacity for tumor-associated antigen assays. Bioreactor facilities in the Yangtze River Delta supply recombinant protein substrates to global immunoassay producers. Shanghai's precision medicine corridor attracts multinational biomarker validation partnerships.
Japan
PMDA guidelines for companion diagnostics synchronize biomarker assay readiness with Phase II trial submissions. METI funding for liquid biopsy infrastructure expands circulating tumor DNA specimen processing capacity. The Kansai region's pharmaceutical manufacturing belt concentrates therapeutic antibody production.
United Kingdom
NHS England's national genomic medicine service integrates cancer antigen testing into standardized cancer pathways. MHRA post-Brexit regulatory autonomy maintains alignment with EMA IVD frameworks for market access continuity. London's academic medical centers drive multiplex biomarker panel validation for risk stratification algorithms.
Cancer Antigens Market Competitive Environment
On the supply side, the industry is consolidating around integrated diagnostics divisions with captive reagent manufacturing and established notified body relationships. Three archetypes dominate: diversified life science conglomerates with embedded assay-to-therapy workflows, specialized diagnostics pure-plays with mass spectrometry readout capabilities, and biopharmaceutical developers aligning biomarker discovery with checkpoint inhibitor pipelines. Competitive moves concentrate on strategic partnerships for companion diagnostic co-development and geographic expansion through CE-IVD certification pre-positioning.
Within the integrated conglomerate tier, F. Hoffmann-La Roche and Thermo Fisher Scientific exemplify supply-side consolidation through captive control over recombinant antigen substrates and detection chemistry. Bristol Myers Squibb occupies a distinct position bridging therapeutic development and biomarker validation, representing the pharmaceutical-aligned archetype that increasingly drives antigen assay demand through companion diagnostic mandates.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| Amgen |
| Novartis |
| Merck & Co. |
| Bristol Myers Squibb |
| AstraZeneca |
| Johnson & Johnson |
| Gilead Sciences |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting Chinese bioreactor clusters to European diagnostic manufacturers concentrate input cost volatility for recombinant antigen substrates, compressing margins at the standard-grade tier while premium CE-IVD certified assays retain pricing power through regulatory scarcity.
Pricing Analysis
Mass spectrometry-based detection platforms command substantial premiums over legacy optical immunoassays, while prior-generation ELISA formats face sustained price erosion from automated platform commoditization. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostics from research-use-only panels and unvalidated laboratory-developed tests. Pricing pressure stems from health system purchasing coalitions unbundling instrument and reagent contracts in the United States. Biopharmaceutical companies exhibit lowest price sensitivity due to co-development timeline imperatives, while decentralized clinics face acute cost constraints.
Supply Chain Analysis
Export control regimes restricting mass spectrometry instrument sales to designated research institutions fragment access to next-generation detection platforms in certain markets. Recombinant protein production concentrates in Chinese bioreactor facilities, German precision fermentation sites, and United States contract manufacturing organizations. Purified antigen substrates, monoclonal antibody cell lines, and specialized detection chemistry constitute critical input dependencies. Single-source vulnerability in Chinese bioreactor capacity creates supply interruption exposure. Distribution runs through consolidated pathology networks in Germany and health system purchasing coalitions in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid biopsy platforms threaten to displace tissue-based antigen assays, forcing incumbents to defend installed base relationships while capturing next-generation specimen workflows.
For Market Incumbents: Insulate core immunoassay franchises by deepening captive supply of recombinant antigen substrates through backward integration into bioreactor capacity. Secure notified body relationships for EMA IVDR conformity assessments ahead of European procurement consolidation. Prioritize automated platform placements that create switching friction for emerging mass spectrometry entrants.
For New Entrants and Emerging Players: Southeast Asian hospital systems present underpenetrated demand for CE-IVD certified diagnostic kits as national cancer screening programs expand. Target point-of-care decentralization in United States satellite laboratories as the most penetrable entry channel. Pursue WHO prequalification pathways to unlock procurement eligibility in emerging health systems lacking stringent regulatory infrastructure.
For Investors and Strategic Acquirers: FDA's accelerated approval pathway for companion diagnostics reshapes the acquisition landscape toward biomarker validation capabilities synchronized with Phase II trial timelines. Position for five-to-ten year horizon consolidation around integrated assay-to-therapy workflows. Monitor companion diagnostic co-development announcement velocity as the signal indicating platform technology inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | FDA accelerated approval timelines compress assay validation windows for checkpoint inhibitor pipelines. |
| CE-IVD Certification Pre-positioning | EMA IVDR notified body relationships secure procurement access across German regional laboratory networks. |
| Mass Spectrometry Platform Deployment | Academic medical centers in Greater Boston adopt digitized antigen quantification for research-use profiling. |
| Recombinant Substrate Backward Integration | Captive bioreactor capacity insulates margin pools from Chinese supply volatility. |
| Liquid Biopsy Infrastructure Partnership | METI funding in Japan expands circulating tumor DNA specimen processing for oncology drug labels. |
Study Parameters
A standing panel of regulatory affairs leads, hospital procurement managers, pathology laboratory directors, and biopharmaceutical biomarker strategists provided ongoing calibration against primary interview findings. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov companion diagnostic mandates, and CMS Medicare reimbursement code databases. Bottom-up assay volume modeling triangulated against top-down market sizing from instrument placement records and reagent consumption estimates.
Scenario bracketing around liquid biopsy penetration rates, companion diagnostic approval velocity, and European procurement consolidation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, therapy area, end user, and application with regional regulatory cluster overlays. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns in precision oncology, incorporating biomarker validation cycle times and payer evidence requirement evolution as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese bioreactor operators or accelerated FDA breakthrough device designations would shift outcomes. Material shifts in EMA IVDR implementation timelines or CMS multiplex panel reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Insulinoma Market