
 Neurotrophins Market | 2026-2036
Neurotrophins Market Size, Share, and Industry Trends Forecast 2026-2036
Neurotrophins Market Foresight
Subscription-based access to recombinant neurotrophin manufacturing platforms is rebalancing how pharmaceutical companies procure critical biologics inputs. Genentech leverages its mammalian cell culture expertise to sustain high-purity Brain-Derived Neurotrophic Factor output for internal pipeline programs. Regeneron Pharmaceuticals competes through proprietary VelociGene technology that accelerates neurotrophin analog development timelines.
Neurotrophins comprise a family of secreted growth factors—principally Nerve Growth Factor, Brain-Derived Neurotrophic Factor, Neurotrophin-3, and Neurotrophin-4—that regulate neuronal survival, differentiation, and synaptic plasticity through Trk receptor tyrosine kinase and p75NTR signaling pathways; recombinant production employs Chinese hamster ovary cell lines or yeast expression systems to achieve glycosylation patterns essential for biological activity. Intravenous and subcutaneous delivery modes currently dominate commercial formulations, though intranasal routes represent the fastest-growing segment as manufacturers seek to bypass the blood-brain barrier. Neurodegenerative disorders anchor application demand, while traumatic brain injury indications attract emerging investment due to unmet clinical need and orphan drug incentives.
FDA orphan drug designations and EMA's PRIME scheme for neurological therapies shape neurotrophin development priorities, accelerating regulatory review for conditions like amyotrophic lateral sclerosis and spinal muscular atrophy. ISO 13485 quality management standards and ICH Q5D cell substrate guidelines govern manufacturing compliance for recombinant neurotrophin products. Stakeholders must monitor evolving blood-brain barrier delivery technologies and payer evidence requirements for neuroregenerative claims.
Market Dynamics
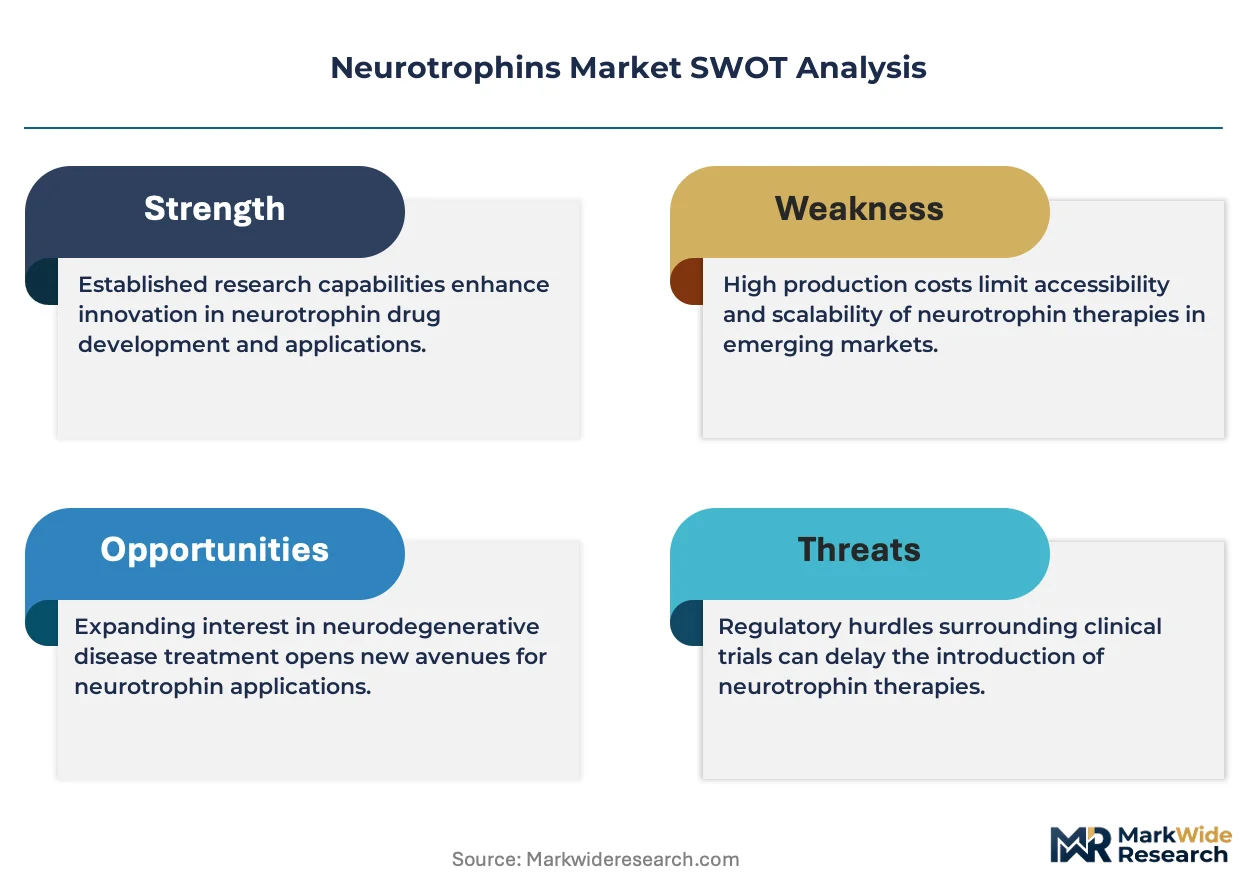
Accelerated approval pathways for orphan neurological indications are compressing clinical trial timelines and reshaping how biopharmaceutical firms allocate R&D capital toward neurotrophin-based therapies.
Growth Catalysts
- FDA orphan drug designation:Accelerated review timelines for amyotrophic lateral sclerosis and spinal muscular atrophy indications reduce regulatory friction and compress time-to-market for novel neurotrophin analogs.
- Intranasal delivery innovation:Blood-brain barrier bypass technologies are expanding addressable patient populations beyond intravenous and subcutaneous formulation limits.
- Alzheimer's disease investment:Unmet clinical need in neurodegenerative disorders is channeling venture and strategic capital into neurotrophin-3 and Brain-Derived Neurotrophic Factor therapeutic programs.
Market Restraints
- Glycosylation complexity:Chinese hamster ovary cell line dependence creates yield variability and purification cost escalation for recombinant neurotrophin manufacturing.
- Reimbursement evidence requirements:Payer demands for neuroregenerative outcome demonstration exceed current clinical biomarker validation standards, extending commercialization timelines.
- Peptide stability limitations:Short half-lives of native neurotrophin proteins necessitate frequent dosing or expensive analog engineering, constraining chronic disease market penetration.
Strategic Opportunities
- Traumatic brain injury expansion:Orphan drug incentives and absence of approved disease-modifying therapies position acute neurological injury as a priority indication for neurotrophin-4 development.
- EMA PRIME scheme alignment:Priority medicines designation for neurological therapies offers enhanced regulatory support and accelerated assessment pathways for qualifying neurotrophin candidates.
- Bioprocessing subscription models:Pharmaceutical manufacturers are externalizing mammalian cell culture capacity through platform access agreements rather than captive facility investment.
Industry Challenges
- Trk receptor selectivity engineering:Cross-reactivity between neurotrophin family members and receptor subtypes complicates therapeutic index optimization and toxicology profiling.
- ICH Q5D compliance timelines:Cell substrate qualification and master cell bank characterization for recombinant products extend preclinical development schedules by 18-24 months.
- Specialized formulation talent:Blood-brain barrier drug delivery expertise resides in limited academic and contract research organization clusters, constraining pipeline expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurotrophins Market |
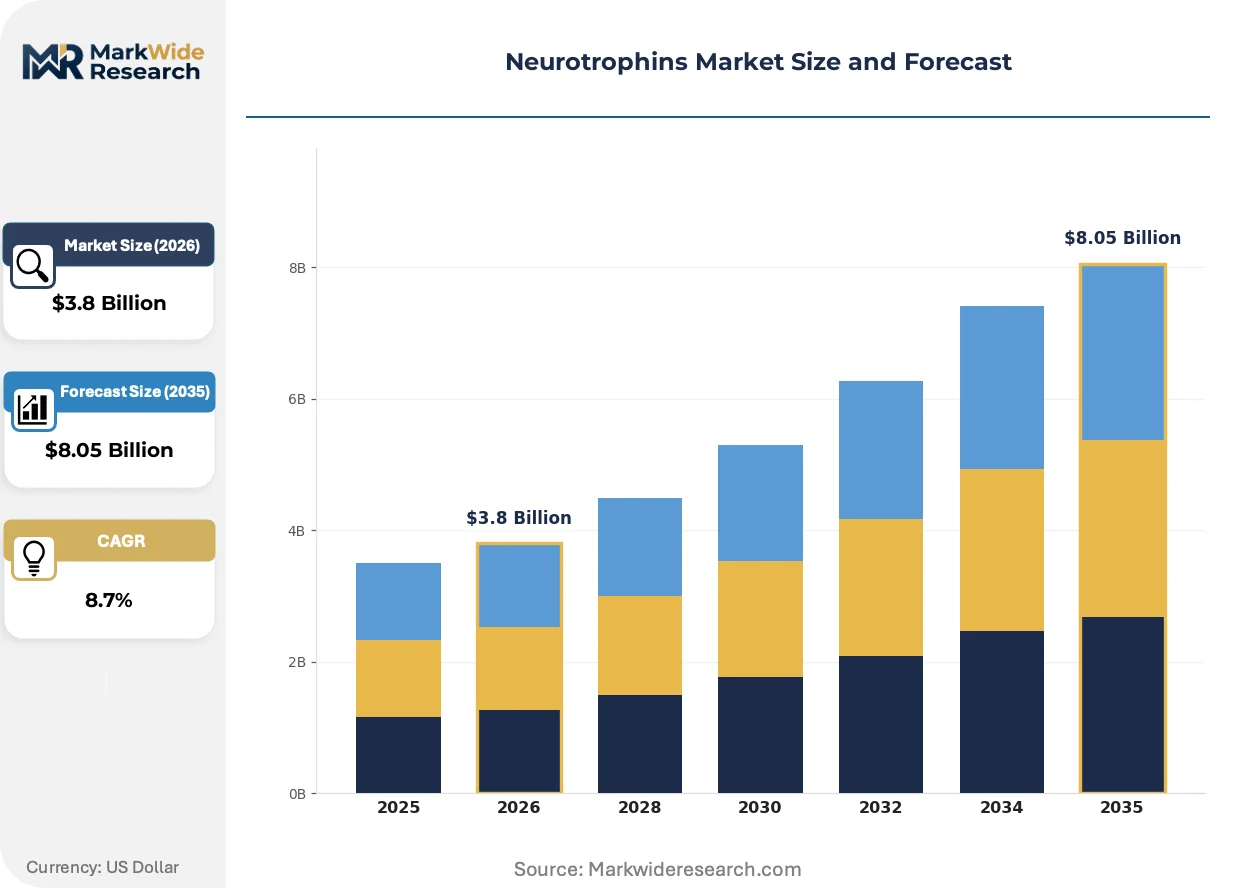
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Growth Factor, Brain-Derived Neurotrophic Factor, Neurotrophin-3, Neurotrophin-4 Delivery Mode: Intravenous, Subcutaneous, Intranasal, Oral Application: Neurodegenerative Disorders, Traumatic Brain Injury, Peripheral Neuropathy, Spinal Cord Injury End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies |
| Companies Covered | Johnson & Johnson, PeproTech, Merck Serono, FibroGen, Genentech, Regeneron Pharmaceuticals, Biogen, Lonza Group, R&D Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurotrophins Market Shifts & Advancements
Neurotrophin therapeutic development is pivoting toward delivery technology convergence and regulatory pathway optimization as manufacturers confront the fundamental challenge of protein drug access to central nervous system targets.
Recombinant fusion proteins incorporating blood-brain barrier shuttle domains are unifying neurotrophin pharmacology with transport biology. Biopharmaceutical firms developing Alzheimer's and Parkinson's disease candidates are adopting these engineered constructs to achieve therapeutic central nervous system exposure. This convergence is compressing the historical gap between peripheral dosing and intracranial activity, enabling chronic disease management paradigms previously inaccessible to protein therapeutics.
EMA's PRIME scheme for priority medicines is redirecting neurotrophin clinical trial design toward adaptive protocols and biomarker-enriched patient selection. Sponsors are incorporating surrogate endpoint strategies earlier in development to align with accelerated assessment timelines. Neurological therapy developers targeting amyotrophic lateral sclerosis are most affected, with regulatory submission packages now structured around conditional approval pathways rather than traditional Phase III completion.
Academic medical centers and specialized neurology consortia are consolidating neurotrophin clinical trial access through preferred site networks. Pharmaceutical sponsors are displacing traditional contract research organization site selection with direct institutional partnerships that compress patient recruitment timelines. Germany, Japan, and the United States exhibit the most pronounced concentration of these investigator-initiated and industry-collaborative trial structures.
Neurotrophins Market Segmentation
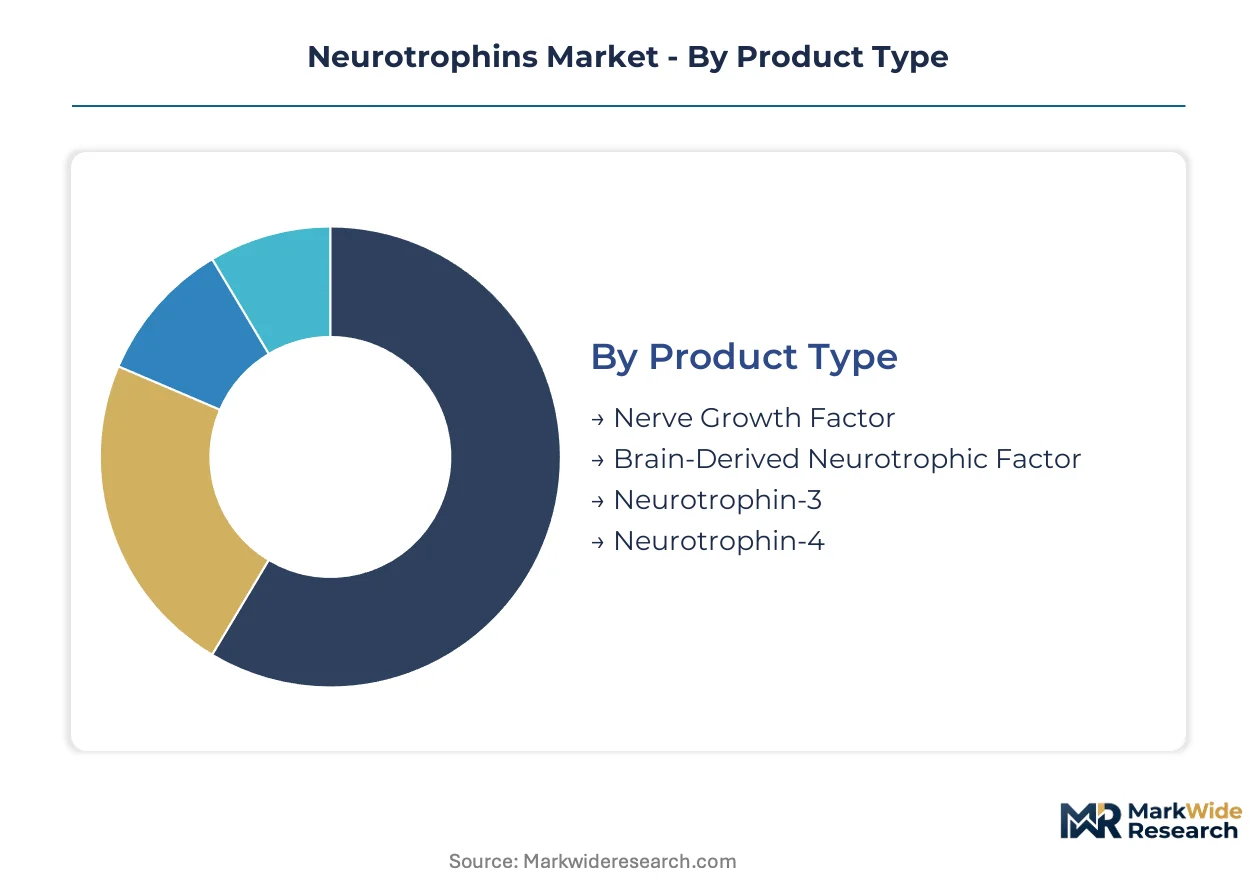
Neurotrophin therapeutic development demands precise segmentation alignment with biological mechanism and delivery feasibility. Each dimension—molecular target, administration route, clinical indication, and procurement channel—carries distinct regulatory, manufacturing, and reimbursement implications that reshape competitive positioning.
Product Type:
Upgrade cycles in neurotrophin pipelines follow receptor selectivity breakthroughs and blood-brain barrier engineering milestones that obsolete earlier-generation candidates.
- Brain-Derived Neurotrophic Factor:Recombinant glycoprotein modulates synaptic plasticity and neuronal survival through TrkB receptor activation. Demand concentrates in Alzheimer's disease programs across the United States and Germany where academic consortia validate cognitive endpoint biomarkers. FDA orphan drug designations for amyotrophic lateral sclerosis accelerate development timelines for high-purity mammalian cell culture outputs.
- Nerve Growth Factor:Foundational neurotrophin regulates peripheral sympathetic and sensory neuron development via TrkA signaling. Peripheral neuropathy applications in Japan and diabetic patient populations drive procurement from specialized bioprocessing facilities. Short plasma half-life necessitates sustained-release formulation engineering or fusion protein modification.
- Neurotrophin-3:TrkC-selective ligand promotes proprioceptive neuron survival and motor circuit development.
- Neurotrophin-4:TrkB-activating factor with emerging traumatic brain injury applications leveraging orphan drug incentives.
Brain-Derived Neurotrophic Factor sits at the top of the volume ranking, with Neurotrophin-4 climbing the fastest.
Delivery Mode:
Cost tier stratification separates chronic disease management formulations from acute intervention modalities with divergent reimbursement and manufacturing scale economics.
- Intravenous:Established administration route for hospital-based neurodegenerative therapy requiring controlled infusion protocols and cold-chain distribution. High manufacturing purity standards and specialized compounding infrastructure limit site-of-care expansion.
- Intranasal:Blood-brain barrier bypass technology enables direct olfactory bulb delivery with reduced systemic exposure. United States and European research institutions pioneer device-compatible formulations for outpatient Alzheimer's management.
- Subcutaneous:Patient-administered alternative for chronic dosing regimens with prefilled pen device compatibility.
- Oral:Peptide stability challenges constrain bioavailability; formulation innovation focuses on enteric coating and permeation enhancers.
Intravenous maintains revenue leadership through hospital anchoring, while intranasal gains share fastest on outpatient expansion.
Application:
Customer maturity varies sharply between indication categories with approved disease-modifying pathways versus exploratory neuroregenerative claims.
- Neurodegenerative Disorders:Alzheimer's and Parkinson's disease anchor commercial demand with validated Trk receptor pharmacology and measurable cognitive-motor endpoints. Germany, Japan, and the United States concentrate specialized neurology trial infrastructure and payer familiarity with biologic therapy.
- Traumatic Brain Injury:Acute neurological injury represents priority indication for Neurotrophin-4 development with unmet clinical need and FDA orphan drug incentives. Military and civilian trauma centers in the United States drive early-access protocols.
- Peripheral Neuropathy:Diabetic and chemotherapy-induced indications leverage Nerve Growth Factor mechanisms with established peripheral nerve biomarkers.
- Spinal Cord Injury:Axonal regeneration claims face stringent EMA and FDA evidentiary requirements for functional recovery demonstration.
Neurodegenerative Disorders dominates current revenue, with Traumatic Brain Injury expanding most quickly on regulatory pathway acceleration.
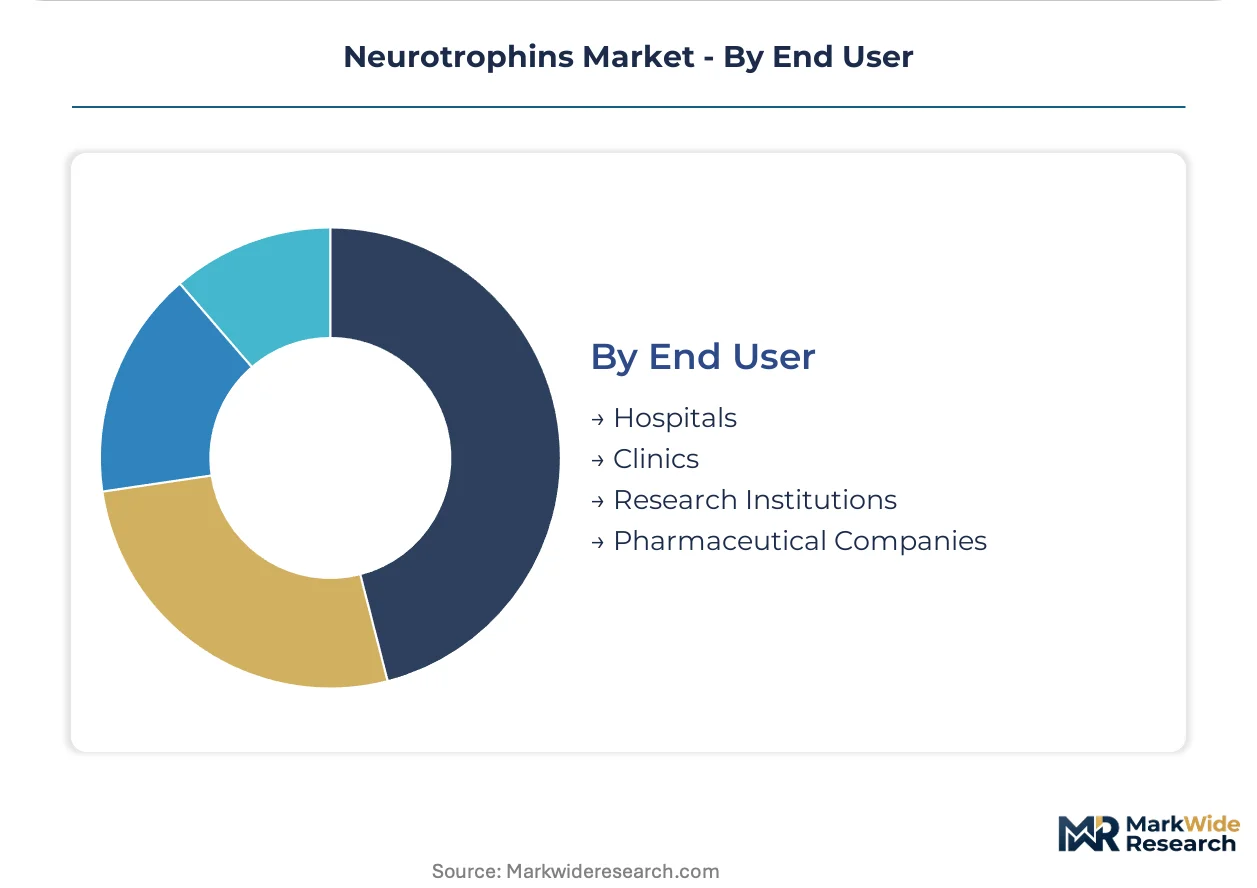
End User:
Supply concentration in mammalian cell culture capacity shapes procurement patterns across institutional buyer categories with divergent quality specification and volume requirements.
- Pharmaceutical Companies:Integrated biopharmaceutical firms and emerging biotechnology sponsors procure recombinant neurotrophin for internal pipeline programs and contract manufacturing organization partnerships. Subscription-based platform access agreements displace captive facility investment.
- Research Institutions:Academic medical centers and specialized neurology consortia in Germany, Japan, and the United States consolidate clinical trial access through preferred site networks.
- Hospitals:Tertiary care centers with specialized neurology infusion suites administer intravenous formulations under protocol-driven reimbursement.
- Clinics:Outpatient neurology practices pilot intranasal delivery protocols with device training and patient monitoring requirements.
Pharmaceutical Companies command the largest procurement volumes, with Research Institutions gaining influence fastest on trial site consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialized neurology trial infrastructure while the United States channels venture capital into blood-brain barrier delivery platforms, creating divergent innovation pathways across Atlantic neurotrophin development clusters.
United States
FDA orphan drug designations for amyotrophic lateral sclerosis compress regulatory timelines, while military trauma centers in Maryland and civilian academic medical centers in Massachusetts pilot acute neurological injury protocols. NIH neurodegeneration research consortia in Boston and San Francisco validate cognitive endpoint biomarkers for Alzheimer's programs.
Germany
EMA PRIME scheme alignment accelerates assessment pathways for neurological priority medicines, with Heidelberg and Munich university hospitals consolidating preferred site networks for investigator-initiated trials. BfArM early access frameworks support compassionate use protocols for spinal cord injury candidates.
Japan
PMDA Sakigake designation system fast-tracks neurotrophin-3 development for motor circuit disorders, while Tokyo and Osaka neurology centers pioneer intranasal device training programs. METI biomedical innovation subsidies channel manufacturing investment toward mammalian cell culture capacity expansion.
Switzerland
Swissmedic accelerated review pathways for rare neurological diseases attract pipeline relocation from larger regulatory jurisdictions, with Basel and Zurich biotech clusters specializing in Trk receptor selectivity engineering. ETH Zurich blood-brain barrier research programs supply formulation talent to regional sponsors.
United Kingdom
MHRA innovation passport designation for neurological therapies compresses market authorization timelines post-Brexit, while London and Cambridge academic consortia consolidate patient recruitment for neurodegenerative disorder trials. Cell and Gene Therapy Catapult facilities in Stevenage support master cell bank characterization.
Neurotrophins Market Competitive Landscape
Top-tier vendors anchor integrated biopharmaceutical development, while specialized biotechnology firms and contract manufacturing organizations occupy mid-tier positions through platform access agreements. The competitive structure stratifies across three archetypes: mammalian cell culture specialists with captive capacity, recombinant protein engineering boutiques with receptor selectivity expertise, and subscription-based bioprocessing platforms externalizing manufacturing risk. Dominant competitive moves include strategic partnerships between delivery technology developers and formulation specialists, plus geographic expansion through preferred site network consolidation in Germany, Japan, and the United States.
Within the integrated biopharmaceutical tier, Genentech and Regeneron Pharmaceuticals exemplify divergent strategic positioning around mammalian cell culture scale versus proprietary gene technology acceleration. Lonza Group occupies the contract manufacturing platform position, externalizing recombinant neurotrophin production capacity through subscription access agreements that displace captive facility investment among emerging biotechnology sponsors.
| Leading Market Players |
|---|
| Johnson & Johnson |
| PeproTech |
| Merck Serono |
| FibroGen |
| Genentech |
| Regeneron Pharmaceuticals |
| Biogen |
| Lonza Group |
| R&D Systems |
| Others |
Supply & Pricing Matrix
Intranasal delivery device convergence is compressing manufacturing scale economics while simultaneously redistributing bargaining power toward formulation specialists with blood-brain barrier engineering capabilities. This technological pivot elevates cost premiums for receptor-selective neurotrophin analogs against commoditized intravenous formulations.
Pricing Analysis
Capacity additions in Switzerland and Germany are reshaping price floors for recombinant neurotrophin manufacturing as mammalian cell culture platforms achieve yield parity. Three-tier pricing structure across GMP-certified premium, research-grade standard, and preclinical economy levels reflects ISO 13485 compliance differentiation. Cost compression in the standard tier is intensifying because contract manufacturing organizations are externalizing bioreactor capacity through subscription access agreements. Emerging biotechnology sponsors exhibit highest price sensitivity due to pre-revenue funding constraints, while integrated pharmaceutical companies prioritize quality grade over unit cost.
Supply Chain Analysis
Domestic-content mandates in Japan and the United States are reshaping sourcing patterns for master cell bank characterization services and specialized formulation talent. Manufacturing gravity centers on Switzerland, Germany, and the United States for Trk receptor engineering and blood-brain barrier shuttle domain development. Recombinant production draws from Chinese hamster ovary cell lines, yeast expression systems, and glycosylation-modified substrates. Single-source vulnerability concentrates in specialized academic contract research organization clusters with blood-brain barrier delivery expertise. Distribution runs through cold-chain logistics networks anchored by tertiary neurology centers and preferred site trial networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA PRIME scheme regulatory acceleration in Germany contrasts with FDA orphan drug designation cost structures in the United States, creating divergent capital efficiency profiles.
For Market Incumbents: Deploy receptor selectivity engineering capabilities to extend therapeutic index advantages against emerging biosimilar threats. Captive mammalian cell culture capacity in Basel and Boston insulates against bioprocessing subscription model commoditization. Prioritize preferred site network consolidation in Heidelberg and Tokyo to compress patient recruitment timelines for amyotrophic lateral sclerosis programs. For New Entrants and Emerging Players: Begin with traumatic brain injury indications where orphan drug incentives and absence of approved disease-modifying therapies create white-space access. Intranasal delivery device compatibility represents the most penetrable technical wedge against intravenous incumbents. Pursue direct institutional partnerships with military trauma centers in Maryland rather than traditional contract research organization site selection. For Investors and Strategic Acquirers: Valuations sit cheapest among recombinant protein engineering boutiques with TrkC selectivity expertise and blood-brain barrier shuttle domain IP. Long-term viability hinges on successful navigation of ICH Q5D compliance timelines and payer evidence requirements for neuroregenerative claims. Monitor EMA PRIME scheme designation velocity as the critical inflection signal for regulatory pathway de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| Intranasal Device Formulation Partnership | Blood-brain barrier bypass technology enables outpatient Alzheimer's management expansion beyond hospital infusion suites. |
| EMA PRIME Scheme Alignment | Priority medicines designation compresses assessment timelines for amyotrophic lateral sclerosis candidates. |
| Preferred Site Network Consolidation | Direct institutional partnerships in Germany and Japan displace traditional contract research organization patient recruitment. |
| Master Cell Bank Characterization Investment | ICH Q5D compliance capabilities extend preclinical development schedules by 18-24 months for competitors without captive capacity. |
| Receptor Selectivity Engineering Program | TrkB versus TrkC differentiation resolves cross-reactivity toxicology challenges in neurotrophin-4 traumatic brain injury development. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at German and Japanese hospital systems, and payer access specialists grounded qualitative insights. Secondary validation drew from FDA orphan drug designation filings, EMA PRIME scheme submissions, ClinicalTrials.gov protocol registries, and ISO 13485 certification databases. Bottom-up neurotrophin procurement volume estimates triangulated against top-down biopharmaceutical R&D expenditure allocations across the analysis window.
Segmentation outputs by product type, delivery mode, application, and end user fed into analytical framework construction over the projection horizon. CAGRs derived from patient population epidemiology, regulatory approval pathway velocity assumptions, and reimbursement timeline probability weightings. Forecast inputs incorporated blood-brain barrier delivery technology readiness levels and mammalian cell culture yield improvement curves.
Caveats apply where ICH Q5D compliance timeline extensions, payer neuroregenerative evidence requirement escalations, or glycosylation yield variability could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market