
 Catering Equipment Market | 2026-2036
Catering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Catering Equipment Market Intelligence
The rise of equipment-as-a-service and leasing models is reshaping competitive positioning for smaller operators by reducing upfront capital expenditure. This shift allows established players with strong financial backing to offer flexible procurement options. Middleby Corporation leverages its extensive brand portfolio to serve diverse applications from fast-food to fine dining. Meanwhile, Rational AG specializes in high-performance combi-ovens, and Hobart Corporation sustains its market presence through a focus on durable food preparation and warewashing systems.
Catering equipment encompasses a range of commercial-grade appliances engineered for high-volume food production, storage, and service. These products, often constructed from 304-grade stainless steel for hygiene and durability, are designed to withstand the rigorous demands of professional kitchens. Their primary purpose is to ensure food safety, operational efficiency, and consistency in culinary output. Cooking equipment constitutes the largest product segment, while specialized beverage equipment represents a fast-growing category, particularly for hotels and corporate cafes.
The market operates within a strict regulatory framework that dictates product safety and sanitation standards. Compliance with NSF International standards is critical for market access in the United States, while CE marking is mandatory for products sold in the European Union. In China, GB standards for energy efficiency impact appliance design. Future profitability depends on successfully integrating IoT connectivity for remote diagnostics and predictive maintenance across equipment lines.
Market Dynamics
The convergence of stringent energy efficiency regulations and the demand for connected, smart kitchens is the central force shaping the catering equipment market. This dual pressure compels manufacturers to innovate beyond basic functionality toward integrated, sustainable systems that improve operational oversight and reduce resource consumption.
Growth Catalysts
- EU Green Deal Implementation:This policy framework accelerates demand for energy-efficient appliances, pushing manufacturers to adopt advanced insulation and heat recovery systems to meet new performance standards for the hospitality sector.
- Ghost Kitchen Expansion:The proliferation of delivery-only food service models creates concentrated demand for compact, multi-functional cooking stations and high-speed warewashing equipment designed for continuous, high-volume operation.
- Advanced Material Adoption:The use of improved 304-grade stainless steel alloys and composites enhances equipment durability and hygiene, meeting stricter food safety protocols in institutional catering and healthcare settings.
Market Restraints
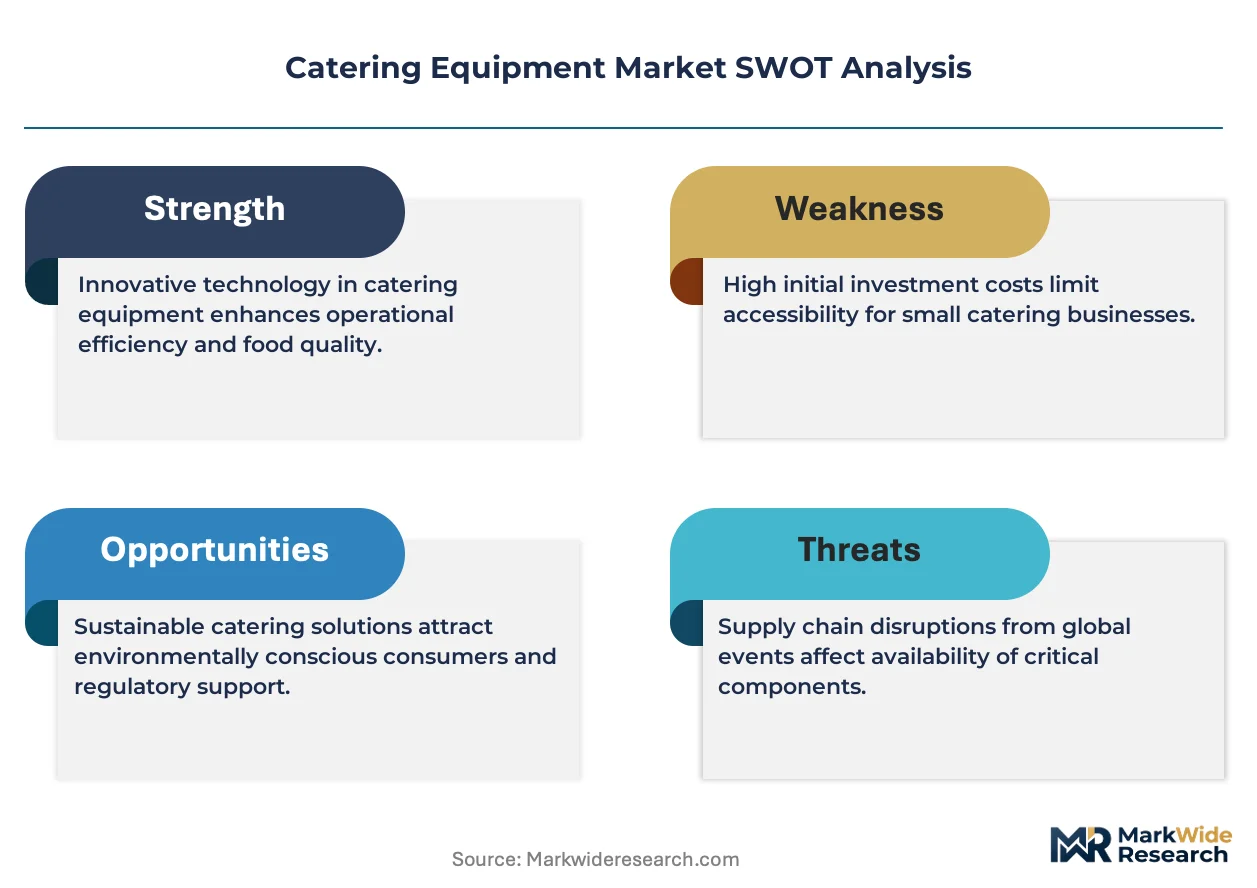
- Stainless Steel Price Volatility:Fluctuations in the global price of nickel and chromium, key components of 304-grade stainless steel, create unpredictable manufacturing costs and pressure profit margins for equipment producers.
- Complex NSF Certification:The rigorous and lengthy process for obtaining NSF International sanitation certification for new equipment designs can delay market entry in the United States, acting as a barrier for smaller innovators.
- Rise of Used Equipment Markets:A growing secondary market for refurbished commercial kitchen equipment offers a lower-cost alternative for new restaurant startups, diverting some demand from new, premium-priced products.
Strategic Opportunities
- Hospitality Sector Recovery in Southeast Asia:Rebounding tourism and hospitality investment in urban centers like Bangkok and Singapore present an opportunity to supply new hotels and restaurants with modern, integrated kitchen systems.
- Predictive Maintenance Services:Integrating IoT sensors into equipment to offer subscription-based remote diagnostics and predictive maintenance services creates a new, recurring revenue stream beyond the initial hardware sale.
- Specialized Beverage Stations:Demand for premium beverage options in corporate cafes and hotels opens a niche for developing automated, high-end coffee, tea, and infused water dispensing systems.
Industry Challenges
- Shortage of Skilled Technicians:A lack of technicians trained in servicing IoT-enabled and electronically complex modern catering equipment leads to longer downtimes and customer dissatisfaction, impacting brand reputation.
- Legacy System Integration:Integrating new, smart appliances with older, non-connected kitchen management systems in existing commercial kitchens poses significant technical and software compatibility challenges for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catering Equipment Market |
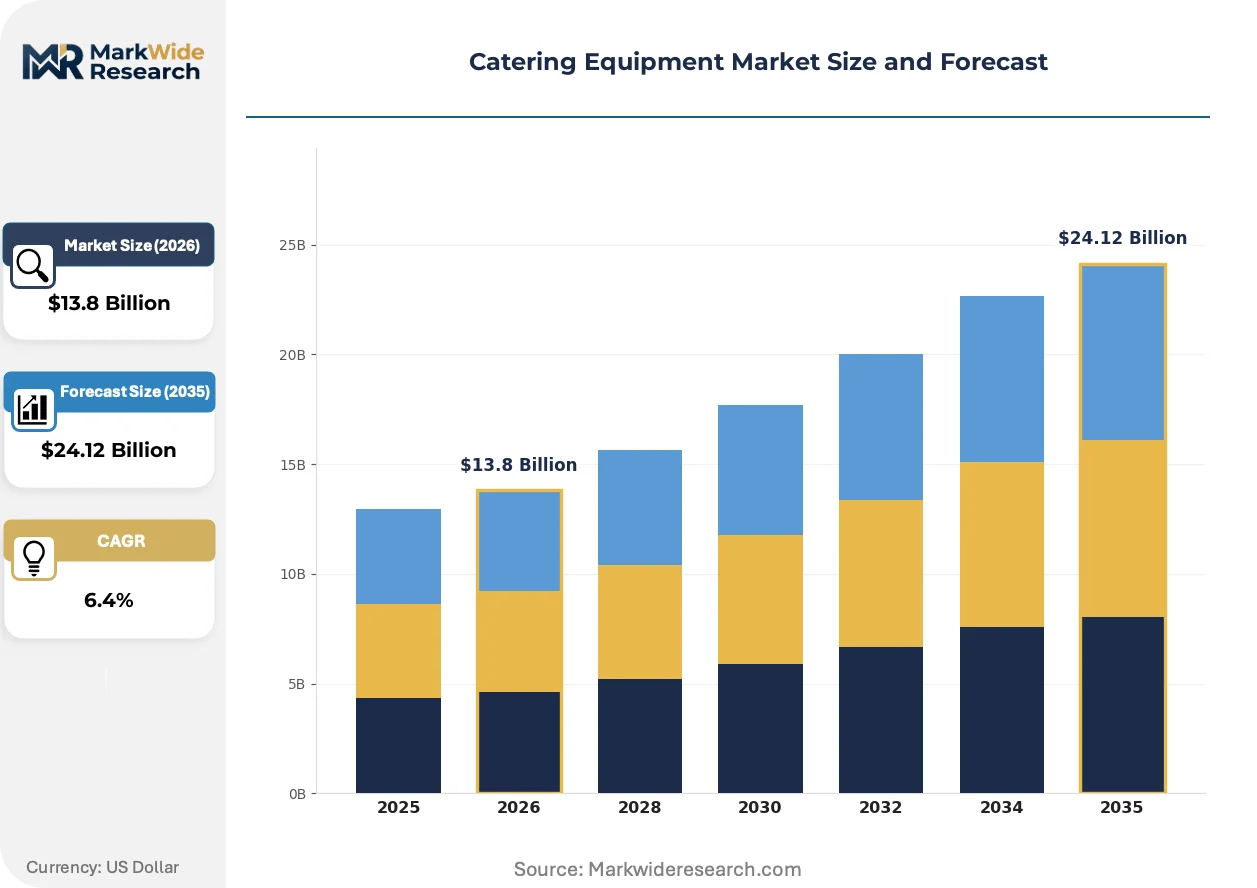
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Equipment, Refrigeration Equipment, Food Preparation Equipment, Serving Equipment, Beverage Equipment Application: Restaurants, Hotels, Event Catering, Cafeterias, Institutional Dining End User: Commercial Kitchens, Food Trucks, Catering Companies, Corporate Cafes Distribution Channel: Direct Sales, Dealers & Distributors, Online Retailers, Wholesalers |
| Companies Covered | Electrolux Professional, Welbilt, Ali Group, Blodgett, Fagor Commercial, Middleby Corporation, Rational AG, Vulcan, Hobart Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catering Equipment Market Strategic Shifts & Innovations
Automation and sustainability are converging to redefine equipment functionality in the catering industry. This evolution moves the market from standalone hardware toward integrated solutions that prioritize operational efficiency and resource conservation.
Digital touchscreen interfaces with pre-programmed cooking cycles are replacing analog knobs and dials, providing precise control over culinary processes. Chain restaurants and large caterers are rapidly adopting this technology to ensure menu consistency. Consequently, equipment design is migrating from user-dependent manual operation to software-driven, automated execution, reducing staff training requirements.
The U.S. Environmental Protection Agency's ENERGY STAR certification for commercial food service equipment is a critical procurement standard, setting strict energy and water consumption limits. Compliance incentivizes manufacturers to invest in technologies like heat-reclamation systems and improved insulation. The institutional sector, including schools and hospitals, is most affected, often mandating rated equipment in public tenders to meet sustainability goals.
End-users now favor flexible, subscription-based access to equipment over outright capital purchases, bundling hardware and maintenance into an operational expense. This equipment-as-a-service model disrupts traditional distributor-led sales, allowing manufacturers to build direct customer relationships. The trend is most visible among independent restaurants and food-truck operators in North American and European cities.
Catering Equipment Market Segmentation
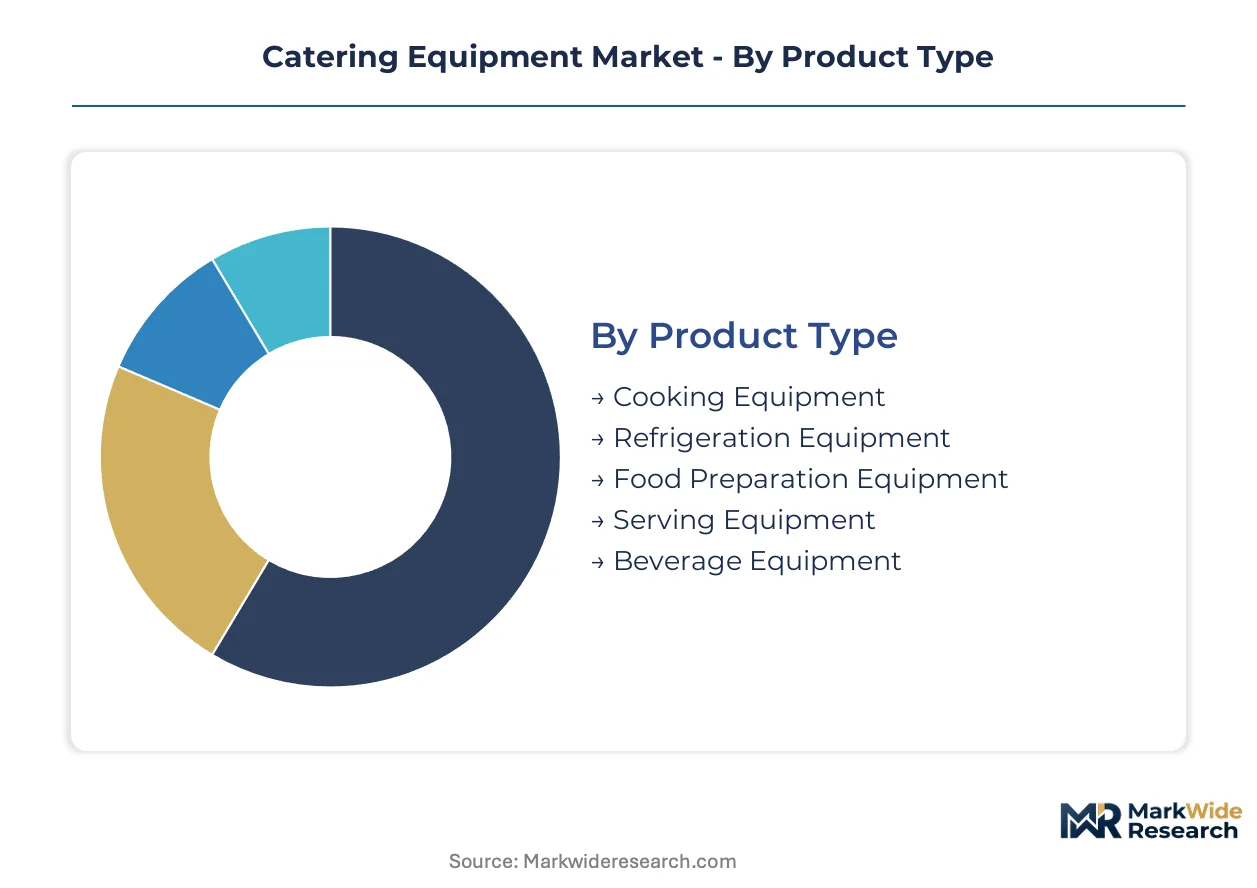
Segmenting the catering equipment market clarifies the diverse operational needs across the food service industry. This granular analysis provides insights into specific product requirements, application contexts, end-user procurement behaviors, and optimal distribution strategies. Understanding these distinctions is crucial for manufacturers and suppliers to align offerings with market demands.
Product Type:
Equipment within this category exhibits varying replacement cycles, influencing capital expenditure planning for operators.
- Cooking Equipment:Includes ovens, ranges, fryers, and griddles, engineered for continuous high-temperature operation. Ghost kitchens exhibit concentrated demand, driven by the need for continuous, high-volume food production.
- Beverage Equipment:Comprises automated coffee machines, juice dispensers, and specialized infused water systems. Hotels and corporate cafes in Southeast Asian urban centers drive demand for premium beverage options.
- Refrigeration Equipment:Stores perishable ingredients and prepared foods at precise temperatures to maintain food safety.
- Food Preparation Equipment:Encompasses mixers, slicers, and processors, essential for efficient ingredient handling in commercial kitchens.
- Serving Equipment:Includes hot holding units, display cases, and buffet lines, designed for maintaining food quality during service.
Cooking Equipment dominates the installed base. Beverage Equipment exhibits concentrated expansion.
Application:
Each application type presents distinct operational requirements and volume demands for catering equipment.
- Restaurants:Requires a full suite of equipment from cooking to warewashing, often with diverse menu capabilities. Independent restaurants in North American and European cities drive demand for flexible, subscription-based equipment models.
- Event Catering:Demands robust, often portable equipment capable of high-volume output in varied locations. The recovering hospitality sector, particularly in urban centers like Bangkok and Singapore, fuels demand for specialized event solutions.
- Hotels:Integrates equipment for multiple outlets, including fine dining, banquet services, and in-room dining.
- Cafeterias:Utilizes efficient food preparation and serving lines to handle peak service periods in corporate and educational settings.
- Institutional Dining:Focuses on high-capacity, durable equipment to serve large populations in schools and hospitals, often mandating ENERGY STAR certification.
Regulatory compliance significantly impacts equipment procurement for Institutional Dining. Event Catering equipment needs to meet diverse operational standards.
End User:
End-users exhibit varied procurement patterns, from large-scale capital expenditure to flexible leasing models.
- Commercial Kitchens:Equips dedicated professional spaces with robust, high-performance appliances for continuous operation. Established players with strong financial backing offer flexible procurement options for these large-scale operations.
- Food Trucks:Requires compact, multi-functional equipment optimized for limited space and mobile operation. The proliferation of delivery-only food service models creates specific demand for efficient, space-saving solutions.
- Catering Companies:Utilizes versatile and often portable equipment to prepare and transport food for off-site events.
- Corporate Cafes:Focuses on efficient, user-friendly equipment for high-volume beverage preparation and quick-service food options.
Innovation in IoT connectivity heavily influences equipment design for Commercial Kitchens. Food Trucks prioritize compact, multi-functional designs.
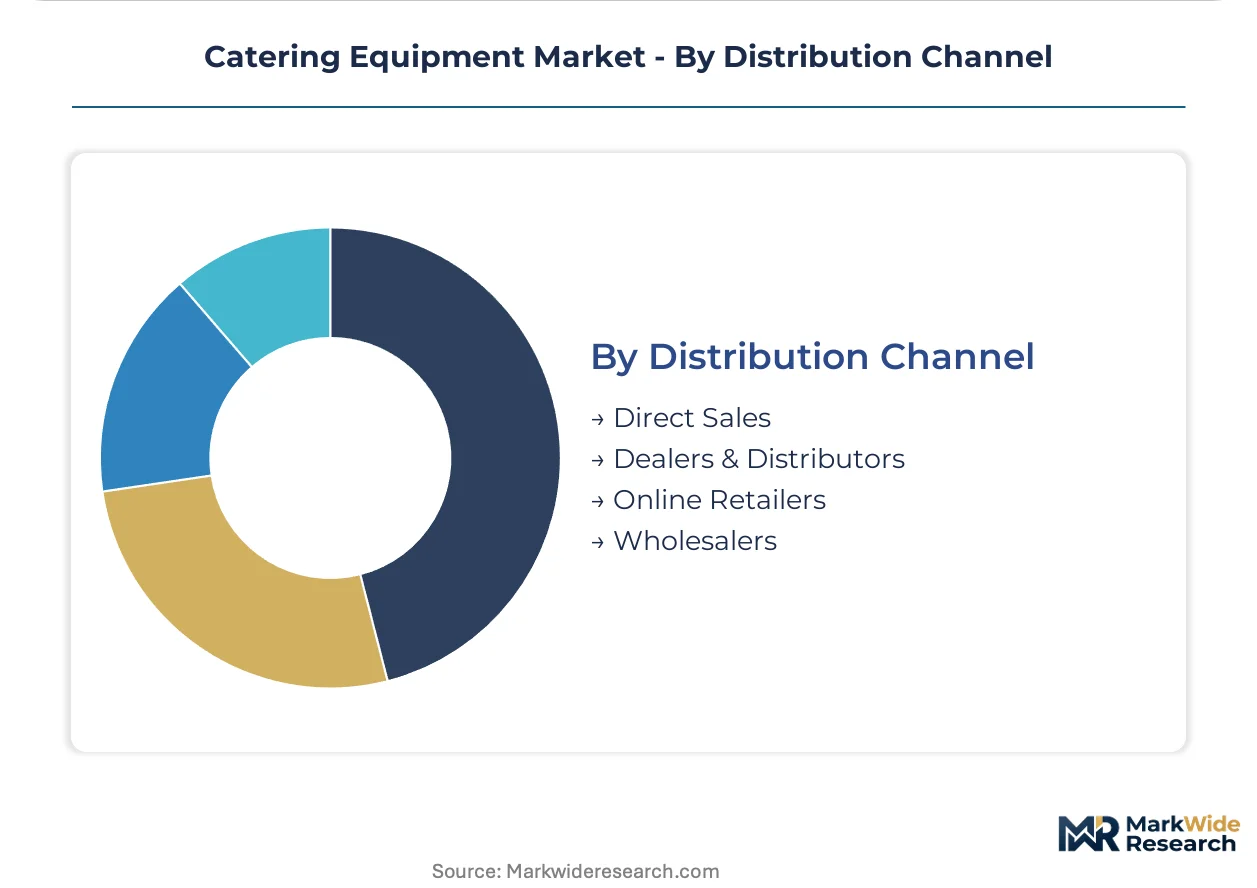
Distribution Channel:
Distribution channels determine market access and influence the speed of product delivery and service support.
- Direct Sales:Manufacturers engage directly with large institutional clients or chain accounts, often for customized solutions. This channel is critical for integrating IoT-enabled equipment and offering predictive maintenance services.
- Dealers & Distributors:These channels provide local sales, installation, and maintenance support for a wide range of equipment brands. Smaller operators rely on dealers for bundled services and access to diverse product portfolios.
- Online Retailers:Offers convenience and price comparison for standard equipment, appealing to new startups and smaller businesses.
- Wholesalers:Supplies bulk orders to larger businesses, often providing cost advantages for high-volume purchases.
The competitive dynamics favor Dealers & Distributors for broad market penetration. Direct Sales channels are gaining importance for strategic partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration varies significantly across global geographies. Urban centers in Southeast Asia are seeing a resurgence in hospitality demand, while established markets like North America drive equipment-as-a-service models. Regulatory frameworks also dictate equipment adoption rates and design parameters worldwide.
United States
Demand for compact, multi-functional cooking stations concentrates in US urban ghost kitchens. NSF International sanitation certification remains critical for market entry and product acceptance. Major metropolitan areas like New York City and Los Angeles see robust activity in both new restaurant startups and delivery-only models.
Germany
The EU Green Deal implementation accelerates demand for energy-efficient appliances across Germany's hospitality sector. Manufacturers must adopt advanced insulation and heat recovery systems to meet new performance standards. Cities such as Berlin and Munich are hubs for sustainable kitchen design and high-performance combi-oven technology.
China
Ghost kitchen expansion creates concentrated demand for high-speed warewashing equipment in Chinese megacities. GB standards for energy efficiency significantly impact appliance design and procurement decisions. Industrial zones around Guangzhou and Shanghai are centers for manufacturing and deploying new catering solutions.
Singapore
Rebounding tourism and hospitality investment in Singapore drive demand for modern, integrated kitchen systems. The country's strict food safety protocols encourage the use of advanced 304-grade stainless steel equipment. Hotels and corporate cafes in the Central Business District fuel specialized beverage equipment expansion.
United Kingdom
Independent restaurants and food-truck operators in UK cities favor flexible, subscription-based equipment access. Compliance with CE marking is mandatory for products sold within the European economic area, including the UK. London and Manchester exhibit high demand for versatile and often portable equipment for event catering.
Catering Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share, creating a dynamic competitive environment. The catering equipment market exhibits a tiered structure, with established global conglomerates alongside agile niche innovators. Strategic archetypes include full-suite providers offering comprehensive solutions, high-performance specialists focusing on specific technologies, and regional value-focused manufacturers. Portfolio diversification into complementary services and strategic partnerships for IoT integration represent dominant competitive moves across the industry.
Among the established players, Middleby Corporation exemplifies a full-suite provider, leveraging its extensive brand portfolio to serve diverse applications from fast-food to fine dining. Rational AG, meanwhile, represents a high-performance specialist, anchoring the market for advanced combi-ovens with a focus on precision and efficiency, particularly in European markets. Hobart Corporation sustains its market presence through a focus on durable food preparation and warewashing systems, occupying a position of reliability and longevity for institutional and commercial kitchens. These companies collectively influence market standards and innovation trajectories through their distinct offerings and strategic focus on specific end-user needs.
| Leading Market Players |
|---|
| Electrolux Professional |
| Welbilt |
| Ali Group |
| Blodgett |
| Fagor Commercial |
| Middleby Corporation |
| Rational AG |
| Vulcan |
| Hobart Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, experiencing fluctuating fuel surcharges, influence both the concentrated supply of catering equipment components and the downstream price differentiation for end-users. These cost dynamics impact manufacturers' ability to maintain stable pricing structures, especially for products heavily reliant on imported materials.
Pricing Analysis
Stainless steel raw material indexation underpins many cost-plus contract patterns for commercial catering equipment. Per-unit transactional models dominate sales, alongside subscription services for maintenance and IoT-enabled features. Price differentiation stems from NSF International certification and the bundling of integrated after-sales service. Pricing softness reflects the rise of used equipment markets offering lower-cost alternatives. New restaurant startups exhibit the highest price sensitivity, while large institutional buyers prioritize long-term durability and compliance.
Supply Chain Analysis
Extended payment terms offered by manufacturers to distributors facilitate the flow of catering equipment through the supply chain. Geographic supply concentrates in China, Germany, and Italy, which house major production hubs for commercial appliances. The industry relies on 304-grade stainless steel and advanced electronic components for IoT integration. Stainless steel price volatility represents a significant structural risk for equipment producers. Distribution runs primarily through established dealers and distributors, with direct sales channels serving large institutional clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The catering equipment market requires a substitution defense, as incumbents must navigate the threat posed by refurbished equipment and its lower upfront cost appeal.
For Market Incumbents:
Harden market share by aggressively expanding equipment-as-a-service models, bundling hardware with subscription-based maintenance and remote diagnostics. Invest heavily in IoT integration R&D to differentiate new products from the growing used equipment market. Streamline NSF International certification processes to accelerate market entry for innovative, compliant designs. Strengthen relationships with key distributors to ensure preferential channel access and service support.
For New Entrants and Emerging Players:
Urban centers in developing Southeast Asian economies present significant underpenetration for modern catering solutions. Target food trucks and corporate cafes with compact, multi-functional equipment designed for efficiency in limited spaces. Offer flexible leasing models to lower upfront capital expenditure barriers for new restaurant startups. Focus on specialized beverage stations as a niche entry point, capitalizing on demand for premium coffee and infused water systems.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core appliance divisions. The long-term viability of this market hinges on integrating sustainability and smart technology into core offerings. Seek out niche specialists in energy-efficient or IoT-enabled equipment with strong intellectual property portfolios. Practitioners should monitor the growth in subscription service revenue as a key inflection indicator for future profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Development | Enhances remote diagnostics capabilities for Hobart Corporation. |
| Equipment-as-a-Service Expansion | Reduces upfront capital expenditure for independent restaurants. |
| Advanced Material R&D | Improves equipment durability for institutional dining applications. |
| Energy Efficiency Certification | Meets EU Green Deal standards for German manufacturers. |
| Specialized Beverage System Launch | Captures demand from corporate cafes in Singapore. |
Research Approach
A spread of perspectives from commercial kitchen operators, equipment manufacturers, distributors, and hospitality consultants converged on the working assumptions for this study. Primary interviews with industry stakeholders were conducted, alongside secondary validation from sources including NSF International standards, EU Green Deal policy documents, national trade association reports, and company financial filings. Both bottom-up and top-down triangulation methods were applied to ensure data consistency.
The analytical framework modeled demand-supply balance across the modeling period, segmenting by product type, application, end-user, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical performance and projected market dynamics, factoring in key inputs such as hospitality sector investment trends and stainless steel commodity prices.
Practitioners should monitor geopolitical events, shifts in raw material costs, and new regulatory mandates for early signals of market deviation. Forecasts reflect documented assumptions regarding market conditions and technological progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Multi Cooker Market