
 Commercial Ventless Cooking Equipment Market | 2026-2036
Commercial Ventless Cooking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Ventless Cooking Equipment Market Intelligence
The EPA's commercial kitchen emissions framework is realigning buyer priorities toward greaseless cooking architectures that eliminate traditional hood infrastructure. Middleby Corporation leverages its broad manufacturing scale to dominate ventless oven distribution across North American foodservice channels. RATIONAL sustains technology leadership through precision-controlled steam and convection systems purpose-built for confined commercial footprints. Alto-Shaam anchors the premium segment with low-temperature holding and cook-and-hold equipment that minimizes ventilation requirements in institutional settings.
Commercial ventless cooking equipment comprises self-contained appliances utilizing infrared, induction, or advanced filtration technologies to capture and treat cooking effluent internally without external ductwork, typically rated for grease-laden vapor removal through EPA Method 202 compliance. These systems serve operators facing spatial constraints, utility limitations, or prohibitive hood installation costs in dense urban environments. Induction cooktops command the strongest margin pools due to precision energy delivery and minimal residual heat, while electric grills represent the fastest-growing product category as protein-focused quick service concepts expand ventless footprints. Steam cookers retain stable demand within institutional end users where nutrient retention and water-based effluent management align with health department protocols.
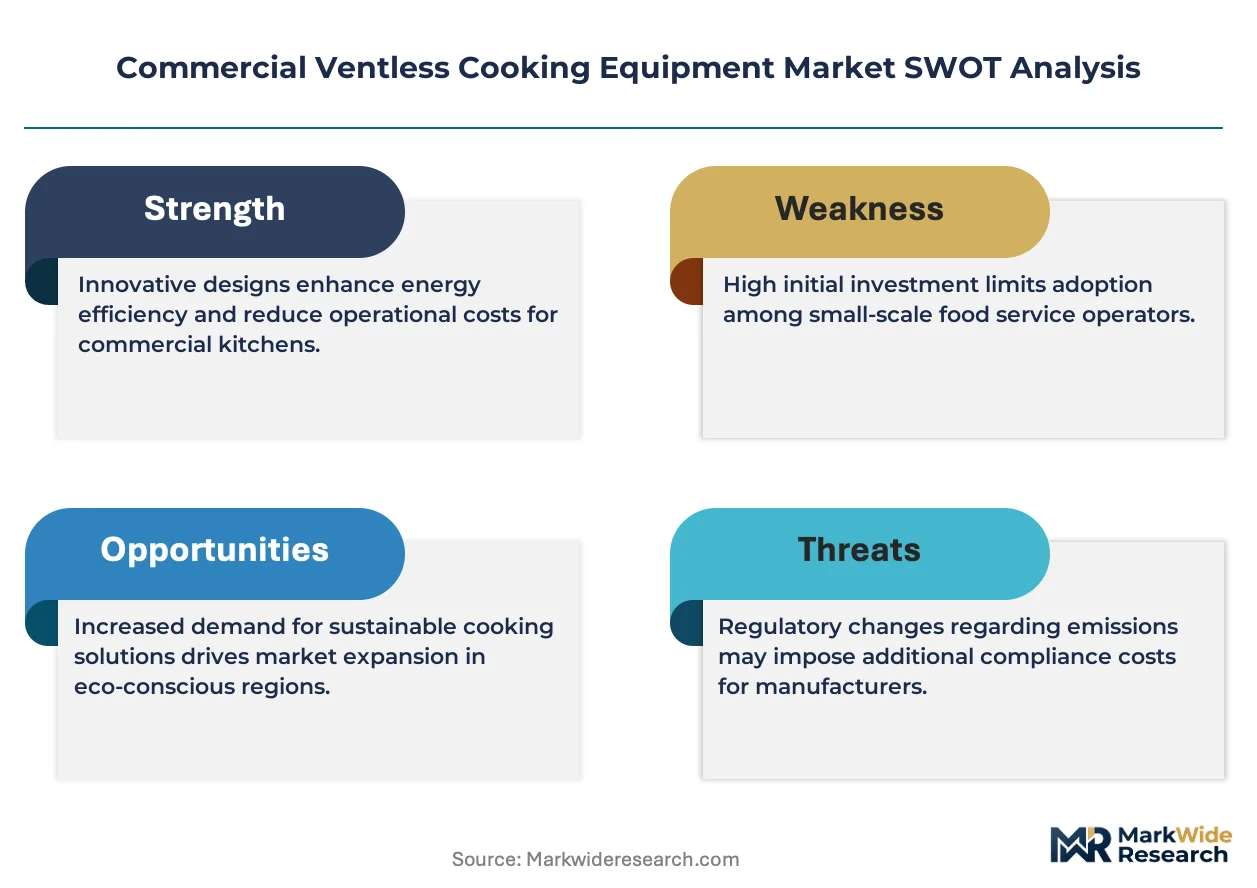
FDA food code provisions on cooking surface temperatures interact with municipal fire authority interpretations of NFPA 96 to create uneven approval landscapes across jurisdictions, directly constraining where ventless equipment deploys. The Department of Energy's commercial kitchen equipment standards further shape product development roadmaps by establishing minimum efficiency thresholds for electrically heated alternatives. Stakeholders must monitor evolving local fire code amendments and utility rebate programs, as these dual levers determine payback periods and therefore adoption velocity in the channel.
Market Dynamics
Urban density restrictions across major metropolitan areas are compressing kitchen footprints and eliminating traditional hood infrastructure, forcing operators toward self-contained effluent management systems that satisfy municipal fire codes without external ductwork.
Growth Catalysts
- EPA Method 202 compliance frameworks:Federal grease-laden vapor standards are mandating internal filtration architectures, accelerating equipment replacement in legacy commercial kitchens.
- Quick service restaurant retrofit cycles:Compact urban locations are prioritizing ventless configurations to reclaim ceiling space and reduce utility connection costs.
- Induction energy delivery systems:Precision thermal control and minimal residual heat generation are expanding operator acceptance of electric alternatives to gas-fired equipment.
Market Restraints
- Stainless steel and rare-earth magnet input volatility:Induction cooktop manufacturing faces cost pressure from concentrated rare-earth supply chains.
- NFPA 96 interpretation variance:Municipal fire authority discretion creates uneven approval landscapes, constraining deployment in certain jurisdictions.
- Traditional gas infrastructure sunk costs:Existing hood and duct investments in established foodservice operations delay ventless adoption timelines.
Strategic Opportunities
- Department of Energy commercial kitchen equipment rebates:Utility incentive programs are compressing payback periods for electrically heated alternatives in qualifying districts.
- Ghost kitchen and delivery-only concepts:High-throughput, low-footprint operations are emerging as ideal deployment environments for ventless protein-focused equipment.
- Infrared and advanced filtration convergence:Hybrid thermal and mechanical effluent capture systems are opening applications previously restricted to hooded configurations.
Industry Challenges
- Certification timeline compression:EPA Method 202 and local fire code dual approval processes extend product launch schedules.
- Specialized technician scarcity:Infrared emitter and advanced filtration maintenance requires skills absent from standard foodservice equipment service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Ventless Cooking Equipment Market |
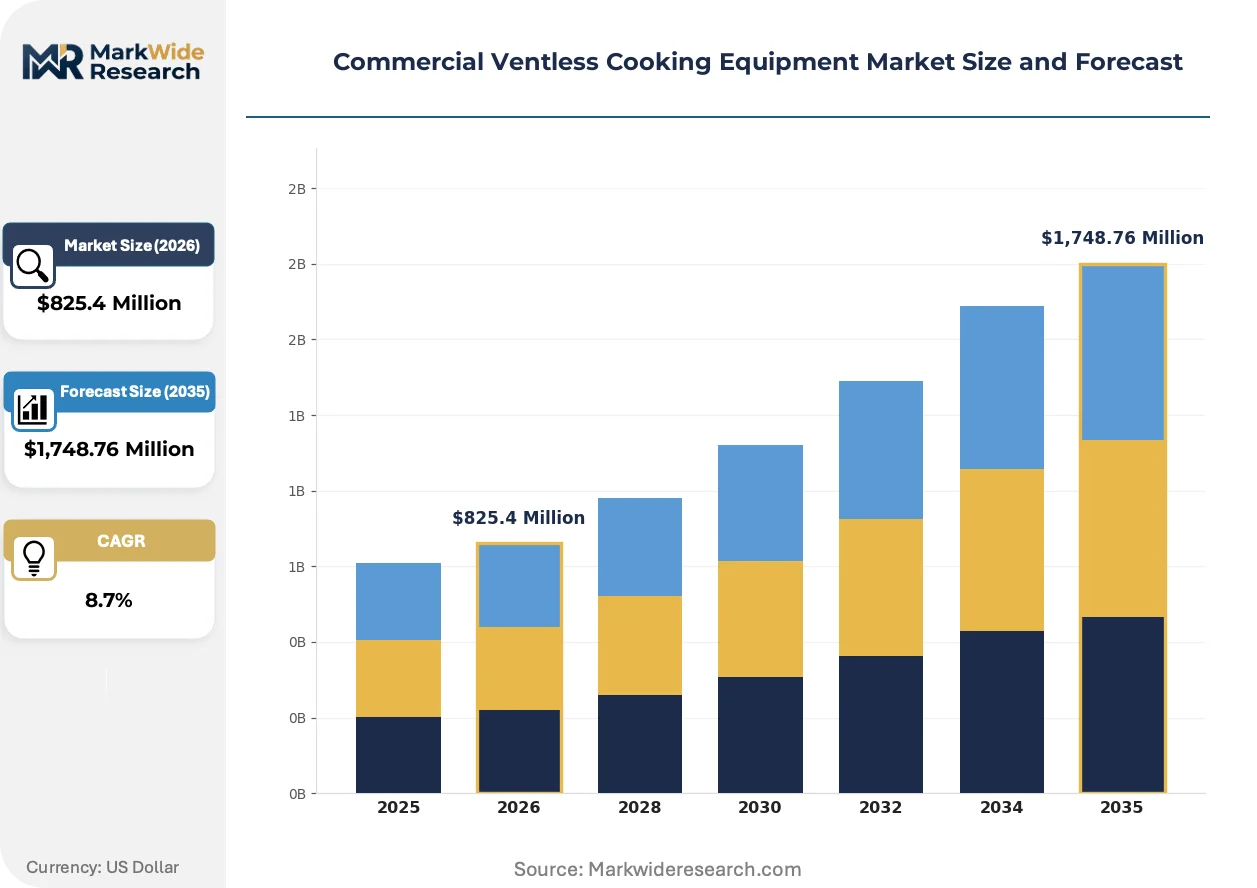
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Ovens, Induction Cooktops, Electric Grills, Convection Microwaves, Steam Cookers Technology: Infrared Heating, Induction Heating, Convection Heating, Microwave Technology, Steam Generation Application: Quick Service Restaurants, Catering Services, Food Trucks, Institutional Kitchens, Convenience Stores End User: Hospitality Chains, Educational Institutions, Correctional Facilities, Corporate Cafeterias, Event Venues |
| Companies Covered | Middleby Corporation, Alto-Shaam, RATIONAL, Antunes, Wells, Welbilt, Hatco Corporation, MTI Products, Giles Foodservice Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Ventless Cooking Equipment Market Strategic Shifts & Innovations
Equipment architecture is fragmenting into configurable subsystems that operators can scale and reposition without infrastructure modification, fundamentally altering how kitchen layouts are engineered and financed.
Electromagnetic induction cooking systems are modularizing commercial kitchen design by eliminating combustion ventilation requirements entirely. Mid-scale independent restaurants are adopting these platforms fastest, driven by lease restrictions in converted retail spaces. The technology is modularizing equipment procurement from fixed capital investments toward reconfigurable operational assets.
EPA commercial kitchen emissions guidelines are tightening grease-laden vapor thresholds, forcing manufacturers to integrate secondary filtration stages. This regulatory pressure is elevating R&D allocation toward catalytic oxidation and electrostatic precipitation technologies. Quick service operators in dense urban districts are responding by front-loading replacement cycles to preempt compliance deadlines.
Leasing and equipment-as-service arrangements are displacing outright purchase in capital-constrained segments. Ghost kitchen operators and mobile foodservice concepts are driving this shift, prioritizing operational flexibility over asset ownership. This pattern concentrates visibly in converted warehouse districts where tenant turnover and layout reconfiguration occur quarterly.
Commercial Ventless Cooking Equipment Market Segmentation
Segmentation in commercial ventless cooking equipment reveals how capital deployment, regulatory exposure, and operational constraints reshape procurement patterns across foodservice verticals. Equipment buyers face divergent approval pathways and utility rebate eligibility depending on product-technology combinations and installation geography.
Product Type:
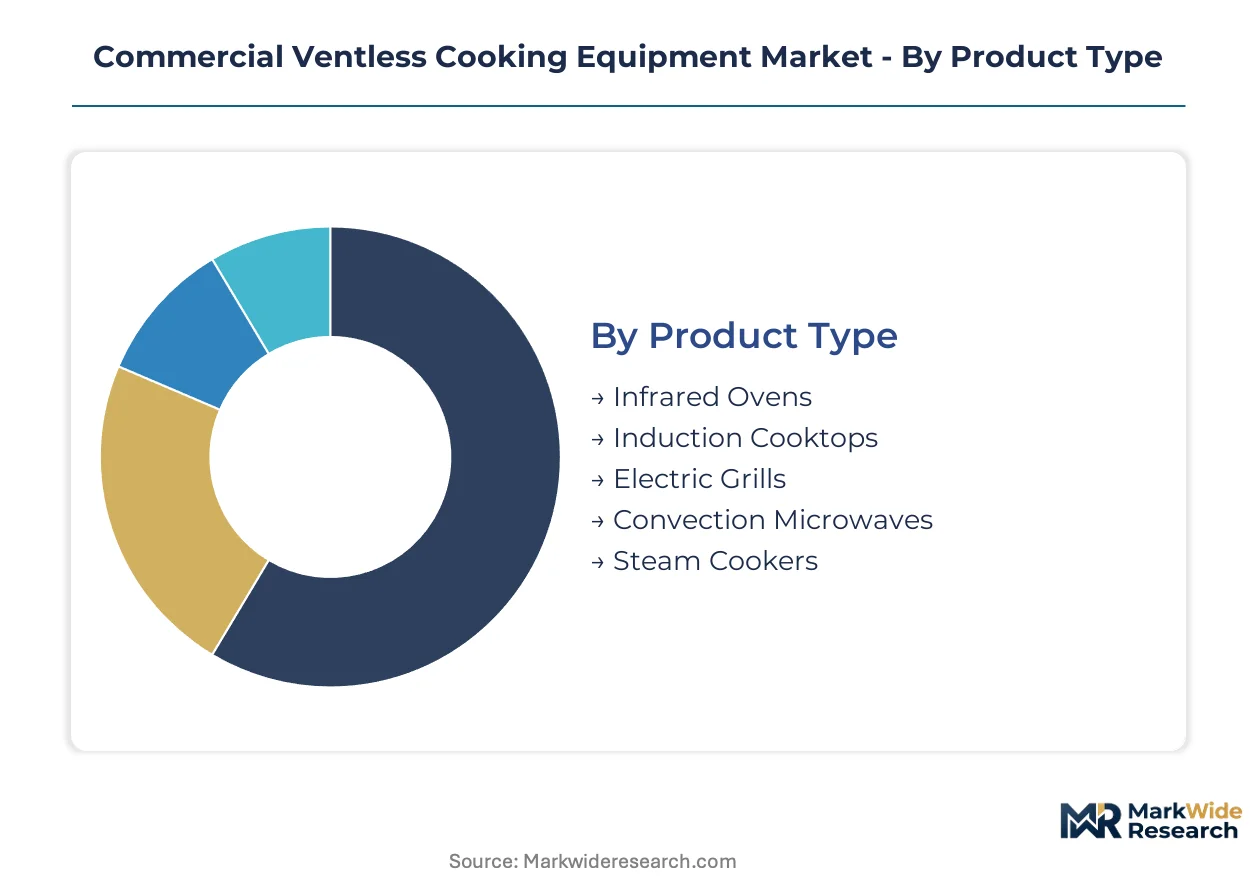
Capital-intensity varies sharply across product categories, with induction cooktops requiring the highest upfront investment due to rare-earth magnet assemblies and precision control electronics, while convection microwaves occupy the entry tier.
- Induction Cooktops:Electromagnetic coil systems deliver instantaneous thermal response with 90%+ energy conversion efficiency. Demand clusters in urban quick service restaurants where lease restrictions prohibit gas infrastructure and operators prioritize reclaimable ceiling space. EPA Method 202 compliance is inherent, eliminating secondary filtration costs.
- Infrared Ovens:Quartz or ceramic emitter arrays generate radiant heat for rapid surface browning without convective airflow. Deployment concentrates in high-throughput protein-focused concepts across dense metropolitan districts where hood replacement costs exceed equipment purchase price. Municipal fire code variance creates uneven adoption timelines.
- Electric Grills:Contact and open-plate configurations serve compact footprints in delivery-only kitchens.
- Convection Microwaves:Combined forced-air and microwave energy reduces cook times for reheating applications in convenience stores.
- Steam Cookers:Boilerless and generator-based systems retain institutional demand within educational and healthcare foodservice for nutrient preservation.
Most installed capacity flows through induction cooktops. Expansion is steepest in electric grills.
Technology:
Technology selection determines compliance burden and operational flexibility, with infrared and induction platforms offering the cleanest path through EPA grease-laden vapor standards.
- Induction Heating:Alternating magnetic fields induce eddy currents in ferrous cookware, eliminating combustion byproducts entirely. Quick service operators in converted retail spaces favor this architecture for its minimal residual heat and reduced HVAC load. Utility rebate programs in qualifying districts compress payback periods.
- Infrared Heating:Electromagnetic radiation in the near-to-mid spectrum penetrates food surfaces for rapid sear development. Ghost kitchen operators deploy these systems for protein throughput without ventilation infrastructure. Filtration integration requirements vary by jurisdiction.
- Convection Heating:Forced-air circulation achieves temperature uniformity for baking applications.
- Microwave Technology:Dielectric heating excites water molecules for rapid reheating cycles.
- Steam Generation:Boiler-based or boilerless water vapor systems serve health-code-sensitive institutional environments.
Technology mix tilts toward induction and infrared in new construction. Microwave and convection dominate retrofit replacements.
Application:
Application segmentation tracks kitchen footprint constraints and throughput requirements, with the most compact operational models driving ventless specification.
- Quick Service Restaurants:High-volume, limited-menu operations in urban cores face the most severe spatial restrictions. Chains retrofit legacy locations with ventless equipment to eliminate hood maintenance and reclaim vertical space for storage. EPA compliance deadlines accelerate replacement cycles.
- Food Trucks:Mobile operations with zero ductwork tolerance represent pure-play ventless demand. Induction and infrared systems dominate due to electrical infrastructure availability and fire authority permitting simplicity. Generator capacity limits constrain equipment selection.
- Catering Services:Event-based and commissary operations prioritize equipment portability.
- Institutional Kitchens:Schools, hospitals, and correctional facilities balance volume with regulatory scrutiny.
- Convenience Stores:Prepared food expansion in petroleum retail drives compact equipment demand.
Application concentration sits with quick service restaurants. Food trucks are gaining share fastest.
End User:
End user procurement authority varies from centralized corporate specification to decentralized facility management, reshaping vendor access and contract structure.
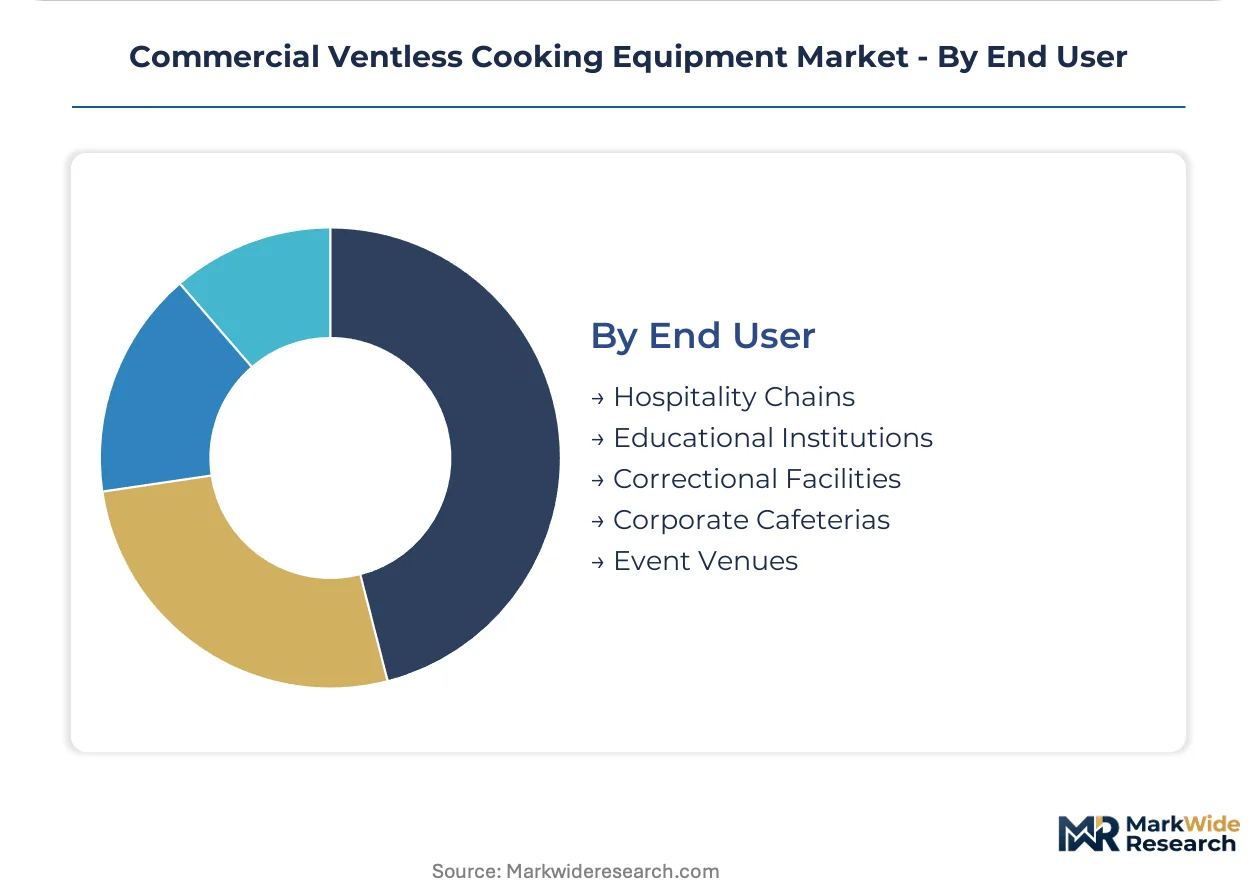
- Hospitality Chains:Corporate engineering teams standardize equipment platforms across hundreds of locations. Ventless specifications proliferate in airport, urban hotel, and lifestyle brand portfolios where construction cost reduction outweighs operational preference. National accounts negotiate service-inclusive pricing.
- Corporate Cafeterias:Contract foodservice management companies control procurement for Fortune 500 campuses. Sustainability mandates and LEED certification targets favor electric ventless alternatives to gas-fired equipment. Lease structures in suburban office parks vary in hood infrastructure provision.
- Educational Institutions:K-12 and university foodservice directors balance student nutrition guidelines with capital budget constraints.
- Correctional Facilities:Security protocols and 24/7 operational requirements shape equipment durability specifications.
- Event Venues:Stadiums, arenas, and convention centers deploy ventless for temporary kitchen builds.
End user spend concentrates in hospitality chains. Corporate cafeterias show the steepest specification shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial ventless cooking equipment industry traces its commercial scaling to post-war American foodservice modernization, when compact kitchen designs first eliminated external ductwork in urban diners. European regulatory frameworks later codified grease-laden vapor standards, while Asian manufacturing hubs developed cost-optimized induction platforms. Today's demand geography reflects this tripartite heritage: mature specification markets in North America and Western Europe, rapid retrofit cycles in dense Asian megacities, and emerging adoption across Middle Eastern hospitality developments.
United States
Urban density restrictions in Manhattan, San Francisco, and Chicago compress kitchen footprints and prohibit traditional hood infrastructure. The EPA's commercial kitchen emissions guidelines mandate EPA Method 202 compliance for grease-laden vapor capture, accelerating equipment replacement in legacy operations. Quick service restaurant chains in Los Angeles and Miami retrofit locations to reclaim ceiling space and reduce utility connection costs.
Germany
Energy efficiency mandates under the EU Green Deal favor electrically heated alternatives to gas-fired equipment in commercial foodservice. The country's national fire safety regulator enforces strict ventilation requirements that ventless architectures satisfy through internal filtration. Equipment specification concentrates in Bavaria's hospitality clusters and North Rhine-Westphalia's corporate cafeteria networks.
China
Dual carbon goals drive municipal governments in Shanghai and Shenzhen to restrict gas infrastructure in new commercial developments. The national standards administration certifies ventless platforms for grease-laden vapor removal in dense urban districts. Ghost kitchen operators in Beijing and Guangzhou deploy compact ventless systems to minimize ventilation capital in converted warehouse spaces.
Japan
Fire authority interpretations of building codes create stringent ventilation requirements that infrared and induction platforms address through self-contained effluent management. The Ministry of Economy, Trade and Industry promotes energy-efficient commercial kitchen equipment through utility rebate programs. Tokyo and Osaka hospitality chains specify ventless ovens to reduce HVAC loads in high-rise hotel properties.
United Arab Emirates
Hospitality developments in Dubai and Abu Dhabi prioritize flexible kitchen designs that accommodate rapid tenant turnover and layout reconfiguration. The national food safety regulator aligns with international grease-laden vapor standards for equipment approval. Airport and hotel foodservice operations in the emirates deploy ventless configurations to minimize infrastructure modification costs.
Commercial Ventless Cooking Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the commercial ventless cooking equipment landscape. The vendor base consolidates around integrated manufacturers with captive distribution networks and specialized component suppliers focused on single technology verticals. Three archetypes dominate: diversified foodservice conglomerates with broad manufacturing scale, precision thermal control specialists, and regional fabrication houses serving localized approval pathways. Competitive positioning hinges on certification timeline acceleration and service network density rather than pure manufacturing scale.
Within the diversified conglomerate tier, Middleby Corporation and Welbilt occupy positions defined by broad channel access across North American foodservice. RATIONAL exemplifies the precision-control specialist archetype through its focus on steam and convection systems. Among premium-tier equipment fabricators, Alto-Shaam anchors the low-temperature holding segment. These three companies represent distinct competitive vectors: scale-driven distribution, technology-led specification, and application-specific premium positioning.
| Leading Market Players |
|---|
| Middleby Corporation |
| Alto-Shaam |
| RATIONAL |
| Antunes |
| Wells |
| Welbilt |
| Hatco Corporation |
| MTI Products |
| Giles Foodservice Equipment |
| Others |
Cost & Logistics Intelligence
Rare-earth magnet procurement costs cascade through induction cooktop manufacturing into three distinct buyer tiers, with neodymium price volatility compressing margins most severely at the standard-equipment level while premium brands absorb fluctuations through captive sourcing arrangements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA Method 202-certified systems from basic electric alternatives and entry-level convection equipment. Price differentiation rests on certification grade and after-sales service bundling, with installation-inclusive packages commanding spreads over bare-equipment transactions. Cost compression in the standard tier is intensifying because stainless steel sheet and copper winding prices have climbed steadily. Quick service restaurant chains exhibit the highest price sensitivity, while institutional buyers with LEED mandates tolerate premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from hospitality chains, while specialized distributors serve independent restaurant retrofit projects. Manufacturing concentrates in China, Germany, and the United States, with induction coil assemblies drawing from Japanese ferrite suppliers and Chinese rare-earth processors. Supply chain risk centers on single-source vulnerability for EPA-certified filtration media. Distribution runs through captive service networks for premium brands and third-party logistics for volume-tier equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where operator specifications are migrating toward EPA Method 202-certified platforms that eliminate hood infrastructure entirely.
For Market Incumbents: Hedge against rare-earth supply disruption through backward integration into magnet recycling or long-term offtake agreements with Australian and Canadian rare-earth developers. Certification timeline acceleration represents the priority defensive lever as municipal fire code variance creates approval bottlenecks that favor established testing relationships. For New Entrants and Emerging Players: Ghost kitchen operators in converted warehouse districts present the most penetrable buyer archetype, as these capital-constrained concepts prioritize operational flexibility over brand heritage. Equipment-as-service leasing arrangements offer a differentiated go-to-market angle that bypasses incumbent distribution lock-in. For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication houses with localized approval expertise because NFPA 96 interpretation variance creates fragmented regulatory moats that resist national standardization. The acquisition target archetype is mid-scale manufacturers with EPA Method 202 certification and dense service networks in specific metropolitan corridors. The signal to watch is utility rebate program expansion in qualifying districts, which would accelerate payback periods and trigger replacement cycle front-loading.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Method 202 Certification Investment | Accelerates product launch timelines by preempting municipal fire code approval bottlenecks. |
| Backward Integration into Rare-Earth Sourcing | Stabilizes induction cooktop margins against neodymium price volatility from Chinese suppliers. |
| Equipment-as-Service Leasing Launch | Captures ghost kitchen demand from operators prioritizing flexibility over asset ownership. |
| Ghost Kitchen Channel Partnership | Secures volume commitments from delivery-only concepts in dense urban warehouse districts. |
| Utility Rebate Program Alignment | Compresses customer payback periods in qualifying districts, accelerating replacement cycles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement directors, commercial kitchen design consultants, municipal fire authority inspectors, and EPA compliance officers with secondary validation against FDA food code provisions, NFPA 96 documentation, utility rebate program filings, and trade customs data. Bottom-up equipment shipment tallies and top-down foodservice construction spending estimates were triangulated to anchor market sizing.
Historical reference periods spanning the full projection horizon established baseline penetration rates for ventless configurations across quick service, institutional, and mobile foodservice segments. The analytical framework modeled demand across product type, technology platform, application vertical, and end-user procurement authority. CAGRs were derived from segmented growth rate differentials weighted by installed base evolution. Forecast inputs incorporated municipal fire code amendment timelines and utility incentive program expansion trajectories.
Inputs from regulatory filings and equipment certification databases were available through the study window; gaps in real-time ghost kitchen operator census data introduce uncertainty bands around the delivery-only kitchen segment. Forecasts reflect assumptions regarding EPA enforcement consistency and rare-earth supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market