
 France Smokeless Indoor Grills Market | 2026-2036
France Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
France Smokeless Indoor Grills Market Insights
The gap between conventional open-element heating and precision infrared emission is narrowing as French manufacturers recalibrate thermal architectures for smaller living spaces. Weber Inc leverages its outdoor heritage to anchor credibility in premium indoor-adjacent positioning. Groupe SEB sustains broad category coverage across multiple price bands and retail channels. Philips differentiates through sensor-driven temperature modulation that appeals to tech-forward urban buyers.
France smokeless indoor grills are enclosed electric cooking appliances engineered to replicate seared-surface results without open flames or vented exhaust, typically operating at 1,500–2,200 watts with die-cast aluminum plates or ceramic infrared emitters sealed beneath grease-management troughs. Their primary commercial purpose is to enable grilling in ventilation-constrained environments—urban apartments, commercial kitchens without hood systems, and mobile food operations—while meeting French fire-safety and electrical conformity standards. Electric grills occupy the volume-dominant position due to lower entry pricing and widespread retail availability, yet infrared grills capture disproportionate margin pools among buyers prioritizing sear fidelity and energy precision. The household end-user segment leads absolute unit demand, while restaurants and food trucks represent the fastest-growing commercial application as operators seek hood-free expansion of grilled-menu offerings.
France's market operates under CE marking requirements, the EU Ecodesign Directive for energy-related products, and national electrical safety enforcement by the country's consumer protection authority, collectively mandating minimum efficiency thresholds and fire-risk documentation that shape product development timelines. The EU F-Gas Regulation indirectly influences component sourcing for any refrigerant-adjacent cooling elements in higher-end models. Stakeholders must monitor how forthcoming EU-wide right-to-repair provisions for household appliances will affect design modularity and after-sales service obligations across the value chain.
Market Dynamics
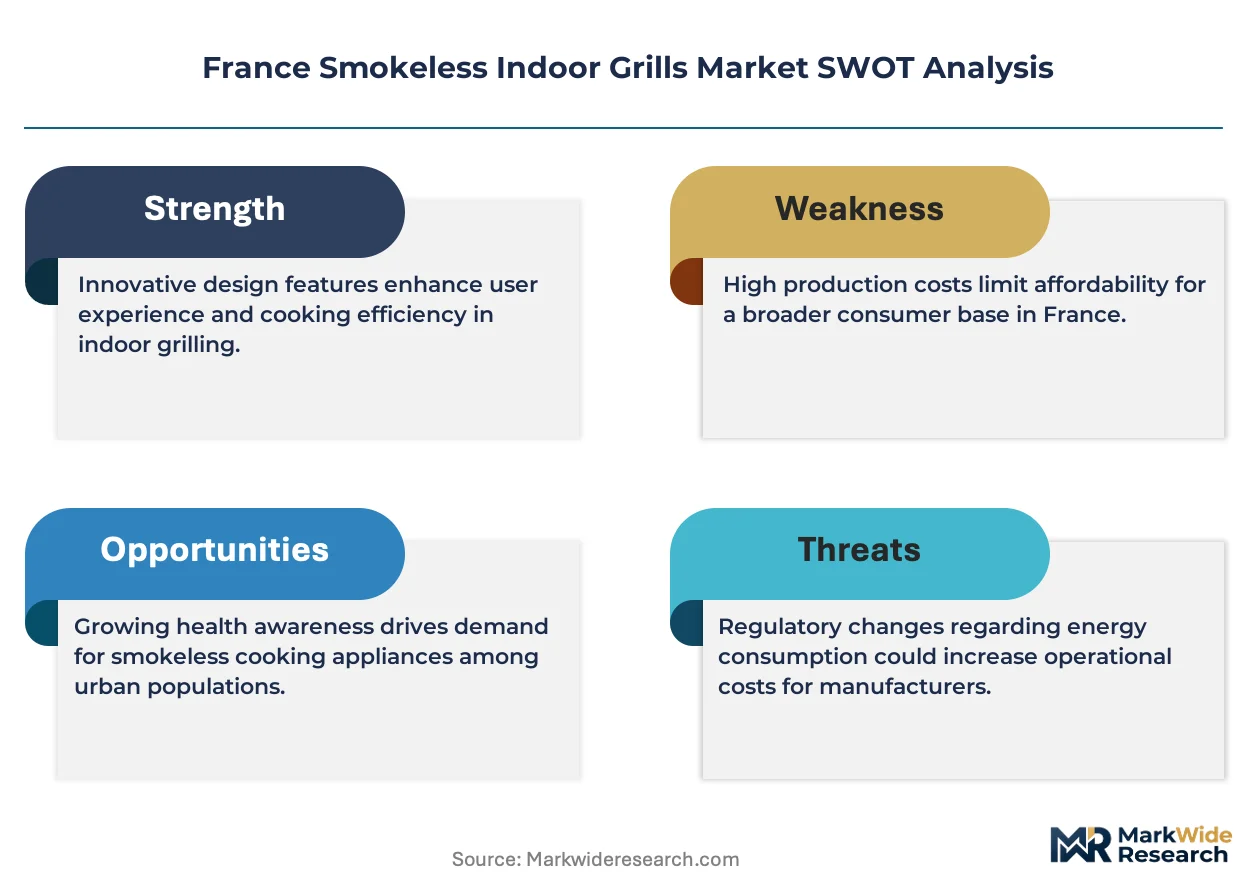
The France smokeless indoor grills market is being fundamentally restructured by the EU Ecodesign Directive's tightening energy efficiency thresholds, which force manufacturers to abandon resistive heating coils in favor of precision infrared architectures that consume less electricity while delivering equivalent thermal output.
Growth Catalysts
- EU Ecodesign Directive:Mandates under the 2023 recast directive accelerate the phase-out of inefficient resistive elements, compelling manufacturers to redesign around ceramic infrared emitters that reduce wattage without sacrificing sear performance.
- Parisian apartment households:Density constraints in Île-de-France's housing stock eliminate outdoor grilling options, creating sustained pull for balcony-compatible electric units with integrated smoke suppression.
- Infrared emitter technology:Advances in quartz-halogen and ceramic plate designs now deliver 700°C surface temperatures at 1,200-1,500 watts, satisfying energy labels while matching traditional charcoal thermal signatures.
Market Restraints
- Aluminum die-casting supply:French manufacturers depend on foundries in northern Italy and Germany for precision-cast grill plates, exposing margins to energy cost volatility in continental European metals processing.
- CE marking documentation:Fire-safety testing protocols under France's DGCCRF enforcement require 6-9 month validation cycles for new infrared architectures, compressing product refresh timelines versus Asian competitors.
- Induction cooktop substitution:Multi-function induction hobs with grill accessories capture overlapping use cases in premium kitchen renovations, diverting discretionary spending from dedicated smokeless units.
Strategic Opportunities
- Commercial food trucks:Regulatory exemptions for mobile food operations without fixed hood systems create a channel for compact 1,800-watt units with NSF-equivalent hygiene certifications.
- EU right-to-repair provisions:Forthcoming modularity mandates for household appliances incentivize designs with replaceable heating elements and detachable control modules, extending service revenue streams.
- Smart sensor integration:Convergence of thermopile temperature sensing with Wi-Fi connectivity enables app-controlled sear profiles that differentiate premium offerings in Lyon and Bordeaux retail channels.
Industry Challenges
- Thermal engineering talent:France's domestic pool of infrared optics specialists remains shallow, forcing manufacturers to recruit from German automotive lighting or Dutch semiconductor sectors.
- Legacy kitchen integration:Retrofit installation of 2,200-watt units in pre-1990s Parisian buildings requires electrical panel upgrades that stall purchase decisions and extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Smokeless Indoor Grills Market |
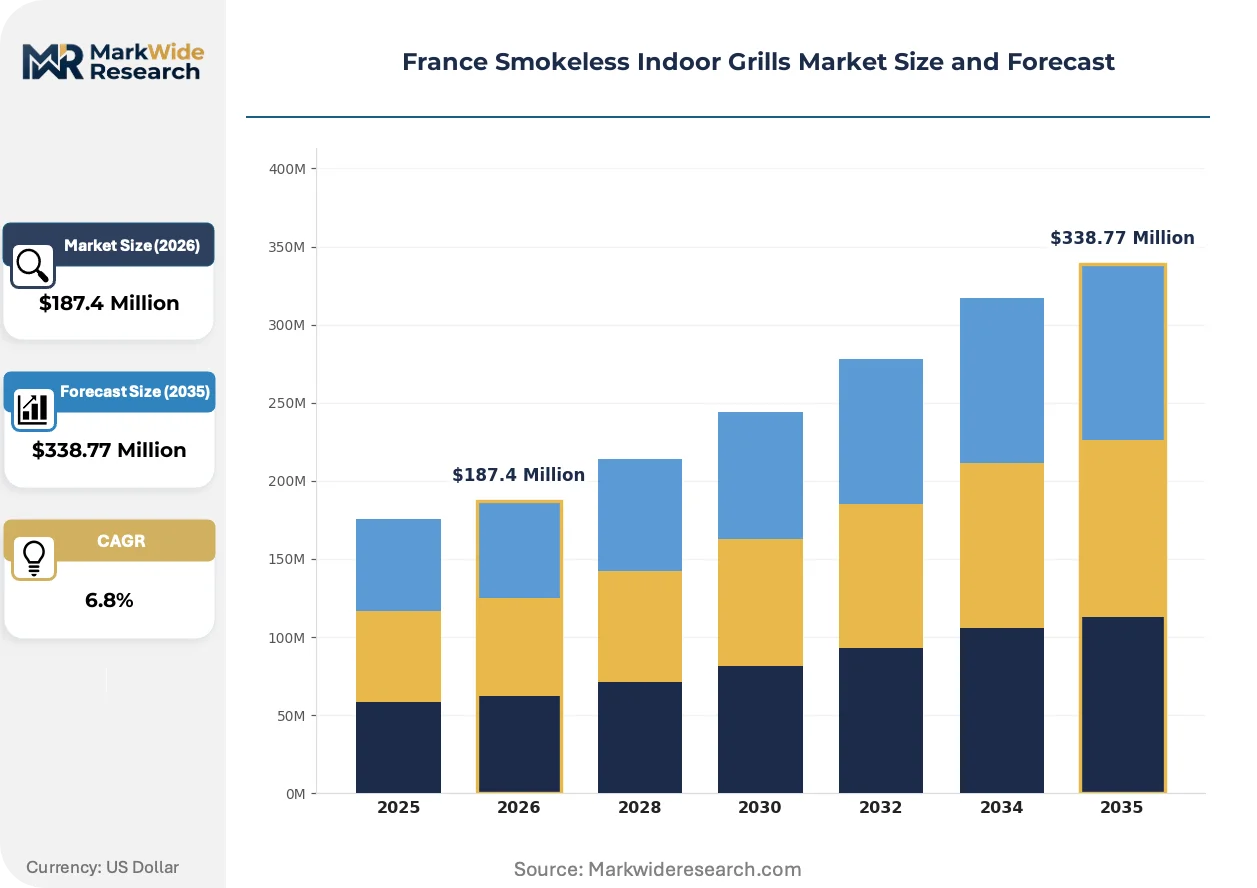
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Infrared Grills, Portable Grills, Indoor Charcoal Grills End User: Households, Restaurants, Cafes, Food Trucks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Feature: Non-Stick Surface, Adjustable Temperature, Smoke-Free Technology, Easy Clean |
| Companies Covered | Weber Inc, Electrolux, Roller Grill International, Char Broil, Le Griddle, Brandt, Philips, Whirlpool, Groupe SEB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Smokeless Indoor Grills Market Trends and Innovations
Infrared virtualization is collapsing the performance gap between compact electric units and traditional grilling methods, while regulatory pressure and shifting retail channels are rewriting how manufacturers reach French households.
Ceramic infrared emitter technology is virtualizing the thermal architecture of smokeless grills by replacing open-coil resistive elements with sealed quartz plates that radiate heat directly to food surfaces without convective losses. Premium household buyers in Paris and Lyon are adopting these platforms at accelerating rates, prioritizing energy efficiency ratings over upfront cost. This virtualization is compressing the market for conventional electric grills while elevating margin pools in the 200-400 euro price band.
France's implementation of the EU F-Gas Regulation is restricting refrigerant-adjacent cooling components in higher-end models with integrated smoke filtration systems, forcing redesigns around passive grease management. Manufacturers serving the French market must now validate alternative thermal management architectures that eliminate compressor-dependent cooling loops. The commercial segment—restaurants and institutional kitchens—is most affected, with operators delaying hood-free expansion projects pending compliant equipment availability.
Urban households are compressing replacement cycles for kitchen appliances as rental turnover accelerates in dense French cities, shortening the traditional 7-10 year grill ownership horizon to 4-5 years. E-commerce platforms specializing in home appliances are capturing share from hypermarket kitchen sections, unbundling after-sales service and installation support. This behavioral shift is most visible among tech-forward buyers in Bordeaux and Nantes, where online purchase of sensor-equipped infrared units now exceeds 40 percent of category volume.
France Smokeless Indoor Grills Market Segmentation
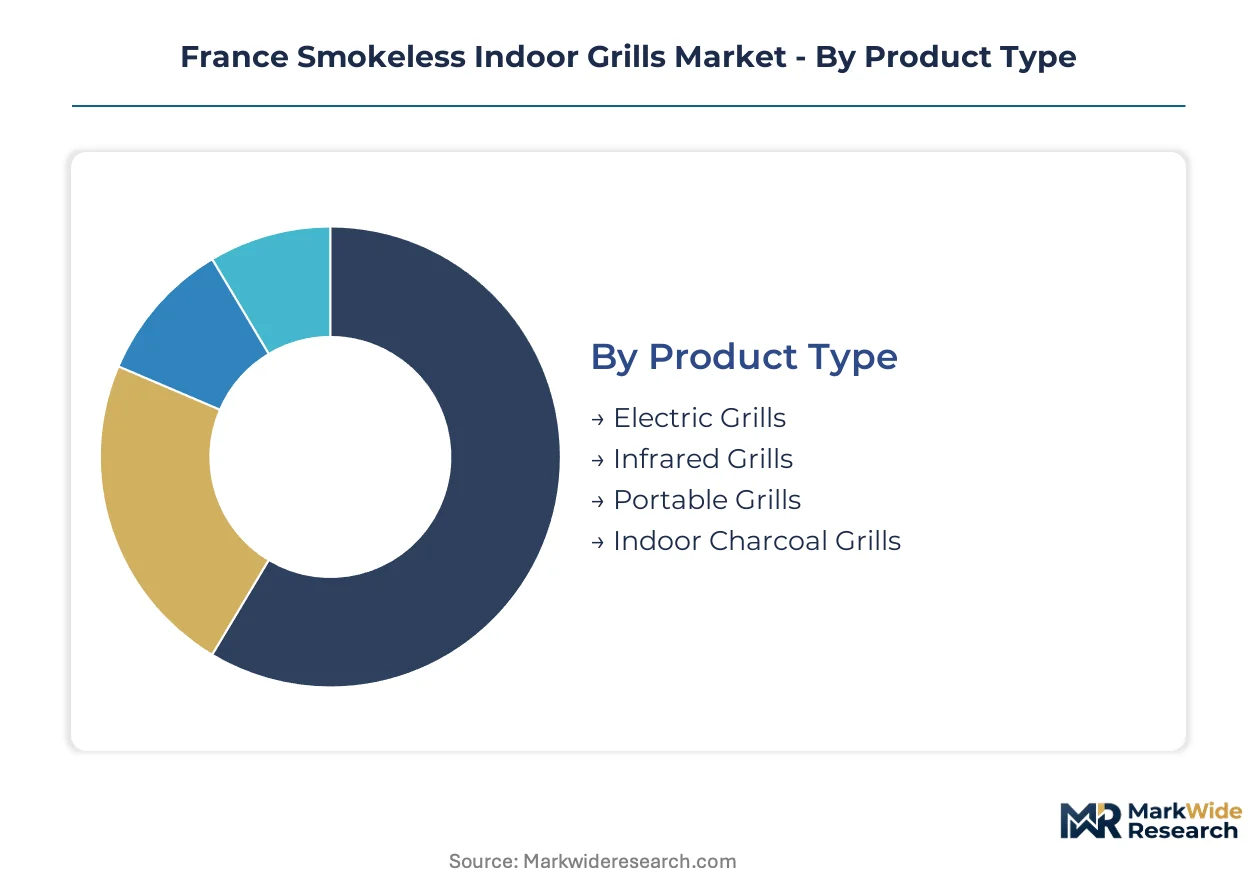
Segmentation in the France smokeless indoor grills market reveals how regulatory pressure and urban living constraints fragment demand across technical architectures and purchasing channels. Manufacturers must align product specifications with distinct energy efficiency thresholds and space limitations that vary by end-use environment.
Product Type:
Mature resistive heating designs coexist with emerging infrared architectures as French manufacturers navigate EU Ecodesign Directive compliance timelines.
- Electric Grills:Open-coil resistive elements housed in die-cast aluminum chassis dominate unit volumes through lower price positioning and established retail presence. Parisian apartment households purchase these units most heavily, though tightening energy labels are compressing their permissible wattage ranges.
- Infrared Grills:Ceramic and quartz-halogen emitters deliver 700°C surface temperatures at reduced power draw. Lyon and Bordeaux premium buyers prioritize these platforms for balcony-compatible cooking that satisfies France's national energy efficiency labeling requirements without sacrificing sear fidelity.
- Portable Grills:Compact sub-1,500-watt units with detachable power cords target mobile food operators and seasonal users in coastal Provence.
- Indoor Charcoal Grills:Enclosed combustion designs with active filtration represent a niche category constrained by fire-safety documentation from France's DGCCRF.
Electric grills handle the majority of throughput; infrared grills are climbing the fastest on share as energy regulations harden.
End User:
Cost tier stratification separates discretionary household purchasing from commercial operators seeking hood-free expansion paths.
- Households:Urban apartment dwellers in Île-de-France drive absolute demand, prioritizing compact footprints and integrated smoke suppression for balcony installation. Rental turnover acceleration in dense French cities compresses replacement cycles toward 4-5 year horizons.
- Restaurants:Full-service operators deploy 2,200-watt infrared platforms to extend grilled-menu offerings without fixed exhaust infrastructure. Regulatory exemptions for temporary kitchen installations create pull from bistros seeking menu flexibility.
- Cafes:Limited-service formats favor lower-wattage electric units for occasional hot sandwich preparation.
- Food Trucks:Mobile operators represent the steepest expansion trajectory among commercial segments, sourcing NSF-equivalent certified units that bypass fixed hood requirements under French mobile food regulations.
Households absorb the dominant share of unit flow; food trucks are gaining share fastest as regulatory arbitrage opportunities expand.
Distribution Channel:
Volume concentration in physical retail contrasts with margin capture through direct manufacturer relationships.
- Online Retail:E-commerce platforms specializing in home appliances now exceed 40 percent of category volume in tech-forward urban markets. Bordeaux and Nantes buyers favor sensor-equipped infrared units purchased through digital channels with unbundled installation support.
- Supermarkets:Hypermarket kitchen sections retain significance for entry-level electric grill distribution, though share erosion to digital channels accelerates.
- Specialty Stores:Independent kitchen retailers in Paris and Lyon provide hands-on demonstration and after-sales service for premium infrared platforms.
- Direct Sales:Manufacturer-controlled channels capture highest margins on commercial-grade units for restaurant and food truck procurement.
Supermarkets move the largest unit volumes; online retail is expanding most quickly as rental turnover shortens replacement horizons.
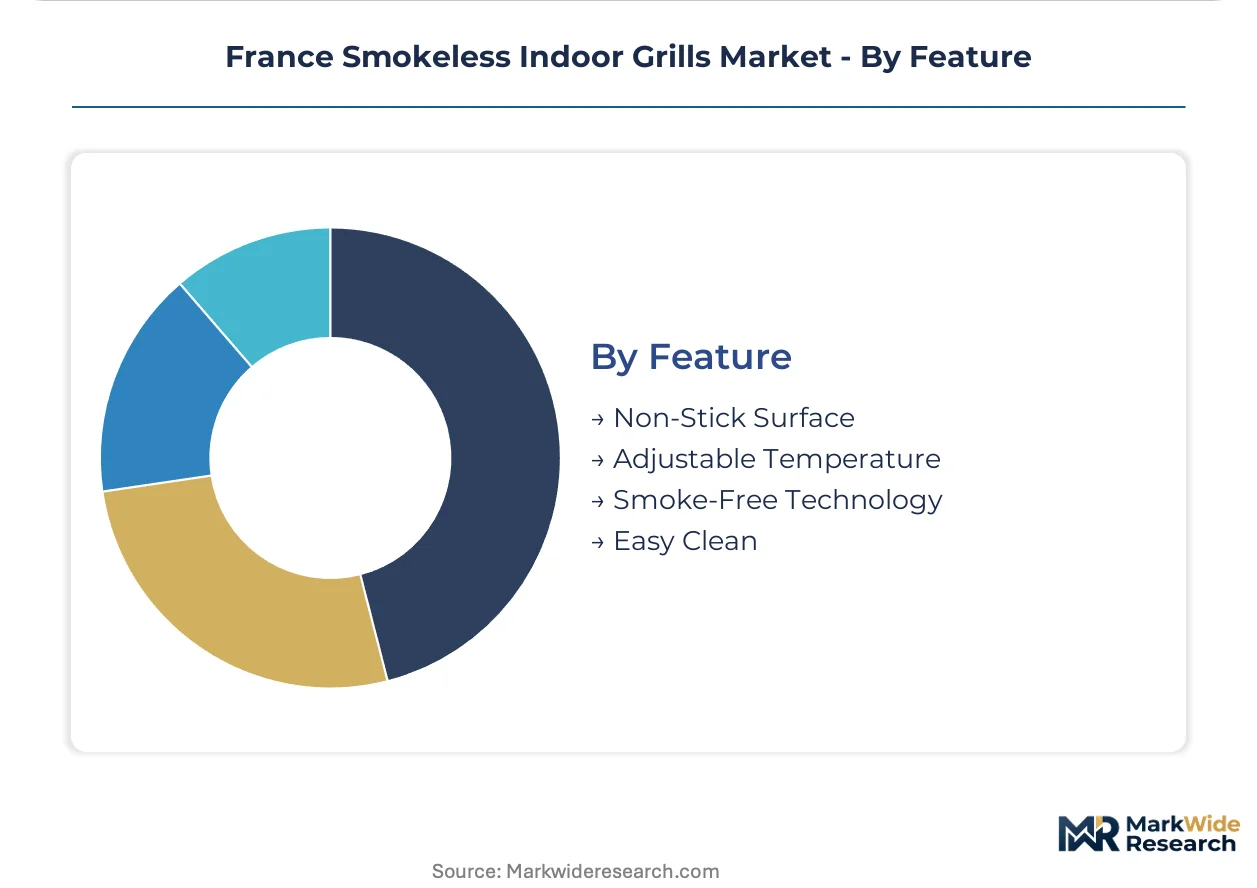
Feature:
Customer type differentiation separates tech-forward buyers seeking connectivity from practical users prioritizing maintenance simplicity.
- Non-Stick Surface:Ceramic and diamond-infused coatings reduce oil requirements and simplify cleaning for busy urban households.
- Adjustable Temperature:Dial or digital controls spanning 80-300°C accommodate proteins and vegetables across cooking scenarios.
- Smoke-Free Technology:Integrated grease management troughs and passive filtration systems enable operation in ventilation-constrained environments without active exhaust.
- Easy Clean:Detachable plates and dishwasher-safe components address the primary post-purchase concern cited by French household buyers.
Non-stick surfaces appear most frequently across unit configurations; smoke-free technology commands the highest feature premium in commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision infrared emitter components to French assembly plants serving Île-de-France and Lyon metropolitan markets. Italian foundries supply die-cast aluminum grill plates across the Rhône corridor. Belgian distributors channel entry-level electric units into northern French retail networks.
Île-de-France
Parisian apartment density eliminates outdoor grilling options, creating sustained demand for compact balcony-compatible units. DGCCRF enforcement of fire-safety documentation shapes product validation timelines for manufacturers targeting this region. Urban households in the capital prioritize smoke-free technology and integrated grease management for ventilation-constrained cooking environments.
Auvergne-Rhône-Alpes
Lyon's premium buyer segment drives adoption of ceramic infrared platforms with sensor-driven temperature modulation. The EU Ecodesign Directive's energy efficiency thresholds accelerate phase-out of resistive heating elements in this high-discretion market. Manufacturing clusters around Saint-Étienne supply precision-cast components to regional assembly operations.
Provence-Alpes-Côte d'Azur
Coastal seasonal usage patterns favor portable sub-1,500-watt units with detachable power cords. Mobile food operators exploit regulatory exemptions for hood-free temporary kitchen installations in Nice and Marseille. Tourism-driven rental turnover compresses appliance replacement cycles toward 4-5 year horizons.
Nouvelle-Aquitaine
Bordeaux's tech-forward households exceed 40 percent online purchase rates for sensor-equipped infrared grills. E-commerce platforms capture share from hypermarket kitchen sections through unbundled installation support. The region's wine-country hospitality sector sources commercial-grade units for hood-free menu expansion.
Hauts-de-France
Cross-border procurement patterns from Belgian distributors influence entry-level electric grill availability in Lille metropolitan retail channels. Northern industrial heritage sustains demand for durable die-cast aluminum constructions. Energy cost consciousness among households accelerates shift toward lower-wattage infrared architectures.
France Smokeless Indoor Grills Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands shaped by retail format and technical architecture. The market exhibits moderate concentration with three to four manufacturers capturing disproportionate margin pools in premium infrared segments while fragmented competition characterizes entry-level electric grill distribution. Strategic archetypes include heritage outdoor brands repositioning for indoor-adjacent credibility, diversified appliance conglomerates sustaining broad category coverage, and precision-engineering specialists leveraging sensor integration. Competitive moves concentrate on portfolio diversification toward smart connectivity features and strategic partnerships with e-commerce platforms to bypass traditional retail intermediaries.
Among heritage-positioned specialists, Weber Inc exemplifies outdoor-to-indoor brand extension strategies, while Groupe SEB occupies a position as diversified conglomerate with multi-channel presence. Philips represents the technology-forward archetype through sensor-driven differentiation. These three anchors illustrate how competitive positioning splits between brand heritage, portfolio breadth, and technical innovation vectors.
| Leading Market Players |
|---|
| Weber Inc |
| Electrolux |
| Roller Grill International |
| Char Broil |
| Le Griddle |
| Brandt |
| Philips |
| Whirlpool |
| Groupe SEB |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Italian and German foundries for precision die-cast aluminum grill plates determines both the 80-120 euro spread between economy and premium tiers and the elongated supply chain configuration that French manufacturers cannot easily diversify. This concentration forces pricing power toward upstream metal processors while compressing margins on entry-level electric units that compete primarily on landed cost.
Pricing Analysis
The technology-generation pricing gap separates legacy resistive-coil platforms from ceramic infrared emitters and emerging smart-sensor configurations. Three-tier pricing structure across premium, standard, and economy levels reflects wattage efficiency ratings and CE marking tier rather than brand heritage alone. Cost compression in the standard tier is intensifying because multi-function induction cooktops with grill accessories capture overlapping use cases in kitchen renovations. Household buyers in Île-de-France exhibit highest price sensitivity, while commercial food truck operators demonstrate lowest sensitivity due to regulatory arbitrage value.
Supply Chain Analysis
Contract manufacturing concentration rests with precision foundries in northern Italy and western Germany holding capacity for die-cast aluminum grill plates and ceramic emitter housings. Component sourcing draws from Chinese PCB assembly for control modules, Dutch semiconductor firms for thermopile sensors, and domestic French electrical cordage suppliers. Single-source vulnerability in Italian aluminum processing exposes margins to energy cost volatility in continental European metals markets. Distribution runs through hypermarket kitchen sections for economy units, specialty retailers for premium demonstration, and direct manufacturer channels for commercial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France smokeless indoor grills market is recovering from cyclical compression as EU Ecodesign Directive compliance timelines force replacement demand for non-compliant resistive heating inventory. This regulatory-driven refresh cycle creates temporary demand elevation that manufacturers must capture before efficiency thresholds stabilize.
For Market Incumbents: Entrench category ownership by securing exclusive supply agreements with Saint-Étienne-area precision foundries before capacity tightens. Accelerate sensor-integration R&D to differentiate premium tiers against induction cooktop substitution threats. Lock in hypermarket shelf space through multi-year category management contracts that block challenger brand placement.
For New Entrants and Emerging Players: Build out white-space presence in the food truck commercial segment where NSF-equivalent certification requirements create barrier-protected demand. Target Bordeaux and Nantes metro areas where online purchase rates exceed national averages and unbundled installation support lowers market entry cost. Pursue direct-to-operator digital marketing bypassing established retail intermediaries.
For Investors and Strategic Acquirers: Precision-engineering specialists with captive infrared emitter technology represent the most defensible acquisition archetype as energy efficiency mandates harden. Long-term viability hinges on modular design capabilities that satisfy forthcoming EU right-to-repair provisions. Monitor DGCCRF validation cycle lengths as an inflection indicator; compression signals regulatory environment favoring established compliance infrastructure over agile challengers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive supply of die-cast aluminum plates insulates margins from Italian energy cost volatility. |
| Smart Sensor Platform Launch | Wi-Fi-enabled thermopile modulation differentiates premium offerings in Lyon and Bordeaux retail channels. |
| Food Truck Certification Pathway | NSF-equivalent hygiene validation unlocks regulatory arbitrage in mobile food operations. |
| Modular Design Redesign | Replaceable heating elements align with EU right-to-repair mandates and extend service revenue. |
| E-commerce Channel Expansion | Direct digital sales capture margin pools as rental turnover compresses replacement cycles. |
Research Methodology
The analysis maps electric grill, infrared grill, portable grill, and indoor charcoal grill sub-sectors, each validated through product development executives at French manufacturers, category buyers at hypermarket chains, and regulatory affairs specialists familiar with DGCCRF enforcement protocols. Primary interviews with channel distribution heads and commercial kitchen operators were cross-referenced against EU Ecodesign Directive documentation, French customs trade data, and SEC filings from publicly traded appliance conglomerates. Bottom-up unit shipment estimates and top-down market value reconstructions were triangulated to anchor segmentation outputs.
Assumptions around EU energy efficiency threshold implementation timing and Parisian apartment household formation rates were held fixed, while infrared technology adoption curves and food truck regulatory exemption durability were stress-tested across sensitivity bands. The projection horizon spans product type, end user, distribution channel, and feature segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to historical replacement cycle compression patterns and commercial segment expansion trajectories. Input variables included wattage efficiency improvement rates and e-commerce penetration trends in French home appliance categories.
Stress conditions across aluminum input cost volatility, DGCCRF validation timeline extension, and induction cooktop substitution intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and could revise materially if EU right-to-repair implementation accelerates or F-Gas Regulation restrictions expand to passive cooling components. Quarterly review of foundry capacity utilization rates and food truck licensing issuance volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Digital Menu Boards Market