
 Europe Commercial Dishwashers Market | 2026-2036
Europe Commercial Dishwashers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Dishwashers Market Foresight
Foodservice equipment distribution is fragmenting as regional dealers lose ground to manufacturer-direct digital platforms and integrated service contracts. MEIKO Maschinenbau GmbH and Co. KG leverages its German engineering base to dominate high-throughput conveyor installations for institutional kitchens. Electrolux Professional AB competes through broad portfolio breadth across under-counter and door-type formats. Winterhalter Gastronom GmbH specializes in precision glasswashing systems for premium hospitality accounts.
Commercial dishwashers are industrial sanitization machines engineered to wash, rinse, and thermally disinfect tableware, cookware, and glassware at temperatures exceeding 82°C for final rinse cycles, using stainless-steel construction and pumped detergent systems to meet HACCP hygiene protocols in high-volume foodservice operations. Door-type units anchor the installed base across mid-scale European restaurants where throughput requirements fall between under-counter flexibility and conveyor scale. Energy-efficient technology leads replacement demand as operators face escalating utility costs and Ecodesign compliance deadlines. Automated systems with soil-sensing and self-diagnostics command margin premiums in hotel and catering service deployments.
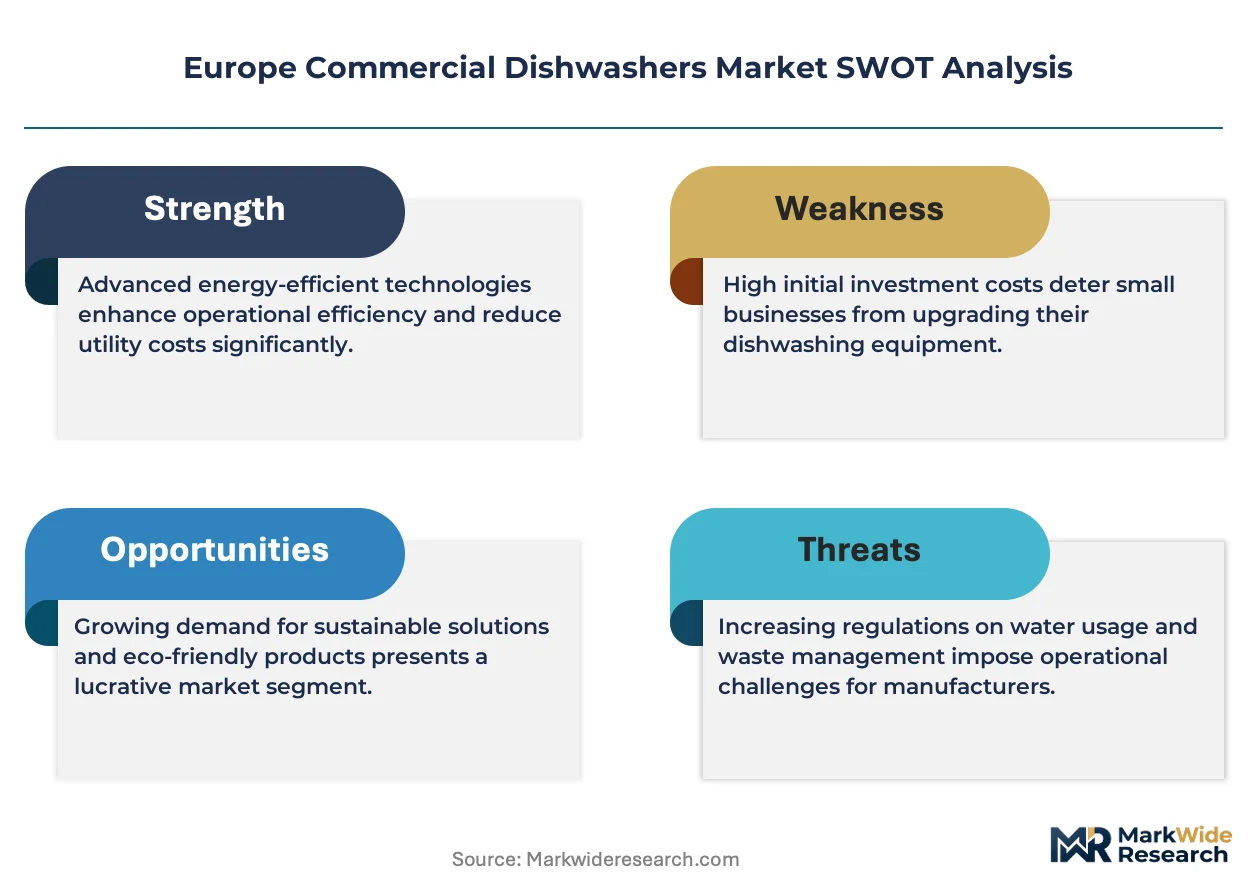
EU Ecodesign Directive and F-Gas Regulation shape product development trajectories by mandating heat-pump recovery and restricting high-GWP refrigerants in drying subsystems. CE marking and national energy-labelling schemes create tiered market-access thresholds that filter out non-compliant imports. Stakeholders must monitor evolving ECHA substance restrictions on rinse-aid chemistries and prepare for potential water-efficiency standards under the EU Green Deal implementation.
Market Dynamics
The EU Ecodesign Directive's tightening energy-efficiency mandates are forcing fleet replacements across European foodservice operations, compressing replacement cycles from ten-year intervals to seven-year cycles as heat-pump recovery systems become mandatory for new installations.
Growth Catalysts
- F-Gas Regulation Phase-Down:Restrictions on high-GWP refrigerants in drying subsystems accelerate adoption of closed-loop heat-pump technology across institutional kitchen deployments in Germany and France.
- Hotel Chain Consolidation:Pan-European hospitality groups standardize on automated soil-sensing systems to reduce water consumption and labor costs across Southern European resort properties.
- HACCP Protocol Intensification:Thermal disinfection requirements exceeding 82°C final rinse temperatures drive specification upgrades in healthcare and aged-care foodservice facilities.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 stainless price swings compress fabrication margins for door-type and conveyor manufacturers dependent on European mill supply.
- Component Supply Concentration:Heat-pump compressors and precision rinse nozzles concentrate among German and Italian subsystem suppliers, creating single-source vulnerability for mid-scale equipment assemblers.
- CE Marking Escalation:Evolving conformity assessment procedures under the Machinery Directive extend type-approval timelines for novel water-recovery architectures.
Strategic Opportunities
- Poland and Czech Republic Underpenetration:Independent restaurant sectors in Central European markets show 40% lower automated dishwasher penetration than Western European averages, presenting retrofit volume.
- EU Green Deal Water-Efficiency Standards:Anticipated mandatory water-consumption limits per rack cycle will create first-mover advantage for manufacturers with sub-2-liter rinse systems.
- IoT-Enabled Predictive Maintenance:Convergence of cloud diagnostics with automated detergent dosing enables subscription revenue models for equipment financiers and service integrators.
Industry Challenges
- Field Service Technician Scarcity:Heat-pump and electronic control specialization outpaces vocational training pipeline output across Iberian and Balkan service territories.
- Legacy Hydraulics Integration:Retrofitting energy-recovery modules into existing under-counter footprints demands custom plumbing fabrication that extends installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Dishwashers Market |
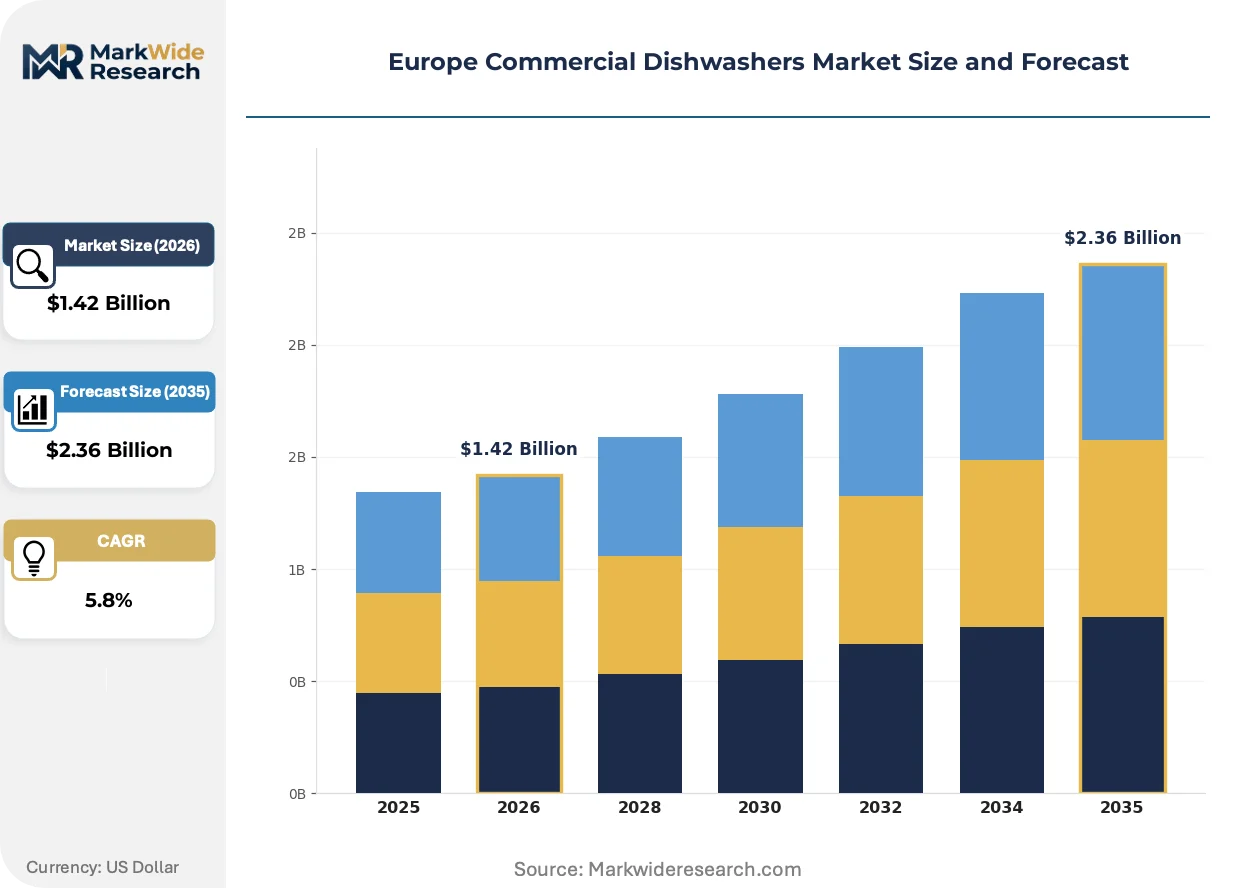
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Under-counter, Conveyor, Door-type, Glasswasher End User: Restaurants, Cafés, Hotels, Catering Services Installation Type: Built-in, Stand-alone, Portable, Custom Technology: Standard, Energy-efficient, Automated, Hybrid |
| Companies Covered | MEIKO Maschinenbau GmbH and Co. KG, Insinger Machine Co., Electrolux Professional AB, MVP Group Corp., Blakeslee Inc., Winterhalter Gastronom GmbH, Fagor Industrial S. Coop, Washtech Ltd., Miele and Cie. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Dishwashers Market Shifts & Advancements
Digital twin architecture is virtualizing equipment commissioning and remote diagnostics across European commercial kitchen deployments. Three distinct vectors are compressing development cycles and reshaping buyer-supplier relationships.
Heat-pump drying technology is virtualizing the thermal management layer previously handled by conventional gas or electric resistance elements. Hotel chains in Spain and Portugal deploy these systems at replacement rates triple those of conventional architectures. The technology is virtualizing capital expenditure structures by enabling performance-based service contracts where efficiency guarantees replace upfront hardware purchases.
The EU F-Gas Regulation's staged refrigerant phase-down is compressing R-404A and R-134a availability for drying subsystems. Equipment manufacturers accelerate heat-pump platform development to maintain CE marking eligibility. Door-type and conveyor segments face the steepest redesign timelines as 2027 bans on high-GWP refrigerants approach.
Buyer concentration among contract foodservice management companies is consolidating procurement authority away from individual restaurant operators. Multi-site catering groups in the UK and Netherlands now specify pan-European service agreements with unified telemetry standards. Southern European hotel chains resist this consolidation, maintaining decentralized purchasing through regional dealer networks that bundle installation with local water-treatment expertise.
Europe Commercial Dishwashers Market Segmentation
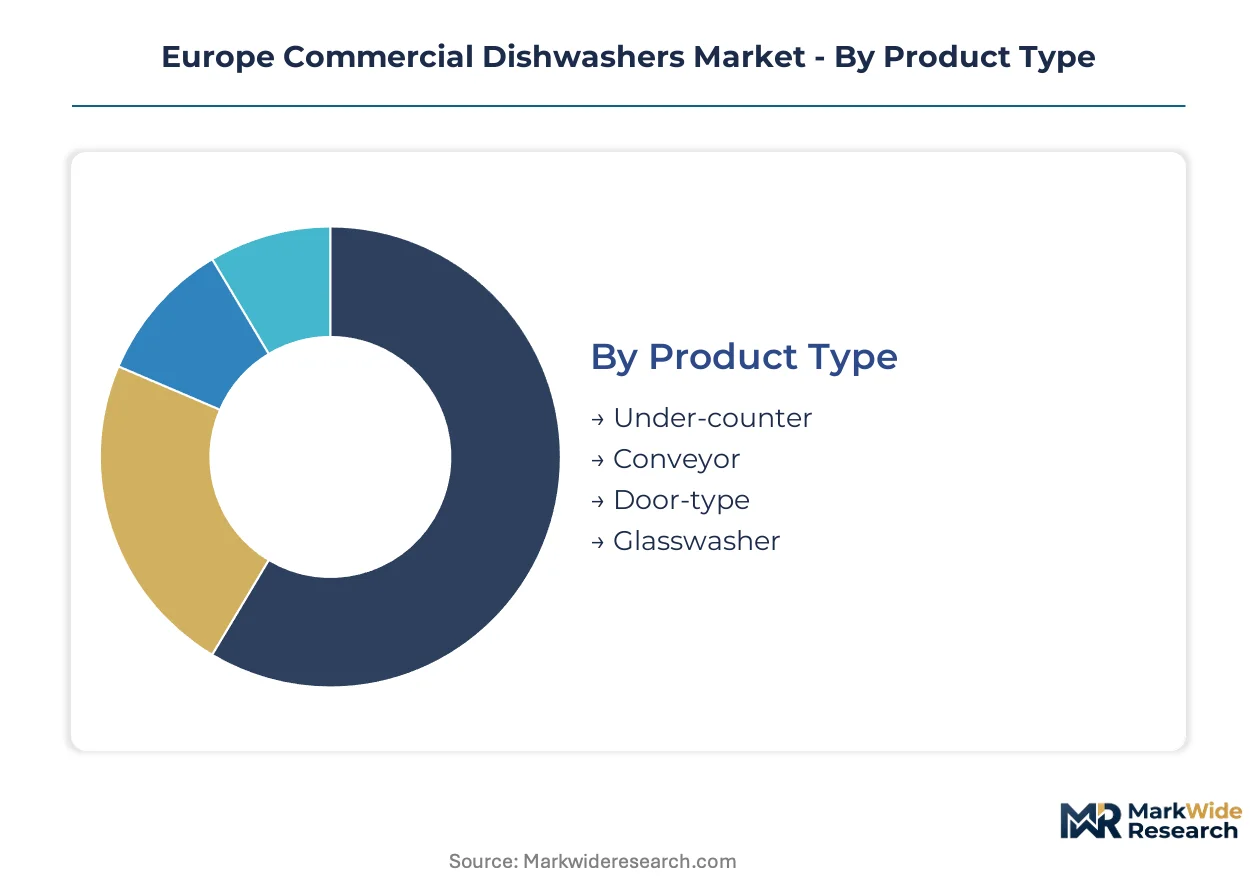
Equipment specification varies sharply across European foodservice operations, with thermal performance requirements and floor-space constraints driving divergent procurement patterns. Segmentation reveals how regulatory pressure and operational scale reshape vendor prioritization across product formats and buyer categories.
Product Type:
Volume throughput and kitchen footprint dimensions determine equipment selection across German institutional kitchens and French full-service restaurants.
- Door-type:These units occupy the middle ground between compact under-counter models and high-volume conveyor systems, typically processing 50-150 racks per hour through a vertical lifting door mechanism. Demand concentrates in mid-scale independent restaurants across France and Italy where EU Ecodesign retrofit deadlines are compressing replacement cycles.
- Conveyor:Continuous-belt systems handle 200+ racks hourly through automated loading zones, requiring dedicated floor space and three-phase electrical infrastructure. German hospital and university cafeterias dominate procurement as heat-pump recovery mandates force fleet upgrades in institutional settings.
- Under-counter:Compact units fit beneath preparation surfaces in space-constrained cafés and small bistros.
- Glasswasher:Specialized low-temperature rinse systems protect stemware integrity in premium hospitality accounts.
Door-type holds installed capacity. Conveyor is rotating up the share rankings.
End User:
Buyer concentration and procurement centralization diverge sharply between fragmented independent operators and consolidated multi-site groups.
- Hotels:Pan-European hospitality groups standardize on automated soil-sensing systems with unified telemetry standards, particularly across Spanish and Portuguese resort properties where water-recovery technology reduces utility expenditures. Procurement authority is consolidating away from individual property managers toward centralized technical specifications.
- Restaurants:Full-service establishments in Germany and France are expanding fleet replacements as energy-efficiency mandates tighten, with independent operators relying on regional dealer networks for installation bundling.
- Catering Services:Contract foodservice management companies in the UK and Netherlands drive pan-European service agreements with performance-based efficiency guarantees.
- Cafés:Small-format operators prioritize under-counter flexibility and minimal installation disruption.
Restaurants hold installed capacity. Hotels are climbing the fastest.
Installation Type:
Physical integration requirements reflect kitchen layout permanence and regulatory compliance complexity across member states.
- Stand-alone:Freestanding units with integrated water connections dominate replacement cycles in older European kitchen infrastructure where plumbing retrofit costs deter built-in conversion. German and Italian manufacturers optimize these configurations for rapid field commissioning.
- Built-in:Flush-mounted systems require custom cabinetry integration and permanent water hard-piping, attracting new-construction specifications in Nordic markets where kitchen design standards emphasize aesthetic cohesion.
- Portable:Castor-mounted units serve temporary event catering and seasonal hospitality operations.
- Custom:Bespoke configurations address non-standard architectural constraints in historic building conversions.
Stand-alone holds installed capacity. Built-in is gaining share fastest.
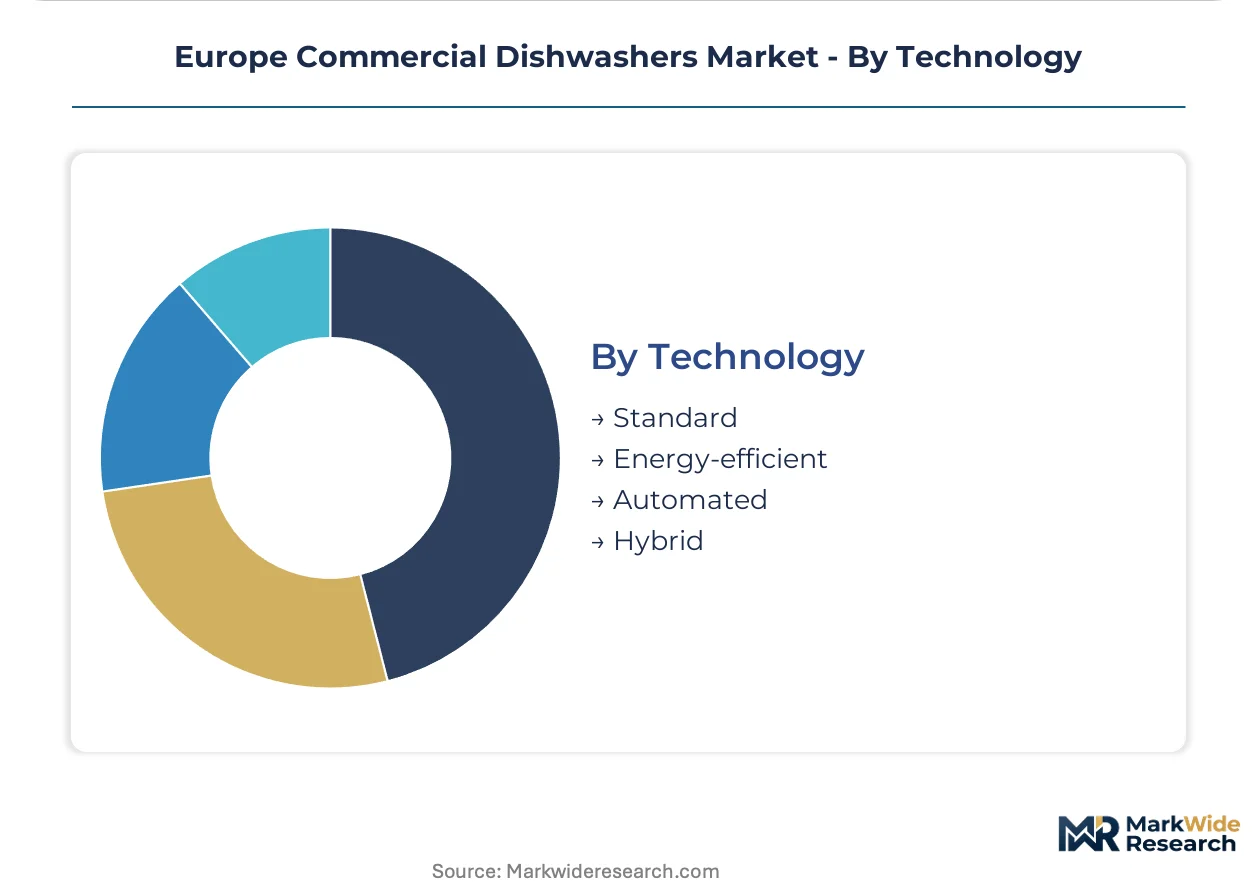
Technology:
Regulatory tiering under EU Ecodesign and F-Gas Regulation is stratifying equipment classes by thermal efficiency and refrigerant architecture.
- Energy-efficient:Heat-pump recovery systems and closed-loop drying architectures now dominate replacement demand as operators face escalating utility costs and compliance deadlines. Spanish and Portuguese hotel chains deploy these at replacement rates triple those of conventional architectures.
- Automated:Soil-sensing controls and self-diagnostic modules command margin premiums through reduced water consumption and labor intervention, particularly in UK and Netherlands contract catering deployments.
- Standard:Conventional electric resistance drying remains prevalent in budget-constrained independent operations.
- Hybrid:Mixed-technology systems combine heat-pump recovery with conventional backup elements for transitional installations.
Standard holds installed capacity. Energy-efficient is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor anchors Central European distribution networks for commercial foodservice equipment, connecting German manufacturing clusters to Black Sea ports and Mediterranean logistics hubs.
Germany
Institutional kitchen retrofits in Bavaria and North Rhine-Westphalia drive conveyor system demand as the EU Ecodesign Directive compresses replacement cycles. The Federal Environment Agency enforces heat-pump recovery mandates through national energy-labelling schemes. MEIKO Maschinenbau anchors production in Offenburg, supplying high-throughput installations to hospital and university cafeteria networks.
France
Full-service restaurant chains in Paris and Lyon accelerate door-type replacements ahead of 2027 F-Gas Regulation deadlines. ANSM monitors rinse-aid chemistry compliance under evolving ECHA substance restrictions. The Auvergne-Rhône-Alpes cluster concentrates precision glasswashing specialists serving premium hospitality accounts.
Spain
Hotel resort properties in Andalusia and the Balearic Islands deploy automated soil-sensing systems at triple the replacement rates of conventional architectures. The Ministry for Ecological Transition implements EU Green Deal water-efficiency standards through regional utility incentives. Barcelona anchors distributor networks bundling installation with local water-treatment expertise.
United Kingdom
Contract foodservice management companies in London and the Southeast consolidate procurement authority through pan-European service agreements. The Environment Agency enforces thermal disinfection protocols exceeding 82°C in healthcare foodservice facilities. The Midlands corridor hosts integration centers for IoT-enabled predictive maintenance platforms.
Poland
Independent restaurant sectors in Warsaw and Kraków show automated dishwasher penetration 40% below Western European averages, presenting retrofit volume. The Polish Committee for Standardization aligns national certification with CE marking and Machinery Directive requirements. The Silesian industrial zone attracts component assembly for heat-pump compressor subsystems.
Europe Commercial Dishwashers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service contracts and manufacturer-direct digital platforms that displace regional dealer networks. Three strategic archetypes dominate: German-engineered institutional specialists, Scandinavian portfolio generalists, and precision glasswashing boutiques. Competitive intensity centers on heat-pump platform development and IoT-enabled predictive maintenance subscriptions.
Among German fabricators, MEIKO Maschinenbau GmbH and Co. KG and Winterhalter Gastronom GmbH exemplify engineering-intensive archetypes focused on high-throughput and precision applications respectively. Electrolux Professional AB represents the portfolio-breadth approach across multiple equipment formats. These three occupy positions that illustrate how regulatory pressure under the EU Ecodesign Directive and F-Gas Regulation stratifies competitive positioning by thermal efficiency capability.
| Leading Market Players |
|---|
| MEIKO Maschinenbau GmbH and Co. KG |
| Insinger Machine Co. |
| Electrolux Professional AB |
| MVP Group Corp. |
| Blakeslee Inc. |
| Winterhalter Gastronom GmbH |
| Fagor Industrial S. Coop |
| Washtech Ltd. |
| Miele and Cie. KG |
| Others |
Supply & Pricing Matrix
Grade 304 and 316 stainless steel price volatility determines both margin compression across fabrication tiers and the geographic clustering of European mill-dependent assemblers. This input-cost instability widens pricing spreads between premium heat-pump systems and conventional electric-resistance units while forcing supply chain consolidation around German and Italian subsystem suppliers.
Pricing Analysis
Volume-discount tiering separates pan-European hotel chain procurement from independent restaurant spot purchases. Pricing stratifies across premium, standard, and economy tiers based on heat-pump certification grade and bundled telemetry service levels. Cost compression in the standard tier is intensifying because regional dealers face displacement by manufacturer-direct digital platforms. Independent operators in Poland and the Czech Republic exhibit highest price sensitivity, while consolidated UK contract caterers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among German heat-pump compressor specialists and Italian precision rinse-nozzle fabricators. Component sourcing draws from Bavarian electromechanical clusters, Emilian hydraulic subsystem producers, and Iberian water-treatment module assemblers. Single-source vulnerability pervades heat-pump compressor supply for mid-scale equipment assemblers lacking backward integration. Distribution runs through integrated service contracts that bundle installation, detergent supply, and predictive maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a regulatory-driven replacement cycle as EU Ecodesign Directive deadlines compress fleet turnover intervals across Central European institutional kitchens.
For Market Incumbents: Build installed-base lock-in through IoT-enabled predictive maintenance subscriptions that capture lifetime service revenue. Defend against manufacturer-direct disintermediation by embedding regional dealers in water-treatment expertise bundles. Prioritize certification investment in sub-2-liter rinse systems ahead of anticipated EU Green Deal water-efficiency mandates. For New Entrants and Emerging Players: Pursue underpenetrated independent restaurant sectors in Warsaw and Kraków where automated dishwasher penetration trails Western European benchmarks by substantial margins. Target white-space in Central European retrofit demand through rental-based performance contracts that eliminate upfront capital barriers. Anchor go-to-market strategy around rapid field commissioning capabilities that match German manufacturer service levels. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors heat-pump platform specialists with proven CE marking pathways. Long-term viability hinges on regulatory compliance architecture rather than manufacturing scale alone. Acquisition targets should demonstrate closed-loop thermal management IP and established service technician training pipelines. Monitor F-Gas Regulation enforcement intensity as the primary inflection indicator for platform transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Platform Development | CE marking eligibility under F-Gas Regulation phase-down secures market access across German institutional procurement. |
| IoT Predictive Maintenance Launch | Cloud diagnostics integration with MEIKO and Winterhalter equipment enables recurring subscription revenue streams. |
| Central European Distribution Expansion | Warsaw and Kraków dealer networks capture retrofit volume in 40% underpenetrated independent restaurant segments. |
| Water-Efficiency Certification Investment | Sub-2-liter rinse system validation creates first-mover positioning ahead of EU Green Deal implementation. |
| Integrated Service Contract Rollout | Performance-based efficiency guarantees displace transactional equipment sales in UK contract catering consolidation. |
Research Methodology
A standing panel of foodservice equipment procurement directors, commercial kitchen maintenance engineers, and regional dealer principals provided ongoing calibration across the primary research phase. This study combined structured interviews with these stakeholders against secondary validation from EU Ecodesign Directive implementation reports, national energy-labelling scheme databases, and F-Gas Regulation compliance filings. Bottom-up equipment shipment triangulation with top-down foodservice operator expenditure analysis anchored market sizing.
Scenario-bracketing around regulatory deadline timing and stainless steel price volatility shaped the analytical framework across the projection horizon. Segmentation modeling captured product type, end-user category, installation format, and technology tier dimensions. CAGRs derived from replacement-cycle compression rates and heat-pump adoption curves specific to German institutional and Spanish hospitality deployments. Forecast inputs incorporated EU Green Deal water-efficiency standard anticipation effects and pan-European hotel chain procurement centralization trends.
Macroeconomic conditions sit as an overlay; deviation in energy price trajectories or stainless steel input costs would shift the replacement timing trajectory. These projections reflect documented assumptions regarding regulatory enforcement consistency and component supply continuity. Quarterly review of F-Gas Regulation phase-down announcements and ECHA substance restriction updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Commercial Rotisserie Oven Market