
 Commercial Steamer Market | 2026-2036
Commercial Steamer Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Steamer Market Analysis
A capital-intensity divergence between stainless-steel fabrication capabilities and digital control integration is reorganizing competitive tiers in the commercial steamer landscape. Rational AG leverages its combi-steamer technology leadership to command premium positioning in European and North American institutional kitchens. Cleveland Range sustains foundry-to-finish vertical integration that anchors its cost position in mid-scale restaurant chains. Hobart competes through service-network density, using its extensive technician footprint to reduce downtime guarantees for healthcare and hospitality operators.
A commercial steamer is a pressurized or atmospheric cooking vessel that generates saturated steam at temperatures between 100°C and 135°C to heat food through conduction and condensation, typically constructed from 304-grade stainless steel with programmable humidity sensors and automated descaling cycles. Its primary industrial purpose centers on nutrient-retentive batch cooking for high-volume foodservice operations where speed and consistency override conventional dry-heat methods. Electric steamers dominate installed base across urban restaurants constrained by gas hookup limitations, while convection steamers capture fastest-growing share as operators seek dual-mode flexibility in compact kitchen footprints. Pressure steamers retain concentrated margin pools in institutional healthcare facilities where batch throughput and HACCP traceability requirements outweigh upfront equipment premiums.
The EPA Energy Star program and EU Ecodesign Directive impose minimum cooking efficiency thresholds that disqualify legacy boiler-based models from new construction specifications, directly accelerating replacement demand. NSF International sanitation standards and FDA Food Code provisions govern material safety and temperature logging protocols, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving electrification incentives under the US Inflation Reduction Act and parallel EU Green Deal funding mechanisms, as subsidy eligibility increasingly restricts access for gas-powered equipment categories.
Market Dynamics
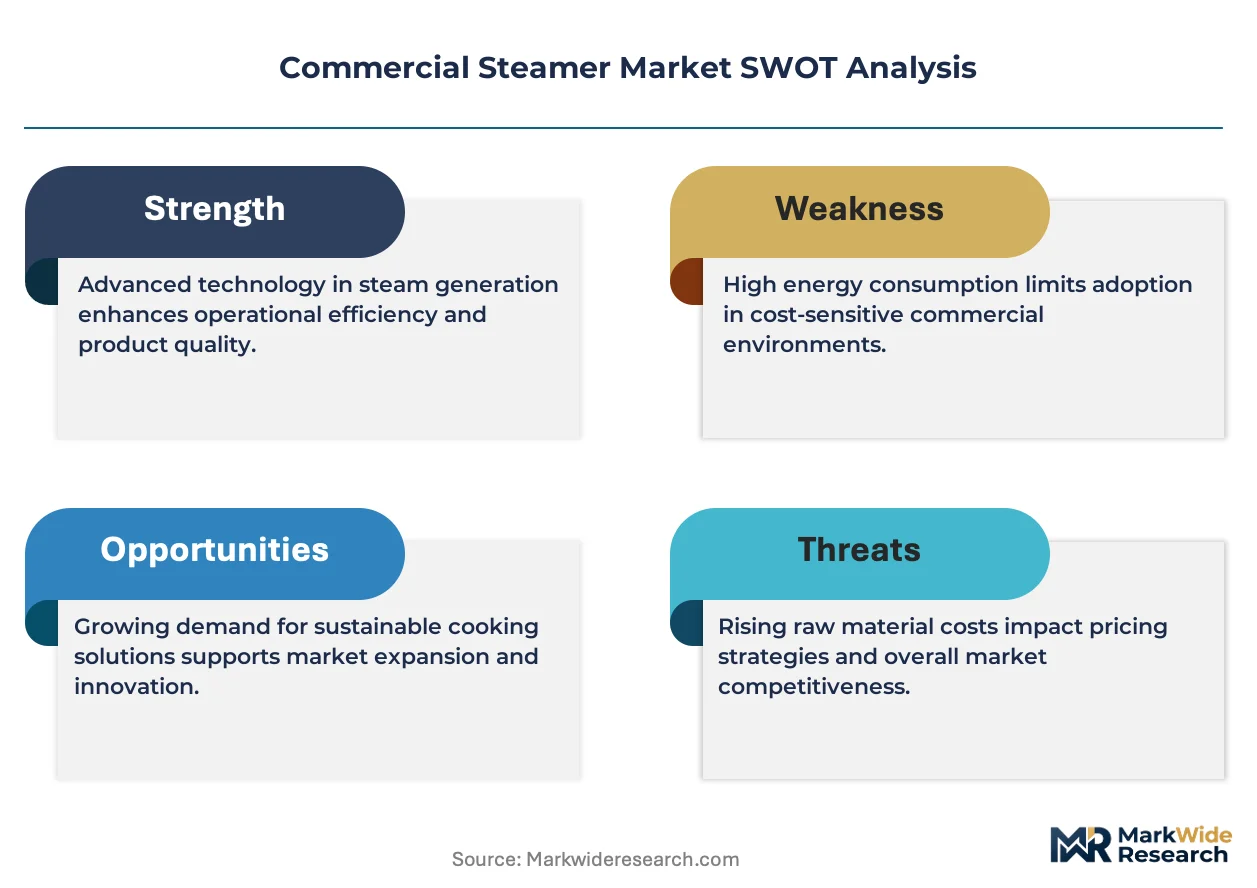
Energy-efficiency mandates from the EPA and EU Ecodesign Directive are forcing commercial kitchen operators to retire aging boiler-based steamers, triggering a replacement cycle concentrated in the United States, Germany, and China.
Growth Catalysts
- EPA Energy Star thresholds:Minimum cooking efficiency standards disqualify legacy equipment from new construction specifications, accelerating fleet turnover in institutional foodservice.
- Connected kitchen platforms:IoT-enabled steamers with automated descaling and HACCP logging attract healthcare operators seeking traceability compliance.
- Urban gas hookup constraints:Electric steamer demand concentrates in dense metropolitan restaurant markets where infrastructure limitations block gas equipment installation.
Market Restraints
- 304-grade stainless steel input volatility:Nickel and chromium price swings compress fabrication margins for equipment manufacturers dependent on commodity metal markets.
- Foundry capacity concentration:Boiler component suppliers cluster in specific industrial regions, exposing procurement to localized supply disruptions and extended lead times.
- Pressure vessel certification friction:ASME and PED compliance timelines extend product launch schedules, delaying revenue recognition for new model introductions.
Strategic Opportunities
- US Inflation Reduction Act electrification incentives:Subsidy eligibility increasingly restricts gas-powered categories, creating competitive opening for all-electric platform specialists.
- Combi-steamer convergence:Dual-mode convection-steam functionality addresses compact kitchen footprints in high-rent urban dining districts.
- Cloud-connected predictive maintenance:Service-network density becomes a differentiation vector as operators prioritize uptime guarantees over upfront equipment cost.
Industry Challenges
- Control systems integration complexity:Legacy kitchen management platforms resist seamless API connection with new steamer generations, requiring costly middleware development.
- NSF sanitation certification bottlenecks:Material safety testing queues at accredited laboratories extend time-to-market for imported component substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Steamer Market |
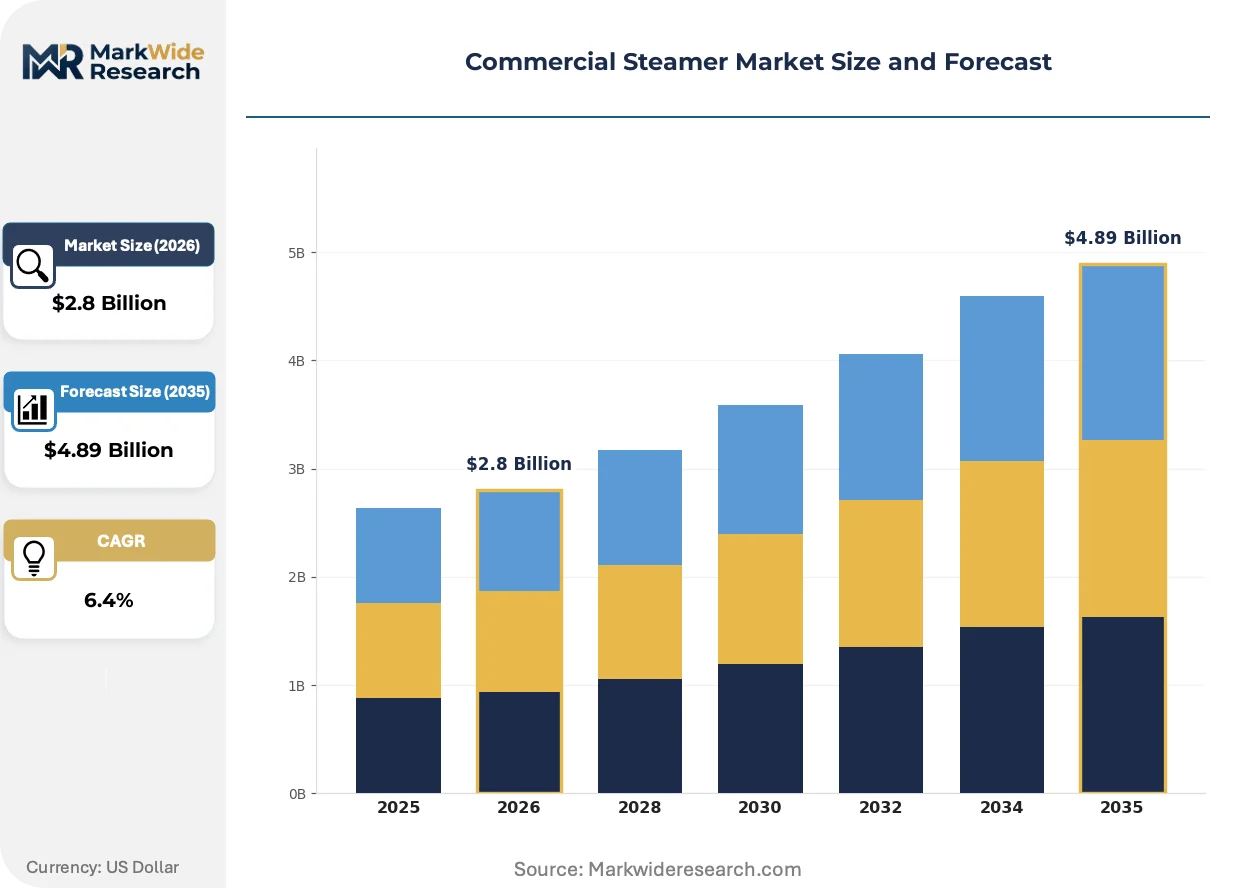
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Steamer, Gas Steamer, Pressure Steamer, Convection Steamer Application: Food Preparation, Laundry, Industrial Cleaning, Medical Equipment Sterilization End User: Restaurants, Hotels, Catering Services, Healthcare Facilities Size: Small, Medium, Large, Extra Large |
| Companies Covered | Rational AG, Cleveland Range, Hobart, Vulcan, Alto-Shaam, G.S. Blodgett, AccuTemp Products, Unified Brands, Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Steamer Market Emerging Trajectories
Steam generation architecture is compressing from centralized boiler rooms to point-of-use modular systems, while digital control layers transform equipment from isolated appliances into networked kitchen nodes.
Induction-based steam generation is miniaturizing thermal mass requirements from hundred-liter boiler volumes to compact countertop units. Fast-casual chains with severe space constraints are adopting these systems at accelerating rates. The technology is miniaturizing equipment footprints sufficiently to displace traditional boiler infrastructure in renovation projects where mechanical room expansion is structurally impossible.
The EU Ecodesign Directive's 2024 cooking efficiency thresholds are disqualifying atmospheric steamers from public procurement tenders. German and French institutional buyers now specify pressure-steamer or convection-steamer categories exclusively. Healthcare operators in these markets are responding by consolidating vendor relationships with manufacturers holding pre-certified product portfolios.
Equipment-as-a-service contracting is displacing capital purchase models among multi-unit restaurant operators. Third-party finance vehicles now bundle steamer hardware, maintenance, and energy monitoring into per-meal cost structures. This pattern concentrates in the United States where tax-advantaged leasing structures reduce effective ownership costs for franchise networks.
Commercial Steamer Market Segmentation
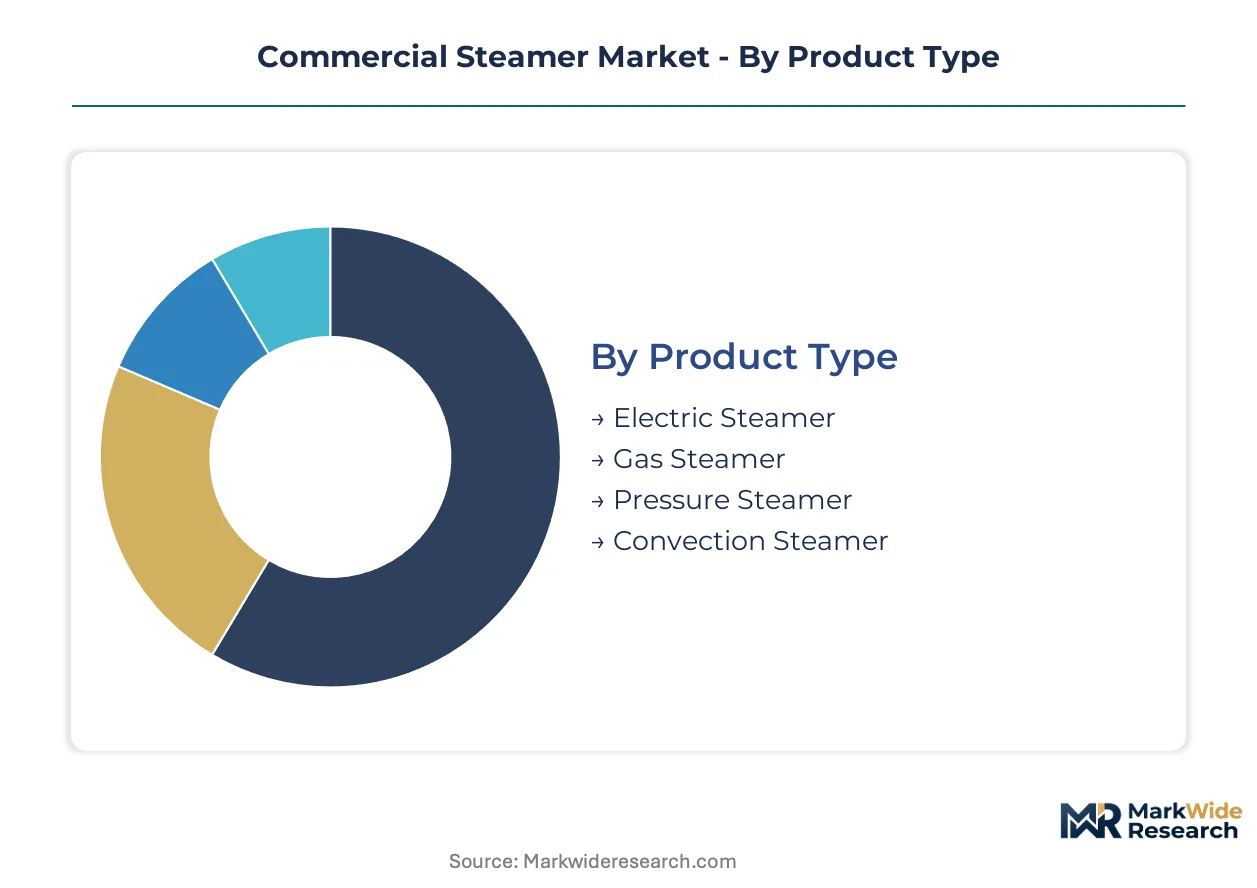
Commercial steamer procurement patterns diverge sharply across operational contexts. Kitchen operators select equipment based on fuel availability, throughput requirements, and facility infrastructure constraints rather than brand preference alone.
Product Type:
Gas steamers face the most acute substitution pressure as electrification mandates tighten across municipal jurisdictions and institutional procurement codes.
- Electric Steamer:Resistance-element or induction-based systems generating saturated steam without combustion. Demand concentrates in Manhattan, San Francisco, and London where gas hookup moratoriums block fossil-fuel equipment installation in new construction.
- Convection Steamer:Dual-mode units combining forced-air convection with steam injection for protein finishing and vegetable batch cooking. Fast-casual chains with compact kitchen footprints in high-rent districts favor these systems for equipment-count reduction.
- Gas Steamer:Atmospheric or power-burner configurations using natural gas or propane combustion.
- Pressure Steamer:ASME-certified vessels operating above atmospheric pressure for accelerated batch throughput.
Electric steamers retain volume leadership; convection steamers hold the steepest expansion curve.
Application:
Cost-tier stratification separates capital-intensive medical sterilization from commoditized food preparation equipment.
- Food Preparation:Atmospheric or pressure vessels for vegetable steaming, protein poaching, and starch gelatinization in high-volume foodservice. Restaurant chains in Germany and China are replacing boiler-based systems with point-of-use modular units to reduce energy recovery losses.
- Medical Equipment Sterilization:ASME and PED-compliant pressure vessels with automated cycle validation and FDA 21 CFR Part 11 electronic record-keeping. Hospital procurement committees prioritize pre-validated equipment to accelerate installation qualification timelines.
- Laundry:Industrial steam injection for textile finishing and stain removal in hospitality operations.
- Industrial Cleaning:High-pressure saturated steam for degreasing and sanitation in food processing plants.
Food preparation dominates installed base; medical sterilization commands the highest average equipment value.
End User:
Customer-type differentiation tracks HACCP compliance intensity and capital deployment flexibility across facility categories.
- Restaurants:Independent and chain operators with varying throughput requirements and space constraints.
- Healthcare Facilities:Hospitals and long-term care operations with mandatory temperature logging and batch traceability requirements. These buyers specify NSF-certified equipment with automated HACCP documentation to reduce manual record-keeping labor.
- Catering Services:Mobile and commissary operations requiring rapid heat-up cycles and transport durability.
- Hotels:Full-service properties with banquet capacity and room service integration needs.
Restaurants generate the highest unit volume; healthcare facilities drive premium pricing realization.
Size:
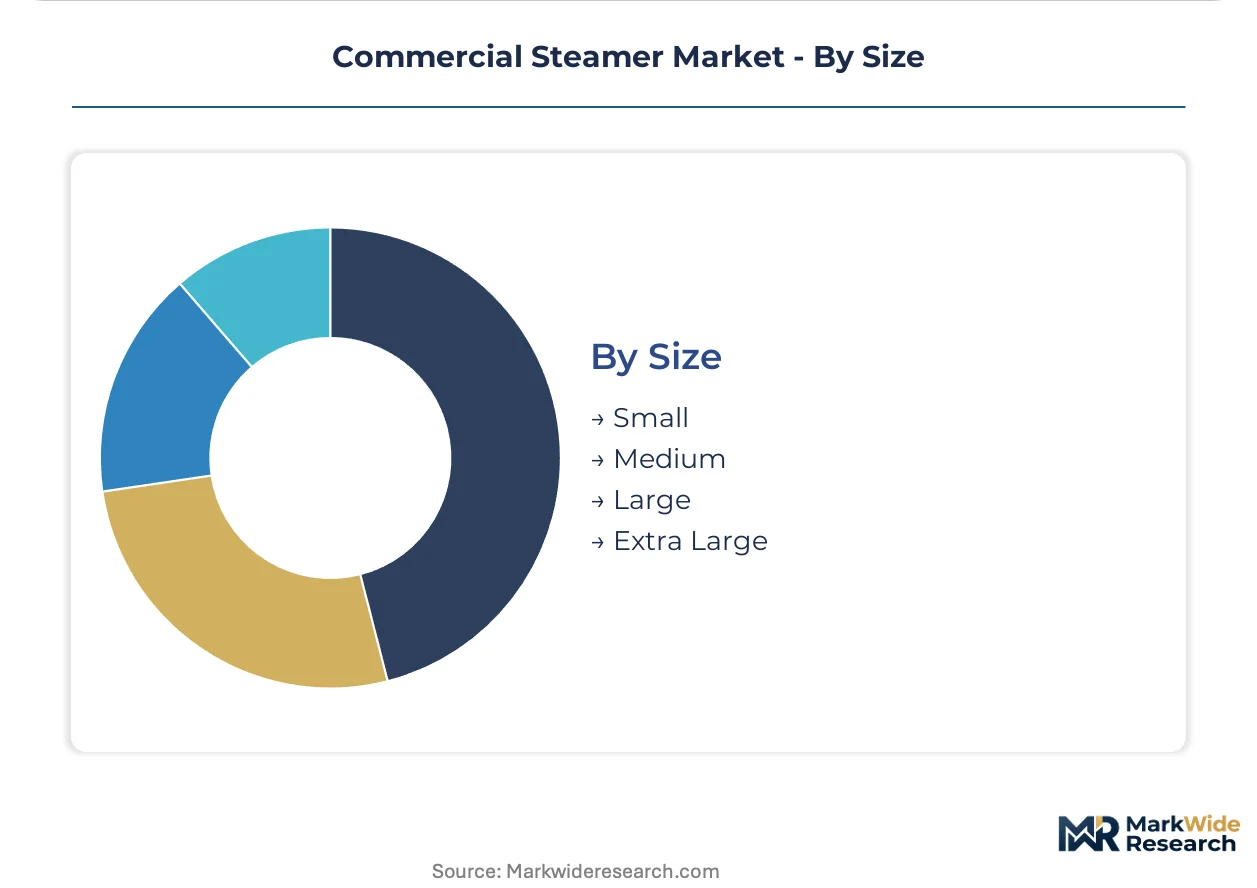
Volume concentration favors mid-capacity units that balance batch flexibility with kitchen footprint efficiency.
- Medium:Three to six pan capacity units serving 200-400 meal equivalents per hour. Urban restaurant renovations with structural mechanical room limitations specify these units to avoid boiler infrastructure expansion.
- Large:Ten to twenty pan configurations for institutional cafeterias and central commissaries. Hospital foodservice directors in the United States select these systems to consolidate production from satellite kitchens into centralized cook-chill operations.
- Small:Countertop units with one to two pan capacity for limited-menu concepts.
- Extra Large:Custom-engineered systems exceeding twenty pan capacity for stadium and airport concession clusters.
Medium sizes anchor procurement volume; large units deliver the strongest margin contribution per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement committees in Germany pay equipment premiums without volume elasticity, while fast-casual chains in the United States negotiate aggressively on per-unit cost. Chinese institutional buyers fall between these poles, prioritizing throughput efficiency over brand prestige.
United States
Hospital foodservice directors in Illinois and Texas are consolidating cook-chill operations into centralized kitchens, driving demand for ten-to-twenty-pan pressure steamers. The EPA Energy Star program disqualifies atmospheric models from federal procurement tenders, accelerating fleet turnover at Veterans Affairs facilities. Cleveland and Chicago restaurant clusters specify electric units exclusively where municipal gas moratoriums block fossil-fuel hookups.
Germany
EU Ecodesign Directive thresholds have eliminated atmospheric steamer eligibility from public healthcare tenders since early 2024. Bavarian and North Rhine-Westphalian hospital procurement committees now specify only pressure-steamer or convection-steamer categories with pre-certified efficiency documentation. Rational AG's combi-steamer technology commands premium positioning across Frankfurt and Munich institutional kitchens.
China
Central kitchen operators in Shanghai and Beijing are replacing aging boiler-based systems with point-of-use modular units to reduce energy recovery losses. The country's dual carbon goals pressure state-owned hospital networks to electrify foodservice equipment ahead of provincial emission targets. Yangtze River Delta manufacturing clusters supply 304-grade stainless steel fabrication to domestic and export markets.
United Kingdom
NHS Trust procurement frameworks in London and Birmingham mandate NSF-certified equipment with automated HACCP documentation to reduce manual record-keeping labor. The country's net-zero building codes restrict gas-powered equipment in new healthcare construction, favoring induction-based steam generation. Southeast England restaurant operators face similar electrification pressures from municipal climate action plans.
Japan
Compact kitchen footprints in Tokyo and Osaka metropolitan areas favor dual-mode convection-steam functionality for equipment-count reduction. METI efficiency standards for commercial cooking equipment accelerate replacement of legacy boiler systems in hospital and eldercare facilities. Kansai region fabricators specialize in miniaturized thermal mass systems for fast-casual chain adoption.
Commercial Steamer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure rather than consolidated dominance. Combi-steamer specialists command premium positioning through programmable humidity control and connected kitchen integration. Foundry-integrated fabricators anchor mid-scale segments through captive stainless steel supply and vertical manufacturing control. Service-network operators compete on technician density and uptime guarantees rather than equipment specifications. Strategic moves concentrate on portfolio diversification into adjacent cooking platforms and geographic expansion through distribution partnerships.
Among European technology leaders, Rational AG exemplifies the premium-tier archetype through combi-steamer specialization. Cleveland Range occupies a position among vertically integrated North American fabricators with foundry-to-finish manufacturing control. Hobart sits within the service-network tier, leveraging extensive technician footprints to reduce downtime guarantees for healthcare and hospitality operators.
| Leading Market Players |
|---|
| Rational AG |
| Cleveland Range |
| Hobart |
| Vulcan |
| Alto-Shaam |
| G.S. Blodgett |
| AccuTemp Products |
| Unified Brands |
| Middleby Corporation |
| Others |
Supply Flow & Price Mechanics
EPA Energy Star certification thresholds simultaneously gate supply qualification for federal procurement tenders and stratify price realization across equipment tiers, forcing manufacturers to absorb compliance costs or forfeit institutional volume. This regulatory filtering concentrates margin capture among pre-certified portfolios while compressing pricing power for atmospheric steamer incumbents facing disqualification from new construction specifications.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value realization beyond equipment margins. Three-tier pricing structure across premium combi-steamers, standard convection units, and economy electric models tracks NSF certification grade and connected-platform capability. Cost compression in the economy tier intensifies because 304-grade stainless steel input volatility erodes fabrication margins. Fast-casual chains exhibit highest price sensitivity, while German hospital procurement committees accept premiums for pre-validated ASME-certified pressure vessels.
Supply Chain Analysis
Inventory lead times for boiler components and pressure vessel assemblies have extended due to foundry capacity concentration in specific industrial regions. China, Germany, and the United States anchor stainless steel fabrication and control systems integration. Supply chains draw from nickel and chromium commodity markets, ASME-certified foundries, and IoT sensor module producers. Single-source vulnerability in pressure vessel certification creates procurement friction. Distribution runs through manufacturer-direct service networks and foodservice equipment dealers with installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial steamer market sits in early-cycle expansion as electrification mandates and connected kitchen platforms displace legacy boiler infrastructure across institutional foodservice. EPA and EU regulatory tailwinds accelerate replacement demand beyond natural equipment depreciation cycles.
For Market Incumbents: Secure captive supply of 304-grade stainless steel through backward integration or long-term offtake agreements to buffer nickel price volatility. Defend service-network density as a differentiation vector against emerging cloud-connected entrants, prioritizing technician footprint expansion in healthcare-dense metropolitan clusters. For New Entrants and Emerging Players: NSF International certification fast-tracks unlock access to US hospital procurement frameworks where pre-validation requirements create incumbent protection. Target mid-scale restaurant chains in gas-moratorium jurisdictions with compact induction-based systems. Pursue equipment-as-a-service contracting models to reduce upfront capital barriers for franchise networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-connected steamer sub-segments as software margins displace hardware dependency. Five-to-ten year viability favors manufacturers with pre-certified product portfolios spanning pressure, convection, and electric categories. Monitor EPA electrification incentive expansion as inflection signal for gas-to-electric substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Captive 304-grade sourcing buffers nickel volatility for Cleveland Range and similar fabricators. |
| Cloud-Connected Predictive Maintenance Launch | Hobart's technician density enables uptime guarantees that attract healthcare procurement committees. |
| Combi-Steamer Platform Convergence | Rational AG's programmable humidity control commands premium positioning in German institutional kitchens. |
| Equipment-as-a-Service Contracting Model | Third-party finance vehicles reduce effective ownership costs for US fast-casual franchise networks. |
| ASME Pressure Vessel Pre-Certification Investment | Pre-validated portfolios accelerate installation qualification timelines for hospital foodservice directors. |
Methodological Framework
A spread of perspectives from hospital foodservice directors, restaurant chain procurement managers, foodservice equipment dealers, and aftermarket service technicians converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA Energy Star databases, NSF International certification registries, EU Ecodesign Directive technical documentation, and customs trade data for stainless steel fabrication inputs. Bottom-up equipment shipment analysis and top-down foodservice operator expenditure modeling were triangulated to constrain estimate ranges.
Segmentation dimensions modeled include product type, application context, end-user category, and equipment size tier across the projection horizon. CAGRs were derived from replacement cycle analysis, regulatory mandate timing, and electrification incentive uptake patterns. Industry-specific forecast inputs incorporated hospital cook-chill consolidation trends and municipal gas hookup moratorium expansion.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and stable commodity metal pricing; material deviation would warrant model refresh. Specific risk factors include nickel price spikes, ASME certification backlog delays, and subsidy program eligibility revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Food Display Cabinet Market