
 Multi-Deck Refrigerated Display Cases Market | 2026-2036
Multi-Deck Refrigerated Display Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Deck Refrigerated Display Cases Market Foresight
The EU F-Gas Regulation is recalibrating procurement specifications across European food retail, compelling retrofit programs and new-build projects to specify lower-GWP refrigerant architectures. Carrier Global Corporation leverages its transcritical CO2 system expertise to anchor large-format supermarket contracts in Northern Europe. Daikin Industries, Ltd. competes through integrated compressor-display unit pairings that reduce installation complexity for chain operators. Hussmann Corporation specializes in vertical multi-deck configurations with adaptive defrost controls, sustaining its position in North American grocery renovation cycles.
Multi-deck refrigerated display cases are engineered commercial fixtures employing forced-air or gravity-coil refrigeration circuits to maintain product temperatures between 0°C and 7°C across multiple horizontal or angled shelves, typically constructed with insulated steel cabinets and low-emissivity glass panels. These units serve primarily to merchandise chilled packaged foods, beverages, and deli items in self-service retail environments while minimizing thermal load through controlled air curtains. Vertical multi-deck units dominate volume deployment due to their floor-space efficiency in high-traffic aisles, while open multi-deck formats without glass doors represent the fastest-growing configuration as retailers balance merchandising accessibility against energy consumption targets. Stainless steel and aluminum framing materials command premium positioning where hygiene certification and structural longevity justify higher capital outlay.
The EPA's SNAP program in the United States and the EU F-Gas Regulation collectively constrain hydrofluorocarbon refrigerant options, redirecting engineering investment toward hydrocarbon and CO2-based systems that alter compressor sizing and cabinet insulation requirements. China's GB standards for commercial refrigeration equipment, enforced by SAMR, mandate energy-efficiency labeling that filters market access for imported display case platforms. Japan's METI Top Runner program extends comparable performance benchmarks across East Asian supply chains. Stakeholders must monitor refrigerant-phase-down schedules and efficiency-tier migrations to align product roadmaps with tightening compliance thresholds.
Market Dynamics
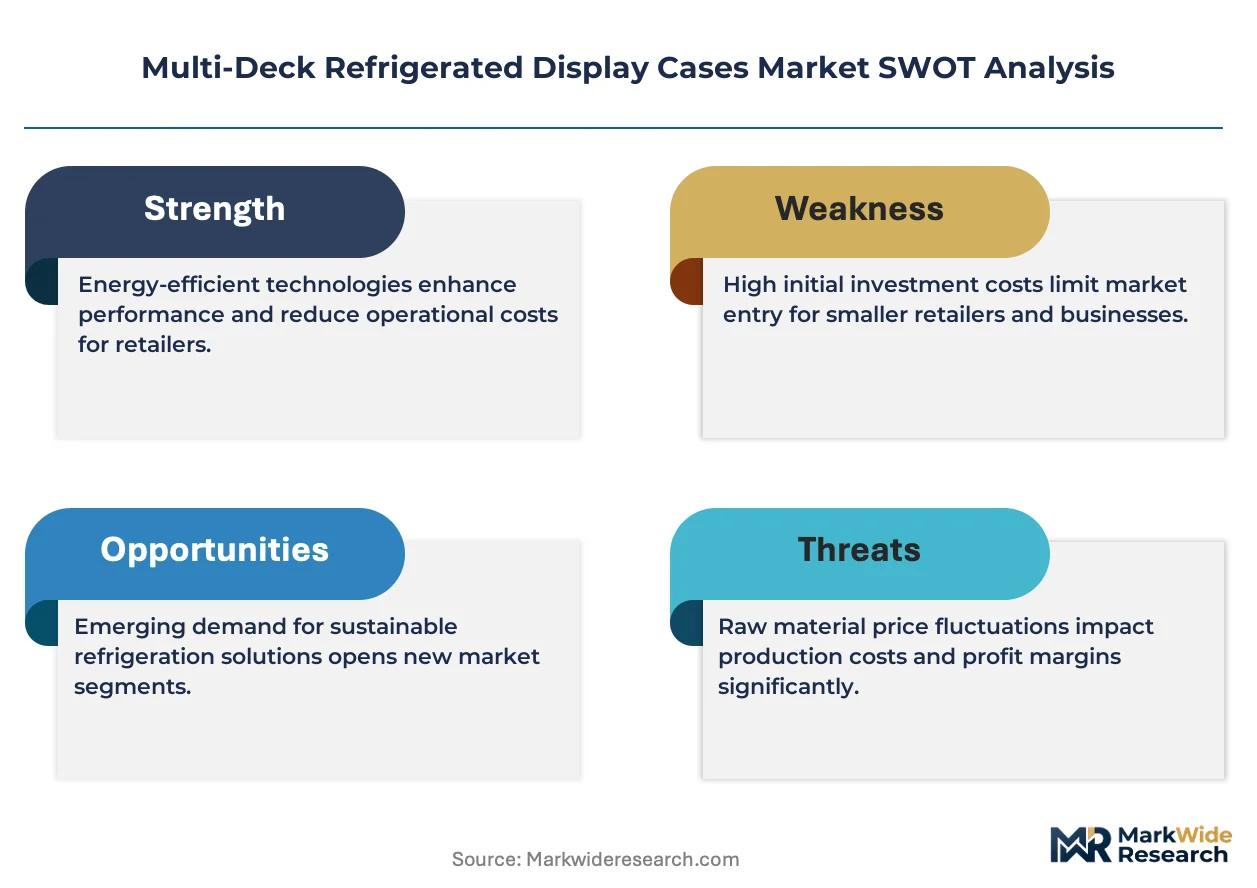
The EU F-Gas Regulation is compressing refrigerant choice sets across European food retail, forcing engineering teams to redesign compressor architectures and insulation specifications around CO2 and hydrocarbon alternatives. This single policy lever is cascading through procurement timelines, retrofit budgets, and supplier qualification criteria.
Growth Catalysts
- Natural refrigerant mandates:The EU F-Gas Regulation's phase-down schedule is accelerating specification shifts toward transcritical CO2 systems in German and French supermarket chains.
- Convenience-store format proliferation:China's tier-one cities are driving fixture replacement cycles as 7-Eleven and local chains expand chilled fresh-food footprints.
- Energy-efficiency labeling:China's GB standards enforced by SAMR are filtering market access, advantaging platforms that exceed baseline tiers.
Market Restraints
- Copper and aluminum input volatility:Cabinet framing and coil materials face commodity price swings that compress margin predictability for manufacturers.
- Compressor supply concentration:European and Japanese compressor specialists control critical component availability, creating bottleneck risk for case assemblers.
- Refrigerant retrofit complexity:The EPA's SNAP program constraints on hydrofluorocarbons force costly system redesigns for US operators with installed HFC bases.
Strategic Opportunities
- India's organized retail expansion:Reliance Retail and D-Mart are scaling chilled sections in tier-two cities where multi-deck penetration remains below Western benchmarks.
- Adaptive defrost integration:Convergence of IoT sensors with machine learning algorithms is enabling demand-responsive defrost cycles that cut energy draw.
- Japan's METI Top Runner program:Performance benchmarks are creating export pull for efficiency-optimized platforms across East Asian supply chains.
Industry Challenges
- CO2 system engineering talent scarcity:Transcritical refrigeration design requires specialized thermodynamics expertise that outpaces vocational training pipeline output.
- Legacy HFC infrastructure stranding:Supermarket operators face accelerated depreciation on existing fleets as phase-down timelines compress replacement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Deck Refrigerated Display Cases Market |
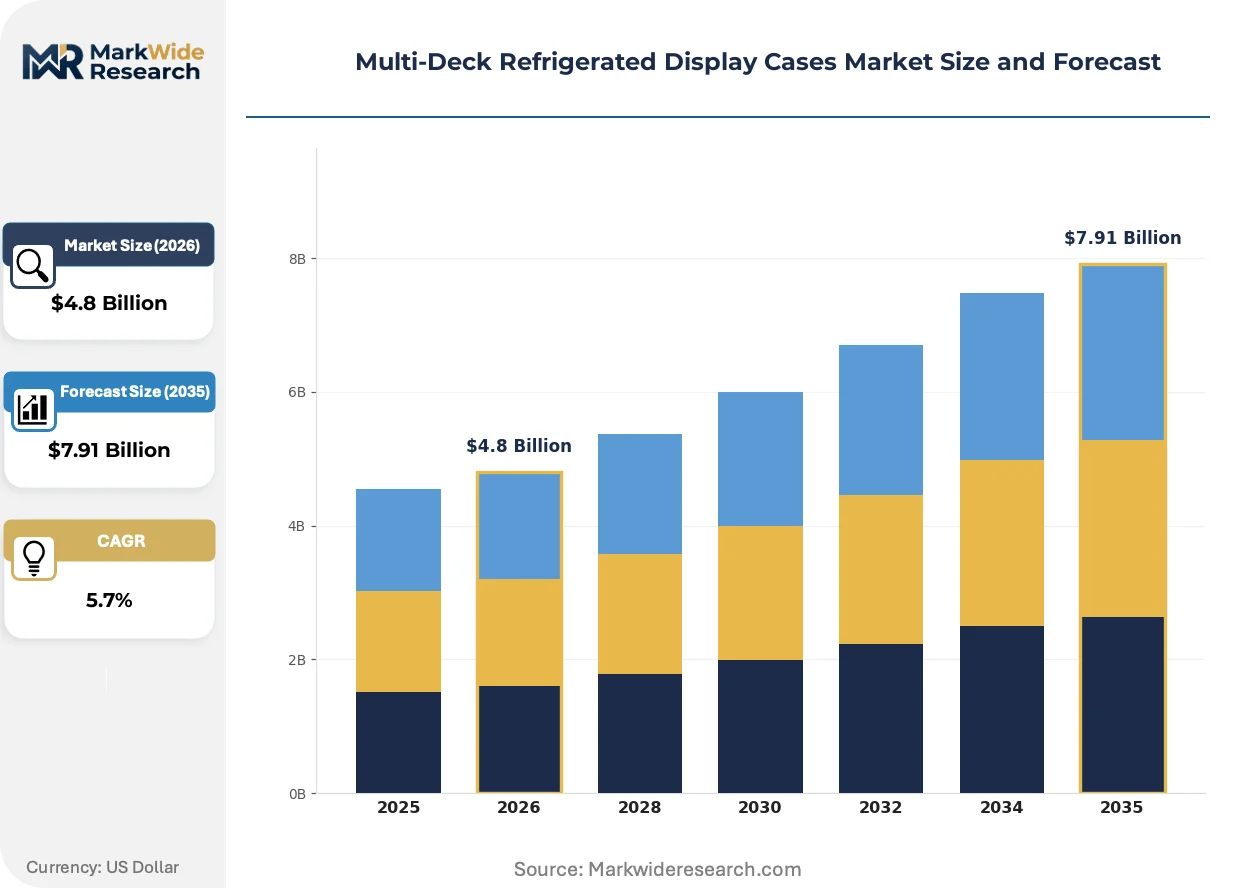
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Curved Glass, Open Multi-Deck End User: Supermarkets, Convenience Stores, Restaurants, Cafés Material: Stainless Steel, Aluminum, Glass, Plastic Feature: Energy Efficient, Adjustable Shelving, Temperature Control, LED Lighting |
| Companies Covered | Arneg S.p.A., Daikin Industries, Ltd., Carrier Global Corporation, True Manufacturing Co., Inc., Metalfrio Solutions S.A., Hussmann Corporation, AHT Cooling Systems GmbH, Panasonic Corporation, Epta S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Deck Refrigerated Display Cases Market Shifts & Advancements
Refrigeration engineering is pivoting from centralized rack systems toward distributed architectures. Three parallel developments are compressing traditional design assumptions and opening new competitive terrain.
Transcritical CO2 booster systems are decentralizing refrigeration plant design across European supermarket networks. German chains including Edeka and REWE are deploying distributed gas cooler configurations that eliminate long refrigerant pipe runs. This topology is compressing installation timelines and reducing charge volumes per store.
The EU F-Gas Regulation's 2024 review tightened hydrofluorocarbon quotas, forcing case manufacturers to validate hydrocarbon and CO2 architectures ahead of schedule. Engineering teams are redesigning cabinet insulation thickness and compressor mounting specifications. Northern European retrofit programs are absorbing the bulk of compliance-driven R&D spend.
Leasing and performance-contracting models are displacing capital purchase for multi-deck fleets in UK grocery. Tesco and Sainsbury's are unbundling equipment ownership from energy performance, shifting risk to OEM service arms. This reconfiguration is most advanced in markets where energy volatility makes operating-cost certainty valuable.
Multi-Deck Refrigerated Display Cases Market Segmentation
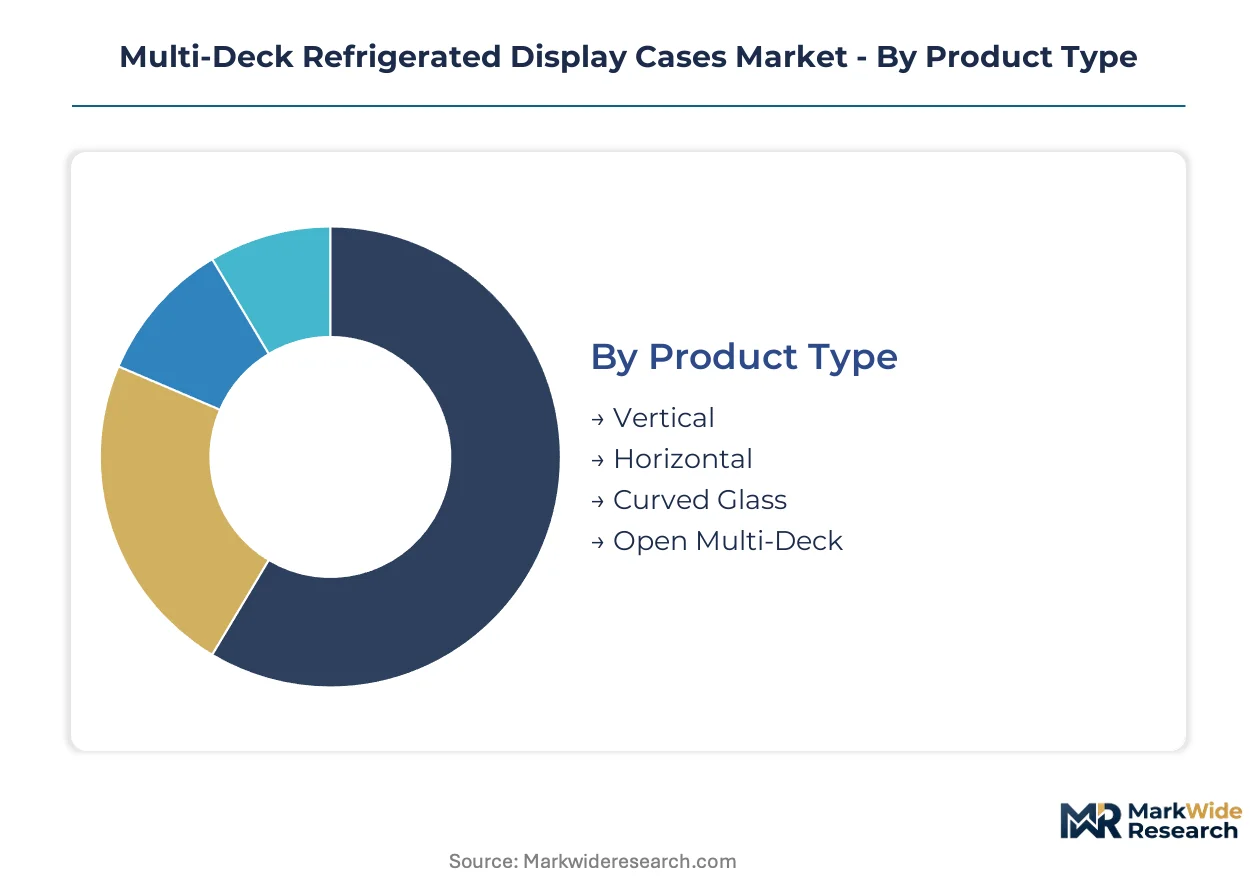
Segmentation in multi-deck refrigerated display cases reveals how fixture architecture, end-use environment, and material specification interact to determine procurement priorities. Each dimension carries distinct engineering and commercial logic that shapes supplier positioning and customer selection criteria.
Product Type:
Integration depth varies sharply across product architectures, with standalone vertical units dominating high-traffic retail floors while open formats embed into broader store design systems.
- Vertical:Tall cabinet configurations with forced-air circulation through multiple angled shelves maximize product-facing density per square meter. German supermarket chains including Edeka and REWE specify these for chilled fresh-food aisles where floor-space efficiency drives layout economics.
- Open Multi-Deck:Doorless architectures prioritize customer accessibility and impulse purchase conversion over thermal efficiency. Convenience-store operators in China's tier-one cities favor this format despite higher energy draw, balancing merchandising accessibility against operating cost targets.
- Horizontal:Low-profile cases suit deli and prepared-food sections where customer reach and sightlines matter more than vertical density.
- Curved Glass:Aesthetic-forward designs command premium positioning in upscale grocery and specialty retail environments.
Vertical configurations lead volumes today; open multi-deck formats are gaining share fastest.
End User:
Customer type determines specification rigor, with large-format operators driving standardization while fragmented foodservice accounts prioritize flexibility.
- Supermarkets:Full-service grocery operators specify integrated fleet architectures with centralized refrigeration plant compatibility. The EU F-Gas Regulation's phase-down mandates are accelerating retrofit programs across French and German chains, compressing replacement windows and favoring transcritical CO2-ready case designs.
- Convenience Stores:Small-footprint operators demand plug-and-play units with minimal installation complexity. 7-Eleven's expansion across China's tier-one cities is driving fixture replacement cycles as local chains compete on chilled fresh-food assortment.
- Restaurants:Foodservice operators prioritize hygiene certification and rapid temperature recovery under high-door-opening frequency.
- Cafés:Beverage-forward formats specify compact multi-deck units for grab-and-go chilled display with aesthetic integration into interior design.
Supermarket chains anchor procurement volumes; convenience-store format proliferation is expanding the addressable base most quickly.
Material:
Cost tier and durability requirements segment material selection, with premium stainless steel commanding hygiene-critical applications while aluminum reduces weight for modular installations.
- Stainless Steel:Corrosion-resistant 304-grade and 316-grade alloys dominate deli, seafood, and high-moisture environments where sanitation protocols mandate frequent aggressive cleaning. North American grocery renovation cycles sustain demand for structural longevity despite higher capital outlay.
- Aluminum:Lightweight extrusions enable faster installation and modular reconfiguration in convenience-store rollouts where lease terms and format experimentation drive layout flexibility.
- Glass:Low-emissivity panels with heated edges control condensation and thermal transmission in climate-variable retail environments.
- Plastic:Interior liners and trim components reduce cost in economy-tier specifications for price-sensitive emerging market deployments.
Stainless steel leads value concentration; aluminum is climbing the fastest on convenience-store format expansion.
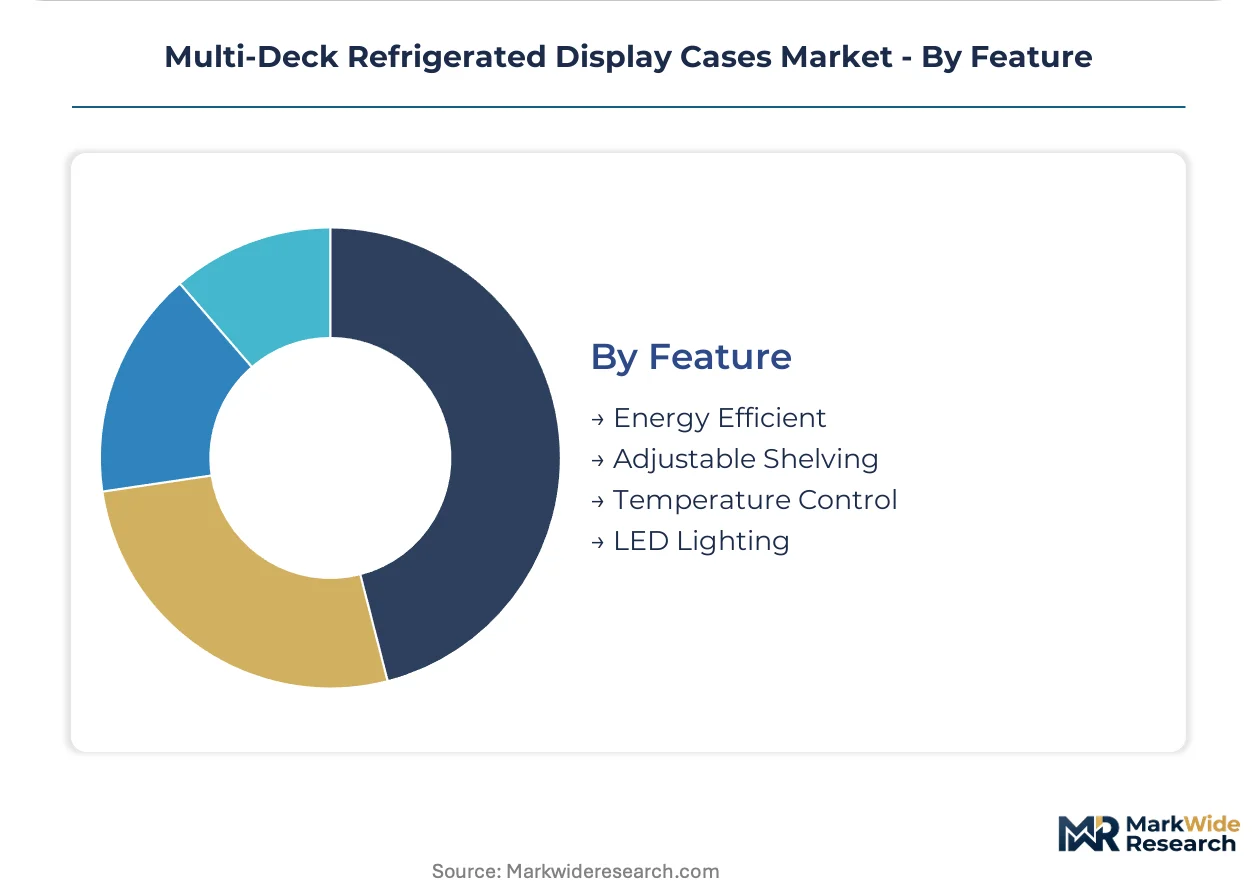
Feature:
Technology embedding depth separates basic specifications from premium tiers, with energy-efficiency optimization now table stakes rather than differentiator.
- Energy Efficient:Enhanced insulation thickness, low-emissivity glass, and optimized air curtain engineering reduce compressor runtime. China's GB standards enforced by SAMR mandate efficiency labeling that filters market access, advantaging platforms that exceed baseline tiers.
- Temperature Control:Precision electronic expansion valves and multi-sensor feedback loops maintain 0°C to 7°C band stability under variable load conditions. Japanese METI Top Runner benchmarks are creating export pull for performance-optimized platforms across East Asian supply chains.
- Adjustable Shelving:Modular racking systems accommodate SKU mix changes without case replacement, extending fixture lifecycle in volatile retail assortments.
- LED Lighting:Integrated vertical or shelf-edge illumination enhances product presentation while reducing heat load versus legacy fluorescent alternatives.
Energy-efficient specifications dominate new-build procurement; adaptive temperature control integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-deck refrigerated display case manufacturing originated in post-war European food retail modernization, with Italian and German engineering clusters establishing the foundational forced-air circulation architectures that persist today. The industry subsequently diffused through Japanese convenience-store format exports and North American supermarket consolidation. Contemporary demand concentrates in five national markets where regulatory timing and retail format evolution diverge sharply.
Germany
Edeka and REWE chains are retrofitting chilled aisles with transcritical CO2-ready vertical units ahead of EU F-Gas quota tightening. The national regulator enforces stricter hydrofluorocarbon phase-down schedules than baseline EU requirements. Engineering clusters around Stuttgart and Nuremberg supply compressor-integrated case architectures to Northern European retrofit programs.
China
7-Eleven and local convenience chains are expanding chilled fresh-food footprints across Shanghai, Beijing, and Shenzhen. SAMR-administered GB standards mandate energy-efficiency labeling that filters import access. Tier-one city procurement cycles concentrate in Yangtze River Delta manufacturing corridors where domestic case fabricators achieve scale.
United States
Kroger and Albertsons renovation programs sustain demand for stainless steel deli cases with adaptive defrost controls. EPA SNAP program constraints on hydrofluorocarbons force costly system redesigns for operators with installed HFC infrastructure. Equipment specification authority concentrates in Chicago and Dallas procurement headquarters serving continental store networks.
Japan
Lawson and FamilyMart format proliferation drives compact open multi-deck deployment in Tokyo-Osaka corridors. METI Top Runner performance benchmarks create export pull for efficiency-optimized platforms across East Asian supply chains. Nagoya-area engineering groups specialize in precision electronic expansion valve integration for temperature stability.
India
Reliance Retail and D-Mart are scaling chilled sections in Bangalore, Hyderabad, and Pune where multi-deck penetration trails Western benchmarks. BIS certification requirements for commercial refrigeration equipment filter import compliance. Western India manufacturing zones near Mumbai supply aluminum-framed modular units for rapid convenience-store rollout.
Multi-Deck Refrigerated Display Cases Market Competitive Landscape
Premium-margin players sit above commodity-margin players across refrigerant architecture sophistication and service bundling depth. The vendor base stratifies into three tiers: integrated refrigeration plant specialists, standalone case fabricators, and regional assembly operations serving price-sensitive emerging markets. Two dominant competitive moves are reshaping positioning: transcritical CO2 system engineering talent acquisition and performance-contracting model unbundling of equipment ownership from energy guarantees.
Within the integrated systems tier, Carrier Global Corporation and Daikin Industries, Ltd. occupy positions that span compressor technology and display case integration. Hussmann Corporation exemplifies the North American vertical specialist archetype with concentrated presence in grocery renovation cycles. These three entities represent divergent strategic bets on refrigerant transition timing and geographic format proliferation.
| Leading Market Players |
|---|
| Arneg S.p.A. |
| Daikin Industries, Ltd. |
| Carrier Global Corporation |
| True Manufacturing Co., Inc. |
| Metalfrio Solutions S.A. |
| Hussmann Corporation |
| AHT Cooling Systems GmbH |
| Panasonic Corporation |
| Epta S.p.A. |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation's hydrofluorocarbon phase-down schedule gates qualified supply for transcritical CO2-ready case architectures and anchors premium-tier pricing access for compliant manufacturers serving German and French supermarket retrofit programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates stainless steel transcritical CO2 systems from aluminum-framed hydrocarbon units and basic HFC-based imports. Price differentiation hinges on refrigerant architecture certification tier and after-sales service bundling depth. Cost compression in economy tiers intensifies as Chinese domestic fabricators achieve scale in Yangtze River Delta manufacturing corridors. Convenience-store operators exhibit highest price sensitivity, while German Edeka and REWE chains prioritize lifecycle operating-cost certainty over capital outlay.
Supply Chain Analysis
Specialized welding and refrigeration engineering talent availability constrains output expansion in German and Italian manufacturing clusters where transcritical CO2 expertise concentrates. Component sourcing draws from Chinese aluminum extrusion hubs, Japanese precision valve specialists, and European compressor engineering groups. Single-source vulnerability runs through Japanese electronic expansion valve suppliers serving temperature-control subsystems. Distribution runs through OEM-direct contracting for large-format supermarket chains and specialized refrigeration distributors serving fragmented convenience-store accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural refrigerant transition timelines compress replacement windows and expand premium-tier attach rates, creating margin-expansion headroom for engineering-capable suppliers.
For Market Incumbents: Deepen transcritical CO2 system engineering talent pools through targeted acquisition of German and Austrian refrigeration specialists to defend against emerging Asian compressor-integrated case platforms. Anchor fleet retrofit contracts with performance-guarantee service bundling that locks out price-competitive challengers. For New Entrants and Emerging Players: The mid-market price-point gap between premium stainless steel transcritical systems and basic aluminum HFC units creates white-space opportunity for hydrocarbon-ready case platforms with modular installation architecture. Target India's tier-two city convenience-store rollouts where BIS certification barriers filter import competition and local manufacturing partnerships accelerate market access. For Investors and Strategic Acquirers: Roll-up economics work for regional case fabricators with established SAMR or BIS certification pathways because regulatory compliance investments create moats against unqualified competitors. Monitor EU F-Gas quota auction prices as inflection indicator for retrofit program acceleration and premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Transcritical CO2 Engineering Acquisition | Carrier and Daikin compete for German refrigeration specialist talent pools ahead of quota tightening. |
| Performance-Contracting Model Expansion | Tesco and Sainsbury's unbundle ownership from energy guarantees, shifting risk to OEM service arms. |
| Adaptive Defrost Technology Integration | IoT sensor and machine learning convergence enables demand-responsive cycles that cut energy draw. |
| India Tier-Two Manufacturing Localization | Reliance Retail and D-Mart expansion creates pull for aluminum-framed modular units near Mumbai. |
| Natural Refrigerant Certification Investment | GB standards and METI Top Runner benchmarks filter market access for efficiency-optimized platforms. |
Research Methodology
Bottom-up supermarket and convenience-store operator modeling reconciled against top-down compressor and case fabricator production tracking forms the analytical core of this study. Primary interviews with refrigeration plant engineering directors, supermarket procurement heads, convenience-store format development leads, and commercial refrigeration distributors combined with secondary validation against SAMR GB standard filings, EU F-Gas Regulation quota registry data, and METI Top Runner benchmark disclosures. Triangulation across stakeholder inputs and regulatory databases ensures segmentation integrity.
Input-output matrices map transcritical CO2 system deployment rates, hydrocarbon architecture adoption curves, and aluminum versus stainless steel material mix shifts across the projection horizon. Segmentation dimensions include product architecture, end-use environment, material specification, and feature embedding depth. CAGRs derive from installer pipeline tracking and retrofit program announcement monitoring. Forecast inputs incorporate refrigerant-phase-down schedule compliance cost modeling and convenience-store format proliferation velocity in named city clusters.
Caveats apply where EU F-Gas Regulation review outcomes or EPA SNAP program rulemaking could materially shift the outlook for hydrofluorocarbon retrofit economics. Forecasts reflect assumptions about commodity input price stability and compressor specialist supply availability. Practitioners should monitor quota auction price volatility and transcritical CO2 engineering graduate pipeline output for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Commercial Hot Dog Cooker Market