
 Gas Floor Fryers Market | 2026-2036
Gas Floor Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Floor Fryers Market Foresight
EPA commercial kitchen emissions guidelines is recalibrating procurement priorities across the foodservice sector. Henny Penny leverages its vertical integration into burner assembly manufacturing to control cost structures and accelerate compliance-ready product cycles. Middleby Corporation anchors its position through R&D intensity focused on automated temperature control systems that reduce idle energy consumption. ITW Food Equipment Group competes on geographic dominance, sustaining dense service networks that minimize downtime for high-volume operators.
Gas floor fryers are freestanding commercial cooking appliances that heat oil through direct or radiant gas combustion to temperatures between 325°F and 400°F for batch or continuous food frying. Stainless steel tank construction, cast-iron burner assemblies, and integrated filtration systems define the equipment category, which serves quick-service chains, full-service restaurants, and institutional cafeterias requiring sustained high-volume output. High-efficiency gas fryers capture expanding margin pools as operators prioritize ENERGY STAR-compliant models that trim utility expenditures under tightening operating budgets. Automated temperature control technology leads growth trajectories by reducing oil degradation and labor intervention, while standard gas floor fryers occupy the mature replacement segment where price sensitivity dominates purchasing decisions.
EPA emissions protocols, DOE commercial cooking efficiency mandates, and NFPA 96 ventilation standards collectively shape equipment specifications, installation requirements, and market access conditions across the United States. State-level energy rebate programs in California, Texas, and Florida amplify federal incentives and accelerate turnover of pre-2015 fryer inventories. Stakeholders must monitor evolving burner efficiency thresholds and filtration integration requirements as regulatory layering intensifies capital planning complexity for multi-unit operators.
Market Dynamics
EPA emissions thresholds and DOE commercial cooking efficiency standards are forcing a wholesale retirement of legacy open-pot fryers across American foodservice operations, compressing replacement cycles and redirecting capital toward compliance-ready equipment with integrated filtration and automated controls.
Growth Catalysts
- ENERGY STAR Rebate Amplification:State-level programs in California, Texas, and Florida stack federal incentives, accelerating turnover of pre-2015 fryer inventories in quick-service chains.
- Quick-Service Footprint Expansion:Southern United States franchise development rates outpace national averages, concentrating demand for high-throughput gas floor fryers in metropolitan clusters.
- Automated Temperature Control:Sensor-driven oil management systems reduce degradation and labor intervention, pulling upgrade demand from full-service restaurants seeking operational consistency.
Market Restraints
- Stainless Steel Input Volatility:Commodity price swings for 304-grade tank construction compress manufacturer margins and complicate long-term contract pricing.
- Cast-Iron Burner Supply Concentration:Domestic foundry capacity constraints in the Midwest create single-source vulnerabilities for critical burner assembly components.
- NFPA 96 Ventilation Mandates:Installation cost escalation for hood and ductwork upgrades delays replacement decisions among independent operators.
Strategic Opportunities
- Institutional Cafeteria Modernization:K-12 and university foodservice directors face mandated efficiency upgrades, creating volume demand for ENERGY STAR-certified equipment.
- Filtration-Oil Management Convergence:Integration of automated filtration with predictive oil quality monitoring opens premium pricing tiers for integrated system vendors.
- Cloud Kitchen Infrastructure Buildout:Ghost kitchen operators prioritize equipment density and throughput over front-of-house aesthetics, favoring compact high-BTU floor fryer configurations.
Industry Challenges
- Certified Food Equipment Technician Shortage:Complex burner control and filtration integration demands specialized service capability that distributor networks struggle to staff.
- Legacy Hood System Compatibility:Pre-2010 ventilation infrastructure requires costly retrofitting to accommodate high-efficiency fryer exhaust profiles, stretching project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Floor Fryers Market |
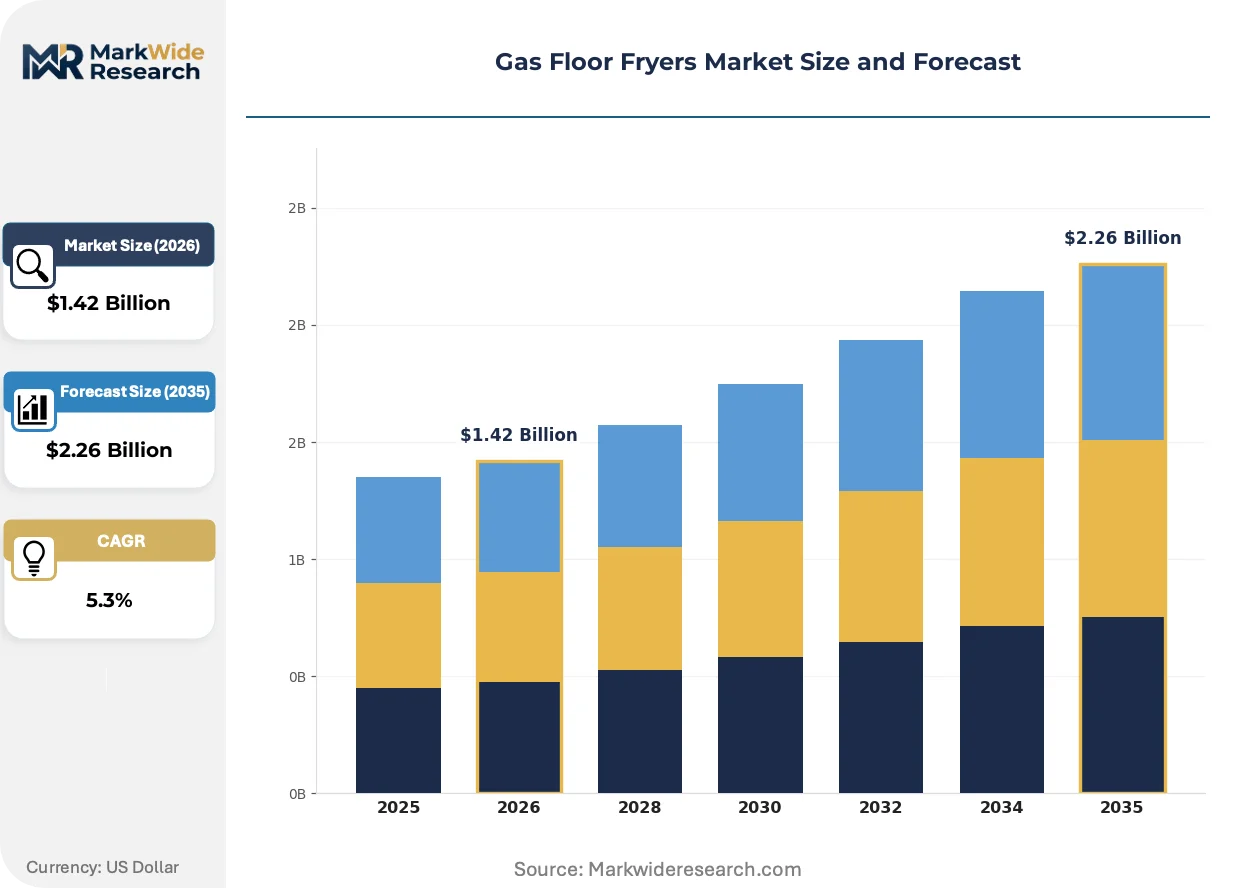
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.26 Billion |
| CAGR (2026 – 2036) | 5.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gas Floor Fryers, High-Efficiency Gas Fryers, Built-In Gas Fryers, Mobile Gas Fryers, Countertop Gas Fryers Technology: Direct Gas Heating, Radiant Gas Heating, Infrared Gas Heating, Convection Gas Heating, Automated Temperature Control Usage Environment: Commercial Kitchens, Food Trucks, Catering Services, Institutional Canteens, Outdoor Food Stalls End User: Restaurants, Quick-Service Chains, Hospitality Operators, Foodservice Providers, Cafeterias |
| Companies Covered | Henny Penny, Middleby Corporation, ITW Food Equipment Group, Ali Group, Frymaster, Vulcan, Pitco, Electrolux Professional, Standex International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Floor Fryers Market Shifts & Advancements
Equipment architecture is fragmenting into configurable subsystems as operators demand field-upgradable capability without full replacement, while regulatory layering forces simultaneous compliance across emissions, efficiency, and safety domains.
Split-tank fryer architecture is modularizing kitchen line configurations by allowing independent temperature zones within a single footprint. Quick-service chains deploying these units in high-volume locations report reduced cross-contamination risk and improved throughput during peak periods. The technology is modularizing procurement patterns, letting operators standardize on a single platform while customizing zone capacity to menu mix.
EPA commercial kitchen emissions guidelines are recalibrating burner efficiency thresholds, compelling manufacturers to redesign combustion systems for sub-40 ppm carbon monoxide output. This industrial consequence elevates R&D intensity for in-house burner assembly production. High-volume operators in the southern United States are responding by consolidating purchases with vendors holding captive combustion engineering capability.
Service contract unbundling is separating equipment acquisition from maintenance obligations, with multi-unit chains negotiating direct relationships with regional service aggregators. Distributor channels face margin compression as buyers source fryers through procurement consortiums and negotiate aftermarket support separately. This pattern is most visible in Texas and Florida metropolitan markets where franchisee associations wield collective purchasing leverage.
Gas Floor Fryers Market Segmentation
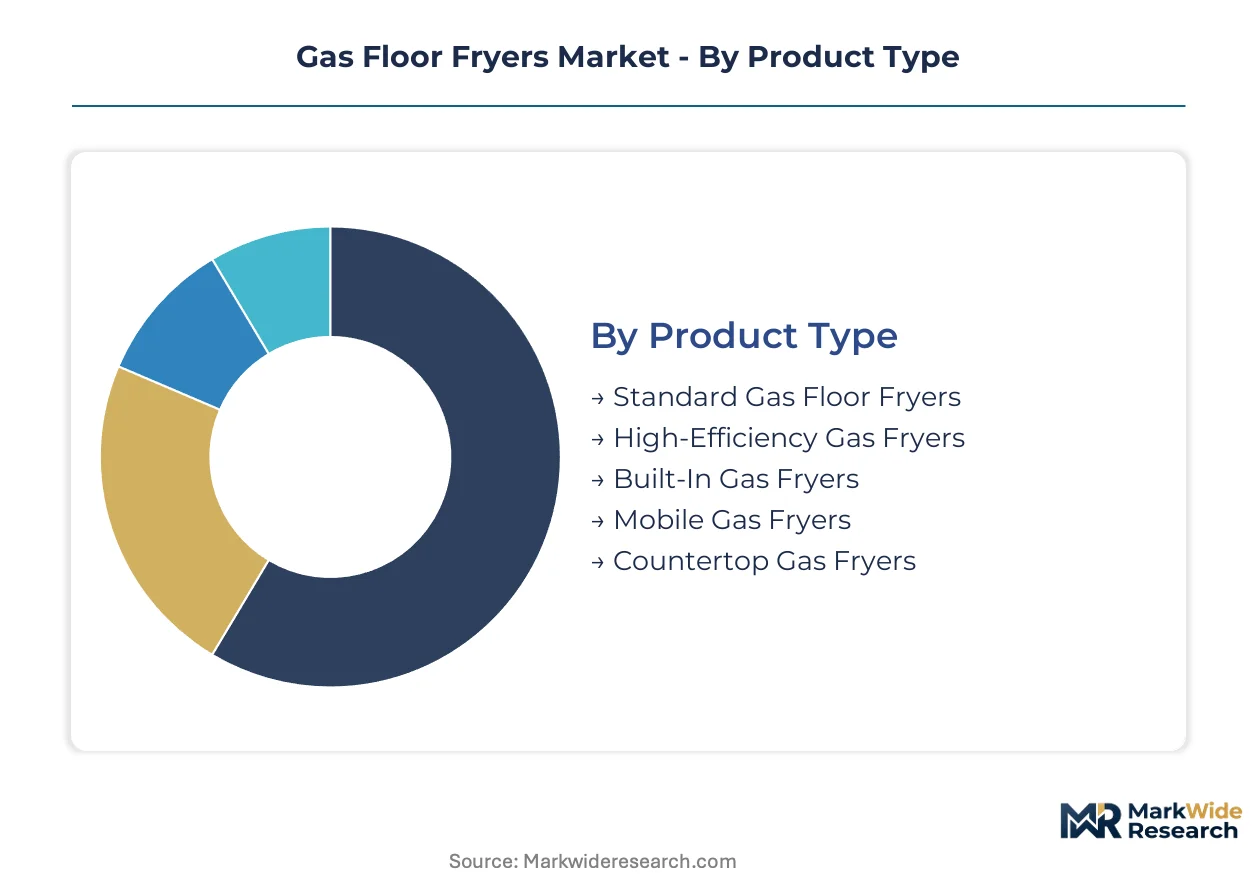
Gas floor fryer purchasing decisions hinge on balancing throughput requirements against energy compliance costs and installation constraints. Operators segment their procurement across efficiency tiers, heating technologies, and operational environments to match equipment specifications to menu volume and regulatory exposure.
Product Type:
Price sensitivity and ENERGY STAR certification status drive buyer selection across the product spectrum, with rebate eligibility often overriding upfront cost considerations.
- Standard Gas Floor Fryers:Open-pot construction with fixed temperature controls and basic cast-iron burner assemblies. Demand concentrates among independent operators in Texas and Florida where replacement cycles compress under state-level efficiency mandates but federal rebate thresholds remain unmet.
- High-Efficiency Gas Fryers:Insulated frypot designs with integrated filtration and programmable controls that trim idle energy consumption. Quick-service chains across California deploy these units to capture stacked federal and state rebates while preempting EPA emissions enforcement.
- Built-In Gas Fryers:Custom line-integrated configurations for new construction kitchen builds.
- Mobile Gas Fryers:Castor-mounted units with quick-disconnect gas fittings for temporary operations.
- Countertop Gas Fryers:Compact footprints under 50 lb oil capacity targeting low-volume fry stations.
High-efficiency models lead on scale; standard units lead on replacement velocity.
Technology:
Heating system selection determines burner efficiency thresholds, oil recovery speed, and compliance with evolving EPA carbon monoxide output limits.
- Direct Gas Heating:Flame impingement on frypot base delivers rapid temperature recovery but generates higher emissions profiles. Southern United States quick-service operators favor these systems for peak throughput handling despite pending regulatory pressure.
- Automated Temperature Control:Sensor-driven oil management with programmable setpoints and filtration integration. Full-service restaurants in metropolitan California markets adopt these systems to reduce labor intervention and extend oil life cycles.
- Radiant Gas Heating:Ceramic burner elements distributing heat across extended surface areas.
- Infrared Gas Heating:Catalytic combustion systems targeting sub-40 ppm carbon monoxide benchmarks.
- Convection Gas Heating:Forced-air circulation around frypot exteriors for uniform temperature distribution.
Direct gas heating dominates installed base; automated temperature control gains share fastest.
Usage Environment:
Installation constraints and ventilation infrastructure availability dictate equipment mobility and footprint requirements across operating contexts.
- Commercial Kitchens:Fixed hood-connected installations with dedicated gas lines and NFPA 96-compliant fire suppression. Demand clusters in Texas and Florida quick-service chain expansions where new construction permits specify high-efficiency equipment.
- Food Trucks:Compact low-BTU configurations with portable ventilation and propane conversion capability. Southern California mobile food operators drive specification innovation for space-constrained frying capacity.
- Catering Services:Event-temporary deployments requiring rapid setup and breakdown protocols.
- Institutional Canteens:K-12 and university cafeterias facing mandated efficiency upgrade schedules.
- Outdoor Food Stalls:Weather-resistant construction with wind-defeating burner shrouds.
Commercial kitchens anchor volume; food trucks show steepest expansion trajectory.
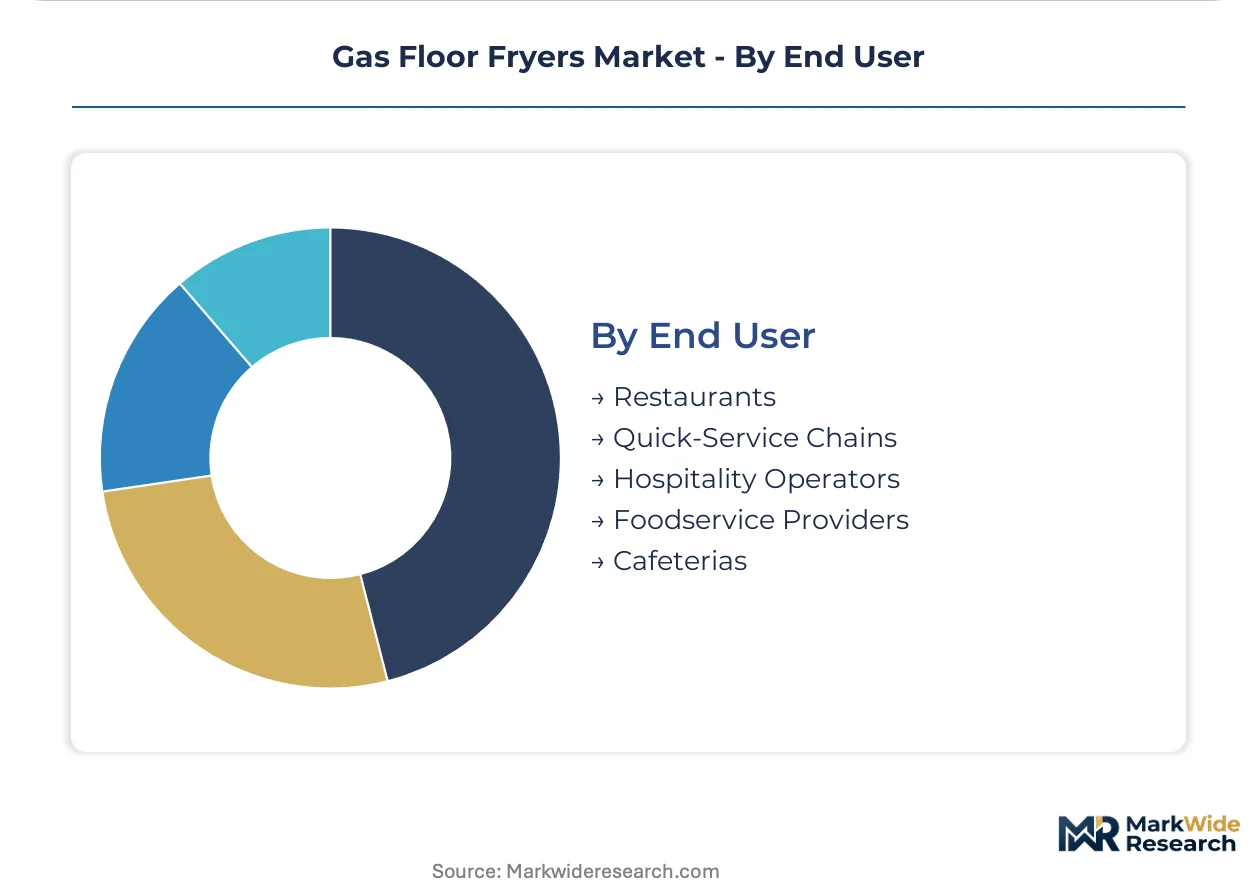
End User:
Procurement authority and capital allocation timelines vary sharply between franchise systems and independent operators.
- Quick-Service Chains:Corporate-level fleet standardization with negotiated national service contracts. Southern United States franchise development concentrates demand for high-throughput split-tank configurations in metropolitan clusters.
- Restaurants:Owner-operator purchasing with price sensitivity dominating replacement decisions. Independent full-service establishments in California leverage state rebates to offset ENERGY STAR upgrade premiums.
- Hospitality Operators:Hotel and resort foodservice directors balancing guest volume against utility cost management.
- Foodservice Providers:Contract management companies serving institutional accounts with mandated compliance schedules.
- Cafeterias:K-12 and corporate dining facilities with constrained capital cycles and efficiency mandates.
Quick-service chains lead on procurement scale; restaurants lead on unit count dispersion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified food equipment technician density concentrates in Texas, California, and Florida metropolitan corridors, anchoring regional service capability and shaping equipment procurement patterns across quick-service franchise networks.
United States
Southern quick-service franchise development outpaces national averages, concentrating demand for high-throughput split-tank configurations in Houston, Dallas-Fort Worth, and Atlanta metropolitan clusters. EPA emissions thresholds and DOE commercial cooking efficiency standards compress replacement cycles for pre-2015 open-pot fryer inventories. Texas and Florida state-level energy rebate programs stack federal ENERGY STAR incentives, accelerating turnover in independent operator segments.
Canada
Quick-service chain expansion in Ontario and British Columbia drives specification demand for ENERGY STAR-certified equipment with integrated filtration systems. Health Canada and PMRA oversight of commercial kitchen ventilation aligns with NFPA 96 adoption, elevating installation compliance costs in Vancouver and Toronto foodservice buildouts. Prairie Provinces institutional cafeteria modernization programs create volume demand for high-efficiency gas fryers in K-12 and university settings.
Mexico
Franchise development in Mexico City Metro and Nuevo León concentrates procurement of direct-gas heating systems for peak throughput handling. SAMR-aligned efficiency benchmarking through national standards bodies shapes equipment import specifications. Guadalajara and Monterrey industrial corridors host assembly operations for burner components serving North American supply chains.
Germany
Commercial kitchen equipment OEMs in Baden-Württemberg and North Rhine-Westphalia drive R&D intensity for automated temperature control systems. Ecodesign Directive and EU F-Gas Regulation compliance requirements elevate burner efficiency thresholds for export-bound equipment. Bavaria's precision manufacturing clusters supply ceramic burner elements to pan-European fryer assembly networks.
China
Stainless steel fabrication capacity in Yangtze River Delta and Pearl River Delta regions supplies 304-grade frypot construction to global OEMs. MIIT industrial efficiency mandates and GB standards for commercial cooking equipment shape domestic product specifications. Shenzhen and Shanghai equipment distributors serve cloud kitchen infrastructure buildouts with compact high-BTU floor fryer configurations.
Gas Floor Fryers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the gas floor fryer landscape, with integrated foundry operations controlling burner assembly cost structures while specialized fabricators outsource critical components. The vendor base stratifies across three tiers: captive combustion engineering specialists, stainless steel tank fabricators with regional service networks, and diversified food equipment conglomerates with procurement consortium relationships. Two dominant competitive moves define current positioning: backward integration into burner manufacturing to secure supply and accelerate compliance cycles, and unbundling of service contracts to capture aftermarket revenue through direct regional aggregator relationships.
Within the captive engineering tier, Henny Penny exemplifies vertical control over burner assembly production, while Middleby Corporation anchors R&D-intensive positioning through automated temperature control specialization. ITW Food Equipment Group occupies the geographic dominance archetype, sustaining dense service networks that minimize downtime for high-volume operators. These three patterns—upstream manufacturing control, technology-led efficiency differentiation, and service infrastructure scale—represent the primary competitive vectors reshaping procurement relationships with quick-service chains and institutional buyers.
| Leading Market Players |
|---|
| Henny Penny |
| Middleby Corporation |
| ITW Food Equipment Group |
| Ali Group |
| Frymaster |
| Vulcan |
| Pitco |
| Electrolux Professional |
| Standex International |
| Others |
Supply & Pricing Matrix
Certified food equipment technician concentration in Texas, California, and Florida metropolitan corridors creates labor-cost differentials that widen pricing spreads between premium ENERGY STAR-certified systems and economy-tier open-pot replacements. Southern quick-service chains absorb higher installation premiums for compliance-ready equipment while independent operators in rebate-poor markets face compressed margins on standard units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies procurement decisions by ENERGY STAR certification status and after-sales service bundling. Price differentiation centers on burner efficiency ratings and filtration integration depth, with California operators least sensitive due to stacked rebate programs. Pricing pressure stems from stainless steel commodity volatility squeezing manufacturer margins on fixed-price contracts. Independent restaurants in Texas and Florida exhibit highest price sensitivity, prioritizing upfront cost over lifecycle efficiency.
Supply Chain Analysis
Cast-iron burner assembly supply rests on domestic Midwest foundry capacity and Mexican maquiladora operations serving North American OEMs. Stainless steel 304-grade tank fabrication draws from Yangtze River Delta mills and domestic rolling facilities in Pennsylvania and Ohio. Single-source vulnerability concentrates in ceramic burner element production anchored in Bavaria, Germany. Distribution runs through manufacturer-direct channels for national quick-service accounts and regional equipment distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
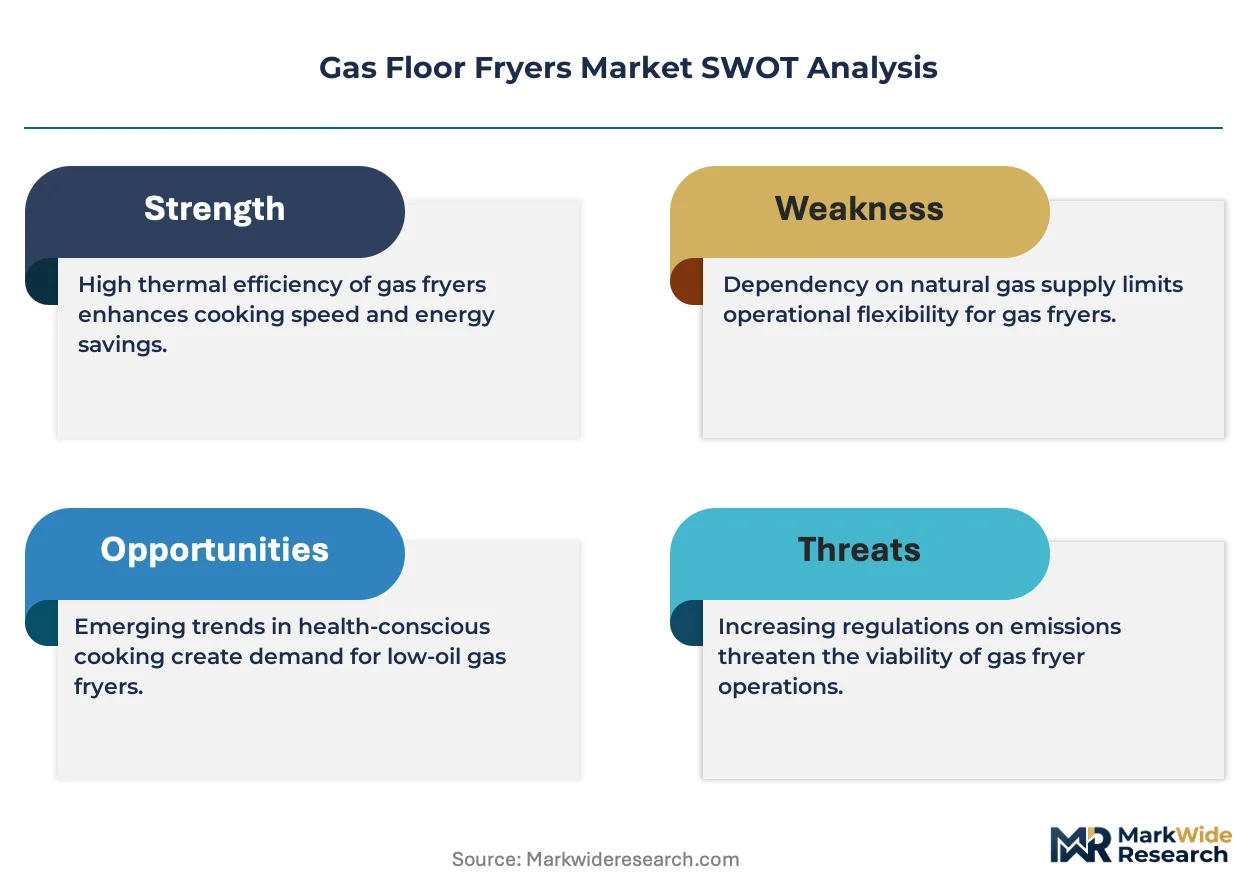
The Gas Floor Fryers Market functions as a geographic-arbitrage play where Texas and Florida state rebate programs create procurement cost advantages against California's stricter EPA enforcement timelines and higher compliance premiums.
For Market Incumbents: Extend captive burner engineering capabilities to compress compliance cycle times ahead of sub-40 ppm carbon monoxide thresholds. Deepen service network density in Houston and Dallas-Fort Worth metropolitan clusters to capture quick-service franchise expansion. Consolidate distributor relationships in Texas and Florida to preempt procurement consortium unbundling. For New Entrants and Emerging Players: The $800-1,200 price-point gap between premium ENERGY STAR systems and economy open-pot units opens white-space targeting of mid-tier automated temperature control configurations. Food truck and ghost kitchen segments in Southern California show lowest incumbent penetration. Pursue cloud kitchen infrastructure buildouts with compact high-BTU floor fryer configurations and quick-disconnect gas fittings. For Investors and Strategic Acquirers: Diversified food equipment conglomerates are the most active acquirer in this space, seeking regional service network scale and burner assembly captive production. Five-to-ten-year viability hinges on regulatory layering intensity across emissions, efficiency, and safety domains. Target acquisition archetype: stainless steel fabricators with dense Midwest service footprints and latent combustion engineering capability. Watch EPA enforcement acceleration in southern United States metropolitan clusters as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Manufacturing | Henny Penny's captive combustion engineering accelerates compliance-ready product cycles ahead of EPA thresholds. |
| Regional Service Network Expansion | ITW Food Equipment Group's Texas and Florida density minimizes downtime for high-volume quick-service operators. |
| Automated Temperature Control R&D Investment | Middleby Corporation's sensor-driven oil management systems extend fryer lifecycle and reduce labor intervention. |
| Procurement Consortium Relationship Building | Direct franchisee association negotiations in Texas and Florida bypass distributor margin compression. |
| Filtration-Oil Management System Integration | Predictive oil quality monitoring opens premium pricing tiers for integrated system vendors serving California chains. |
Research Methodology
Coverage spans the United States, Canada, Mexico, Germany, and China, with primary inputs from each market cluster combining executive interviews and secondary validation. Conversations with quick-service chain procurement directors, commercial kitchen equipment distributors, certified food equipment technicians, and institutional cafeteria directors informed demand-side dynamics. Secondary sources included EPA emissions filings, DOE efficiency standard updates, ENERGY STAR certification databases, and state-level rebate program documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Rate-of-change decomposition across the analysis window separated replacement cycle compression from new construction demand and regulatory-driven upgrade acceleration. Segmentation dimensions modeled include efficiency tier, heating technology, usage environment, and end-user procurement authority. CAGRs derived from regression analysis of historical shipment data against macroeconomic indicators and regulatory implementation timelines. Industry-specific forecast inputs incorporated stainless steel price indices and certified technician labor availability by metropolitan statistical area.
Caveats apply where EPA enforcement acceleration or DOE efficiency threshold revisions could materially shift the outlook beyond modeled parameters. Forecasts reflect assumptions about state rebate program continuity and foundry capacity expansion in the Midwest. Stainless steel commodity volatility, single-source burner component dependencies, and NFPA 96 ventilation retrofit cost escalation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Japan Foodservice Market
Food Service
Steam Tables and Food Well Market
Food Service
Global Online Food Ordering Market
Food Service
Instant Grocery Market
Food Service
Global Vending Machine Market
Food Service
Food Service Disposables Market
Food Service
Food Away from Home Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Takeout Dinner Market
Food Service
China Online Food Delivery Market
Food Service
Global Dark Store Market
Food Service
Commercial Ice Dispenser Market
Food Service
Food Truck Services Market