
 Meal Delivery Carts and Racks Market | 2026-2036
Meal Delivery Carts and Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Meal Delivery Carts and Racks Market Analytics
NSF-certified construction is collapsing into the baseline expectation across institutional procurement, eroding the premium that stainless steel fabrication once commanded. Cambro leverages its polymer engineering expertise to dominate insulated cart production for healthcare networks. Carter-Hoffmann anchors the high-end thermal holding segment with welded aluminum chassis designs that sustain temperature integrity across extended delivery routes.
Meal delivery carts and racks comprise wheeled food transport equipment engineered with thermal insulation layers, typically polyurethane foam cores rated for 180-minute heat retention, designed to maintain safe food temperatures between kitchen origin and patient or patron destination. Mobile racks and delivery carts lead volume shipments due to hospital consolidation of tray-line operations into centralized commissary models, while customizable design types capture widening margin pools as facilities demand ward-specific configurations. Stainless steel material grades retain institutional preference for infection control compliance, though aluminum competes aggressively on weight reduction in high-frequency shuttle applications.
The US FDA Food Code and NSF International standards govern surface material safety and temperature holding validation, forcing manufacturers to submit products for third-party certification before healthcare system acceptance. OSHA ergonomic guidelines on push-force limits influence caster specification and handle geometry, particularly in hospital environments with aging foodservice workforces. Stakeholders must monitor how state-level healthcare facility licensing boards incorporate updated food transport equipment standards into operational inspection checklists.
Market Dynamics
Centralized hospital catering models are compressing tray-line footprints and forcing equipment suppliers to engineer higher-density mobile rack configurations that sustain thermal integrity across extended transport corridors.
Growth Catalysts
- US FDA Food Code temperature mandates:Updated holding requirements for hot and cold food transport are triggering replacement cycles in acute care facilities seeking compliant insulated cart systems.
- Germany's centralized hospital catering expansion:Bundesland-level healthcare consolidation is concentrating procurement authority and standardizing high-capacity meal delivery rack specifications across integrated provider networks.
- Polyurethane foam core advancement:180-minute heat retention ratings in next-generation insulation materials are extending viable delivery radius for commissary-based foodservice operations.
Market Restraints
- Stainless steel input cost volatility:Nickel and chromium price fluctuations are compressing fabrication margins for NSF-certified institutional equipment manufacturers.
- Aluminum supply concentration:Primary smelter capacity in specific geographies creates vulnerability for welded chassis producers serving thermal holding segments.
- Ergonomic push-force thresholds:OSHA guidelines on manual handling limits are constraining cart weight capacity and complicating high-density rack designs.
Strategic Opportunities
- India hospital infrastructure expansion:Greenfield medical cities under the Ayushman Bharat scheme are specifying modular meal delivery systems without legacy equipment constraints.
- Smart cart integration:Convergence of RFID tracking and temperature logging is creating premium upgrade pathways for healthcare networks pursuing digital food safety audit trails.
- Direct-to-facility distribution:Bypassing traditional medical equipment distributors through manufacturer-owned service networks is capturing margin in high-volume institutional accounts.
Industry Challenges
- NSF certification timeline compression:Third-party validation bottlenecks are delaying product launches and freezing engineering change orders mid-cycle.
- Ward-specific configuration complexity:Customized rack dimensions for pediatric, bariatric, and immunocompromised units are fragmenting production runs and elevating tooling costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Delivery Carts and Racks Market |
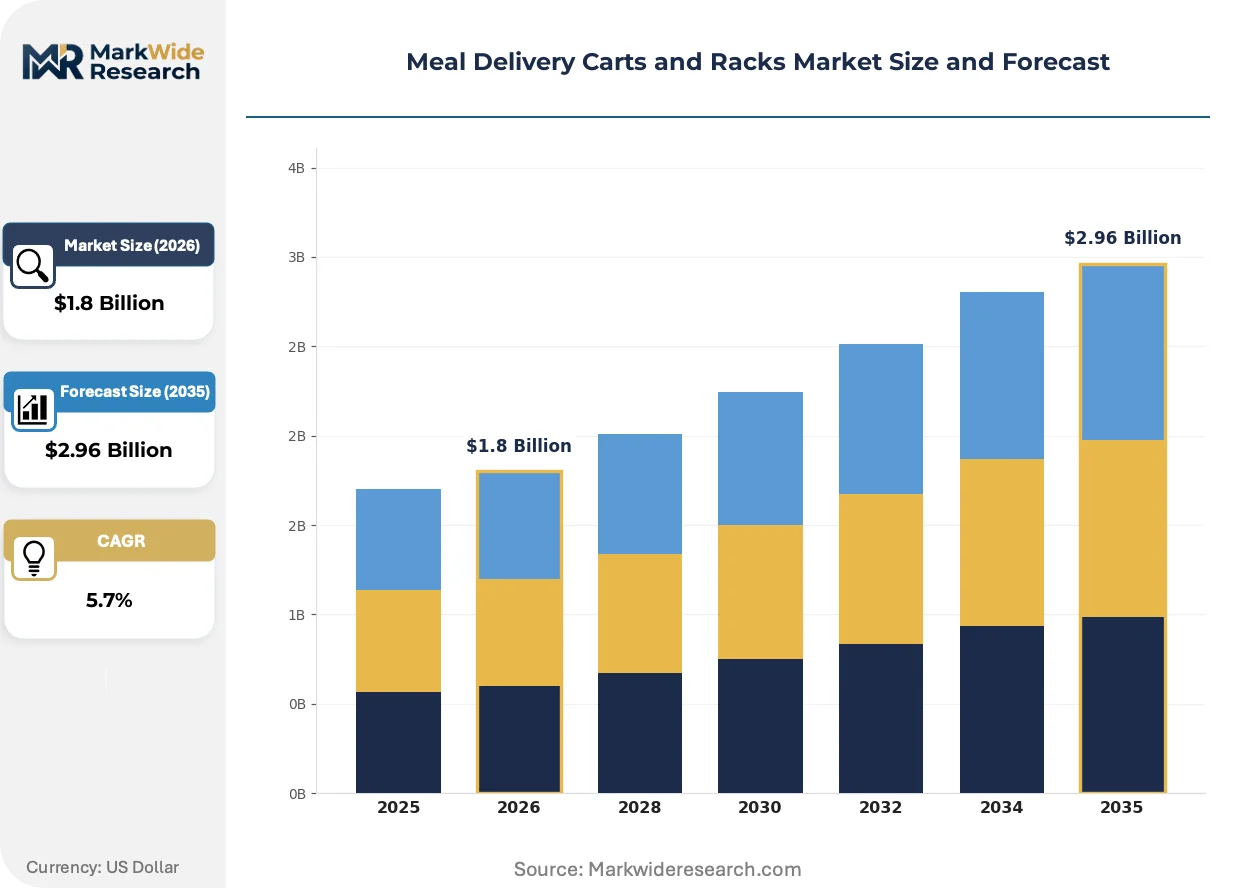
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Delivery Carts, Mobile Racks, Utility Carts, Food Trolleys Material: Stainless Steel, Aluminum, Plastic, Wood End User: Restaurants, Hospitals, Hotels, Schools Design Type: Foldable, Stackable, Multi-Tier, Customizable |
| Companies Covered | Cambro, Carter-Hoffmann, Cadco, Cres Cor, Dinex, IMC Teddy, Lakeside, Lockwood, Aladdin Temp-Rite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Delivery Carts and Racks Market Evolving Landscape
Equipment intelligence and material substitution are converging to redefine thermal performance benchmarks and procurement evaluation criteria across institutional foodservice.
Phase-change material inserts are displacing conventional heated bases in premium cart configurations. Acute care hospitals in the Northeast United States are piloting these systems for extended-route patient feeding. The technology is miniaturizing thermal mass requirements and enabling lighter chassis designs that comply with ergonomic push-force limits.
EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents are forcing polyurethane insulation reformulation. European manufacturers are transitioning to cyclopentane or water-blown foam systems with equivalent R-values. German hospital procurement consortiums are now specifying low-GWP insulation credentials as mandatory bid criteria.
Consolidated buying cooperatives are displacing individual facility purchasing authority. Multi-hospital health systems in the US are centralizing meal delivery equipment selection through shared services organizations. This concentration is most visible in California's integrated delivery networks, where standardization mandates override legacy vendor relationships.
Meal Delivery Carts and Racks Market Segmentation
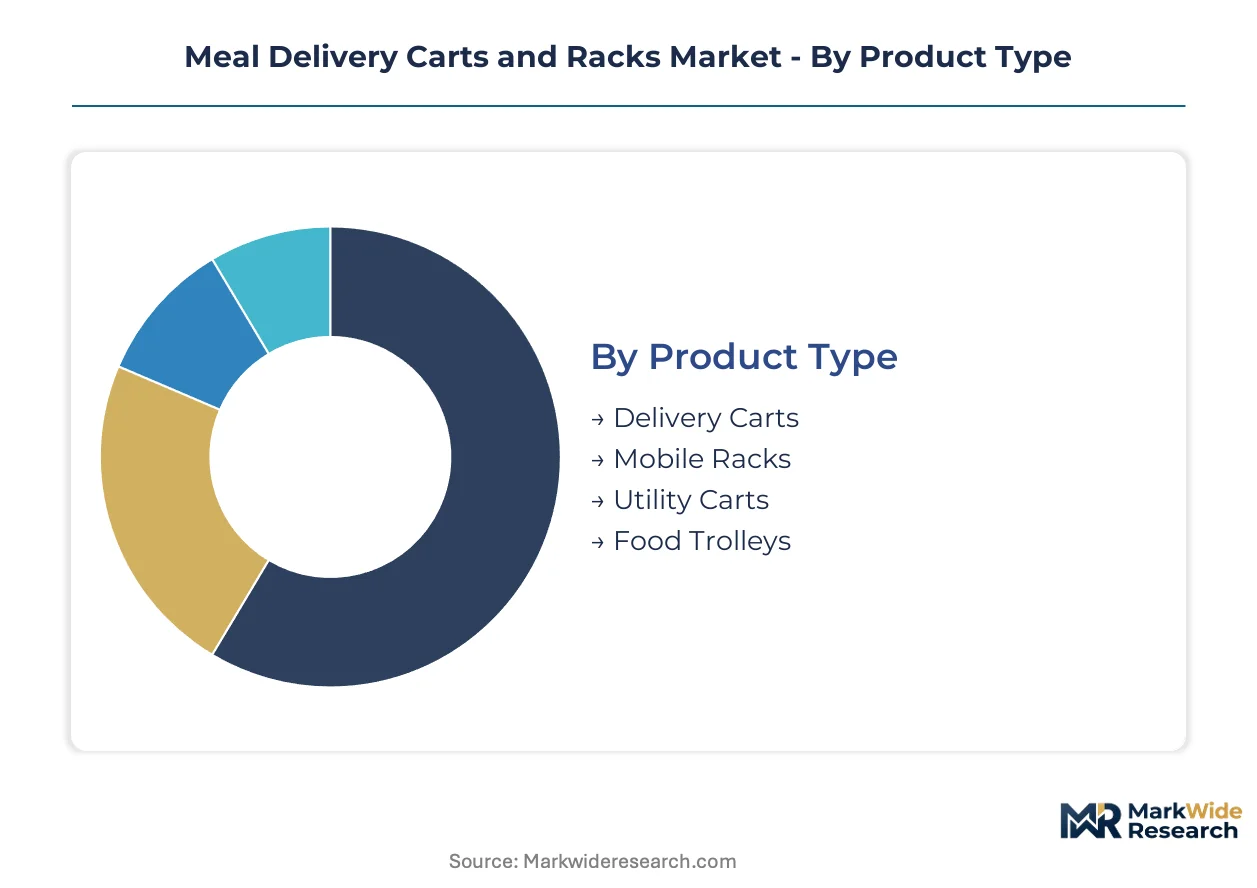
Segmentation in the meal delivery carts and racks market reveals divergent procurement patterns across institutional versus commercial foodservice operators. Equipment specifications vary sharply between acute care facilities requiring NSF-certified thermal retention and hospitality venues prioritizing maneuverability and aesthetic integration.
Product Type:
German hospital consortiums anchor import demand for high-capacity mobile rack systems, while US acute care networks drive domestic insulated cart procurement under FDA Food Code compliance mandates.
- Delivery Carts:Thermal insulation cores rated for 180-minute heat retention define specifications for acute care patient feeding. US hospital systems under FDA Food Code mandates are replacing legacy uninsulated fleets with NSF-certified polyurethane-foam units.
- Mobile Racks:High-density tray configurations engineered for centralized commissary models dominate German Bundesland procurement. Bundesland-level healthcare consolidation is standardizing rack dimensions across integrated provider networks.
- Utility Carts:Lightweight aluminum chassis serve high-frequency shuttle corridors in US hotel and banquet operations.
- Food Trolleys:Compact footprints address space-constrained tray-line retrofits in aging US hospital infrastructure.
Mobile racks command the established base in European institutional procurement. The steepest expansion runs through delivery carts as US acute care facilities execute FDA-mandated replacement cycles.
Material:
Cost tiers stratify sharply between premium NSF-certified grades and commodity alternatives, with stainless steel fabrication absorbing nickel and chromium volatility while aluminum gains ground on ergonomic compliance.
- Stainless Steel:Grade 304 and 316 alloys retain institutional preference for infection control and surface sanitization compliance. Nickel price fluctuations are compressing fabrication margins for NSF-certified equipment manufacturers serving US healthcare networks.
- Aluminum:Welded chassis designs from primary smelter supply chains enable weight reduction for OSHA push-force compliance. Supply concentration in specific geographies creates vulnerability for thermal holding segment producers.
- Plastic:Polymer engineering advances deliver insulated cart cores at lower weight points for commercial foodservice mobility requirements.
- Wood:Aesthetic finishes serve hospitality presentation tiers where thermal performance is secondary to visual integration.
Stainless steel anchors procurement in regulated healthcare environments. Aluminum is climbing fastest as ergonomic mandates constrain cart weights across aging US foodservice workforces.
End User:
Application-specific requirements drive specification divergence, with hospitals demanding thermal audit trails while restaurants prioritize speed of service and reconfiguration flexibility.
- Hospitals:Acute care facilities require temperature logging capabilities and NSF surface certification for patient safety compliance. US FDA Food Code updates on hot and cold holding are triggering equipment replacement cycles.
- Restaurants:High-turnover commercial kitchens specify rapid-cooling inserts and modular tray configurations for menu variety.
- Hotels:Banquet and room service operations balance thermal retention with aesthetic presentation for guest-facing delivery.
- Schools:K-12 district foodservice programs prioritize durability and low maintenance under constrained capital budgets.
Hospitals represent the premium tier by specification intensity. Restaurants are gaining share fastest as commercial kitchen automation drives fleet standardization.
Design Type:
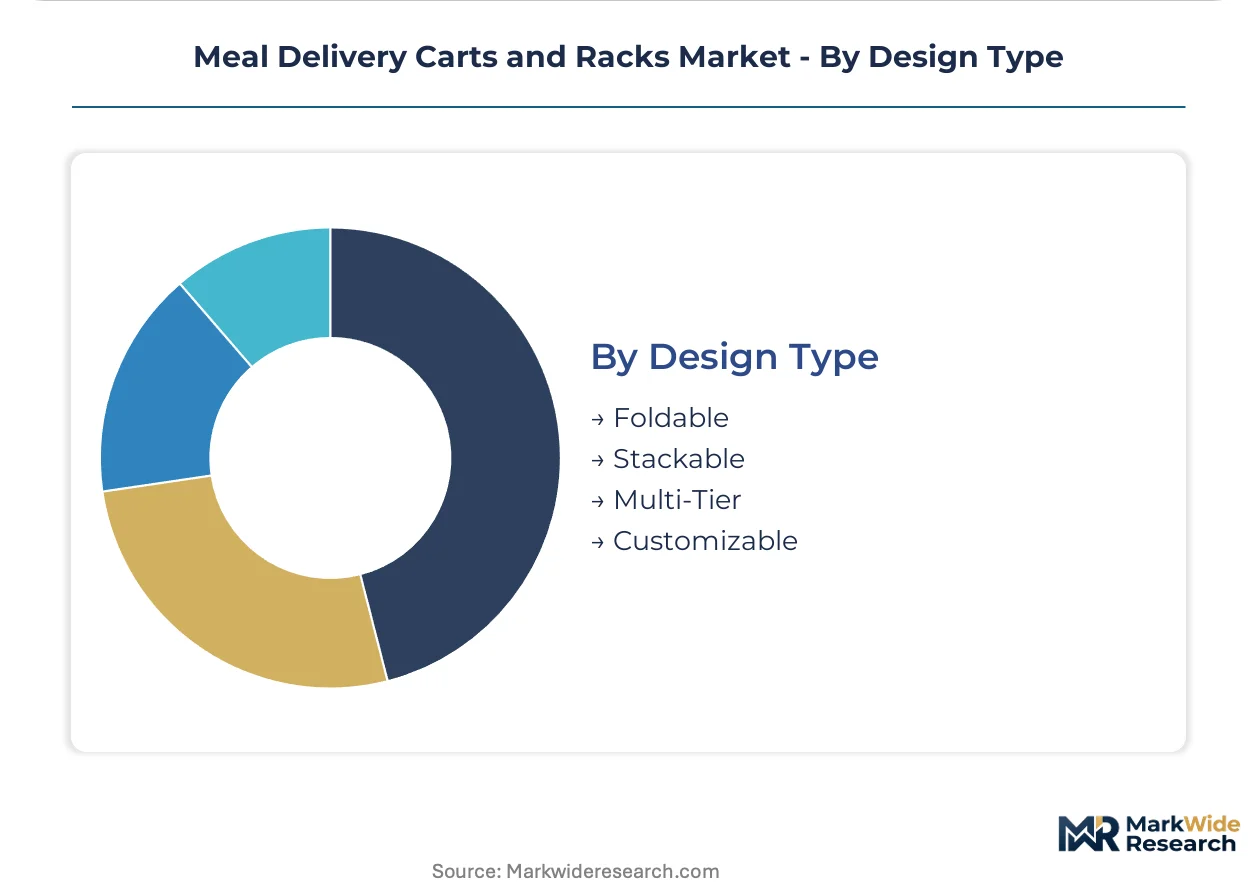
Margin pools widen as facilities demand ward-specific configurations, fragmenting production runs while commanding customization premiums from flexible manufacturing operations.
- Customizable:Ward-specific dimensions for pediatric, bariatric, and immunocompromised units fragment production but capture widening margin pools. German procurement consortiums are mandating modular sub-assemblies for network-wide standardization with local adaptation.
- Multi-Tier:High-density vertical configurations maximize tray capacity for centralized commissary distribution models.
- Foldable:Space-efficient storage addresses back-of-house footprint constraints in urban US hospital renovations.
- Stackable:Nesting designs reduce return-trip vehicle loading for high-frequency shuttle routes.
Multi-tier configurations command volume leadership in consolidated healthcare systems. Customizable designs are expanding most quickly as patient acuity segmentation drives ward-specific equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in meal delivery carts and racks tilt toward manufacturing concentration in Germany and the United States, with Asia-Pacific markets absorbing inbound insulated cart shipments for hospital infrastructure buildouts.
United States
Acute care networks in California and Texas are replacing legacy uninsulated fleets under FDA Food Code temperature mandates. OSHA ergonomic guidelines on push-force limits constrain cart weight specifications across aging hospital foodservice workforces. The Northeast corridor pilots phase-change material inserts for extended-route patient feeding.
Germany
Bundesland-level healthcare consolidation concentrates procurement authority for high-capacity mobile rack systems serving centralized commissary models. EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents force polyurethane insulation reformulation toward cyclopentane or water-blown alternatives. North Rhine-Westphalia anchors domestic fabrication capacity for welded aluminum chassis designs.
India
Greenfield medical cities under the Ayushman Bharat scheme specify modular meal delivery systems without legacy equipment constraints. FSSAI food safety standards for institutional catering drive temperature control equipment adoption in newly licensed hospital kitchens. Maharashtra and Karnataka medical infrastructure clusters import NSF-certified cart configurations for premium private hospital chains.
China
Hospital tier classification reforms accelerate procurement of insulated delivery equipment in tertiary care facilities. GB standards for food contact materials govern surface specifications for domestic manufacturers. Yangtze River Delta industrial zones supply polymer-engineered cart cores for regional healthcare networks.
Japan
Aging hospital infrastructure renovation programs prioritize lightweight aluminum chassis for ergonomic compliance. METI industrial standards for medical foodservice equipment influence domestic manufacturer design specifications. Kansai region hospital groups standardize mobile rack dimensions across integrated delivery networks.
Meal Delivery Carts and Racks Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and thermal retention performance tiers. The vendor base stratifies between NSF-certified institutional fabricators and commercial-grade mobility specialists. Three archetypes dominate: polymer-engineered insulation specialists, welded aluminum thermal holding experts, and diversified foodservice equipment conglomerates. Capacity expansion in polyurethane foam core manufacturing and direct-to-facility distribution network buildouts represent the primary competitive vectors.
Within the polymer-engineered insulation tier, Cambro exemplifies material science specialization for healthcare network supply. Carter-Hoffmann occupies a position among welded aluminum chassis fabricators serving extended-route thermal holding requirements. Cadco represents diversified equipment manufacturers with cross-segment portfolio breadth spanning institutional and commercial foodservice applications.
| Leading Market Players |
|---|
| Cambro |
| Carter-Hoffmann |
| Cadco |
| Cres Cor |
| Dinex |
| IMC Teddy |
| Lakeside |
| Lockwood |
| Aladdin Temp-Rite |
| Others |
Value Network & Pricing Analysis
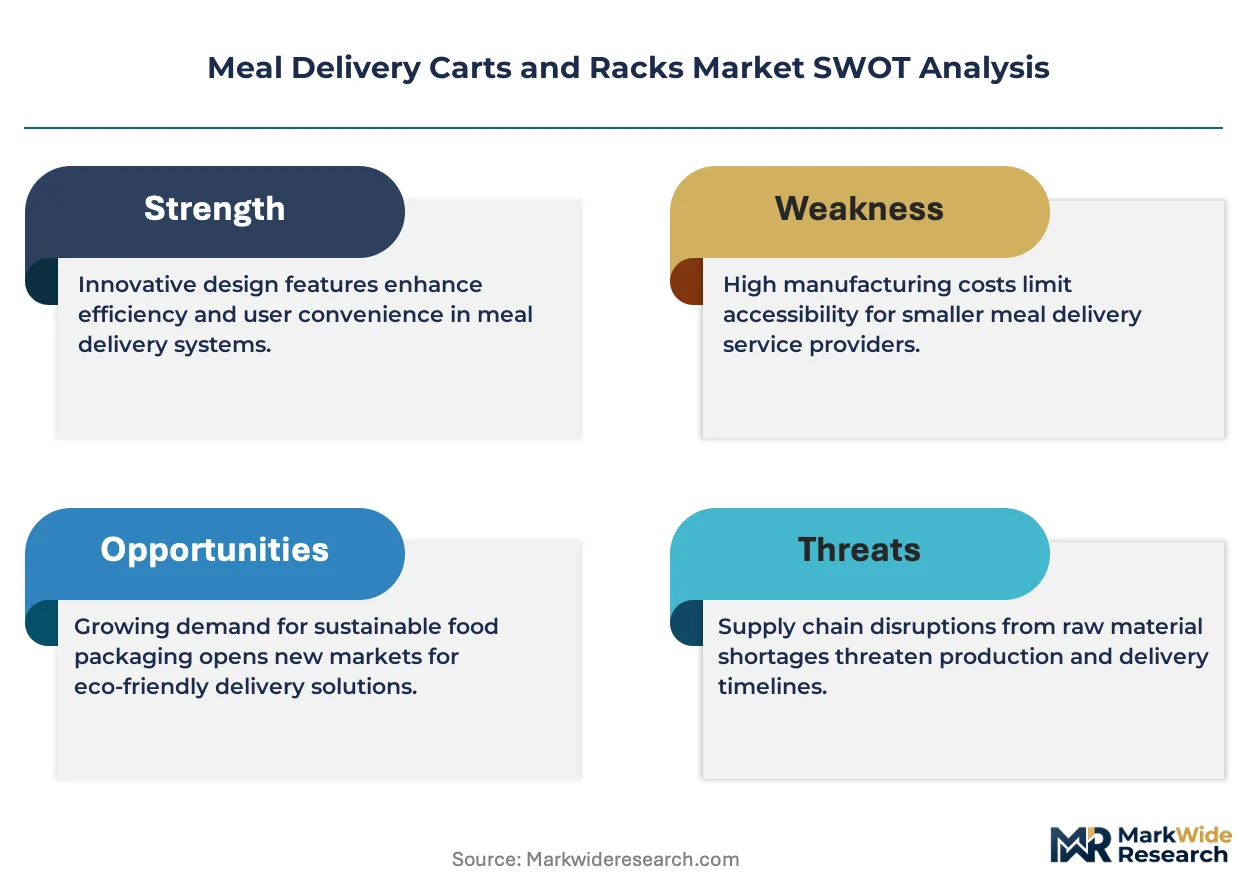
NSF International certification gates both supplier qualification and price differentiation simultaneously, creating tiered access where certified fabricators command sustained premiums while uncertified competitors face exclusion from acute care procurement. Hospital networks in the United States and Germany leverage this regulatory threshold to consolidate vendor lists, compressing margin pools for commodity-grade alternatives while rewarding thermal performance validation with contract security.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with NSF-certified Grade 316 stainless steel units commanding the top tier and polymer-engineered alternatives occupying mid-market positions. Price differentiation hinges on thermal retention certification depth and customization complexity for ward-specific configurations. Cost compression in standard-grade aluminum chassis is intensifying because nickel price volatility erodes fabrication margins. K-12 district foodservice programs exhibit the highest price sensitivity, while integrated German hospital consortiums prioritize performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of polyurethane foam cores and aluminum extrusions characterizes procurement behavior among welded chassis fabricators, buffering against primary smelter concentration in China and Germany. Manufacturing draws from Taiwan for polymer engineering components, the United States for NSF-certified stainless steel fabrication, and North Rhine-Westphalia for aluminum thermal holding systems. Single-source vulnerability in cyclopentane-blown insulation supply chains exposes European producers to EU F-Gas Regulation enforcement delays. Distribution runs through manufacturer-owned service networks and medical equipment distributors serving hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of in-house polymer engineering capability and NSF certification infrastructure constrains competitive entry, privileging incumbent specialists with validated thermal retention platforms over capital-backed challengers seeking rapid scale.
For Market Incumbents: Fortify certification depth by accelerating third-party validation for 180-minute heat retention ratings ahead of FDA Food Code enforcement tightening. Secure captive supply of low-GWP polyurethane foam cores through backward integration into European cyclopentane-blown insulation production, insulating margin structures from regulatory reformulation costs. Channel control through direct-to-facility service networks defends position against distributor disintermediation threats from German procurement consortiums. For New Entrants and Emerging Players: Lead with modular sub-assembly designs targeting India's greenfield medical cities under Ayushman Bharat, where legacy equipment constraints are absent and FSSAI standards create certification parity with established competitors. Phase-change material integration for extended-route thermal holding represents the most penetrable technology wedge, particularly in the Northeast United States corridor piloting lighter chassis configurations. A go-to-market angle anchored in RFID-enabled temperature logging captures digital food safety audit trail demand from integrated delivery networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed polymer engineering specialists holding Cambro-scale healthcare network relationships but lacking welded aluminum chassis diversification. Long-term viability across the analysis window favors platforms spanning both insulation core and structural fabrication capabilities. The signal to watch is Bundesland-level procurement consolidation velocity in Germany, where standardization mandates accelerate vendor list truncation and create acquisition currency for multi-product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Acceleration | Third-party validation unlocks acute care procurement access under FDA Food Code mandates. |
| Low-GWP Insulation Transition | Cyclopentane-blown foam reformulation secures European hospital bid eligibility under EU F-Gas Regulation. |
| Direct-to-Facility Distribution | Manufacturer-owned service networks capture margin from medical equipment distributor bypass. |
| Smart Cart Integration | RFID tracking and temperature logging convergence creates premium upgrade pathways for healthcare networks. |
| Modular Sub-Assembly Design | Standardized components with local adaptation serve German consortium standardization mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with foodservice directors, hospital procurement managers, biomedical engineers, and GPO contracts specialists; and secondary validation against FDA Food Code updates, NSF International certification databases, hospital procurement records, and EU F-Gas Regulation implementation guidance. Bottom-up triangulation across equipment shipment data and top-down reconciliation against healthcare foodservice expenditure patterns anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, material grade, end-user facility category, and design configurability. CAGRs derived from trend extrapolation of replacement cycle timing, regulatory compliance deadlines, and infrastructure buildout schedules. Forecast inputs incorporated polyurethane foam core advancement trajectories and Bundesland-level healthcare consolidation timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or EU insulation reformulation compliance would require recalibration. Forecasts reflect documented assumptions regarding temperature mandate adoption curves and centralized catering model penetration. Revision becomes warranted when nickel price volatility crosses thresholds that compress NSF-certified fabrication margins beyond supplier absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Germany Countertop Ice Makers Market