
 Refrigerated Counter Market | 2026-2036
Refrigerated Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Counter Market Outlook
Remote temperature monitoring and predictive maintenance subscriptions is rebalancing how buyers evaluate total cost of ownership over equipment life. Hillphoenix leverages its controls integration to anchor large-format grocery retrofits across North America. Arneg sustains European market presence through proprietary refrigeration system design. Hoshizaki competes aggressively in compact undercounter configurations for foodservice.
A refrigerated counter is a thermally insulated cabinet with integrated vapor-compression cooling, maintaining temperatures between 0°C and 4°C for perishable display and storage, constructed from galvanized steel frames, polyurethane foam insulation, and forced-air or gravity-coil evaporator systems. Glass door configurations now dominate supermarket refurbishment budgets due to energy savings from reduced air infiltration, while undercounter units capture growing share in back-of-house restaurant environments where floor space commands premium value. Modular installation formats are expanding fastest among convenience store operators seeking flexible layout reconfiguration without structural renovation.
The EPA SNAP program and DOE commercial refrigeration standards govern refrigerant eligibility and minimum efficiency thresholds in the United States, while the EU F-Gas Regulation and Ecodesign directives enforce comparable constraints across European member states, compressing product development cycles for manufacturers serving both jurisdictions. Buyers must now weigh total lifecycle compliance costs against upfront capital expenditure when specifying equipment for multi-site rollouts. Stakeholders should monitor refrigerant transition timelines and regional certification reciprocity to avoid stranded asset risk in cross-border fleet deployments.
Market Dynamics
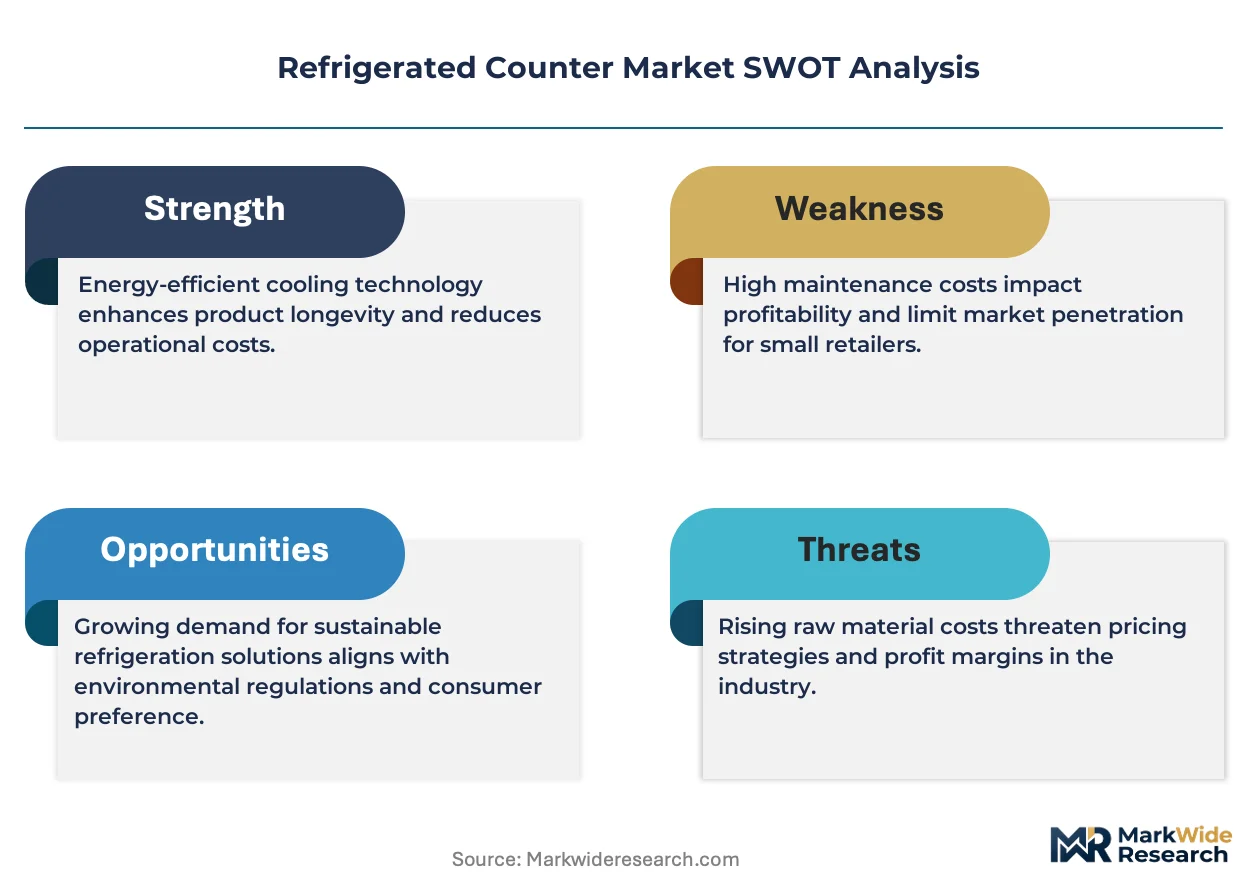
The refrigerated counter market is restructuring around refrigerant phase-down mandates and lifecycle cost recalibration, as buyers weigh compliance timelines against equipment replacement cycles and energy efficiency thresholds.
Growth Catalysts
- EU F-Gas Regulation:The progressive hydrofluorocarbon quota system compels food retailers across Germany, France, and Italy to accelerate equipment modernization, opening replacement demand for low-global-warming-potential refrigeration systems.
- Quick-service restaurant expansion:Chained foodservice operators are extending cold-chain footprints into dense urban clusters, requiring compact undercounter configurations that maximize floor productivity.
- Predictive maintenance platforms:Remote temperature monitoring subscriptions are rebalancing total cost of ownership calculations, favoring suppliers with integrated controls architecture.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings compress fabrication margins and destabilize quoted equipment pricing for multi-site rollout contracts.
- Compressor supply concentration:Sourcing dependency on specialized refrigeration component manufacturers in select East Asian production centers creates lead-time vulnerability.
- Natural refrigerant safety codes:Ammonia and hydrocarbon system standards impose facility retrofit requirements that extend payback periods for smaller independent grocers.
Strategic Opportunities
- Convenience store modular formats:Flexible layout reconfiguration capabilities without structural renovation are capturing share among petroleum-retail hybrid operators.
- DOE commercial refrigeration standards:The Department of Energy's efficiency thresholds create specification tailwinds for manufacturers with advanced insulation and compressor technology portfolios.
- Glass door retrofit convergence:Energy savings from reduced air infiltration are displacing open-air display configurations in supermarket refurbishment budgets.
Industry Challenges
- Refrigerant transition skill gaps:Technician certification for flammable and toxic natural refrigerant handling lags equipment deployment timelines.
- Cross-border certification reciprocity:Divergent EPA SNAP and EU Ecodesign compliance pathways strand assets in multinational fleet standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Counter Market |
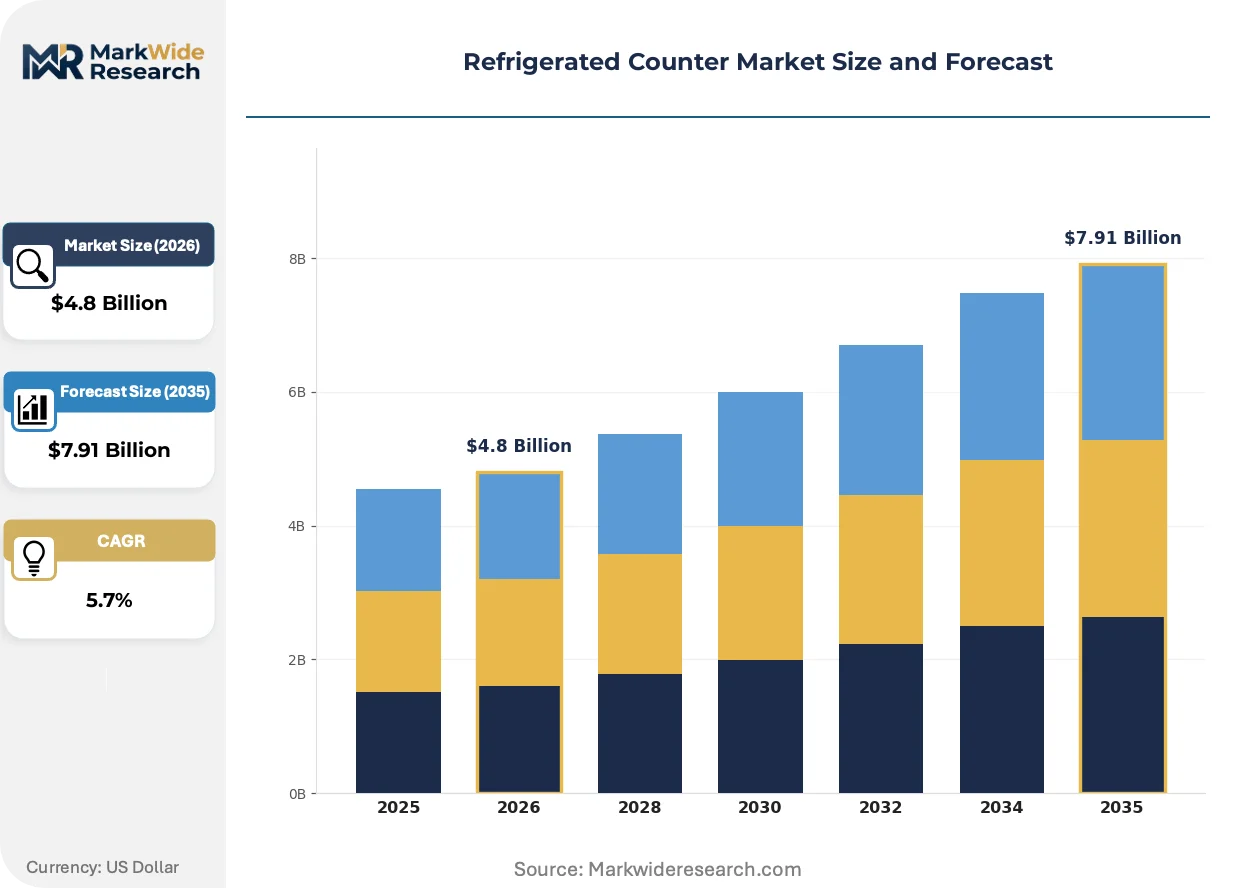
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Display, Glass Door, Undercounter, Food Prep End User: Restaurants, Supermarkets, Convenience Stores, Cafés Installation: Built-In, Freestanding, Modular, Portable Size: Small, Medium, Large, Extra Large |
| Companies Covered | Hillphoenix, Arneg, Hussmann Corporation, Hoshizaki, AHT Cooling Systems, Carrier, Epta Corporate, Haier, True Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Counter Market Strategic Shifts
Equipment specification is pivoting from upfront capital minimization toward lifecycle compliance and energy performance, reshaping supplier relationships and procurement evaluation frameworks across food retail and foodservice verticals.
Variable-speed compressor technology is absorbing demand from fixed-speed legacy systems by matching cooling output to real-time thermal load. Large-format grocery retrofits in North America are specifying these configurations to qualify for utility rebate programs. The technology is absorbing margin pressure from refrigerant transition costs while delivering measurable kilowatt-hour reductions.
REACH substance restrictions and RoHS hazardous material limits are tightening component sourcing requirements for manufacturers serving European member states. Supply chain documentation burdens are increasing, with ECHA compliance databases becoming gatekeepers for market access. German food retail chains are responding by consolidating supplier qualification around pre-certified component ecosystems.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles into subscription-based monitoring and on-demand repair contracts. Foodservice operators with distributed site portfolios are adopting this model to convert fixed maintenance overhead into variable operating expenditure. This pattern is most visible in the United States, where multi-brand equipment fleets complicate single-source service agreements.
Refrigerated Counter Market Segmentation
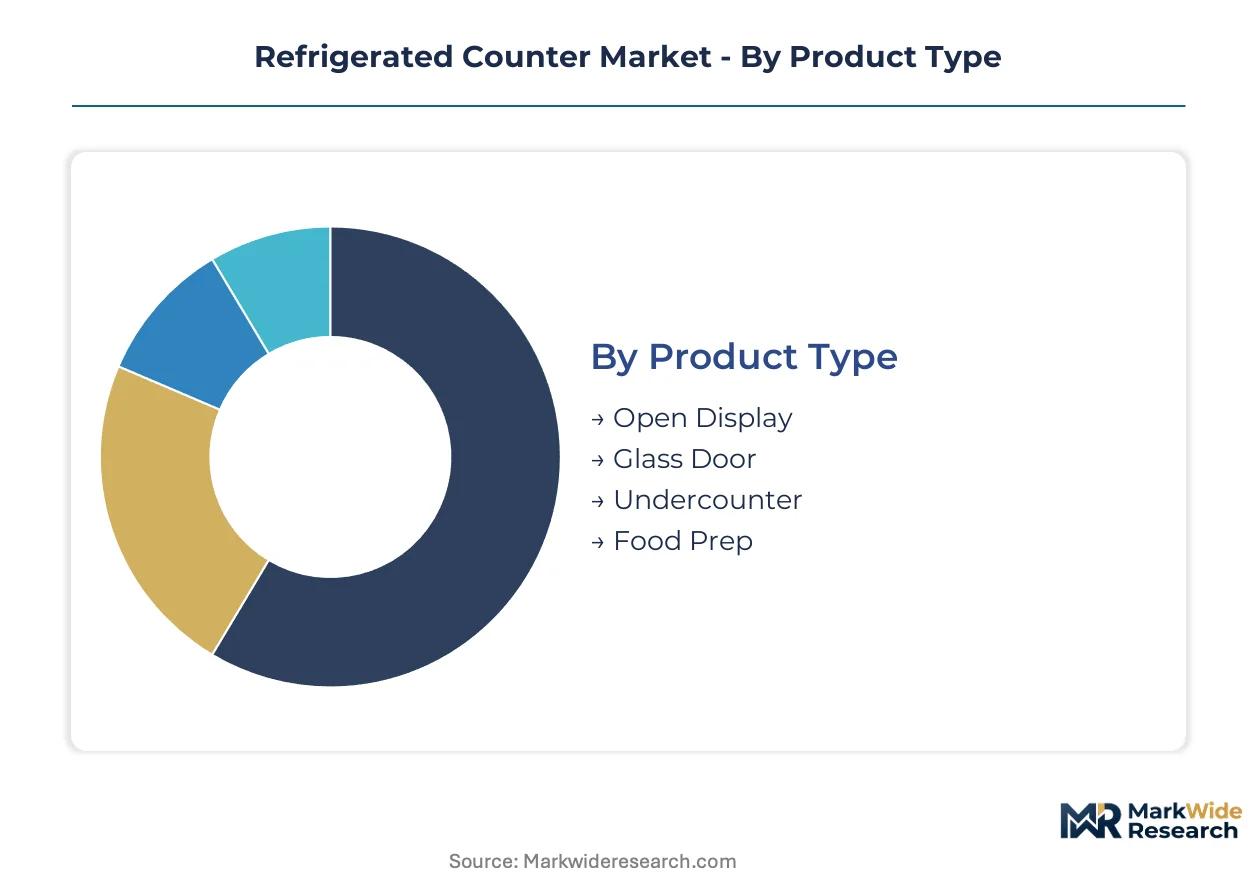
Equipment specification in the refrigerated counter market fragments across display format, end-use environment, and spatial constraints. Procurement decisions hinge on energy compliance trajectories, floor productivity metrics, and refrigerant transition timelines rather than upfront capital alone.
Product Type:
Volume concentration sits with open-air configurations, while premium positioning clusters around glass door and specialized food prep units.
- Open Display:Gravity-coil evaporator systems maintain 0°C to 4°C across unenclosed product zones. German supermarket chains are phasing these out under Ecodesign pressure, yet they retain share in high-turnover fresh produce aisles where accessibility drives purchase velocity.
- Glass Door:Forced-air cooling with triple-pane low-emissivity glazing reduces thermal infiltration. Convenience store operators across France and Italy specify these for extended-hour unmanned formats where energy costs dominate lifecycle economics.
- Undercounter:Compact vapor-compression units fit beneath prep surfaces in space-constrained kitchens.
- Food Prep:Integrated cutting board surfaces with dedicated cooling zones for ingredient staging.
Today's leader: Open Display. Tomorrow's challenger: Glass Door.
End User:
Application requirements diverge sharply between front-of-house display priorities and back-of-house throughput demands.
- Restaurants:Undercounter and food prep configurations dominate quick-service rollouts in dense urban clusters. Chained operators prioritize compact footprints and standardized maintenance protocols across multi-site deployments.
- Supermarkets:Large-format glass door retrofits absorb capital budgets as EU F-Gas Regulation accelerates replacement cycles. German retailers lead refurbishment intensity.
- Convenience Stores:Modular installation formats enable layout reconfiguration without structural renovation.
- Cafés:Small-footprint undercounter units balance pastry display with beverage service workflow.
Supermarkets anchor current procurement volume. Convenience stores are climbing the fastest as petroleum-retail hybrid formats expand cold-chain footprints.
Installation:
Flexibility premiums separate modular and portable formats from fixed infrastructure commitments.
- Built-In:Permanent structural integration with custom facade matching. High-end supermarket deli counters in Italy favor this approach for aesthetic continuity.
- Freestanding:Self-contained refrigeration with caster mobility for seasonal layout adjustments.
- Modular:Standardized connection interfaces allow component swapping without technician dispatch. US convenience store operators adopt this to convert fixed maintenance overhead into variable expenditure.
- Portable:Plug-and-deploy units for temporary events and catering operations.
Freestanding units hold installed base dominance. Modular formats are expanding most quickly among operators with distributed site portfolios.
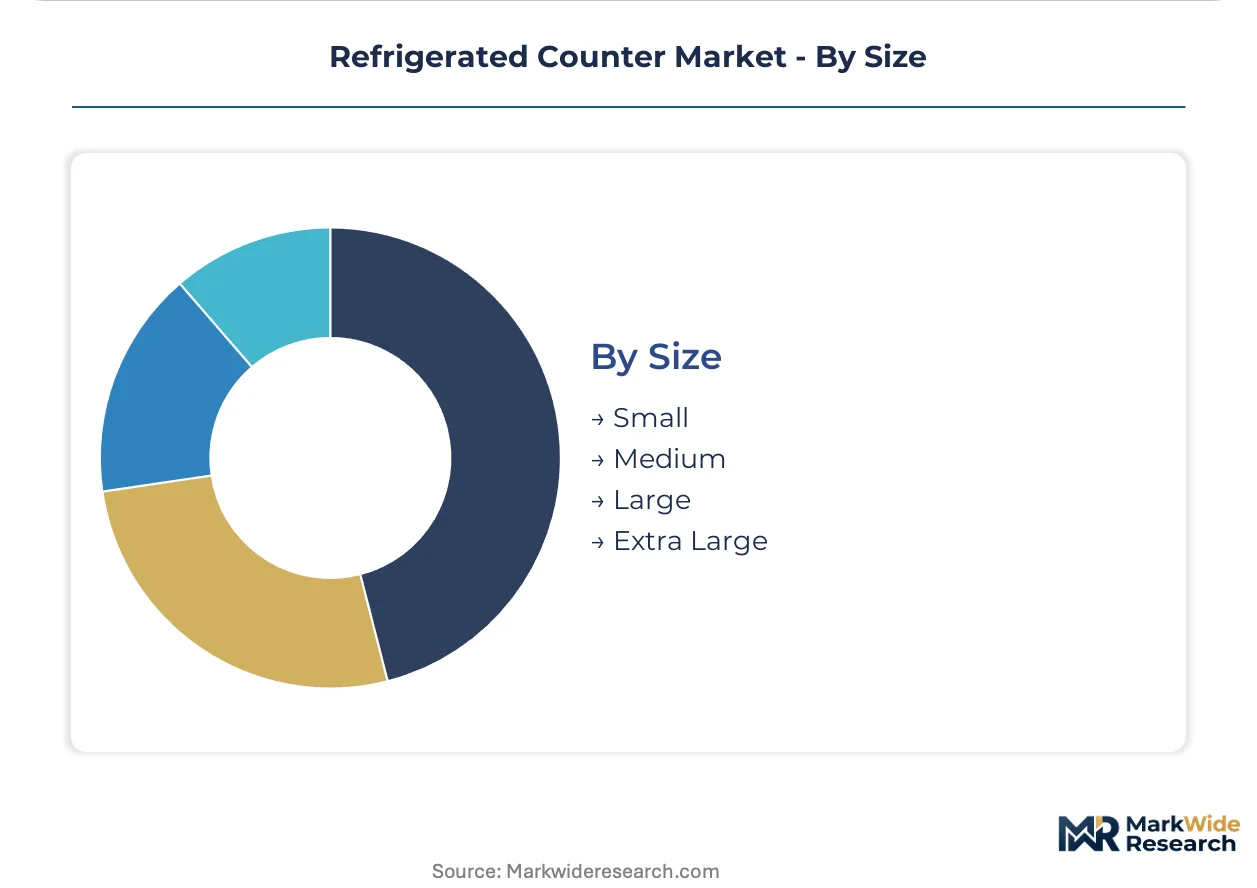
Size:
Space economics and throughput requirements stratify procurement across dimensional tiers.
- Small:Countertop and undercounter units under one meter width. Cafés and specialty food retailers in urban France specify these for premium positioning in constrained floor plans.
- Medium:One to two meter widths balancing display capacity with aisle clearance.
- Large:Two to three meter supermarket aisle configurations with multiple temperature zones.
- Extra Large:Custom deli and seafood departments exceeding three meters with integrated service counters.
Medium size brackets command current shipment volume. Small configurations are gaining share fastest as urban real estate premiums intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek cost-of-compliance advantages across divergent EPA SNAP and EU F-Gas timelines. Equipment specification now varies sharply by jurisdiction, with fleet standardization becoming economically untenable for multinational operators.
Germany
Food retail modernization and energy-efficiency mandates accelerate replacement cycles across supermarket chains. The EU F-Gas Regulation compresses hydrofluorocarbon quota availability, forcing rapid low-GWP system adoption. Berlin and Hamburg anchor refurbishment intensity, with Metro AG and REWE Group consolidating procurement around pre-certified component ecosystems.
United States
Quick-service restaurant chains extend cold-chain footprints into dense urban clusters, requiring compact undercounter configurations. DOE commercial refrigeration standards and EPA SNAP program govern refrigerant eligibility and minimum efficiency thresholds. Dallas-Fort Worth and Atlanta metropolitan areas concentrate multi-site rollout activity among petroleum-retail hybrid operators.
France
Convenience store operators specify glass door configurations for extended-hour unmanned formats where energy costs dominate lifecycle economics. Ecodesign directives enforce insulation and compressor performance minimums. Lyon and Marseille clusters drive modular installation demand among petroleum-retail hybrid networks seeking layout flexibility.
Italy
High-end supermarket deli counters favor built-in permanent structural integration for aesthetic continuity. REACH substance restrictions and RoHS hazardous material limits tighten component sourcing requirements. Milan and Rome retail corridors concentrate premium positioning activity among specialty food retailers in constrained urban floor plans.
Japan
Compact undercounter units capture share in space-constrained convenience store and café environments. METI efficiency standards and JIS certification requirements shape equipment specification. Tokyo and Osaka metropolitan areas anchor demand for small-footprint configurations balancing display capacity with premium real estate economics.
Refrigerated Counter Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated controls providers commanding premium positioning in large-format retrofits while fabrication-focused OEMs compete on unit economics for high-volume foodservice deployments. Market structure tilts toward consolidation at the premium tier and fragmentation in commoditized undercounter segments. Three archetypes dominate: full-system integrators with proprietary refrigeration design, controls-anchored retrofit specialists, and scale-driven compact equipment fabricators. Competitive moves center on M&A for refrigerant technology access and strategic partnerships for predictive maintenance platform integration.
Within the full-system integrator tier, Hillphoenix and Arneg occupy anchor positions exemplifying divergent geographic strengths—Hillphoenix representing North American large-format grocery retrofit concentration, Arneg embodying European market presence through proprietary system design. Hoshizaki sits within the compact equipment specialist archetype, its positioning reflecting aggressive competition in undercounter configurations for space-constrained foodservice environments. These three companies illustrate how competitive advantage fragments across display format specialization rather than consolidating around unified platform dominance.
| Leading Market Players |
|---|
| Hillphoenix |
| Arneg |
| Hussmann Corporation |
| Hoshizaki |
| AHT Cooling Systems |
| Carrier |
| Epta Corporate |
| Haier |
| True Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Captive compressor production in East Asian manufacturing clusters anchors both supply security and pricing leverage for tier-one OEMs serving multi-site rollout contracts. This integration pattern insulates large-format grocery retrofit specialists from copper and aluminum price volatility while compressing fabrication margins for smaller undercounter fabricators dependent on merchant component markets.
Pricing Analysis
Distributor margin layers compress final equipment pricing by 12-18 points for independent grocers versus direct-to-OEM volume discounts captured by chained quick-service restaurant operators. Three-tier pricing structure across premium, standard, and economy levels separates glass door configurations with predictive maintenance subscriptions from basic open-display units. Cost compression in compact undercounter segments is intensifying because Hoshizaki and True Manufacturing compete aggressively for foodservice floor space. Chained operators with standardized fleet specifications exhibit lowest price sensitivity; independent convenience store operators show highest sensitivity due to single-site procurement scale.
Supply Chain Analysis
Ocean freight cost spikes from East Asian component hubs to European assembly plants have destabilized quoted equipment pricing for German supermarket refurbishment contracts. Compressor manufacturing concentrates in China, Japan, and South Korea; polyurethane foam insulation draws from German and Belgian chemical suppliers. Single-source vulnerability sits with specialized refrigeration component manufacturers in select East Asian production centers. Distribution runs through authorized service dealer networks for large-format retrofits and direct OEM fulfillment for compact foodservice deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refrigerated counter market functions as a regulatory compounder where EU F-Gas Regulation hydrofluorocarbon quota phase-downs force equipment replacement cycles regardless of underlying demand conditions.
For Market Incumbents: Cement proprietary controls architecture as the anchor for predictive maintenance subscription revenue across North American large-format grocery retrofits. Deepen backward integration into low-GWP refrigerant system design to offset margin compression from REACH substance documentation burdens. Defend against emerging modular-format specialists by locking convenience store operators into multi-year remote monitoring contracts. For New Entrants and Emerging Players: Launch via petroleum-retail hybrid channel partnerships targeting French and Italian convenience store operators seeking flexible layout reconfiguration without structural renovation. White-space concentration sits with compact undercounter configurations for urban quick-service restaurant expansion in Dallas-Fort Worth and Atlanta metropolitan clusters. Prioritize glass door retrofit convergence in German supermarket chains accelerating Ecodesign-driven refurbishment cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where refrigerant transition skill gaps strand independent service networks unable to certify technicians for flammable natural refrigerant handling. Long-term viability favors full-system integrators with captive compressor sourcing and pre-certified component ecosystems. Target acquisition archetype: regional controls-anchored retrofit specialists with installed base concentration in EU F-Gas compliance jurisdictions. Signal to watch: cross-border certification reciprocity agreements between EPA SNAP and EU Ecodesign frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Remote temperature monitoring subscriptions convert fixed maintenance overhead into variable operating expenditure for distributed foodservice portfolios. |
| Low-GWP Refrigerant System Development | Proprietary hydrocarbon and CO2 refrigeration designs secure EU F-Gas Regulation compliance advantage in German supermarket refurbishment cycles. |
| Modular Installation Format Expansion | Standardized connection interfaces capture convenience store operator demand for layout flexibility without structural renovation requirements. |
| Controls-Anchored Retrofit Specialization | Integrated building management system compatibility commands premium positioning in Hillphoenix-dominated North American large-format grocery retrofits. |
| East Asian Component Hub Diversification | Dual-sourcing compressor supply from China and Japan mitigates lead-time vulnerability for multi-site rollout contract fulfillment. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with equipment manufacturers, food retail procurement directors, foodservice chain maintenance heads, and refrigeration contractor technicians alongside secondary validation through SEC 10-K filings, EPA SNAP program registrations, EU ECHA compliance databases, and utility rebate program disclosures. Bottom-up shipment data triangulated against top-down energy efficiency standard adoption curves anchored the market sizing framework.
Historical reference periods spanning equipment replacement cycle data and refrigerant transition compliance timelines anchored the projection horizon across the analysis window. Segmentation modeling incorporated product type, end-use environment, installation flexibility, and dimensional tier alongside refrigerant technology trajectory and regional regulatory cluster. CAGRs derived from slope-intercept analysis of replacement demand curves and efficiency mandate acceleration patterns, with variable-speed compressor adoption rates and glass door retrofit penetration serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility spikes and compressor supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Digital Menu Boards Market