
 Commercial Catering Equipment Market | 2026-2036
Commercial Catering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Catering Equipment Market Outlook
Cloud kitchen operators and ghost kitchen networks are unwinding the traditional dominance of hotel and institutional buyers in commercial catering equipment procurement. Electrolux Professional leverages its European manufacturing base to sustain premium positioning in combi-oven systems. The Middleby Corporation anchors its portfolio through specialized conveyor and automated cooking platforms. RATIONAL competes on thermal engineering intensity, while Ali Group extends its reach through diversified brand holdings across price tiers.
Commercial catering equipment encompasses electrically or gas-powered appliances engineered for high-throughput food preparation, with operating temperatures ranging from sub-zero refrigeration at −18°C to open-flame grilling exceeding 300°C, designed for sustained daily use in licensed foodservice operations. Ovens and refrigerators command the largest installed base due to universal kitchen requirements, while induction-powered equipment captures accelerated replacement cycles as operators confront volatile gas pricing and stricter ventilation mandates. Small-to-medium capacity units dominate unit shipments, though large-scale configurations concentrate margin pools in chain rollout contracts and centralized commissary projects.
The U.S. Department of Energy and the EPA's ENERGY STAR program shape North American procurement through mandatory efficiency reporting, while the EU Ecodesign Directive and F-Gas Regulation restrict refrigerant choices and insulation performance thresholds across Europe. China's GB standards and SAMR certification requirements govern import access and domestic manufacturing compliance. Stakeholders must monitor regulatory divergence between energy-efficiency testing protocols, as misaligned standards threaten to fragment supplier certification costs and limit cross-regional product platform strategies.
Market Dynamics
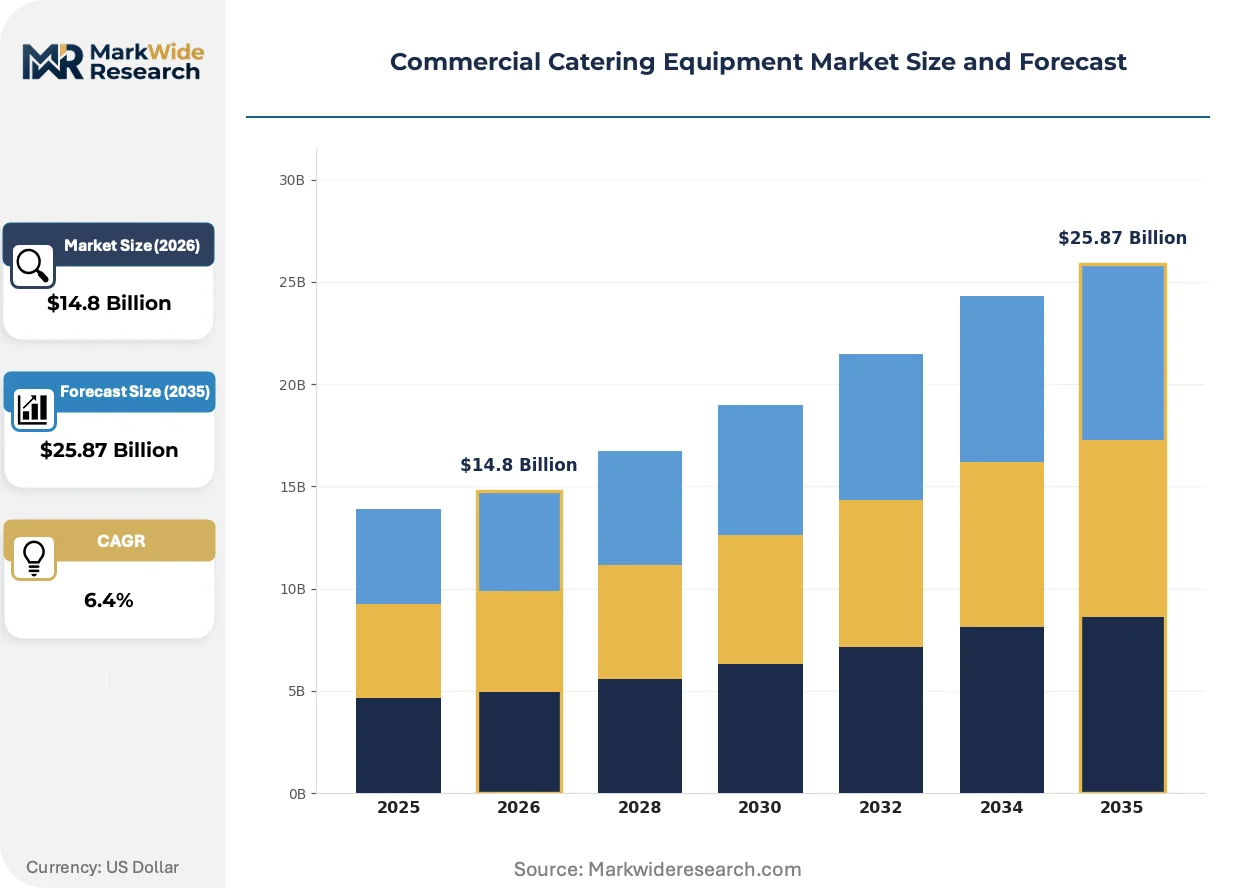
Energy-efficiency mandates from the U.S. Department of Energy and the EU Ecodesign Directive are compressing equipment replacement cycles while simultaneously fragmenting certification requirements across export markets. Kitchen operators now face dual pressure to modernize and comply with divergent testing protocols.
Growth Catalysts
- Cloud kitchen proliferation:Ghost kitchen networks in urban China and Southeast Asia require compact, high-throughput cooking systems designed for delivery-optimized operations.
- F-Gas Regulation phase-down:European restrictions on hydrofluorocarbon refrigerants accelerate retrofit demand for compliant cold-storage equipment across hotel and restaurant chains.
- Induction technology maturation:Precise thermal control and reduced ventilation requirements drive replacement of gas-fired ranges in high-rent metropolitan foodservice districts.
Market Restraints
- Stainless steel price volatility:Input cost swings for 304-grade and 316-grade alloys compress fabrication margins and destabilize contract pricing for custom kitchen fabrications.
- Regional certification fragmentation:Misaligned efficiency testing between DOE protocols and China's GB standards force redundant engineering cycles and limit platform standardization.
- Skilled technician scarcity:Specialized service capacity for programmable combi-oven systems concentrates in Western Europe and select North American metropolitan corridors.
Strategic Opportunities
- India urban foodservice expansion:Tier-2 and Tier-3 city commercial real estate development outpaces equipped kitchen supply, creating first-mover positioning for Western-format equipment.
- Refrigerant technology convergence:CO2 transcritical and hydrocarbon systems align with both EU F-Gas requirements and emerging Middle Eastern efficiency codes.
- Equipment-as-a-service models:Subscription-based maintenance and upgrade programs penetrate chain restaurant procurement, displacing traditional capital expenditure cycles.
Industry Challenges
- Controls software integration:Legacy kitchen management platforms lack API compatibility with IoT-enabled cooking equipment, forcing expensive middleware development.
- Cross-border compliance timelines:SAMR certification in China and UL listing in the United States operate on non-harmonized review schedules that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Catering Equipment Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Ovens, Grills, Fryers, Refrigerators End User: Restaurants, Hotels, Cafes, Catering Services Power Source: Electric, Gas, Induction, Propane Capacity: Small Scale, Medium Scale, Large Scale, Bulk |
| Companies Covered | Electrolux Professional, Alto-Shaam, The Middleby Corporation, Fagor Industrial, Welbilt Inc., RATIONAL, Hobart, MKN Maschinenfabrik Kurt Neubauer, Ali Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Catering Equipment Market Strategic Shifts
Connected kitchen ecosystems and thermal engineering advances are redefining how foodservice operators specify, deploy, and maintain cooking and refrigeration assets. Equipment intelligence now extends beyond standalone automation into networked operational optimization.
Combi-oven intelligence is decomposing the traditional separation between convection and steam cooking modalities. Full-service restaurant chains in Germany and the United Kingdom deploy these systems to consolidate multiple appliance categories into single-footprint units. The technology is decomplicating kitchen layout planning while reducing ventilation infrastructure requirements.
The EU F-Gas Regulation and the U.S. EPA's SNAP program restrict refrigerant options for commercial cold storage. Equipment manufacturers must redesign compressor architectures and insulation systems to maintain performance with lower-global-warming-potential alternatives. European hotel procurement teams now prioritize units qualified for propane or CO2 charge sizes.
Consolidated procurement through centralized commissary operators displaces distributed purchasing by individual franchisees. Large-format cooking and blast-chilling configurations dominate new contract specifications in the United States and China. Cloud kitchen networks in Singapore and Dubai accelerate this concentration by sourcing equipment through single procurement entities serving multiple virtual brands.
Commercial Catering Equipment Market Segmentation
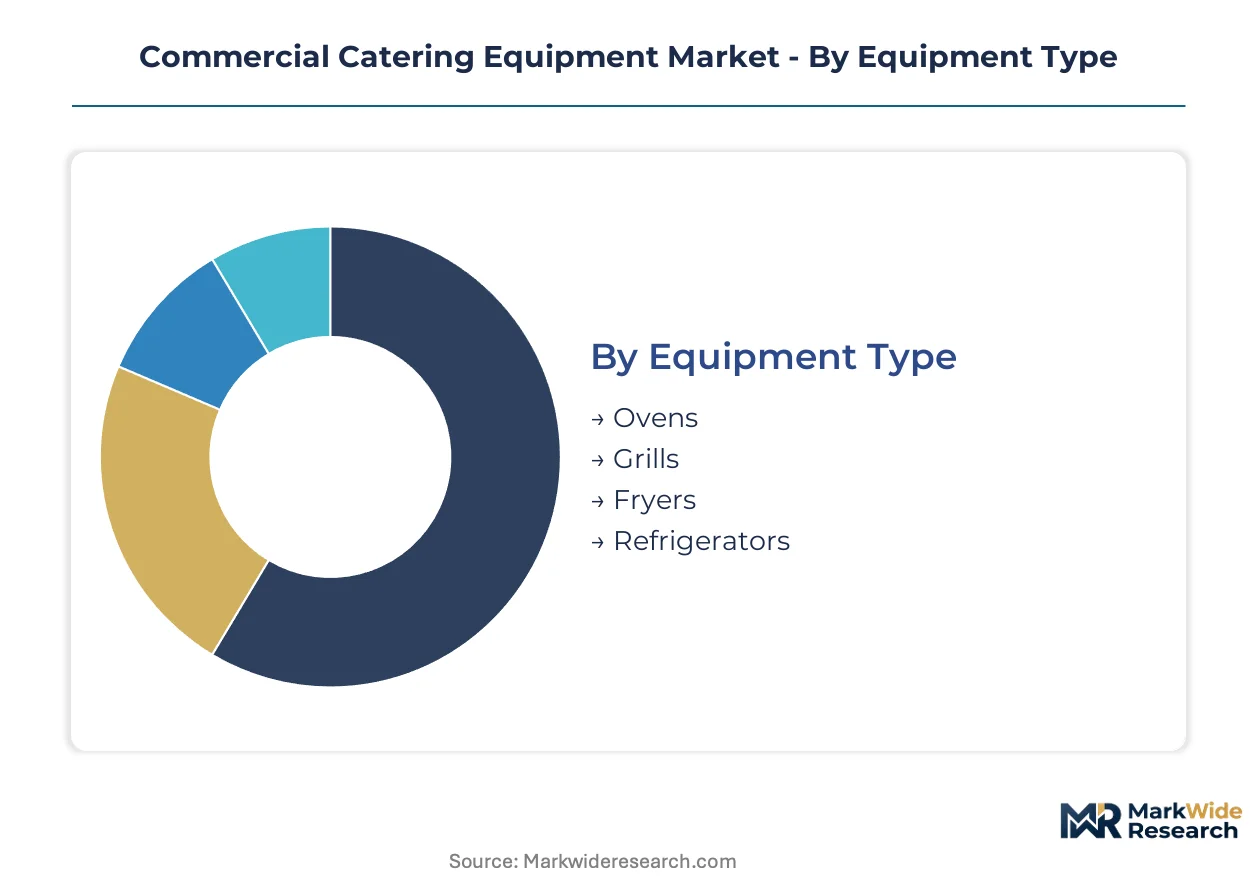
Commercial catering equipment procurement patterns diverge sharply across operational contexts, with power source and capacity specifications determining compliance pathways and total cost of ownership calculations for foodservice operators.
Equipment Type:
Refrigeration units face the most acute substitution pressure as F-Gas Regulation phase-downs force refrigerant chemistry overhauls, while cooking equipment segments compete on energy-efficiency certification alignment.
- Ovens:Combi-oven systems integrate convection and steam modalities within single-footprint configurations, reducing ventilation infrastructure demands. Full-service restaurant chains in Germany and the United Kingdom consolidate procurement around these multi-function units to compress kitchen layout complexity and lower capital deployment.
- Refrigerators:Cold-storage equipment spans reach-in cabinets, walk-in enclosures, and blast-chilling systems engineered for HACCP compliance. European hotel procurement teams now specify propane or CO2 charge sizes to satisfy Ecodesign Directive thresholds, accelerating replacement cycles across established properties.
- Grills:Open-flame and radiant heat systems serve high-throughput protein preparation in steakhouse and fast-casual formats.
- Fryers:Vat-based cooking equipment for breaded and battered products concentrates in quick-service and casual dining deployments.
Ovens retain volume leadership; refrigerators hold the steepest expansion curve as regulatory retrofit mandates compress replacement timelines.
End User:
Cost-tier differentiation separates capital-rich institutional buyers from fragmented independent operators, with procurement centralization concentrating in chain-affiliated categories.
- Restaurants:Full-service and limited-service operators drive standardized equipment specifications through franchise procurement cooperatives. Cloud kitchen networks in Singapore and Dubai source through single entities serving multiple virtual brands, consolidating purchasing power previously dispersed across individual locations.
- Hotels:International brand standards mandate kitchen modernization programs that synchronize equipment refresh cycles across property portfolios. Urban foodservice expansion in China accelerates procurement of Western-format commercial kitchens as international hotel chains enter secondary markets.
- Cafes:Beverage-forward operations with limited cooking footprints prioritize compact refrigeration and espresso equipment configurations.
- Catering Services:Mobile and event-based foodservice requires portable equipment with rapid deployment and breakdown capabilities.
Restaurants dominate unit shipment volumes; hotels command the highest average transaction values through centralized commissary specifications.
Power Source:
Application-specific thermal requirements and ventilation infrastructure availability determine fuel selection, with metropolitan density constraints accelerating technology transitions.
- Electric:Grid-connected equipment dominates installations where gas infrastructure is unavailable or ventilation costs are prohibitive. Precise temperature control capabilities support pastry and confectionery operations requiring thermal stability.
- Induction:Electromagnetic heating technology eliminates open-flame ventilation requirements and reduces ambient kitchen temperatures. High-rent metropolitan foodservice districts in the United States and United Kingdom accelerate replacement of gas-fired ranges as operators confront volatile energy pricing and stricter building codes.
- Gas:Natural gas connections persist in suburban and exurban locations with established utility infrastructure and lower ventilation compliance costs.
- Propane:Bottled fuel systems serve mobile catering operations and locations lacking permanent utility connections.
Electric systems retain installed base dominance; induction gains share fastest in urban premium segments constrained by ventilation mandates.
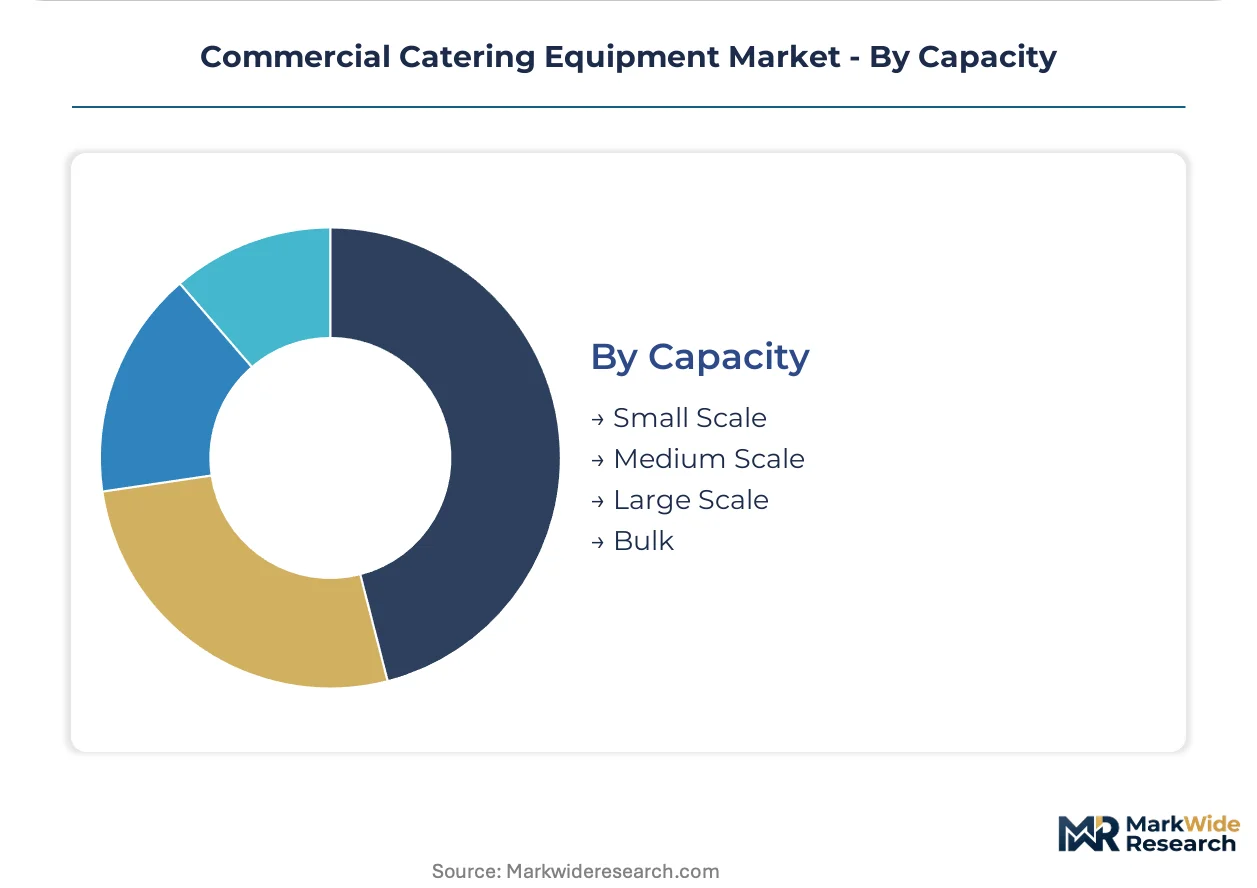
Capacity:
Customer-type segmentation separates high-volume centralized production from distributed point-of-service preparation, with margin concentration in large-format configurations.
- Large Scale:Configurations exceeding 500-liter refrigeration or 20-kW cooking output serve centralized commissaries and flagship hotel properties. Chain rollout contracts and centralized commissary projects concentrate margin pools in this segment, with procurement teams negotiating multi-year supply agreements.
- Medium Scale:Equipment serving 100-300 covers per service period matches independent restaurant and regional hotel requirements. Tier-2 and Tier-3 city commercial real estate development in India outpaces equipped kitchen supply, creating positioning opportunities for Western-format equipment at this capacity tier.
- Small Scale:Compact units under 100-liter capacity address cafe and food-truck footprints with space-constrained layouts.
- Bulk:Industrial-scale systems for institutional feeding and manufacturing operations exceed standard commercial kitchen specifications.
Medium Scale leads unit shipment counts; Large Scale captures the highest margin concentration through contract bundling and service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific equipment flows, handling containerized shipments of combi-oven systems and refrigeration units bound for foodservice operators across East and Southeast Asia. European distribution relies on the Rhine-Alpine rail corridor connecting German manufacturing clusters to Mediterranean port outlets. North American supply chains route through the Port of Los Angeles-Long Beach complex, the dominant entry point for Asian-sourced commercial kitchen equipment.
United States
Full-service restaurant chains and cloud kitchen networks drive procurement volumes across metropolitan foodservice districts. The Department of Energy's commercial kitchen equipment efficiency standards mandate minimum performance thresholds for cooking and refrigeration units. Los Angeles and New York City concentrate demand as operators confront stringent ventilation mandates and volatile utility pricing.
Germany
Hotel kitchen modernization programs and centralized commissary investments sustain premium equipment demand across the hospitality sector. The EU Ecodesign Directive and F-Gas Regulation enforce refrigerant chemistry transitions and insulation performance requirements. The Rhine-Main industrial corridor hosts fabrication clusters supplying combi-oven and precision cooking systems to European markets.
China
Urban foodservice expansion and international hotel brand entry accelerate procurement of Western-format commercial kitchens in secondary cities. SAMR certification requirements and GB standards govern import access and domestic manufacturing compliance. The Yangtze River Delta manufacturing belt concentrates production capacity for export-oriented refrigeration and cooking equipment.
United Kingdom
Ghost kitchen networks and delivery-optimized foodservice operations reshape equipment specifications toward compact, high-throughput configurations. Building regulations and energy efficiency codes tighten ventilation and thermal performance requirements in Greater London. The Midlands industrial region maintains fabrication capacity for standardized cooking platforms serving chain restaurant rollouts.
India
Tier-2 and Tier-3 city commercial real estate development outpaces equipped kitchen supply, creating positioning opportunities for Western-format equipment. FSSAI food safety regulations and BIS standards govern commercial kitchen compliance and import certification. Maharashtra and Karnataka concentrate hospitality investment as international hotel chains expand beyond Mumbai and Bangalore.
Commercial Catering Equipment Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized thermal engineering firms that span multiple price tiers and geographic markets. The vendor base separates into three strategic archetypes: European premium manufacturers with established combi-oven and refrigeration platforms, North American specialists in automated conveyor and large-format cooking systems, and diversified holding companies aggregating brands across market segments. Competitive moves center on portfolio diversification through brand acquisition and geographic expansion into underpenetrated urban foodservice markets.
Within the European premium tier, Electrolux Professional and RATIONAL exemplify thermal engineering intensity and manufacturing base leverage. The Middleby Corporation anchors North American positioning through specialized automated cooking platforms. Ali Group occupies a diversified holding structure, extending reach across price tiers through aggregated brand holdings. These three entities represent distinct competitive vectors: European engineering pedigree, North American automation specialization, and multi-brand portfolio breadth.
| Leading Market Players |
|---|
| Electrolux Professional |
| Alto-Shaam |
| The Middleby Corporation |
| Fagor Industrial |
| Welbilt Inc. |
| RATIONAL |
| Hobart |
| MKN Maschinenfabrik Kurt Neubauer |
| Ali Group |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts between European combi-oven manufacturers and stainless steel mills lock in supply access and price visibility across volatile 304-grade and 316-grade alloy markets. These arrangements insulate fabrication margins from spot-market swings while committing buyers to minimum volume thresholds that concentrate procurement leverage in chain restaurant rollout programs.
Pricing Analysis
Volume-discount tiering structures separate procurement economics across centralized commissary operators, franchise cooperatives, and independent restaurant buyers. Three-tier pricing stratifies across premium European engineering platforms, standardized North American automation systems, and economy Asian-manufactured alternatives. Cost compression in economy tiers intensifies as Chinese producers expand export capacity and European incumbents defend premium positioning through ENERGY STAR and Ecodesign certification bundling. Independent operators exhibit highest price sensitivity due to fragmented purchasing power and limited access to cooperative procurement channels.
Supply Chain Analysis
Inventory lead times for refrigeration compressor systems and precision thermal controls extend delivery windows as European and Chinese manufacturers manage order backlogs from F-Gas retrofit demand. Supply concentrates in Germany, Italy, and China for combi-oven fabrication and compressor assembly. Raw material dependencies on nickel-bearing stainless steels, copper refrigerant tubing, and electronic control modules expose fabricators to commodity volatility. Single-source vulnerability concentrates in specialized induction coil suppliers serving premium cooking equipment. Distribution runs through authorized dealer networks and direct OEM sales teams serving chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as connected kitchen ecosystems demand API-compatible equipment intelligence, interoperability between IoT-enabled cooking assets and legacy kitchen management systems reshaping procurement specifications.
For Market Incumbents: Consolidate service infrastructure around predictive maintenance platforms and remote diagnostics capabilities to defend against emerging equipment-as-a-service entrants. Deepen backward integration into refrigerant system manufacturing to capture margin from F-Gas transition retrofit cycles. Certification investment in SAMR and GB standards compliance secures positioning in Chinese urban foodservice expansion. For New Entrants and Emerging Players: Aftermarket software integration services represent a service-layer gap where incumbents under-serve fragmented independent restaurant operators lacking IT capabilities. Ghost kitchen networks in Southeast Asian metropolitan corridors offer the most penetrable segment given rapid virtual brand proliferation and limited established supplier relationships. Direct-to-operator digital sales channels bypass traditional dealer networks and compress customer acquisition costs. For Investors and Strategic Acquirers: Regional fabrication specialists with established UL and CE certification portfolios represent compelling acquisition target archetypes given regulatory barrier moats and consolidation tailwinds. Long-term viability frames around refrigerant technology convergence and induction platform maturation across the next decade. Watch for SAMR certification timeline acceleration as signal of Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refrigerant Systems | Captures margin from EU F-Gas retrofit mandates and CO2 transcritical transition. |
| Platform Integration with Kitchen Management Software | Resolves API compatibility gaps blocking IoT equipment deployment in chain accounts. |
| Geographic Expansion into Tier-2 Indian Cities | Positions Western-format equipment ahead of international hotel brand entry waves. |
| Long-term Supply Agreement with Stainless Steel Mills | Insulates fabrication margins from 304-grade and 316-grade alloy price volatility. |
| Joint Venture for Localized Chinese Manufacturing | Accelerates SAMR certification access and reduces import duty exposure. |
Study Parameters
Operator-level perspectives from executive chefs, foodservice procurement directors, kitchen design consultants, and facilities maintenance managers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade records, DOE efficiency standard filings, EU Ecodesign directive documentation, and hotel chain capital expenditure disclosures. Bottom-up equipment shipment analysis triangulated against top-down foodservice operator spending estimates across the projection horizon.
Sensitivity analysis tested forecast robustness against stainless steel price volatility scenarios, regulatory timeline acceleration, and cloud kitchen network expansion rates. Segmentation dimensions modeled include equipment type, power source technology, capacity tier, end-user category, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, new construction penetration, and technology substitution elasticity. Industry-specific inputs incorporated ENERGY STAR certification adoption curves and F-Gas phase-down compliance timelines.
Forecasts assume regulatory continuity in U.S. DOE efficiency standards, EU Ecodesign Directive implementation, and Chinese GB standards enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Sheet Pan Racks Market