
 Smart Cooker Market | 2026-2036
Smart Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cooker Market Outlook
Buyer concentration among food service chains and institutional catering operators is recalibrating procurement volumes toward connected kitchen ecosystems. Vorwerk leverages its direct-to-consumer channel to sustain premium positioning in European households. Instant Pot dominates North American retail through broad distribution and recipe ecosystem lock-in. Samsung Electronics extends its smart home platform to integrate cooker functions with refrigerator and oven interfaces.
A smart cooker is an electrically powered, programmable cooking appliance incorporating microprocessor-controlled heating elements, pressure sensors, and wireless connectivity modules to automate temperature curves and cooking duration across multiple methods. These devices serve residential and commercial users seeking labor reduction, energy precision, and remote operation through smartphone interfaces. Multi-cooker configurations anchor volume shipments by consolidating sauté, steam, pressure, and slow-cook functions in single units. IoT-enabled technology commands expanding margin pools as subscription recipe services and firmware updates create recurring revenue attachment. App-controlled interfaces lead growth in urban Asian markets where mobile-first kitchen management dominates consumer preference.
The US Department of Energy enforces minimum efficiency standards under appliance regulations that shape heating element design and standby power limits. The EU Ecodesign Directive and CE marking requirements govern electromagnetic compatibility and material safety for kitchen equipment sold across member states. China's GB standards and MIIT circular economy provisions influence domestic manufacturing specifications and recyclability mandates. Stakeholders must monitor evolving efficiency thresholds and interoperability protocols as regulatory fragmentation between jurisdictions complicates platform standardization strategies.
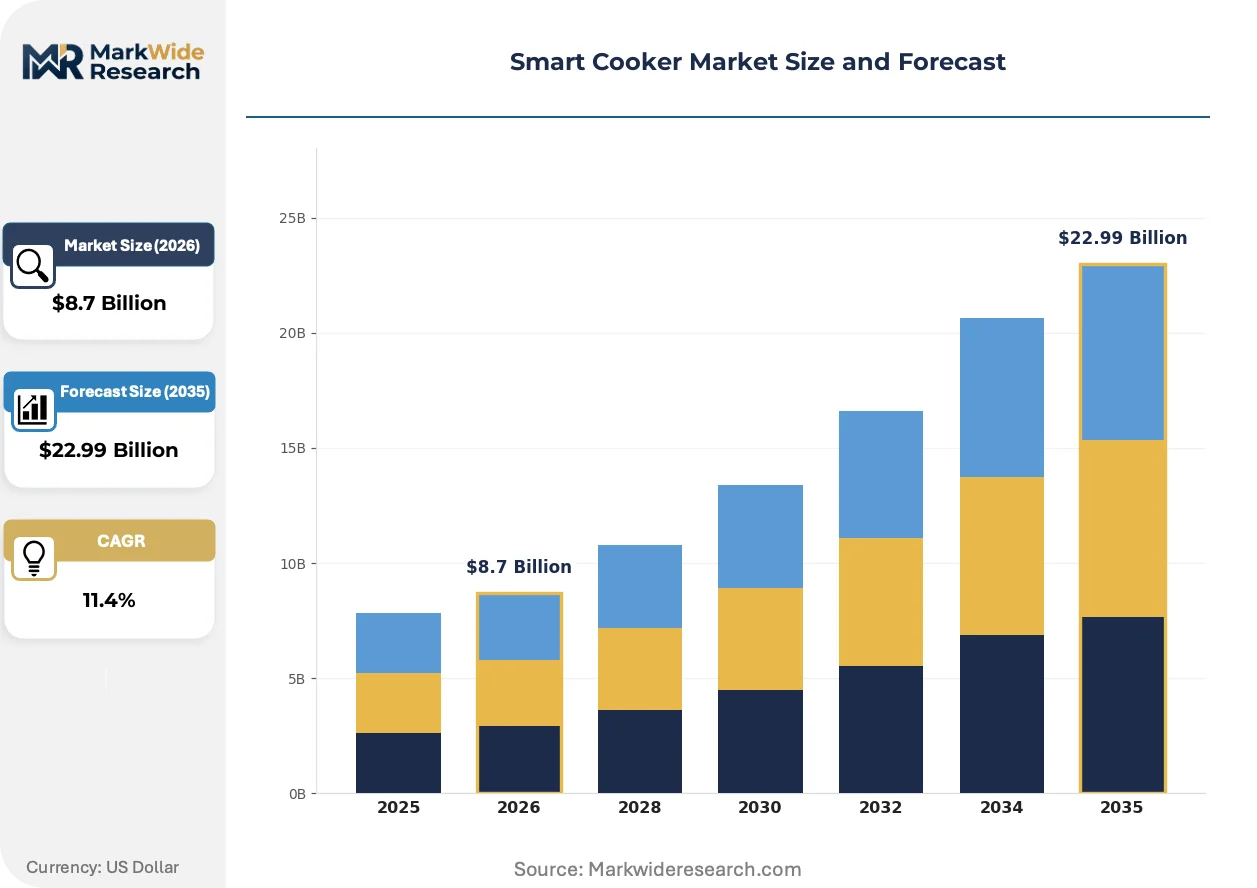
Market Dynamics
Commercial kitchen operators are consolidating procurement around connected appliance ecosystems, forcing manufacturers to bundle hardware with subscription software layers rather than compete on unit economics alone.
Growth Catalysts
- EU Ecodesign thresholds:Tightening efficiency mandates for programmable cooking equipment accelerate replacement cycles in European food service operations.
- Urban middle-class households in China:App-controlled multi-cookers displace traditional stovetop methods as primary cooking infrastructure in dense metropolitan housing.
- Pressure sensor miniaturization:Advances in MEMS fabrication reduce component costs for entry-tier smart cooker models.
Market Restraints
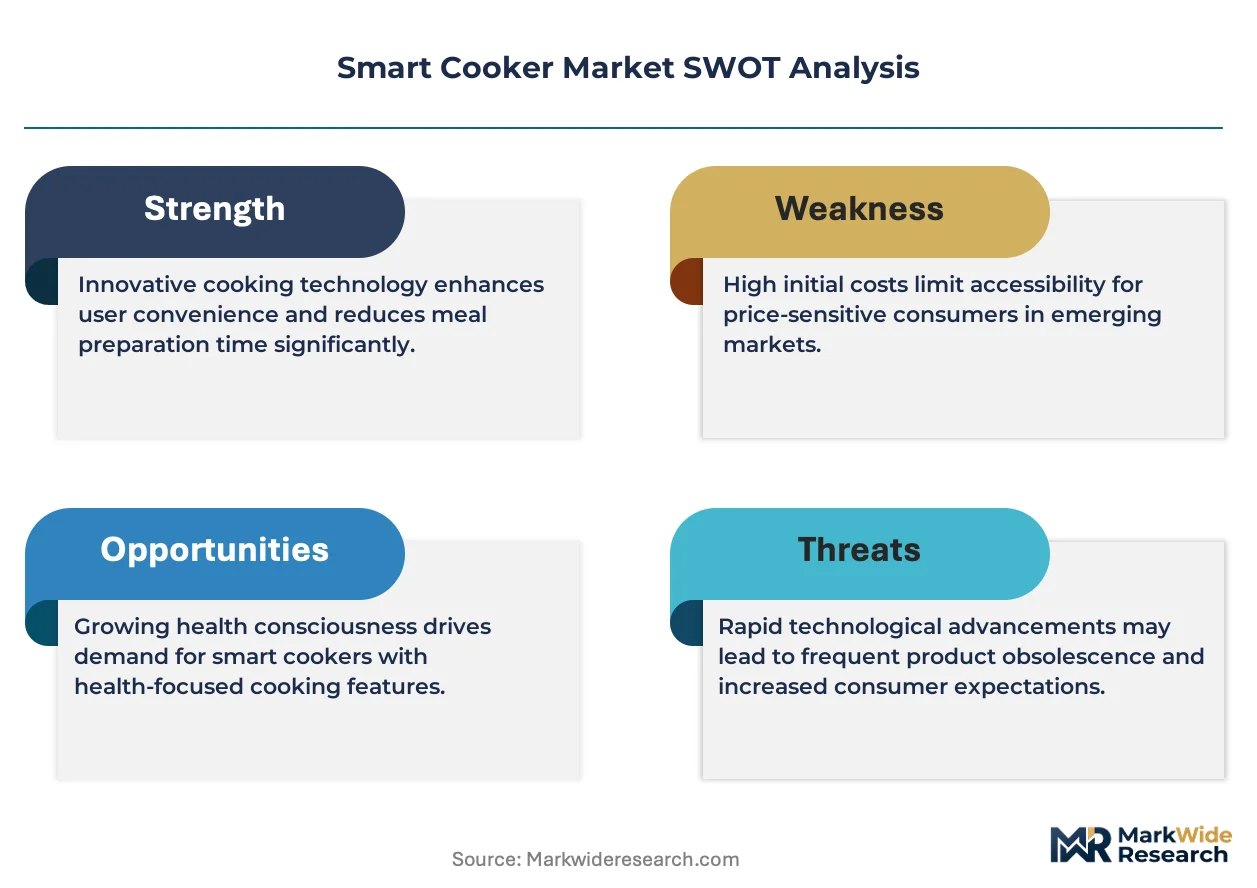
- Semiconductor supply concentration:Microprocessor and connectivity module production clusters in Taiwan and South Korea create input vulnerability.
- Stainless steel price volatility:Raw material swings pressure margin structures for vessel manufacturers.
- Electromagnetic compatibility testing:CE marking requirements extend certification timelines for new product launches.
Strategic Opportunities
- India's BIS appliance safety standards:Formalization of testing protocols creates first-mover advantage for certified connected kitchen entrants.
- Cloud-native recipe platforms:Firmware-over-the-air capabilities enable recurring revenue attachment beyond hardware sales.
- Voice interface convergence:Integration with smart speaker ecosystems opens hands-free operation in residential segments.
Industry Challenges
- Embedded systems engineering talent:Shortage of developers fluent in real-time heating control algorithms constrains product iteration velocity.
- Interoperability protocol fragmentation:Competing smart home standards force redundant engineering investment for multi-platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cooker Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Cooker, Pressure Cooker, Slow Cooker, Rice Cooker End User: Household, Commercial Kitchen, Food Service, Catering Technology: IoT-Enabled, Touchscreen, Voice-Activated, App-Controlled Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Vorwerk, Delonghi Group, Instant Pot, Breville, Ninja Kitchen, Chef IQ, Groupe SEB, Samsung Electronics, KitchenAid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cooker Market Strategic Shifts
Sensor fusion and edge computing are compressing the gap between appliance hardware and cloud-based kitchen management platforms.
Induction heating arrays paired with machine learning temperature prediction are rewriting the economics of precision cooking. High-volume institutional cafeterias in Germany and Japan are retrofitting legacy steam tables with retrofit sensor kits. The technology is compressing energy consumption per prepared meal while extending equipment lifespan through predictive thermal load management.
The US Department of Energy appliance standards are mandating standby power ceilings below one watt for programmable cooking equipment. Manufacturers must redesign power supply architectures to eliminate phantom draw during idle states. Residential multi-cooker lines targeting California and New York compliance zones are shipping with physical disconnect switches ahead of federal adoption timelines.
Food service procurement teams are unbundling equipment purchasing from maintenance contracts, forcing OEMs to compete on lifecycle cost transparency. Independent restaurant groups in France and Italy now require open API access for kitchen equipment integration with inventory management systems. This behavior is most visible in Mediterranean markets where family-owned chains dominate mid-scale dining and resist locked-in proprietary ecosystems.
Smart Cooker Market Segmentation
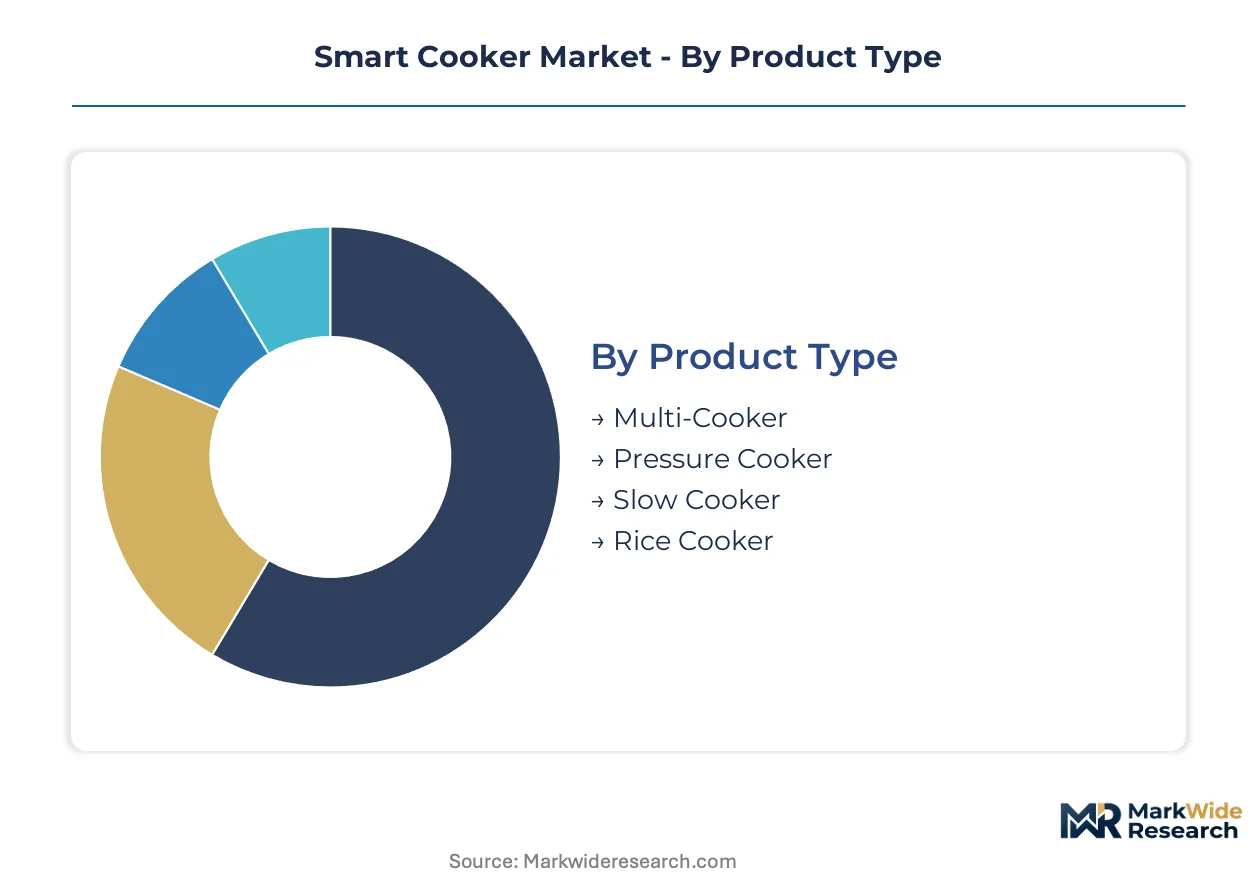
Smart cooker segmentation reveals divergent capital requirements and margin structures across hardware configurations and connectivity tiers. Procurement patterns in food service and residential channels demand distinct engineering investments, reshaping how manufacturers allocate R&D across product lines.
Product Type:
Capital intensity peaks with multi-function architectures requiring redundant heating systems and complex firmware integration.
- Multi-Cooker:Consolidates sauté, steam, pressure, and slow-cook functions through microprocessor-controlled thermal switching. Demand concentrates in Chinese urban households where kitchen footprint constraints drive consolidation. App-controlled interfaces command price premiums in Shanghai and Shenzhen replacement cycles.
- Pressure Cooker:Sealed-vessel designs with MEMS pressure sensors enable accelerated cooking cycles for protein-heavy meal preparation. European food service operators in Germany and France favor these units for institutional catering throughput optimization.
- Slow Cooker:Low-wattage thermal elements suit extended-duration braising with minimal supervision. Residential users in suburban US markets deploy these for batch meal preparation.
- Rice Cooker:Fuzzy-logic temperature curves optimize starch gelatinization for specific grain varieties. Japanese and South Korean households maintain replacement loyalty to induction-heating variants.
Most installed capacity flows through Multi-Cooker. Expansion is steepest in Pressure Cooker.
End User:
Application context determines connectivity requirements and durability specifications across residential and commercial deployments.
- Household:Countertop units prioritizing Wi-Fi integration and recipe app ecosystems. Chinese middle-class buyers in tier-1 cities drive volume through smartphone-centric kitchen management preferences.
- Commercial Kitchen:Stainless-steel construction with NSF certification and open API access for inventory system integration. Independent restaurant groups in Italy and France mandate interoperability.
- Food Service:High-throughput institutional cafeterias in Germany and Japan retrofit steam tables with sensor kits for predictive thermal load management.
- Catering:Mobile units requiring rapid heat-up and transport durability for off-site event provisioning. European contract caterers specify CE-marked electromagnetic compatibility.
Household absorbs the highest unit volumes. Commercial Kitchen delivers the steepest margin expansion trajectory.
Technology:
Connectivity module selection drives bill-of-materials differentiation and recurring revenue potential.
- IoT-Enabled:Cloud-connected firmware architectures enabling over-the-air updates and subscription recipe services. Food service procurement teams bundle these with lifecycle maintenance contracts.
- Touchscreen:Capacitive glass interfaces with programmable temperature curves and guided cooking workflows. Premium residential lines in California integrate physical disconnect switches for standby power compliance.
- Voice-Activated:Smart speaker ecosystem integration for hands-free operation during multi-step preparation. US suburban households show highest activation rates.
- App-Controlled:Smartphone-native interfaces dominating mobile-first Asian markets where kitchen display screens are less common.
Touchscreen represents the dominant installed base. App-Controlled gains share fastest in metropolitan Asian deployments.
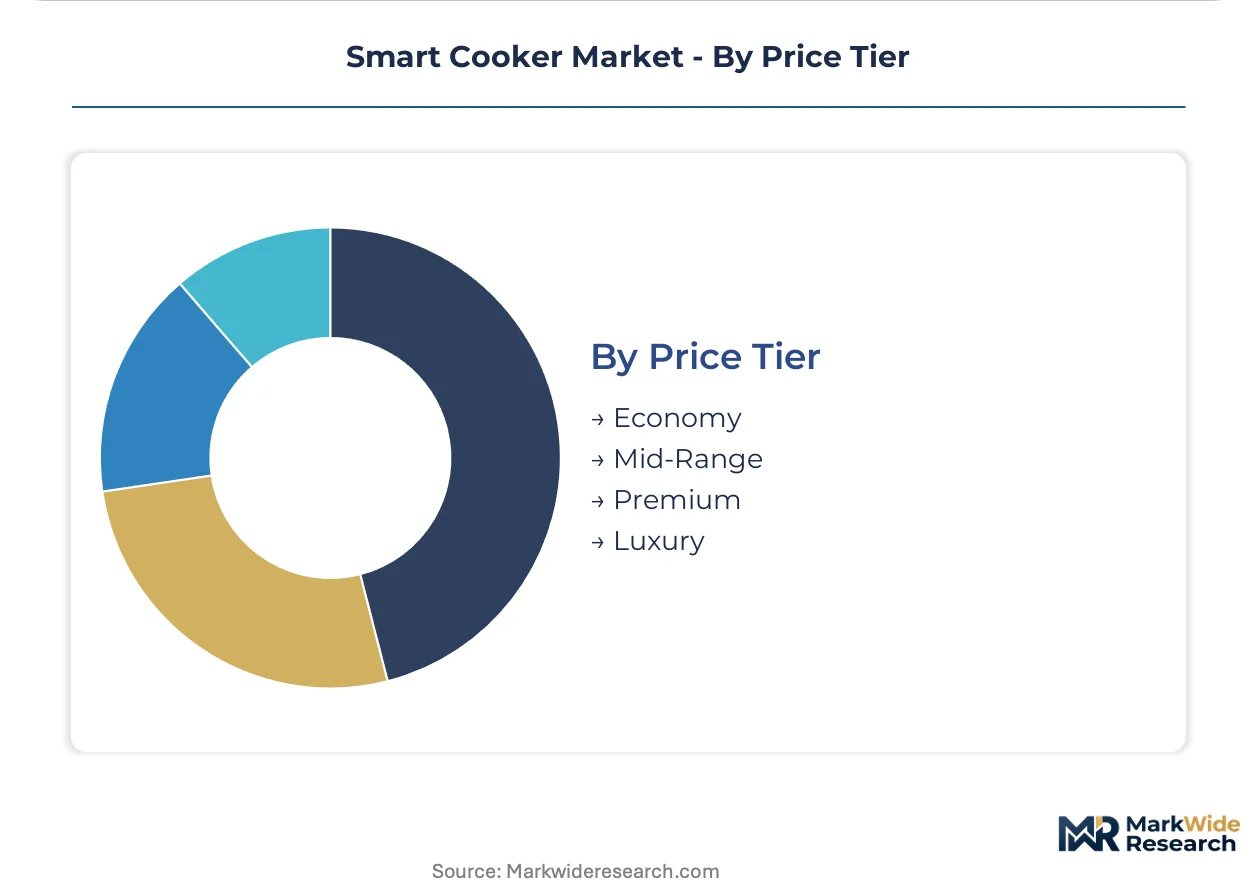
Price Tier:
Component grade and certification level stratify manufacturing cost structures across entry and premium positioning.
- Economy:Basic thermal control without connectivity, targeting price-sensitive replacement cycles in developing markets. Pressure sensor miniaturization reduces entry-tier component costs.
- Mid-Range:Wi-Fi connectivity with limited app functionality and standard warranty terms. European retail channels concentrate volume here.
- Premium:Induction heating arrays with machine learning temperature prediction and extended service agreements. German institutional buyers prioritize lifecycle cost transparency.
- Luxury:Bespoke finishes, concierge recipe curation, and white-glove installation services. Direct-to-consumer channels in European households sustain this positioning.
Mid-Range captures the highest shipment volumes. Premium climbs fastest as food service procurement consolidates around connected ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's urban middle-class households drive replacement cycles toward app-controlled multi-cookers, while the United States channels demand through retail ecosystems anchored by recipe platform lock-in. Regulatory divergence across these markets fragments platform standardization strategies.
China
Tier-1 city households in Shanghai and Shenzhen prioritize smartphone-native kitchen management, displacing traditional stovetop methods with multi-function consolidation. MIIT circular economy provisions mandate recyclability specifications for domestic manufacturing. The Yangtze River Delta hosts dense clusters of MEMS pressure sensor fabricators supplying entry-tier component cost reductions.
United States
Suburban residential segments activate voice-controlled interfaces through smart speaker ecosystem integration. The Department of Energy enforces standby power ceilings below one watt for programmable cooking equipment. California and New York compliance zones now require physical disconnect switches ahead of federal adoption timelines.
Germany
Institutional cafeteria operators retrofit legacy steam tables with sensor kits for predictive thermal load management. EU Ecodesign Directive thresholds tighten minimum efficiency mandates for programmable equipment. Bavarian food service procurement teams unbundle equipment purchasing from maintenance contracts, demanding open API access.
Japan
Households maintain replacement loyalty to induction-heating rice cooker variants with fuzzy-logic temperature optimization. METI efficiency standards shape heating element design for premium residential lines. The Kansai region around Osaka concentrates precision appliance manufacturing for export-oriented production.
India
Urban middle-class consumers in Maharashtra and Karnataka transition from basic thermal control units toward Wi-Fi-enabled mid-range models. BIS appliance safety standards formalization creates certification pathways for connected kitchen entrants. The Delhi-NCR corridor hosts assembly operations targeting price-sensitive replacement cycles.
Smart Cooker Market Competitive Environment
East Asian electronics conglomerates anchor one tier; European direct-to-consumer specialists hold premium positioning through channel control. The vendor base stratifies across three tiers: mass-market retail brands, ecosystem-integrated technology platforms, and boutique appliance houses. Two dominant competitive moves are reshaping positioning: cloud-native recipe platform development for recurring revenue attachment, and vertical integration into MEMS sensor supply to reduce input vulnerability.
Within the ecosystem-integrated tier, Samsung Electronics exemplifies platform convergence strategies, while Vorwerk and Groupe SEB occupy positions as European direct-to-consumer archetypes with sustained premium pricing power. Instant Pot anchors the North American retail vector through broad distribution density.
| Leading Market Players |
|---|
| Vorwerk |
| Delonghi Group |
| Instant Pot |
| Breville |
| Ninja Kitchen |
| Chef IQ |
| Groupe SEB |
| Samsung Electronics |
| KitchenAid |
| Others |
Value Chain & Pricing Dynamics
Food service procurement consolidation around connected appliance ecosystems is forcing manufacturers to absorb software development costs into hardware margins, compressing unit economics while elevating total contract values. This demand-side shift toward bundled lifecycle pricing reshapes how OEMs negotiate component contracts and allocate working capital across production tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for MEMS pressure sensors and microprocessor modules. Pricing stratifies across premium, standard, and economy tiers, with induction heating arrays and machine learning firmware commanding certification-grade premiums. Cost compression in entry-tier models intensifies because pressure sensor miniaturization reduces component costs, while stainless steel price volatility squeezes vessel manufacturers. Food service chains show least price sensitivity due to lifecycle cost transparency requirements, whereas developing-market household segments resist connectivity premiums.
Supply Chain Analysis
CE marking and electromagnetic compatibility testing create qualification gating that extends certification timelines and concentrates supplier relationships around pre-certified component vendors. Microprocessor and connectivity module production clusters in Taiwan and South Korea, with MEMS sensor fabrication expanding in China's Yangtze River Delta. Raw material dependencies span stainless steel for vessels, copper for induction coils, and rare earth elements for high-efficiency heating elements. Single-source vulnerability concentrates in Taiwan's semiconductor foundry capacity. Distribution runs through direct-to-consumer channels for premium European positioning and mass retail density for North American volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Ecodesign compliance costs in Europe run substantially higher than China's GB standards, creating margin expansion for manufacturers with dual-certification capabilities and transferable production footprints.
For Market Incumbents: Lock in cloud-native recipe platform development to sustain recurring revenue attachment as hardware margins tighten from semiconductor input volatility. Prioritize backward integration into MEMS sensor supply to reduce Taiwan foundry exposure. Defend against ecosystem-integrated technology platforms by deepening direct-to-consumer channel control in European households where premium positioning endures. For New Entrants and Emerging Players: Voice interface convergence with smart speaker ecosystems offers a technology-first wedge into US suburban residential segments where hands-free activation rates exceed other geographies. Target India's formalizing BIS appliance safety standards for first-mover certification advantage before incumbent footprint solidifies. Pursue white-label partnerships with food service procurement teams seeking open API access rather than locked-in proprietary ecosystems. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native firmware architectures enabling subscription recipe services and predictive maintenance contracts. Long-term viability centers on vendors with captive sensor supply and multi-platform interoperability engineering. Watch for inflection when food service procurement teams in Mediterranean markets mandate open API access as standard contract terms.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Recipe Platform Development | Enables recurring revenue attachment beyond hardware sales for food service procurement consolidation. |
| MEMS Sensor Supply Integration | Reduces Taiwan foundry exposure and accelerates entry-tier product iteration velocity. |
| Open API Architecture Investment | Unlocks independent restaurant group contracts in France and Italy resisting proprietary ecosystems. |
| Voice Interface Ecosystem Partnership | Captures US suburban household activation through smart speaker integration. |
| Dual-Certification Manufacturing Footprint | Exploits cost differentials between EU Ecodesign and China's GB standards compliance. |
Study Parameters
Coverage spans China, the United States, Germany, Japan, and India, with primary inputs from each market's stakeholder base. The analysis combines primary interviews with connected appliance product managers, food service procurement directors, MEMS sensor manufacturing engineers, and regulatory compliance specialists with secondary validation from SEC filings, MIIT circular economy provisions, EU Ecodesign Directive documentation, and customs trade data. Bottom-up shipment modeling and top-down value reconciliation triangulate market sizing across hardware configurations and connectivity tiers.
Granularity-level modeling disaggregates volume and value across product type, end user, technology, and price tier dimensions throughout the forecast period. CAGRs derive from regression analysis against replacement cycle timing, regulatory mandate adoption curves, and urban household formation rates. Industry-specific forecast inputs include pressure sensor cost decline trajectories and food service procurement consolidation velocity.
The model holds under stable semiconductor supply conditions and gradual regulatory harmonization; deviation in Taiwan geopolitical risk or abrupt EU efficiency threshold acceleration would shift replacement cycle timing and margin structures. Forecasts reflect documented assumptions about connectivity module cost curves and cloud platform subscription attach rates. A model refresh is warranted upon material change in food service procurement unbundling behavior or BIS certification pathway formalization in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market