
 North America and Europe Vending Machine Market | 2026-2036
North America and Europe Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Vending Machine Market Analytics
Remote monitoring as a service layer is broadening what operators sell beyond hardware placement. Crane Merchandising Systems leverages its IoT platform to anchor recurring revenue through real-time inventory telemetry. Fuji Electric Co., Ltd. sustains competitive positioning with energy-efficient refrigeration systems that reduce operating costs for European deployers. Cantaloupe Systems specializes in cashless payment integration, dominating the North American retrofit market for legacy machine estates.
North America and Europe vending machines comprise electromechanical dispensing systems with refrigerated or ambient compartments, payment interfaces, and telemetry modules designed for unattended retail of consumables and convenience goods. These units typically operate on 110-240V AC supply with temperature control ranges from 2°C to 8°C for fresh food applications and serve commercial environments requiring 24-hour product availability without staffed points of sale. Beverage deployments command the largest installed base across both regions while fresh food represents the fastest-growing product category as cold-chain reliability improves. Full-service contracts capture disproportionate margin pools because operators bundle machine maintenance, restocking logistics, and payment processing into single-provider agreements.
The US Food and Drug Administration and the EU Food Information for Consumers Regulation shape fresh food vending through labeling, allergen disclosure, and temperature compliance requirements that elevate equipment specifications. CE marking under the EU Machinery Directive and FCC certification for wireless payment modules in the United States create dual compliance burdens for manufacturers serving both markets. Stakeholders must weigh payment technology refresh cycles against refrigeration energy standards tightening on both sides of the Atlantic.
Market Dynamics
The EU Payment Services Directive and PCI-DSS evolution in the United States are forcing hardware refresh cycles across installed bases, compressing replacement timelines from ten-year cycles to five-to-seven-year intervals as contactless mandates take effect.
Growth Catalysts
- Contactless Payment Mandates:The EU Payment Services Directive and PCI-DSS evolution in the United States are accelerating terminal replacements across legacy estates.
- Healthcare Facility Expansion:Hospital networks in Germany and the US Northeast corridor are deploying refrigerated units for fresh food and medical supply dispensing.
- Energy-Efficient Refrigeration:Cold-chain reliability improvements are unlocking fresh food as the fastest-growing product category across both regions.
Market Restraints
- Dual Compliance Burdens:CE marking under the EU Machinery Directive and FCC certification for wireless modules create redundant testing costs for manufacturers serving both markets.
- Component Supply Concentration:Payment terminal chipsets and refrigeration compressors concentrate among limited East Asian suppliers, exposing operators to lead-time volatility.
- Refrigeration Energy Standards:Tightening F-Gas Regulation in Europe and evolving EPA efficiency requirements in the United States are elevating equipment specifications and unit costs.
Strategic Opportunities
- Remote Monitoring Services:IoT telemetry platforms enable operators to sell real-time inventory management and predictive maintenance as recurring revenue streams beyond hardware placement.
- Fresh Food Cold-Chain Expansion:Allergen disclosure and temperature compliance requirements under the FDA and EU Food Information for Consumers Regulation create premium positioning for certified equipment.
- Urban Transit Hub Density:Machine deployment in German S-Bahn networks and the US Northeast corridor transit systems remains underpenetrated relative to passenger volume potential.
Industry Challenges
- Cashless Retrofit Complexity:Legacy electromechanical estates require extensive hardware modification to integrate modern payment modules, stretching deployment timelines.
- Skilled Technician Shortage:Combined refrigeration, payment systems, and wireless telemetry expertise remains scarce across field service networks in both regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Vending Machine Market |
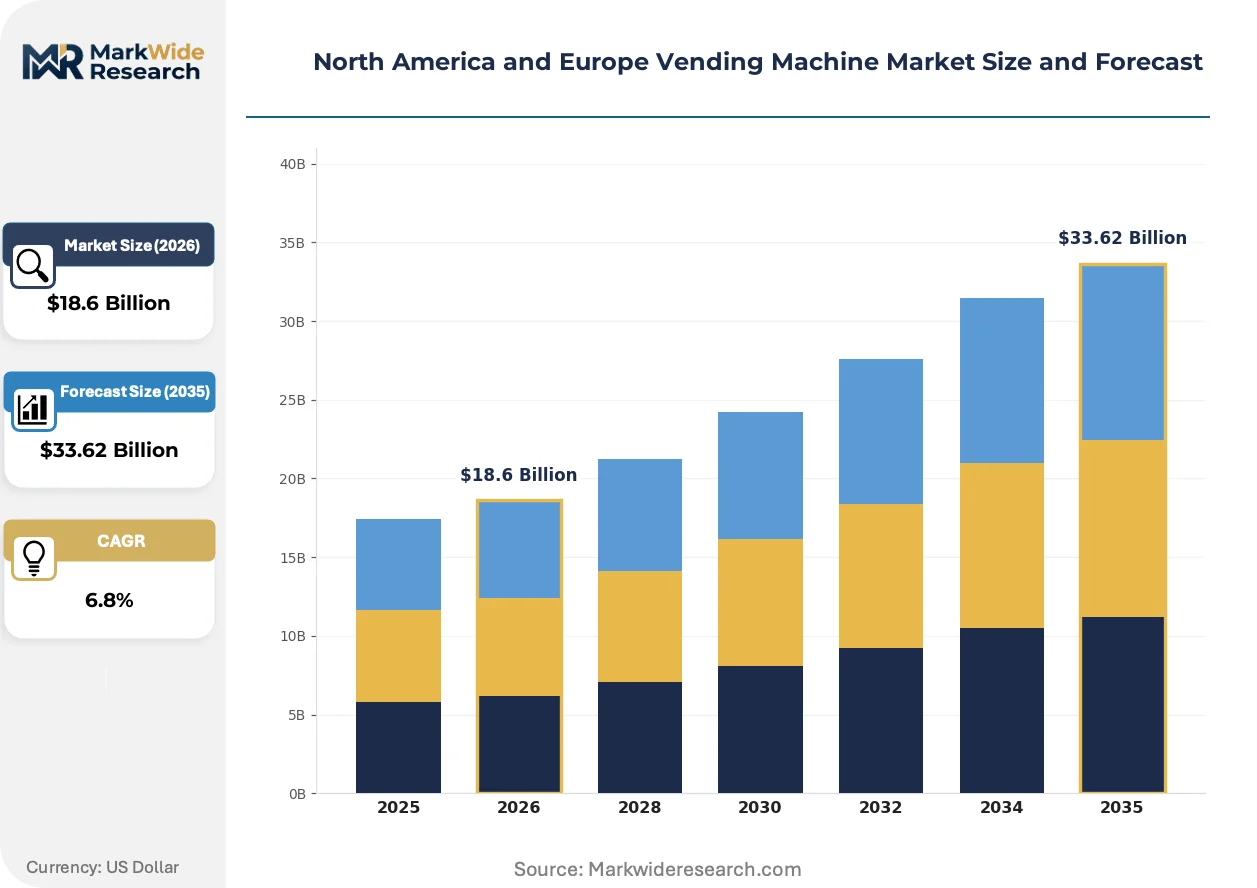
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Fresh Food, Personal Care Deployment: Public Spaces, Offices, Schools, Retail Stores Service Type: Self-Service, Full-Service, Automatic, Remote Monitoring End User: Corporates, Educational Institutions, Healthcare Facilities, Entertainment Venues |
| Companies Covered | Aramark Corporation, Crane Merchandising Systems, American Vending Machines Inc., Selecta, EVOCA, Fuji Electric Co., Ltd., Jofemar Corporation, Cantaloupe Systems, Azkoyen Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Vending Machine Market Evolving Landscape
Telemetry-enabled service models are rewriting how operators capture value, shifting competitive advantage from machine manufacturing to data-driven inventory optimization and predictive maintenance capabilities.
Edge computing modules embedded at the machine level are rewriting operational economics for vending operators. These processors enable real-time inventory decisions without cloud latency. Hospital networks and transit authorities in Germany and the United States are piloting these systems for fresh food applications. The technology is rewriting margin structures by reducing spoilage rates and compressing restocking frequencies.
The EU F-Gas Regulation and evolving EPA refrigerant standards are reshaping equipment specifications across refrigerated vending categories. Manufacturers must redesign compressor systems to accommodate lower-global-warming-potential coolants. Fresh food deployments in healthcare and corporate environments face the steepest compliance curves as temperature validation requirements tighten.
Buyer consolidation among facility management providers is compressing vendor selection cycles and elevating contract scale requirements. Full-service bundling—combining machine provision, maintenance, restocking, and payment processing—is displacing piecemeal procurement. This pattern concentrates most visibly in the United States Northeast corridor and German hospital networks where single-provider agreements now dominate.
North America and Europe Vending Machine Market Segmentation
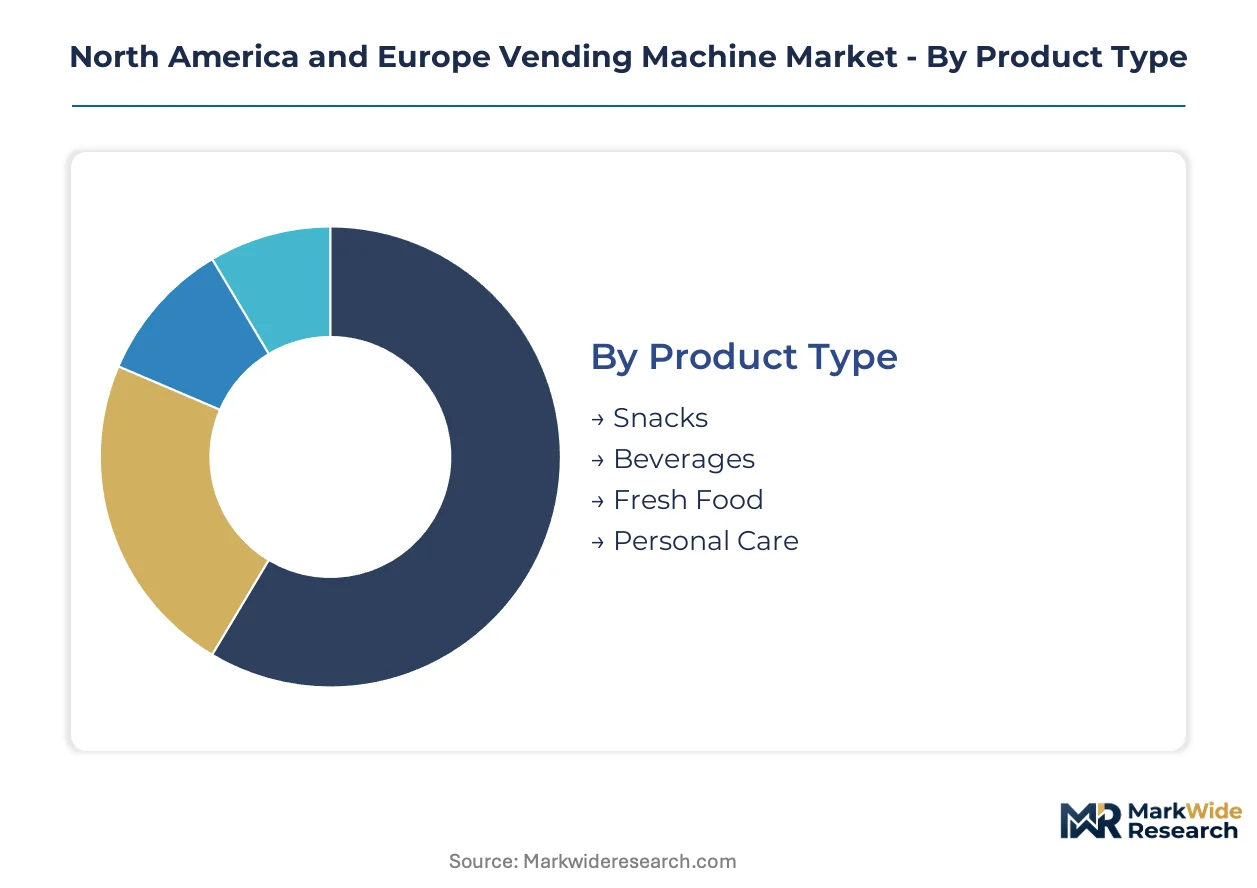
Vending machine segmentation reveals how equipment specifications, service models, and placement contexts determine procurement patterns across North America and Europe. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor positioning.
Product Type:
Beverage and fresh food segments demand integrated refrigeration systems with precise temperature validation, while ambient categories operate through simpler electromechanical mechanisms.
- Beverages:Carbonated and non-carbonated drink dispensers dominate installed bases across German transit hubs and US Northeast corridor locations. Cold-chain reliability requirements under FDA and EU Food Information for Consumers Regulation elevate equipment specifications for this segment.
- Fresh Food:Refrigerated units with 2°C to 8°C temperature control ranges serve healthcare facilities and corporate campuses requiring 24-hour meal availability. Hospital networks in Germany and the United States are expanding deployments as allergen disclosure compliance becomes standard.
- Snacks:Ambient-temperature dispensers for packaged goods operate with lower capital intensity and reduced energy consumption.
- Personal Care:Specialized dispensing systems for hygiene products and medical supplies target healthcare environments with distinct inventory management protocols.
Beverages leads volumes today; fresh food is gaining share fastest.
Deployment:
Placement context determines payment technology requirements, security specifications, and restocking frequency economics across the two regions.
- Public Spaces:Transit authorities and municipal operators in German S-Bahn networks and US Northeast corridor systems require ruggedized hardware with contactless payment mandates under EU Payment Services Directive and PCI-DSS evolution. High passenger throughput justifies premium telemetry integration for real-time inventory tracking.
- Offices:Corporate campuses prioritize fresh food refrigeration and customizable product mixes for employee amenity programs.
- Schools:Educational institutions face distinct nutritional labeling requirements and restricted product categories under national guidelines.
- Retail Stores:Co-located vending extends operating hours for convenience retail without incremental staffing costs.
Public spaces command the highest machine density per square meter; offices show the steepest expansion trajectory for fresh food categories.
Service Type:
Service model selection reflects operator scale, technical capability depth, and appetite for recurring revenue versus capital deployment.
- Full-Service:Bundled contracts covering machine provision, maintenance, restocking logistics, and payment processing capture disproportionate margin pools. Facility management consolidators in the United States Northeast corridor and German hospital networks increasingly mandate single-provider arrangements.
- Remote Monitoring:IoT telemetry platforms enabling predictive maintenance and real-time inventory optimization represent the fastest-climbing service layer as operators seek recurring revenue beyond hardware placement.
- Self-Service:Unstaffed operation with owner-managed restocking suits low-volume locations and specialized product categories.
- Automatic:Fully autonomous replenishment through robotic restocking systems remains pilot-stage in select German and US urban deployments.
Full-service contracts dominate revenue concentration today; remote monitoring is climbing the fastest as a standalone revenue stream.
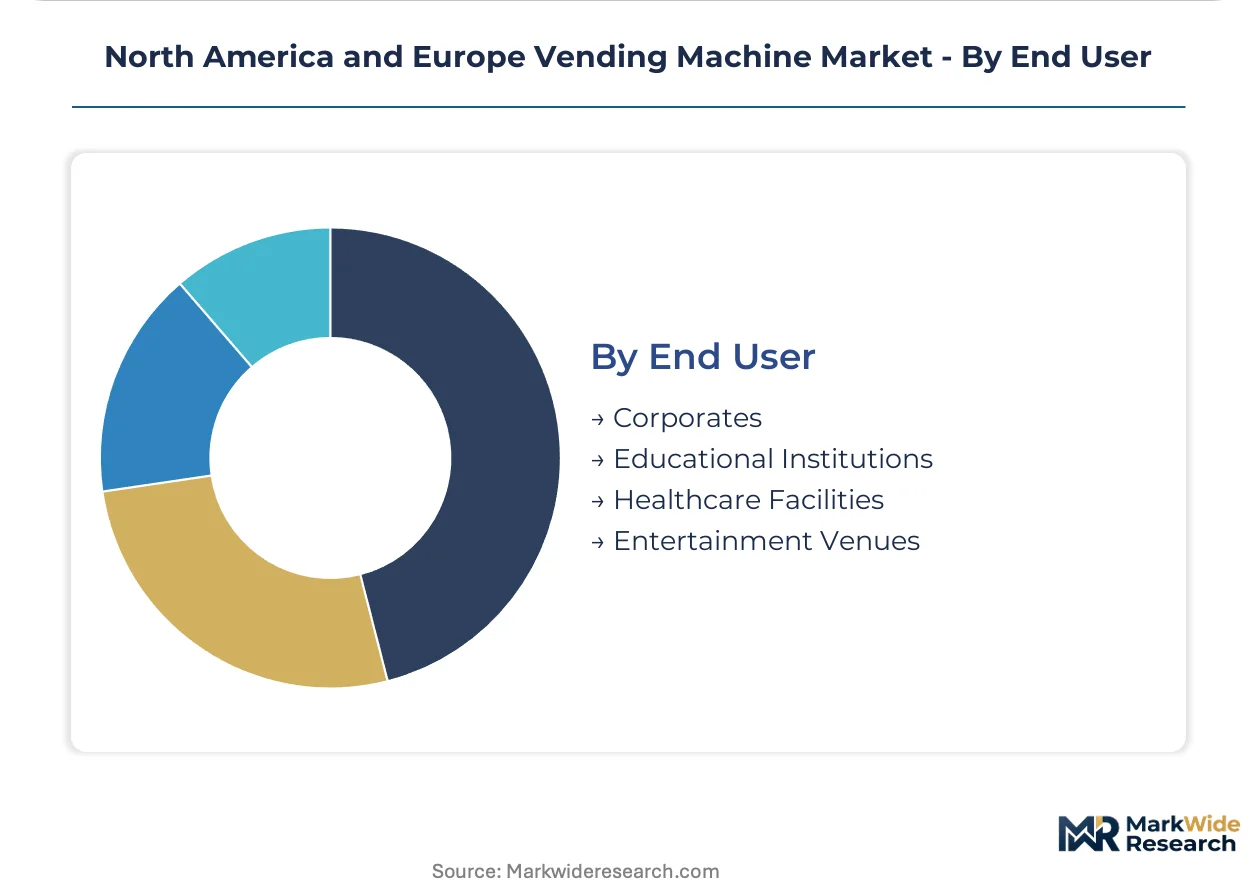
End User:
End-use verticals impose distinct compliance burdens, temperature validation requirements, and contract scale expectations that filter vendor eligibility.
- Healthcare Facilities:Hospital networks require FDA and EU Food Information for Consumers Regulation compliance for fresh food dispensing, plus specialized units for medical supply distribution. German and US Northeast corridor health systems are expanding refrigerated vending estates fastest.
- Corporates:Enterprise campuses prioritize employee amenity value and brand alignment over pure transaction economics, supporting premium equipment specifications.
- Educational Institutions:Universities and K-12 systems navigate nutritional content restrictions and procurement transparency requirements that vary by jurisdiction.
- Entertainment Venues:Stadiums and theaters demand high-capacity beverage dispensing with rapid transaction throughput during peak intervals.
Healthcare facilities anchor premium pricing tiers today; corporate campuses are expanding contract scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys refrigerated vending at higher density per transit hub than the United States, though both markets converge on contactless payment mandates that compress hardware replacement cycles.
United States
Hospital networks across the Northeast corridor are expanding refrigerated estates for fresh food and medical supply dispensing. FDA allergen disclosure requirements and PCI-DSS payment security standards elevate equipment specifications for new deployments. Boston and New York City transit authorities pilot edge-computing inventory systems to reduce spoilage in high-throughput locations.
Germany
S-Bahn networks and municipal transit operators drive machine density in urban corridors with mandated contactless terminals under EU Payment Services Directive. F-Gas Regulation compliance costs reshape compressor specifications for fresh food refrigeration. The Rhine-Ruhr metropolitan region concentrates operator consolidation as facility management providers bundle full-service contracts.
United Kingdom
Corporate campuses in London and Southeast England prioritize employee amenity vending with customizable fresh food mixes. EU Food Information for Consumers Regulation alignment post-Brexit maintains labeling and temperature validation requirements. The Midlands manufacturing belt supplies refrigeration components facing export compliance dual burdens.
France
Healthcare facilities in Île-de-France expand medical supply dispensing alongside fresh food services for patient and staff access. ANSM medical device oversight intersects with EFSA food safety protocols for dual-use equipment. Lyon and Auvergne-Rhône-Alpes host component suppliers adapting to lower-global-warming-potential refrigerant transitions.
Canada
Transit authorities in Toronto and Vancouver deploy ruggedized hardware with Health Canada food safety validation for extended operating hours. Provincial procurement transparency rules extend vendor selection timelines for institutional contracts. The Ontario-Quebec corridor concentrates operator technical service networks addressing refrigeration and payment system maintenance.
North America and Europe Vending Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service bundling consolidating procurement decisions around fewer vendor relationships. The vendor base organizes into three tiers: integrated operators controlling placement-to-payment stacks, component specialists anchoring specific technology layers, and regional service providers capturing localized maintenance contracts. Dominant competitive moves include M&A-driven facility management consolidation and telemetry platform licensing to secure recurring revenue beyond hardware sales.
Among North American and European operators, Crane Merchandising Systems, Fuji Electric Co., Ltd., and Cantaloupe Systems occupy distinct archetype positions. Crane exemplifies the integrated operator model with IoT-enabled service layering. Fuji Electric represents the energy-efficient refrigeration specialist tier serving European deployers with compliance-forward equipment specifications. Cantaloupe Systems anchors the payment technology retrofit segment, capturing legacy estate modernization demand through cashless integration capabilities.
| Leading Market Players |
|---|
| Aramark Corporation |
| Crane Merchandising Systems |
| American Vending Machines Inc. |
| Selecta |
| EVOCA |
| Fuji Electric Co., Ltd. |
| Jofemar Corporation |
| Cantaloupe Systems |
| Azkoyen Group |
| Others |
Value Network & Pricing Analysis
Refrigerant transitions under the EU F-Gas Regulation and EPA efficiency mandates are simultaneously elevating equipment unit costs and compressing supplier margins across North America and Europe. Payment terminal chipsets from concentrated East Asian sources create dual dependency risks that reshape procurement economics for operators managing legacy estate retrofits.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for payment terminal chipsets, compressing hardware margins for European and North American deployers. Three-tier pricing structure across premium telemetry-integrated, standard contactless-enabled, and economy cash-only equipment tiers separates operators by compliance readiness and service bundling intensity. Cost compression in the economy tier is intensifying because legacy electromechanical estates face accelerated replacement timelines under PCI-DSS and EU Payment Services Directive mandates. Transit authorities and hospital networks show least price sensitivity due to compliance-driven procurement, while independent retail operators demonstrate highest elasticity to upfront capital outlays.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated facility management providers in the United States Northeast corridor and German hospital networks. Component manufacturing concentrates in China, South Korea, and Japan for refrigeration compressors, payment terminal chipsets, and wireless telemetry modules. Raw material dependencies span copper refrigerant lines, semiconductor-grade silicon, and lithium-ion battery cells for edge-computing modules. Single-source vulnerability around specialized compressor suppliers exposes operators to lead-time volatility during F-Gas Regulation compliance transitions. Distribution runs through authorized service networks for full-service contracts, while self-service operators procure through wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Payment Services Directive contactless mandates and FDA allergen disclosure requirements create sustained hardware replacement demand across installed bases.
For Market Incumbents: Extend telemetry platform licensing to capture recurring revenue beyond machine placement, insulating against margin erosion in hardware sales. Backward integration into refrigeration compressor servicing capabilities addresses the skilled technician shortage constraining field service networks. Consolidate maintenance contracts with German S-Bahn operators and US Northeast corridor transit authorities before facility management providers complete vendor reduction cycles. For New Entrants and Emerging Players: Independent software vendors specializing in edge-computing inventory optimization represent the most penetrable partnership channel for telemetry layer insertion. Fresh food cold-chain compliance in mid-tier US hospital networks offers white-space expansion with lower incumbent saturation than German healthcare systems. Target corporate campus operators seeking customizable employee amenity programs through refrigerated vending-as-a-service models rather than capital purchase arrangements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service providers with captive maintenance networks but underdeveloped telemetry capabilities. The five-to-ten-year viability window favors acquisition targets with established FDA and EU Food Information for Consumers Regulation compliance credentials that accelerate consolidation into full-service bundling contracts. Watch hospital network procurement standardization around single-provider agreements as the inflection signal for vendor margin concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Licensing | Crane Merchandising Systems anchors recurring revenue through real-time inventory data monetization. |
| Refrigerant Compliance Redesign | Fuji Electric sustains European positioning with lower-global-warming-potential compressor specifications. |
| Cashless Retrofit Integration | Cantaloupe Systems dominates North American legacy estate modernization through PCI-DSS terminal deployment. |
| Full-Service Contract Bundling | Facility management consolidators in Germany and the US Northeast corridor mandate single-provider procurement. |
| Edge-Computing Pilot Expansion | Boston and New York City transit authorities test real-time spoilage reduction in high-throughput fresh food locations. |
Research Methodology
Multiple input streams — vending operator interviews, component supplier discussions, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork encompassed equipment manufacturers, facility management procurement leads, transit authority operations directors, and hospital supply chain managers across Germany, the United States, the United Kingdom, France, and Canada. Secondary validation drew from FDA food safety guidance documents, EU Machinery Directive CE marking databases, EPA refrigerant efficiency standards, and SEC filings from publicly traded vending operators. Bottom-up machine deployment counts by geography and end-use vertical were triangulated against top-down operator revenue estimates.
Data-stream reconciliation across the projection horizon applied product type, deployment context, service model, and end-use vertical segmentation dimensions. CAGRs were derived from installed base replacement cycle compression under payment mandate timelines and fresh food category expansion rates. Industry-specific forecast inputs included F-Gas Regulation compliance cost curves for refrigeration equipment and PCI-DSS terminal refresh acceleration patterns across legacy estates.
Revisions become necessary when refrigerant supply disruptions, payment terminal chipset allocation constraints, or transit authority procurement freezes materialize across the analysis window. Forecasts reflect documented assumptions regarding contactless mandate enforcement timelines and cold-chain reliability improvement trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Dispensing Tap Market